
 Cadmium Telluride Photovoltaic Market | 2026-2036
Cadmium Telluride Photovoltaic Market Size, Share, and Industry Trends Forecast 2026-2036
Cadmium Telluride Photovoltaic Market Analysis
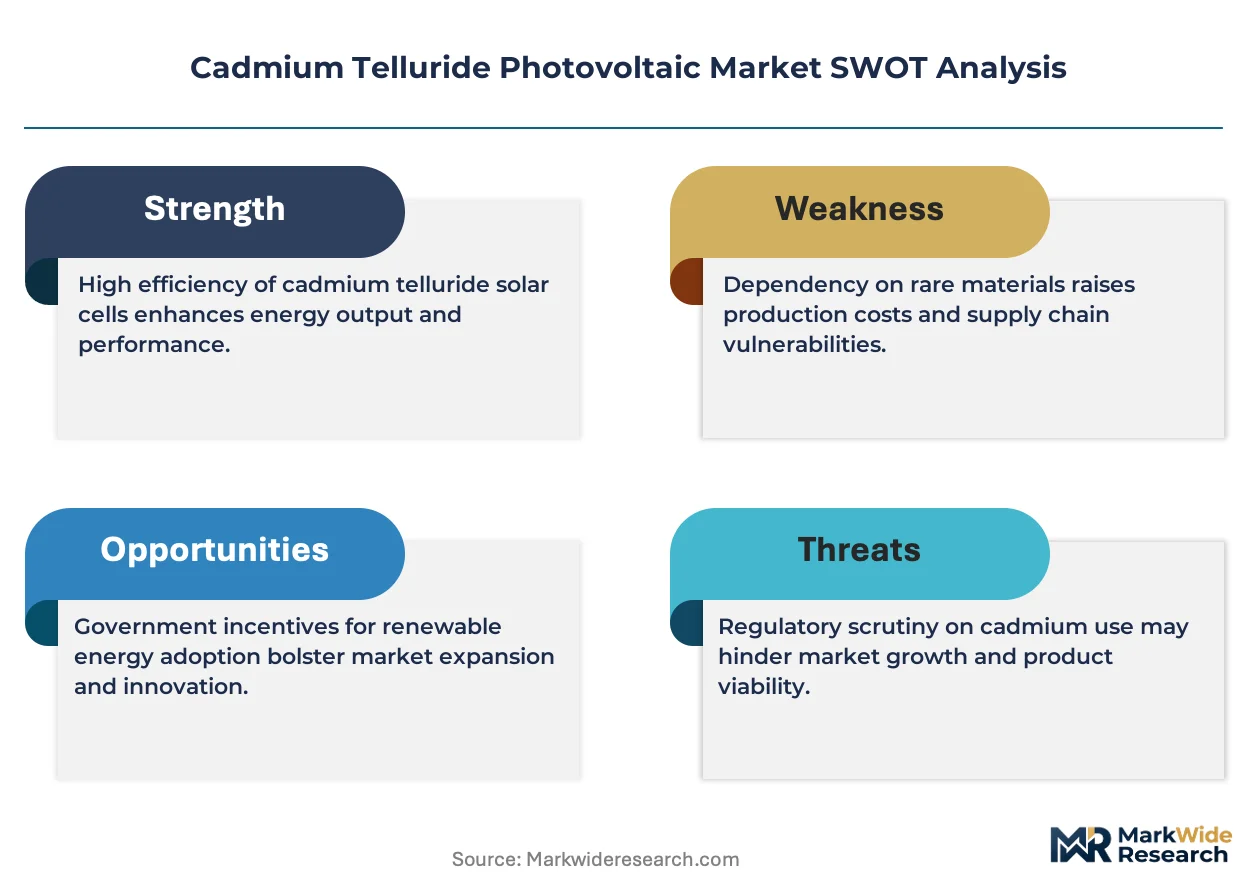
The US Inflation Reduction Act is hardening the cost-of-entry calculus for foreign-made thin-film modules by attaching domestic content bonuses to project finance. First Solar leverages integrated manufacturing across Ohio, Alabama, and Louisiana to capture these incentives. Calyxo anchors European supply through its German deposition expertise, while CNBM Optoelectronic Materials competes on scale from its Chinese production base.
Cadmium telluride photovoltaic technology deposits a p-type CdTe absorber layer one to eight micrometers thick onto glass substrates via vapor transport deposition or close-space sublimation, converting sunlight at laboratory efficiencies exceeding 22 percent with a temperature coefficient superior to crystalline silicon. Thin-film modules dominate utility-scale procurement for their low manufacturing energy and rapid payback, while bifacial modules represent the fastest-growing product type as developers seek incremental energy yield from albedo reflection. Building-integrated photovoltaics remain a margin pool constrained by aesthetic and structural certification complexity.
The US EPA regulates cadmium content under the Resource Conservation and Recovery Act, while the EU REACH framework classifies cadmium compounds and restricts their use in new electrical equipment. India's BIS mandates module certification under IS 14286, creating divergent compliance pathways that fragment market access. Stakeholders must monitor how the EU's forthcoming Critical Raw Materials Act reshapes cadmium sourcing obligations and whether the US Department of Commerce circumvention inquiries expand to Southeast Asian CdTe assembly.
Market Dynamics
The US Inflation Reduction Act's domestic content bonuses have restructured manufacturing location decisions, concentrating thin-film module production in American states with established deposition expertise and favorable project finance terms.
Growth Catalysts
- Utility-scale solar procurement:Developers in the southwestern United States favor CdTe modules for their superior temperature coefficients and rapid energy payback in high-irradiance desert conditions.
- REACH regulatory clarity:The EU framework's explicit cadmium compound classifications enable compliant manufacturers to pre-certify modules for European renewable auctions.
- Vapor transport deposition:This deposition technique reduces manufacturing energy intensity compared to crystalline silicon, aligning with corporate procurement mandates for low-carbon supply chains.
Market Restraints
- Cadmium supply concentration:Primary cadmium sourcing ties to zinc smelting byproduct recovery, creating geographic concentration risk in Chinese and Korean refining capacity.
- Tellurium scarcity:This rare metalloid's extraction from copper anode slimes limits annual supply elasticity, constraining module output scaling during demand surges.
- Crystalline silicon substitution:PERC and TOPCon cell efficiencies above 24 percent in mass production threaten CdTe's cost-positioning in rooftop distributed generation.
Strategic Opportunities
- Building-integrated photovoltaics:Aesthetic CdTe modules with customizable tinting and transparency open architectural specification channels in commercial facade retrofits.
- India's PLI scheme:Production-linked incentives for domestic solar manufacturing create entry pathways for thin-film technology transfer partnerships.
- Bifacial module architecture:Dual-glass CdTe designs capturing albedo reflection from desert surfaces and snow-covered ground unlock incremental yield for utility developers.
Industry Challenges
- Deposition technician scarcity:Close-space sublimation and vapor transport deposition require specialized semiconductor processing skills concentrated in legacy thin-film manufacturing regions.
- Module certification timelines:BIS IS 14286 testing protocols in India and IEC 61215 variant approvals across European notified bodies extend product launch cycles.
- Closed-loop recycling infrastructure:End-of-life module recovery systems for cadmium and tellurium reclamation remain underdeveloped outside German and Ohio processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cadmium Telluride Photovoltaic Market |
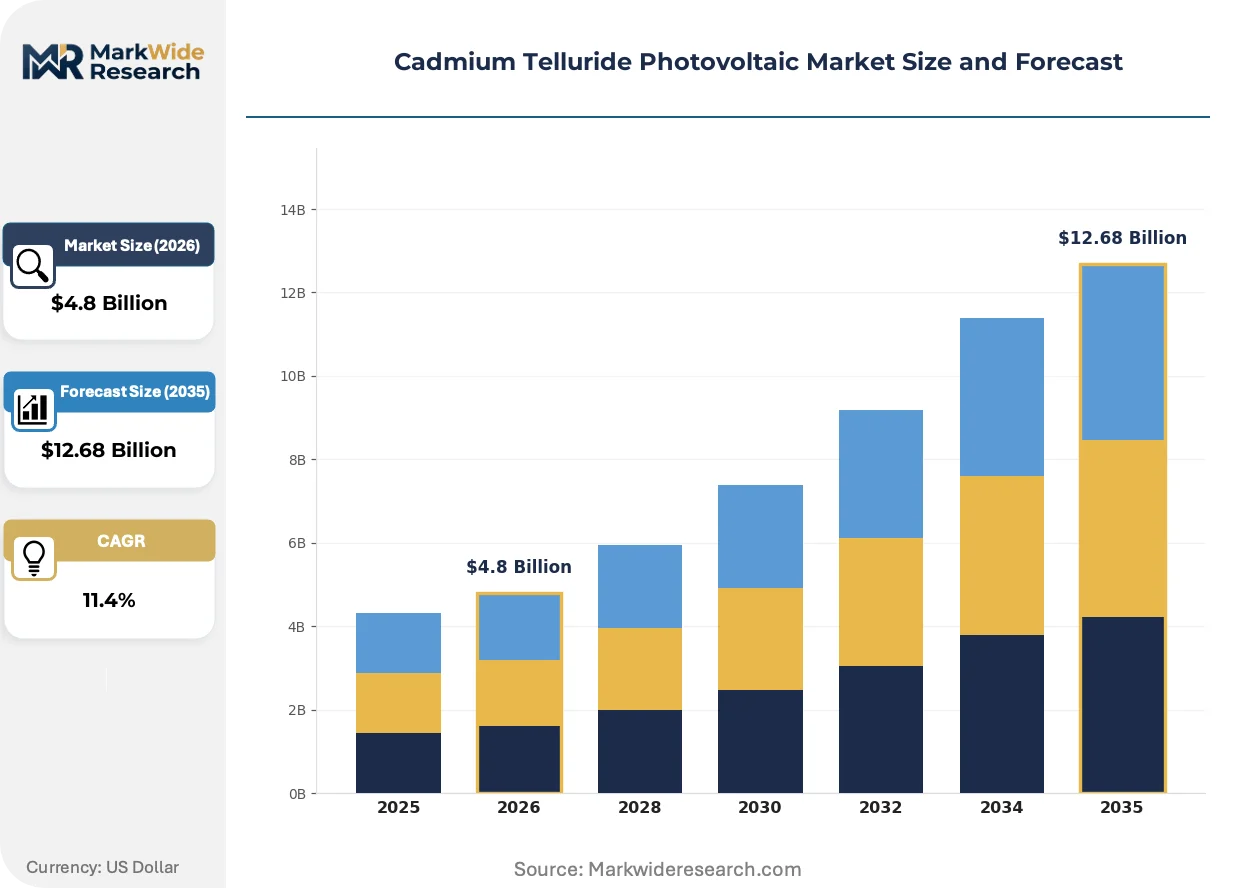
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film Modules, Standard Modules, Bifacial Modules, Integrated Systems End User: Residential, Commercial, Industrial, Utility Application: Power Generation, Off-Grid Systems, Building-Integrated Photovoltaics, Solar Farms Installation Type: Ground Mounted, Roof Mounted, Floating Solar, Hybrid Systems |
| Companies Covered | Calyxo, CTF Solar, First Solar, Dmsolar, D2solar, Antec Solar, CNBM Optoelectronic Materials, Willard & Kelsey Solar, Advanced Solar Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cadmium Telluride Photovoltaic Market Emerging Trajectories
Thin-film photovoltaic architecture is converging with bifacial designs and building-integrated form factors, expanding CdTe modules beyond utility-scale ground-mount into distributed and architectural applications.
Selenium alloying in CdTe absorber layers is integrating into commercial production lines, boosting laboratory cell efficiencies past 22 percent while maintaining the technology's favorable temperature coefficient. Tier-one manufacturers deploy this formulation across Ohio and Alabama fabrication facilities to meet domestic content thresholds for IRA bonus eligibility. The integration is compressing the efficiency gap with crystalline silicon in high-temperature operating environments.
REACH authorization requirements for cadmium compounds in electrical equipment are tightening compliance documentation burdens for EU market entry. Manufacturers must submit substance safety dossiers to ECHA and demonstrate closed-loop recycling commitments to qualify for renewable energy tenders. German and French utility-scale developers now specify REACH-compliant thin-film modules exclusively, filtering non-compliant Asian supply.
Long-term power purchase agreements with corporate offtakers are displacing merchant utility sales as the dominant procurement channel for CdTe project deployment. Data center operators and heavy manufacturers in Texas and Arizona contract directly with project developers for 15-20 year supply, bypassing traditional utility intermediaries. This pattern concentrates demand in southwestern states with transmission interconnection availability and established thin-film installation expertise.
Cadmium Telluride Photovoltaic Market Segmentation
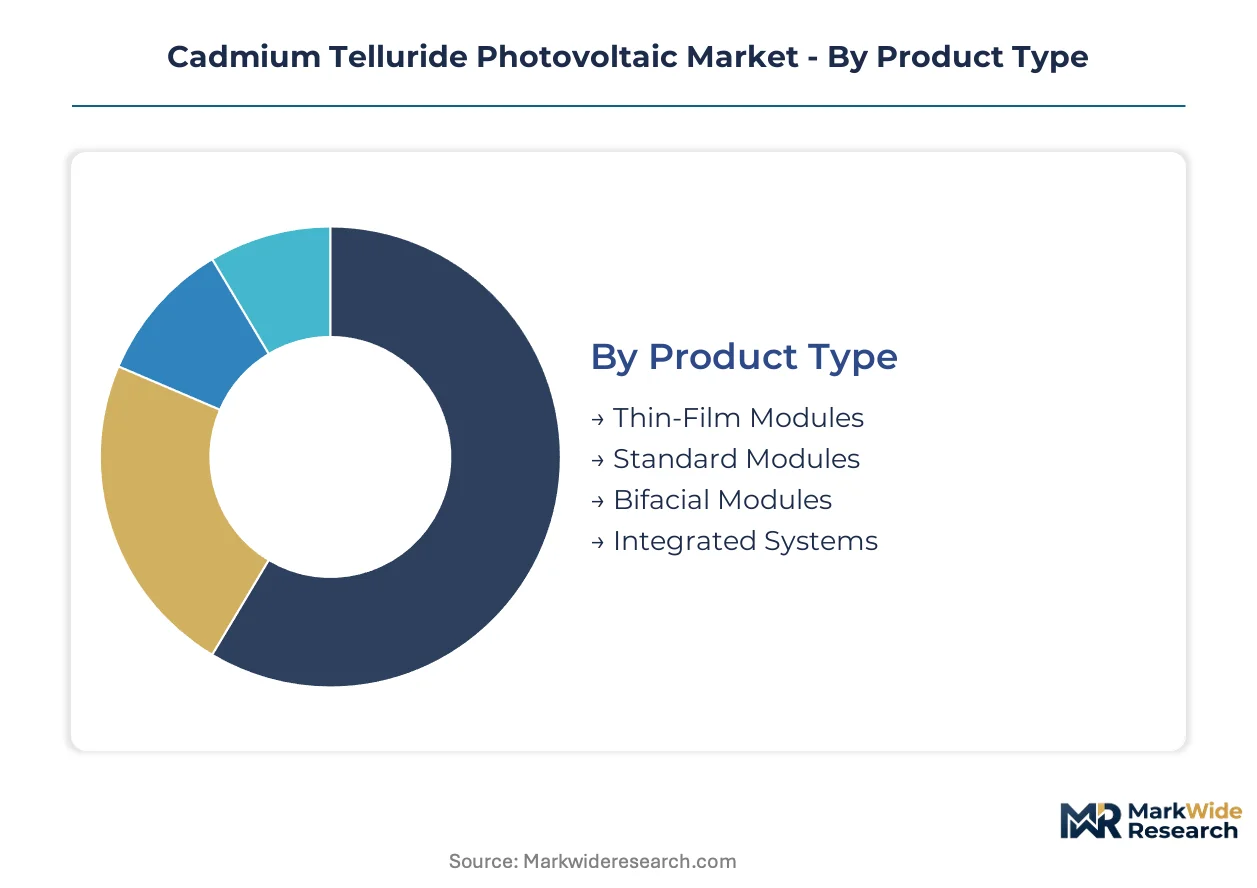
Cadmium telluride module demand fragments across four structural dimensions, each governing distinct procurement patterns and margin profiles. Product architecture determines manufacturing capital intensity, while end-user scale dictates financing mechanisms and regulatory exposure.
Product Type:
Thin-film CdTe manufacturing demands specialized vapor deposition equipment and cleanroom infrastructure, concentrating capital deployment among integrated producers.
- Thin-Film Modules:Glass-substrate CdTe deposition via close-space sublimation achieves absorber layers one to eight micrometers thick with superior temperature coefficients. Utility-scale developers in Arizona and Texas specify these modules for desert installations where heat degradation crushes crystalline silicon output.
- Bifacial Modules:Dual-glass architectures capture albedo reflection from sand, snow, and reflective roofing, boosting energy yield fifteen to twenty percent over monofacial equivalents. Ground-mounted solar farms in Nevada and Colorado favor this form factor for incremental capacity without additional land consumption.
- Standard Modules:Conventional frame-and-glass designs dominate retrofit replacements and distributed commercial rooftops where structural load limits restrict heavier bifacial assemblies.
- Integrated Systems:Pre-wired module-plus-inverter packages reduce balance-of-system labor for residential installers in California and Florida markets.
Thin-film modules absorb the bulk of installed capacity; bifacial modules are expanding most quickly.
End User:
Customer scale determines project finance complexity, with utility offtakers accessing tax equity structures unavailable to residential borrowers.
- Utility:Independent power developers and regulated utilities deploy CdTe arrays exceeding one hundred megawatts, leveraging long-term power purchase agreements with corporate offtakers in Texas and Arizona. IRA domestic content bonuses structure procurement toward American-manufactured thin-film supply.
- Industrial:Heavy manufacturers and data center operators contract directly for behind-the-meter solar, prioritizing rapid energy payback and low-carbon supply chain credentials for Scope 2 emissions reduction.
- Commercial:Retail chains and office portfolios install rooftop systems under net metering regimes, constrained by interconnection queue delays in saturated distribution networks.
- Residential:Single-family installations favor lightweight thin-film modules for structural compatibility, though crystalline silicon dominates this segment on efficiency-per-watt metrics.
Utility procurement commands the dominant share of megawatt deployment; industrial self-generation is climbing the fastest.
Application:
Site constraints and grid connectivity shape technology selection, with remote locations favoring off-grid architectures.
- Solar Farms:Centralized ground-mount arrays exceeding fifty megawatts concentrate CdTe demand in southwestern states with transmission interconnection availability and Bureau of Land Management lease access.
- Building-Integrated Photovoltaics:CdTe's customizable tinting and transparency enable facade and skylight integration, though aesthetic certification complexity limits this segment to premium commercial retrofits in New York and Chicago.
- Power Generation:Grid-connected utility-scale deployment remains the default application, with merchant and contracted offtake structures determining project economics.
- Off-Grid Systems:Remote telecommunications, mining operations, and agricultural pumping in rural Texas and New Mexico deploy CdTe arrays with battery storage where distribution extension is uneconomical.
Solar farms dominate cumulative installed capacity; building-integrated photovoltaics is gaining share fastest.
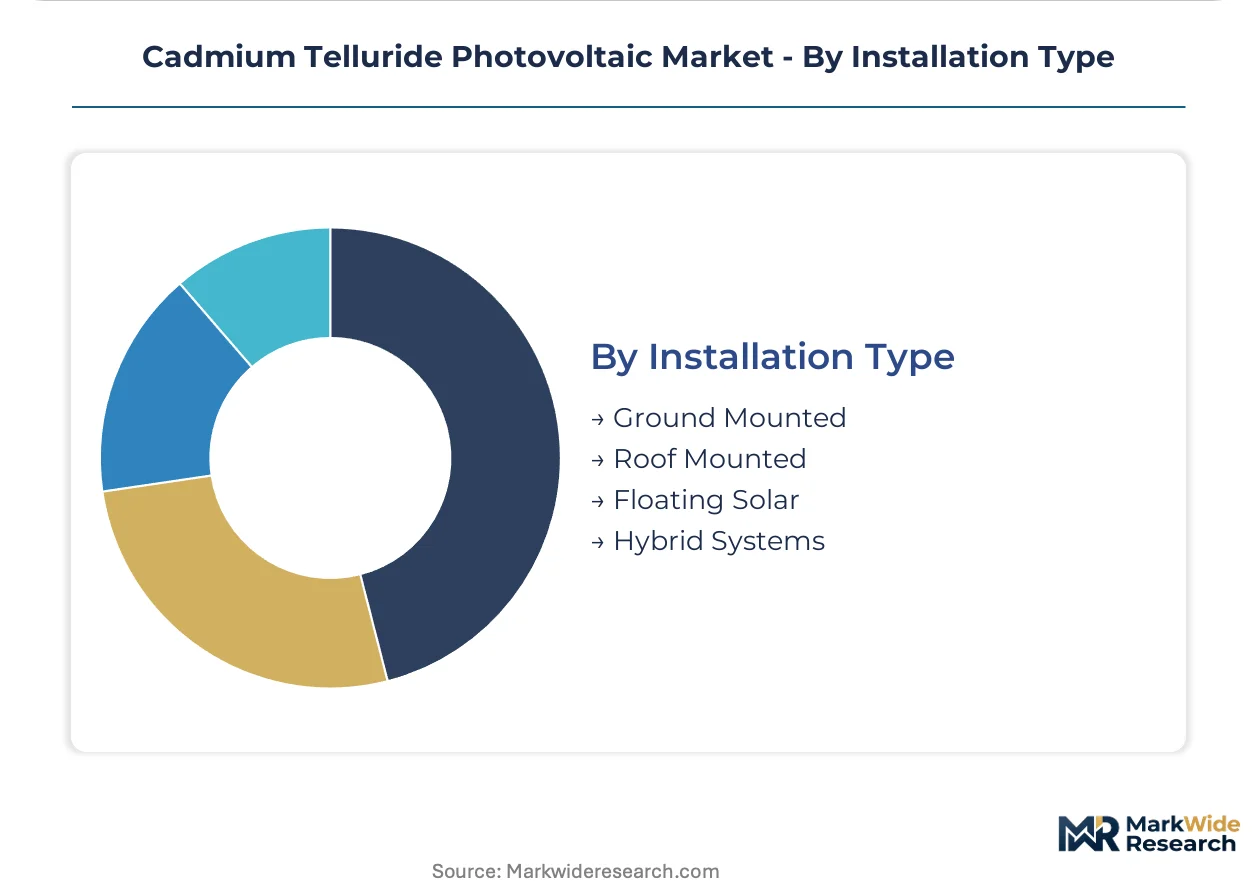
Installation Type:
Mounting configuration determines labor intensity and land use efficiency, with ground-mount systems benefiting from standardized racking economies.
- Ground Mounted:Fixed-tilt and tracking systems on graded desert terrain enable utility-scale deployment with minimal structural engineering overhead. CdTe's favorable temperature coefficient maximizes output in high-irradiance, high-temperature conditions.
- Roof Mounted:Commercial flat-roof ballasted systems and residential pitched-roof penetrations demand lightweight modules and rapid installation protocols to minimize labor cost.
- Floating Solar:Reservoir and quarry installations in California and Florida exploit water surface area while reducing evaporation, though CdTe adoption lags crystalline silicon in this nascent segment.
- Hybrid Systems:Co-located solar-plus-storage configurations pair CdTe generation with lithium-ion batteries, capturing IRA investment tax credit adders for domestic content and energy community siting.
Ground-mounted systems carry the majority of deployed capacity; hybrid configurations are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers in the southwestern United States absorb the dominant share of cadmium telluride module procurement, driven by IRA domestic content bonuses and superior desert performance economics. Manufacturing investment clusters in American states with established thin-film expertise, while European and Asian markets operate under divergent regulatory frameworks for cadmium compound use.
United States
Texas and Arizona utility-scale projects specify CdTe modules for their favorable temperature coefficients in high-irradiance desert conditions. The IRA's domestic content adders structure procurement toward American-manufactured supply, with Ohio and Alabama fabrication facilities capturing bonus eligibility. First Solar's integrated production across multiple states anchors domestic thin-film capacity expansion.
Germany
Calyxo's deposition expertise in Thuringia supplies European renewable auctions with REACH-compliant modules. The ECHA authorization framework mandates closed-loop recycling commitments for cadmium compound use in electrical equipment. German utility-scale developers now specify thin-film modules exclusively from pre-certified domestic supply.
China
CNBM Optoelectronic Materials leverages scale advantages from its Chinese production base for cost-sensitive procurement channels. The country's national environmental regulator monitors cadmium discharge from zinc smelting byproduct recovery operations. Yangtze River Delta industrial clusters concentrate tellurium refining capacity tied to copper anode slime processing.
India
The PLI scheme for domestic solar manufacturing creates technology transfer pathways for thin-film deposition partnerships. BIS mandates IS 14286 module certification, extending product launch timelines for foreign suppliers. Gujarat and Rajasthan states concentrate utility-scale project development with high solar irradiance profiles.
Japan
METI procurement guidelines favor low-carbon manufacturing credentials for utility-scale solar tenders. JIS standards govern module performance certification, creating compliance documentation requirements distinct from IEC frameworks. Kyushu regional utilities evaluate bifacial CdTe architectures for agricultural co-location projects.
Cadmium Telluride Photovoltaic Market Vendor Landscape
American producers anchor one tier of module supply; German and Chinese specialists hold complementary positions in regional markets. The vendor base concentrates around integrated thin-film manufacturers with captive deposition expertise, while smaller regional fabricators serve niche architectural specifications. Two strategic archetypes dominate: vertically integrated energy companies controlling raw material through module assembly, and technology licensors enabling regional production partnerships. Competitive positioning hardens through domestic content compliance for IRA bonus capture and REACH authorization dossier preparation for European market entry.
Among American-integrated manufacturers, First Solar occupies the scale-driven position with multi-state fabrication infrastructure. Calyxo exemplifies European specialization in vapor transport deposition technology for compliant supply chains. CNBM Optoelectronic Materials represents Chinese production-scale competition in cost-sensitive procurement channels. These three anchors illustrate how geographic regulatory alignment shapes competitive segmentation across IRA-driven American deployment, REACH-governed European tenders, and price-sensitive Asian markets.
| Leading Market Players |
|---|
| Calyxo |
| CTF Solar |
| First Solar |
| Dmsolar |
| D2solar |
| Antec Solar |
| CNBM Optoelectronic Materials |
| Willard & Kelsey Solar |
| Advanced Solar Power |
| Others |
Supply Flow & Price Mechanics
REACH authorization requirements for cadmium compounds gate both qualified European supply and premium-tier pricing access for compliant manufacturers, compressing margins for non-certified Asian competitors while rewarding domestic content alignment in American markets.
Pricing Analysis
Short lead-time premiums dominate module procurement economics, with utility developers paying contract premiums for guaranteed delivery windows against crystalline silicon spot alternatives. Three-tier pricing structure across IRA-compliant domestic, REACH-authorized European, and standard import tiers reflects certification grade and geographic delivery cost differentials. Cost compression in the standard import tier is intensifying because of circumvention inquiry exposure and tariff uncertainty. Industrial offtakers in Texas and Arizona exhibit lowest price sensitivity due to long-term power purchase agreement structures, while distributed commercial installers face acute margin pressure from interconnection queue delays.
Supply Chain Analysis
IEC 61215 and BIS IS 14286 certification gating fragments qualified supplier pools, extending product launch timelines and concentrating procurement among pre-certified integrated manufacturers. Tellurium refining capacity draws from copper anode slime processing concentrated in China, Japan, and South Korea, while cadmium recovery hinges on zinc smelting byproduct streams from Chinese and Korean refineries. Single-source vulnerability in tellurium supply constrains module output scaling during demand surges. Distribution runs through direct utility-scale EPC contracts and regional distributor networks serving commercial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Inflation Reduction Act's domestic content bonuses erect a cost-of-compliance moat around American manufacturing, filtering non-compliant foreign supply from bonus-eligible procurement channels.
For Market Incumbents: To counter crystalline silicon efficiency gains above 24 percent in mass production, anchor capacity expansion in Ohio and Alabama to preserve IRA bonus eligibility, while investing in selenium alloying R&D to compress the efficiency gap in high-temperature operating environments. For New Entrants and Emerging Players: Utility-scale EPC contractors in Texas and Arizona represent the most accessible channel partners for thin-film technology transfer, given their procurement concentration and established installation expertise. Target India's PLI scheme for domestic manufacturing partnerships, and wedge through building-integrated photovoltaics specification channels in commercial facade retrofits where aesthetic customization commands premium positioning. For Investors and Strategic Acquirers: First Solar's multi-state fabrication announcements are the leading indicator that domestic content compliance is consolidating competitive advantage around integrated American producers. Five-to-ten-year viability favors vertically integrated specialists with captive tellurium sourcing and closed-loop recycling infrastructure. Watch EU Critical Raw Materials Act implementation timelines as the signal for cadmium sourcing obligation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Compliance Investment | IRA bonus eligibility in Ohio and Alabama fabrication facilities locks in procurement preference from utility developers. |
| Selenium Alloying Production Integration | Laboratory cell efficiencies past 22 percent compress the gap with crystalline silicon in desert installations. |
| Closed-Loop Recycling Infrastructure Buildout | German and Ohio processing facilities satisfy REACH authorization requirements for European market entry. |
| Bifacial Module Architecture Deployment | Dual-glass designs capturing albedo reflection unlock incremental yield for Nevada and Colorado ground-mount projects. |
| Technology Licensing Partnership | India's PLI scheme creates entry pathways for vapor transport deposition expertise transfer to domestic manufacturers. |
Methodological Framework
Trade customs databases, FERC interconnection filings, and ECHA authorization registries formed the secondary backbone, cross-referenced with primary interviews spanning thin-film manufacturing executives, utility procurement officers, EPC project developers, and cadmium refining specialists. Bottom-up and top-down triangulation validated installed capacity figures against module shipment records and project development pipeline databases.
Bottom-up modeling aggregated individual project economics across utility-scale, industrial, commercial, and residential segments, while top-down analysis calibrated aggregate market sizing against national renewable auction awards and corporate power purchase agreement disclosures. Segmentation dimensions included product architecture, end-user scale, application type, and installation configuration. CAGRs were derived from regression analysis of historical deployment trajectories and policy incentive elasticity assumptions, incorporating tellurium supply constraints and domestic content bonus uptake curves as industry-specific forecast inputs.
Caveats apply where tellurium supply disruptions, IRA domestic content rule revisions, or EU Critical Raw Materials Act implementation could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Gunn Diode Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Europe Wigig Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
EPON ONU Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Thermophotovoltaics Market