
 Laser Technology Market | 2026-2036
Laser Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Technology Market Intelligence
Project finance and equipment leasing is tilting competitive dynamics toward asset-light entrants in the laser technology sector. Trumpf sustains manufacturing scale dominance through captive production of resonator components. IPG Photonics anchors fiber laser supply chains with backward integration into diode and fiber manufacturing. Coherent differentiates through vertical control over crystal growth and optical coating processes.
Laser technology encompasses coherent light amplification systems operating across ultraviolet to infrared wavelengths, typically achieving beam qualities below 2.0 M² and power densities exceeding 10⁶ W/cm² for industrial cutting and medical ablation. Fiber lasers now lead material processing deployments due to wall-plug efficiency above 30% and minimal maintenance requirements. Solid-state lasers occupy premium medical and scientific niches where pulse stability and beam quality command higher pricing. Semiconductor lasers dominate communication applications as telecom operators scale coherent transmission architectures.
FDA device classifications govern medical laser safety and efficacy requirements in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances in laser component manufacturing. China's GB standards and MIIT directives shape domestic product certification and export eligibility for laser equipment. Stakeholders must monitor evolving dual-use export controls and carbon-border adjustments that will reshape sourcing decisions for high-power laser systems.
Market Dynamics
Fiber laser efficiency gains above 30% wall-plug efficiency are accelerating replacement cycles across precision manufacturing clusters, compressing equipment lifecycles from 15 to 8 years in automotive and electronics fabrication.
Growth Catalysts
- Minimally Invasive Surgical Adoption:Hospitals in Germany and the United States are expanding procurement of solid-state laser systems for ophthalmic and dermatological procedures under FDA and MDR safety frameworks.
- Industrial Automation Mandates:China's MIIT directives on smart manufacturing are driving fiber laser integration into robotic cutting and welding lines across precision metalworking hubs.
- Telecom Infrastructure Buildout:Coherent transmission architectures by major carriers are amplifying semiconductor laser demand for 400G and 800G optical interconnects.
Market Restraints
- Rare Earth Supply Concentration:Ytterbium and neodymium fiber doping materials concentrate in Chinese processing facilities, creating single-source vulnerability for resonator manufacturers.
- High-Power System Certification Delays:FDA 510(k) and MDR Class IIb approval timelines for medical laser devices extend 18-24 months, freezing product launches.
- Plasma Cutting Substitution:Thick-plate metal fabricators above 25mm retain cost advantages with plasma arc systems, limiting fiber laser penetration in heavy shipbuilding.
Strategic Opportunities
- Battery Cell Welding Expansion:Gigafactory construction in the United States and Germany is opening dedicated procurement channels for fiber laser welding of 4680 cylindrical cells.
- EU Green Deal Alignment:Carbon-border adjustment mechanisms are incentivizing European manufacturers to replace CO2 lasers with fiber systems for energy intensity compliance.
- Additive Manufacturing Convergence:Powder bed fusion and directed energy deposition systems are integrating multi-kilowatt fiber lasers with real-time melt pool monitoring.
Industry Challenges
- Photonics Engineering Talent Scarcity:Resonator design and beam delivery optimization require specialized optical physics expertise that outpaces university pipeline output in precision manufacturing regions.
- Legacy System Integration Complexity:Automotive Tier-1 suppliers face retrofit friction when embedding fiber lasers into existing CO2 laser production lines with incompatible beam delivery infrastructure.
- Dual-Use Export Control Navigation:High-power military-grade laser components trigger ITAR and EU dual-use regulation reviews that delay international shipments by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Technology Market |
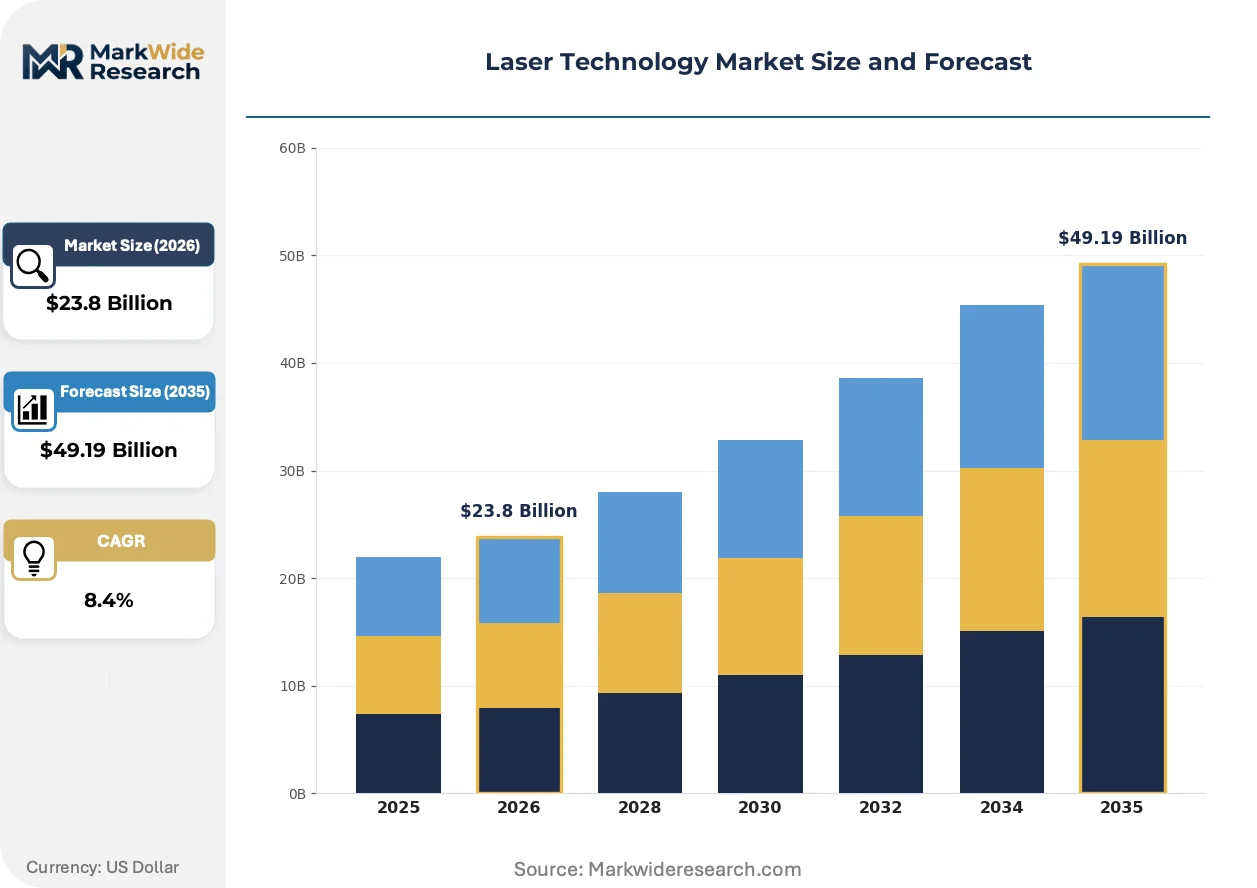
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $49.19 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Laser, Gas Laser, Fiber Laser, Semiconductor Laser, Dye Laser Application: Material Processing, Medical Treatment, Communication, Defense, Scientific Research Technology: Pulsed Laser, Continuous Wave Laser, Q-Switched Laser, Mode-Locked Laser, Excimer Laser End User: Manufacturing Units, Hospitals, Telecom Operators, Aerospace Firms, Research Laboratories |
| Companies Covered | Coherent, Trumpf, Han's Laser Technology Industry Group, IPG Photonics, Jenoptik AG, Lumentum, Novanta, Corning Incorporated, MKS Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Technology Market Strategic Shifts & Innovations
Beam quality improvements and wavelength tunability are compressing application boundaries between laser types, enabling single-platform deployment across medical, industrial, and communication verticals previously served by distinct technologies.
Ultrafast picosecond and femtosecond lasers are collapsing thermal damage zones in medical ablation and micromachining applications. Dermatology clinics and stent manufacturers are adopting these systems at 35% annual clip. Cold ablation physics is collapsing the distinction between cutting and finishing processes, eliminating post-processing steps in cardiovascular device fabrication.
REACH substance restrictions and RoHS hazardous material limits are forcing reformulation of optical coatings and crystal growth dopants. European laser component suppliers are relocating crystal boule production to Switzerland and Austria to maintain CE marking eligibility. Medical device OEMs are most affected, redesigning erbium and holmium laser rods to eliminate restricted heavy metals.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized job shops. German and Japanese machine tool distributors are bundling fiber laser cutting heads with per-minute usage fees and predictive maintenance. Automotive stamping suppliers in Bavaria and Michigan are piloting these arrangements to reduce balance-sheet exposure during demand volatility.
Laser Technology Market Segmentation
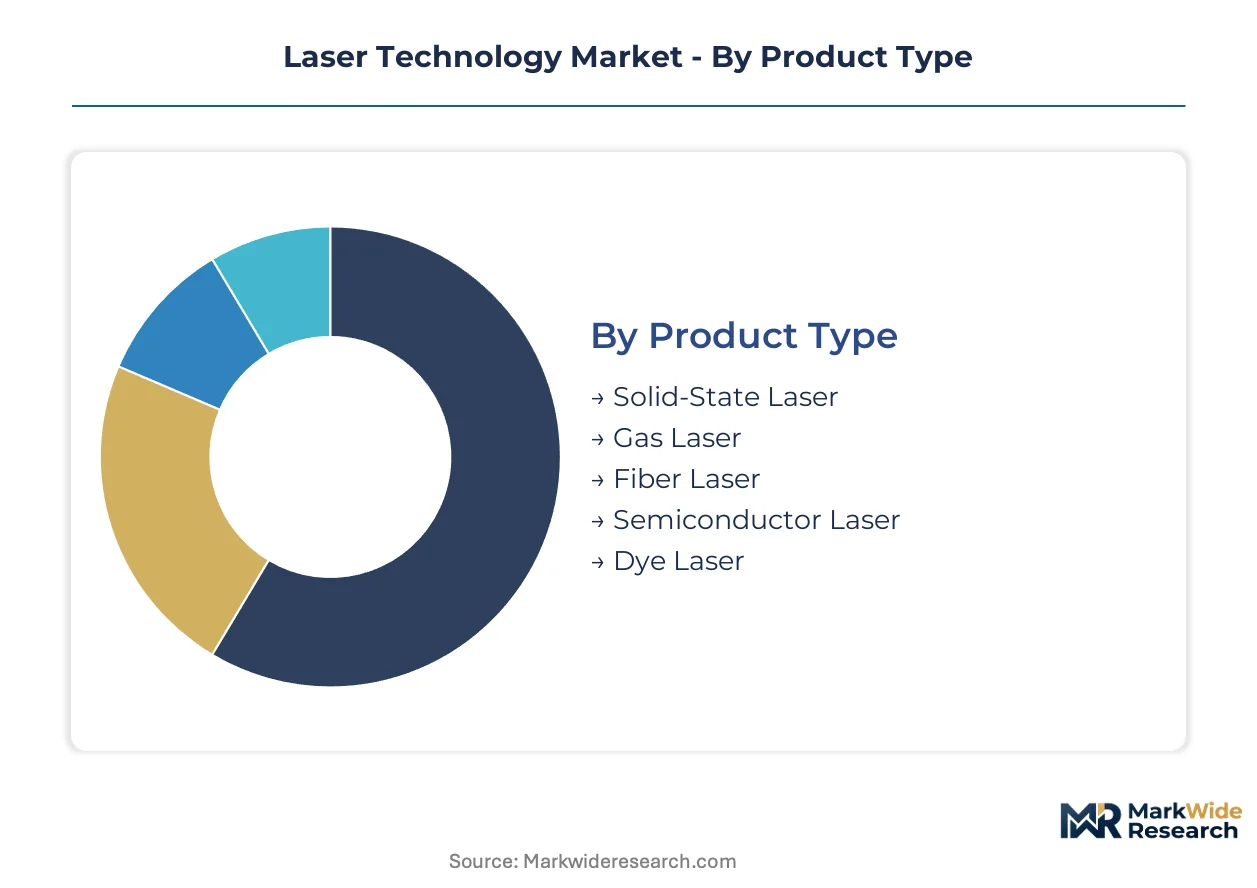
Segmentation reveals distinct service intensity patterns across laser technology categories. Product type determines resonator replacement cycles and field calibration frequency. Application context shapes regulatory compliance burdens and training requirements.
Product Type:
After-sales-service intensity varies sharply by resonator architecture and cooling system complexity.
- Fiber Laser:Diode-pumped ytterbium-doped fiber architectures achieve wall-plug efficiency above 30% with sealed resonator designs that eliminate mirror alignment service calls. German automotive stamping plants and Chinese electronics fabrication hubs are standardizing procurement on 6-8 kilowatt systems for robotic cutting lines, compressing replacement cycles from 15 to 8 years through reliability gains.
- Solid-State Laser:Nd:YAG and Nd:YVO4 crystal rods require annual thermal lensing compensation and flashlamp replacement every 2,000 hours. Hospitals in the United States and Germany specify these systems for ophthalmic capsulotomy and dermatological resurfacing under FDA 510(k) and MDR Class IIb frameworks where pulse stability commands premium pricing.
- Gas Laser:CO2 discharge tubes demand gas refill logistics and mirror cleaning protocols every 500 operating hours. Legacy metal fabricators retain installed bases for thick-plate cutting above 25mm where plasma substitution has not yet displaced capital investment.
- Semiconductor Laser:Edge-emitting and VCSEL diode arrays integrate directly into telecom transceivers with minimal field service beyond thermal management verification. Coherent transmission deployments by carriers in China and the United States are scaling 400G and 800G interconnect demand.
- Dye Laser:Organic dye circulation systems require weekly solvent replacement and optical cavity realignment. Research laboratories in spectroscopy and photochemistry applications sustain niche procurement despite operational complexity.
By volume, Semiconductor Laser leads. By growth pace, Fiber Laser is ahead.
Application:
Margin structures diverge based on regulatory certification depth and customer technical sophistication.
- Material Processing:Multi-kilowatt cutting and welding systems integrate into automated production lines with predictive maintenance contracts. Chinese MIIT smart manufacturing directives are accelerating fiber laser penetration across precision metalworking clusters in Jiangsu and Guangdong provinces.
- Medical Treatment:FDA and MDR compliance burdens extend approval timelines 18-24 months for Class IIb devices. German hospitals and United States ambulatory surgery centers are expanding solid-state laser procurement for minimally invasive ophthalmic and dermatological procedures.
- Communication:Telecom operators specify semiconductor lasers for coherent transmission architectures with 15-year reliability requirements. 400G and 800G optical interconnect buildouts in China, Germany, and the United States anchor volume procurement.
- Defense:ITAR and EU dual-use regulations trigger 6-12 month export review delays for high-power military-grade components. Directed energy and rangefinding applications concentrate procurement through national security channels.
- Scientific Research:Ultrafast pulse systems for spectroscopy and materials characterization command premium pricing from university and government laboratory budgets. Mode-locked titanium:sapphire and dye laser architectures sustain specialized demand.
By revenue concentration, Material Processing dominates. By margin expansion, Medical Treatment shows steepest trajectory.
Technology:
Customer acquisition costs scale with beam control complexity and application engineering requirements.
- Pulsed Laser:Nanosecond pulse durations balance peak power and thermal management for industrial marking and medical hair removal. Chinese manufacturing units and United States dermatology clinics represent parallel demand channels with distinct certification pathways.
- Continuous Wave Laser:Uninterrupted emission enables stable heat input for welding and heat treating. German automotive Tier-1 suppliers specify these systems for battery cell tab welding in gigafactory construction projects.
- Q-Switched Laser:Cavity dumping achieves megawatt peak powers for micromachining and tattoo removal. Industrial job shops and aesthetic clinics share technology platforms with divergent service contract structures.
- Mode-Locked Laser:Femtosecond pulse trains enable cold ablation with negligible heat-affected zones. Stent manufacturers and research laboratories in Germany and the United States are adopting these systems for cardiovascular device fabrication.
- Excimer Laser:UV wavelengths drive photochemical ablation in semiconductor lithography and vision correction. ASML supply chains and LASIK equipment OEMs sustain concentrated procurement with extreme technical qualification barriers.
By installed base, Continuous Wave Laser leads. By technology transition velocity, Mode-Locked Laser is gaining share fastest.
End User:
Procurement authority concentration determines contract negotiation leverage and pricing transparency.
- Manufacturing Units:Automotive, electronics, and metal fabrication facilities specify integrated laser-material-handling systems with throughput guarantees. Chinese precision manufacturing clusters and German machine tool OEMs represent contrasting procurement cultures with divergent service intensity expectations.
- Hospitals:Capital equipment committees evaluate clinical efficacy evidence and total cost of ownership across 10-year depreciation horizons. United States health systems and German university hospitals prioritize FDA and MDR certification status in vendor qualification.
- Telecom Operators:Carrier procurement organizations negotiate volume commitments for coherent transmission modules with 15-year reliability specifications. China Mobile, Deutsche Telekom, and Verizon anchor demand concentration with stringent supplier audit protocols.
- Aerospace Firms:Boeing, Airbus, and COMAC specify laser drilling and welding systems for turbine blade and airframe fabrication with AS9100 quality system requirements. Dual-use export controls constrain vendor selection for military-grade applications.
- Research Laboratories:National science agencies and university physics departments procure customized systems with minimal standardization. Max Planck Institutes, Lawrence Livermore National Laboratory, and Chinese Academy of Sciences facilities sustain specialized demand with extended technical evaluation cycles.
By unit volume, Manufacturing Units lead. By specification complexity, Research Laboratories set the technical frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT smart manufacturing directives in China are accelerating fiber laser deployment across precision metalworking clusters. Germany's EU Green Deal alignment is forcing CO2 laser replacement cycles. FDA 510(k) pathways in the United States are shaping medical laser procurement timelines for hospital capital committees.
China
Jiangsu and Guangdong provinces anchor fiber laser demand from electronics fabrication and automotive stamping plants. MIIT directives mandate robotic cutting line integration with predictive maintenance protocols. Shenzhen and Suzhou precision manufacturing clusters are standardizing on 6-8 kilowatt systems for battery cell tab welding.
Germany
Bavarian automotive Tier-1 suppliers specify fiber lasers for gigafactory construction projects under EU carbon-border adjustment pressure. REACH substance restrictions force crystal boule production relocation to Switzerland and Austria. Stuttgart and Munich machine tool OEMs pilot equipment-as-a-service contracting with per-minute usage fees.
United States
Michigan and Ohio automotive stamping suppliers retrofit fiber lasers into legacy CO2 production lines. FDA Class IIb approval timelines extend 18-24 months for solid-state ophthalmic systems. Lawrence Livermore National Laboratory and Boston-area research facilities sustain ultrafast laser demand for materials characterization.
Japan
METI industrial automation standards drive fiber laser integration into robotic welding lines across Nagoya and Osaka manufacturing hubs. JIS certification requirements shape resonator reliability specifications for export eligibility. Toyota and Honda supply chain partners compress equipment replacement cycles through efficiency benchmarking.
South Korea
Seoul Capital Area semiconductor foundries amplify demand for excimer and deep-ultraviolet lithography systems. MFDS medical device regulations parallel FDA frameworks for laser surgical equipment approval. Samsung and SK Hynix supply chains concentrate procurement of coherent transmission modules for 400G optical interconnects.
Laser Technology Market Key Industry Players
On the supply side, the industry is consolidating around resonator component captive production and backward integration into diode manufacturing. German and Chinese fabricators dominate multi-kilowatt system assembly. Two strategic archetypes prevail: vertically integrated resonator specialists and asset-light leasing platform operators. Competitive moves center on M&A for crystal growth capabilities and capacity expansion in ytterbium-doped fiber production.
Within the integrated component tier, Trumpf and IPG Photonics exemplify contrasting geographic anchoring strategies. Trumpf occupies a position among German-scale manufacturers with captive resonator production. IPG Photonics represents North American backward integration into diode and fiber manufacturing. Coherent sits within the specialty optics archetype with vertical control over crystal growth processes.
| Leading Market Players |
|---|
| Coherent |
| Trumpf |
| Han's Laser Technology Industry Group |
| IPG Photonics |
| Jenoptik AG |
| Lumentum |
| Novanta |
| Corning Incorporated |
| MKS Instruments |
| Others |
Cost & Logistics Intelligence
Jiangsu province's ytterbium-doped fiber production clusters anchor global resonator supply, concentrating pricing power among three vertically integrated manufacturers who dictate terms to downstream system assemblers. German automotive stampers and Chinese electronics fabricators face divergent cost structures based on proximity to these feedstock sources, with REACH compliance and MIIT certification layering additional cost premiums onto European and domestic Chinese deliveries respectively.
Pricing Analysis
Certification level (FDA 510(k)/MDR Class IIb/GB standard) creates the primary spread between premium medical-grade systems and industrial equipment. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales bundling intensity and resonator replacement guarantee duration. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers are scaling 6-8 kilowatt fiber laser production for robotic cutting lines. Hospital capital committees exhibit lowest price sensitivity due to 10-year depreciation horizons and clinical efficacy requirements, while mid-sized job shops demonstrate highest sensitivity and are migrating toward equipment-as-a-service contracting.
Supply Chain Analysis
Extended payment terms from 60 to 90 days and supply-chain finance facilities are proliferating among German machine tool OEMs to preserve distributor relationships amid capital expenditure volatility. Ytterbium and neodymium processing concentrates in China, with diode manufacturing anchored in the United States and Japan. Resonator production draws from rare earth fiber doping, crystal boule growth, and optical coating deposition as critical inputs. Single-source vulnerability in Chinese rare earth processing facilities poses structural risk to resonator manufacturers. Distribution runs through machine tool OEMs, hospital GPOs, and telecom carrier procurement organizations as dominant downstream channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts and per-minute usage fees are expanding at multiples of hardware growth, transforming capital equipment vendors into recurring-revenue platforms. Service-attach depth now determines enterprise valuation multiples across the competitive landscape.
For Market Incumbents: Build captive resonator production moats through backward integration into diode and fiber manufacturing to defend against asset-light leasing entrants. Add ytterbium-doped fiber capacity in Switzerland or Austria to circumvent REACH substance restrictions on crystal growth processes. Control hospital GPO contracting channels before FDA 510(k) approval timelines compress competitive windows for solid-state ophthalmic systems. For New Entrants and Emerging Players: Battery cell tab welding in United States and German gigafactory construction represents the most penetrable white-space target, with automotive Tier-1 suppliers seeking second-source fiber laser welding systems for 4680 cylindrical cells. Ultrafast picosecond systems for stent manufacturing offer parallel entry path with lower certification barriers than medical devices. Pursue equipment-as-a-service pilot programs with Bavarian and Michigan stamping suppliers to bypass capital purchase committee friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among machine tool OEMs bundling predictive maintenance with fiber laser cutting heads, offering superior cash flow quality versus pure hardware manufacturers. Crystal growth and optical coating capabilities represent priority acquisition archetypes given REACH-driven production relocation and supply concentration. Watch FDA 510(k) approval velocity for solid-state medical devices as inflection signal for margin expansion in the premium tier.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diode Manufacturing | IPG Photonics and Trumpf have demonstrated that captive diode production insulates margin pressure from rare earth supply volatility. |
| Equipment-as-a-Service Launch | German and Japanese distributors piloting per-minute fiber laser fees reduce balance-sheet exposure for Michigan and Bavarian automotive stampers. |
| REACH-Compliant Crystal Relocation | European component suppliers relocating boule production to Switzerland and Austria preserve CE marking eligibility for medical device OEMs. |
| Ultrafast Laser Platform Expansion | Picosecond and femtosecond systems for stent cold ablation eliminate post-processing steps in cardiovascular device fabrication. |
| Hospital GPO Partnership Deepening | Solid-state laser vendors securing United States health system contracts navigate 18-24 month FDA 510(k) timelines with committed volume pipelines. |
Research Approach
A standing panel of fiber laser system engineers, hospital biomedical equipment managers, automotive Tier-1 procurement directors, and telecom carrier optical interconnect specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through SEC 10-K filings, MIIT directive documentation, FDA 510(k) clearance databases, and German machine tool association production statistics. Bottom-up equipment shipment tracking and top-down manufacturing value-add estimates were triangulated to anchor volume and value outputs.
Scenario-bracketing around rare earth supply disruption, EU carbon-border adjustment implementation velocity, and FDA approval timeline variability bounded the forecast range across the projection horizon. Segmentation modeling incorporated product type (fiber/solid-state/gas/semiconductor/dye), application context (material processing/medical/communication/defense/scientific), technology architecture (pulsed/continuous wave/Q-switched/mode-locked/excimer), and end-user procurement authority concentration. CAGRs were derived from equipment replacement cycle compression observed in Chinese electronics fabrication and German automotive stamping, cross-referenced with resonator reliability improvement curves.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles among automotive OEMs or hospital construction spending would shift the trajectory. Forecasts reflect documented assumptions regarding MIIT smart manufacturing directive enforcement, REACH substance restriction phase-in schedules, and fiber laser efficiency improvement rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
North America Quantum Computing Market