
 Global Metamaterials Technologies Market | 2026-2036
Global Metamaterials Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metamaterials Technologies Market Foresight
North American defense contractors are rebalancing their supplier bases toward domestic metamaterial antenna producers. Kymeta Corporation leverages its satellite-terminal expertise to anchor maritime and aerospace channels. Echodyne Corp. competes on software-defined radar architectures that integrate metamaterial apertures. PIVOTAL COMMWARE specializes in 5G infrastructure, sustaining carrier relationships through reconfigurable intelligent surface deployments.
Metamaterials technologies are engineered composites with subwavelength periodic structures that manipulate electromagnetic, acoustic, or optical waves through negative refractive index or tailored permeability responses, typically fabricated via lithography, additive manufacturing, or self-assembly of metallic resonators and dielectric substrates. Electromagnetic metamaterials currently lead commercialization, with tunable architectures representing the fastest-expanding product category as reconfigurable intelligent surfaces gain traction in telecommunications infrastructure. Defense end users command the deepest margin pools, while automotive OEMs emerge as a volume growth vector for radar and lidar applications.
The US FAA and FCC jointly shape airspace and spectrum access requirements for metamaterial antenna systems, while the EU's CE marking and RoHS directives constrain material composition and electromagnetic compatibility certification pathways. China's MIIT and GB standards govern domestic 5G base station deployments using intelligent metasurfaces. Stakeholders must monitor evolving spectrum allocation rulings and dual-use export control classifications that determine market access for defense-adjacent technologies.
Market Dynamics
Defense procurement of radar-absorbing surfaces is accelerating across NATO-aligned militaries, creating concentrated demand pools that reshape supplier priorities toward electromagnetic stealth applications and away from civilian optical metamaterials.
Growth Catalysts
- EU F-Gas Regulation:Manufacturers are abandoning liquid-cooled electromagnetic systems for solid-state metamaterial alternatives that eliminate fluorinated gas dependencies.
- Telecommunications infrastructure:5G base station deployments using reconfigurable intelligent surfaces are absorbing capital from traditional antenna suppliers.
- Germany's photonics cluster:Concentrated R&D activity around Jena and Karlsruhe is pulling fabrication equipment and lithography talent into Central Europe.
Market Restraints
- Raw material concentration:Rare-earth element processing for magnetic metamaterials concentrates in China, exposing Western fabricators to supply interruption risks.
- Technical limitation:Broadband absorption across microwave through optical frequencies remains unachievable in single-layer architectures, forcing multi-stack complexity.
- Regulatory friction:Dual-use export control classifications under US ITAR and EU dual-use regulations delay cross-border technology transfers for defense-adjacent metamaterials.
Strategic Opportunities
- India's defense modernization:Indigenous radar-absorbent material programs under the Make in India framework offer entry points for lithography equipment suppliers.
- Automotive radar integration:77-81 GHz metamaterial antennas for adaptive cruise control systems represent underpenetrated volume demand from German and Japanese OEMs.
- Convergence of photonics and RF:Integrated photonic-metamaterial platforms for LiDAR are opening design wins in autonomous vehicle perception stacks.
Industry Challenges
- Specialized fabrication talent:Electromagnetic simulation expertise for subwavelength structure design remains scarce relative to expanding foundry capacity.
- Certification timelines:FAA airworthiness qualification for metamaterial antenna systems in commercial aviation extends development cycles beyond typical venture capital horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metamaterials Technologies Market |
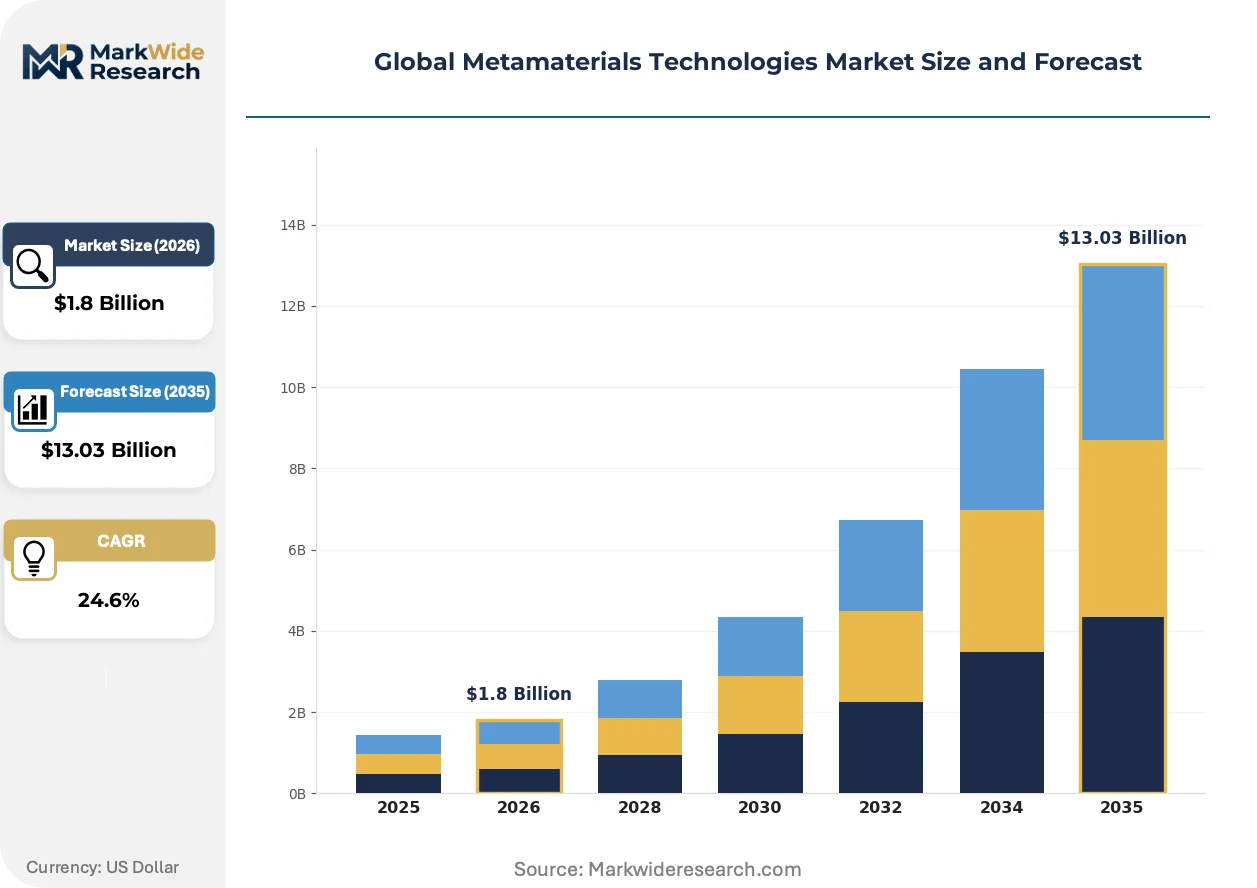
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photonic, Acoustic, Plasmonic, Electromagnetic, Mechanical Application: Radar Systems, Wireless Communication, Imaging Devices, Sensors, Antennas Product Type: Composite Metamaterials, Resonant Metamaterials, Transmission Line Metamaterials, Chiral Metamaterials, Tunable Metamaterials End User: Defense, Telecommunications, Consumer Electronics, Automotive OEMs, Aerospace |
| Companies Covered | Kymeta Corporation, Echodyne Corp., PIVOTAL COMMWARE, Lumotive, Meta Materials Inc., Metamaterial Technologies Inc., TeraView Limited, JEM Engineering LLC, Multiwave Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metamaterials Technologies Market Shifts & Advancements
Active tuning mechanisms and software-defined architectures are displacing passive metamaterial designs across defense and telecommunications applications, compressing product lifecycles and elevating firmware capabilities alongside physical fabrication.
Programmable metasurfaces with embedded varactor diodes and MEMS switches are absorbing development resources from fixed-frequency electromagnetic bandgap structures. North American defense contractors are fielding prototypes for cognitive radar systems that reconfigure aperture responses in microseconds. This capability is absorbing contract awards that previously flowed to conventional phased-array suppliers.
The EU's F-Gas Regulation is forcing thermal management redesigns across electromagnetic equipment manufacturers. Solid-state metamaterial cooling solutions are displacing compressor-based systems in high-power radar installations. German and French defense integrators are accelerating qualification programs to meet 2027 compliance deadlines.
Maritime satellite terminal operators are consolidating supplier relationships around vertically integrated metamaterial antenna providers. Traditional dish-and-gimbal vendors are losing position to flat-panel alternatives that reduce vessel fuel consumption through drag reduction. This pattern is most visible in North Sea and Mediterranean commercial shipping fleets.
Global Metamaterials Technologies Market Segmentation
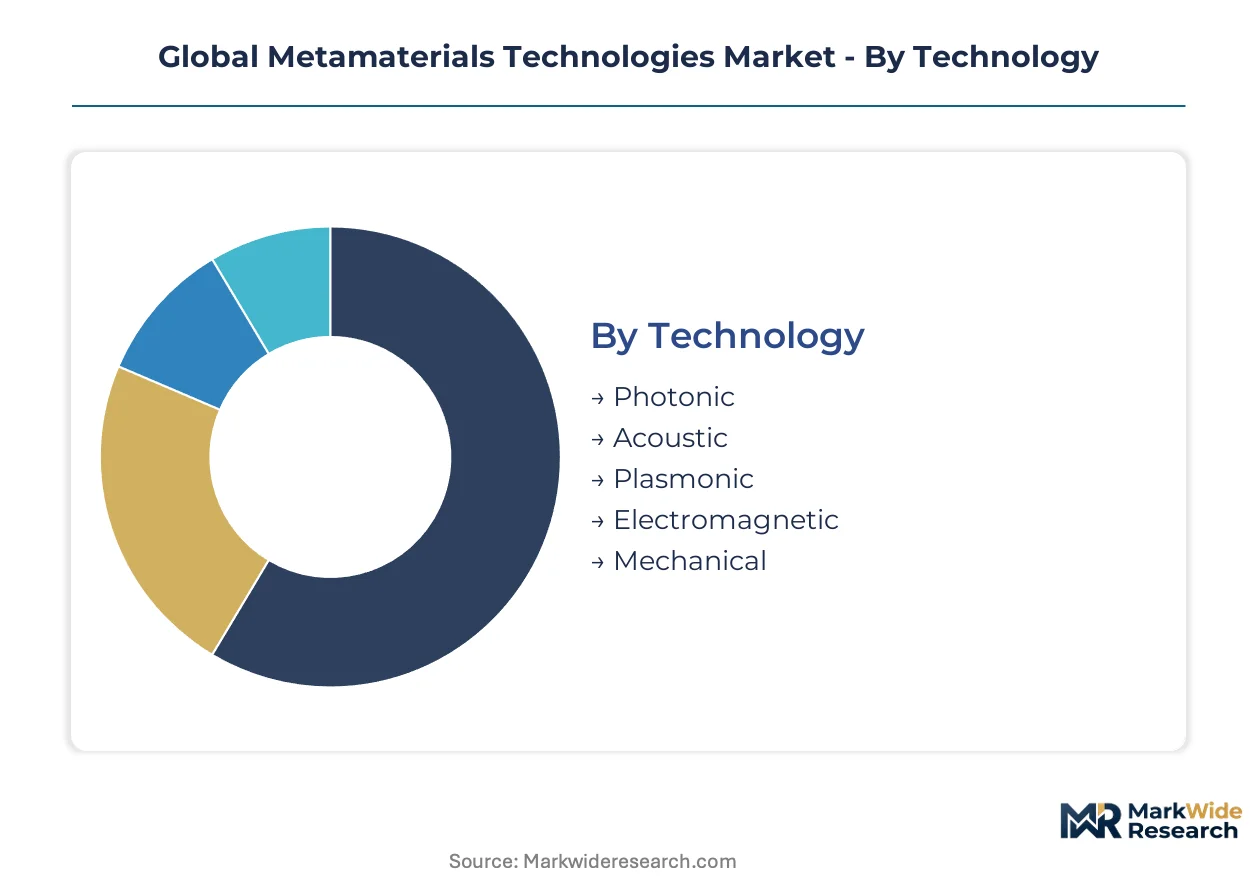
Metamaterials technologies fragment across multiple technical and commercial dimensions. Supply-side specialization in fabrication equipment and lithography talent concentrates competitive advantage in specific segment combinations. Procurement patterns from defense and telecommunications end users reshape which technology-product pairings command premium positioning.
Technology:
Supply concentration for electromagnetic simulation software and nanofabrication equipment favors certain technology branches over others.
- Electromagnetic:Composites with subwavelength metallic resonators and dielectric substrates manipulating microwave through terahertz frequencies. Defense procurement of radar-absorbing surfaces concentrates demand in NATO-aligned military programs, with solid-state cooling requirements under EU F-Gas Regulation accelerating design wins.
- Photonic:Structures engineered for optical wavelength manipulation through negative refractive index or tailored permittivity. Germany's photonics cluster around Jena and Karlsruhe anchors fabrication capacity, pulling lithography talent from competing technology branches.
- Acoustic:Periodic structures controlling sound wave propagation via bandgap engineering or negative bulk modulus.
- Plasmonic:Metal-dielectric interfaces exploiting surface plasmon polaritons for sub-diffraction-limited light confinement.
- Mechanatic:Architected materials with negative Poisson's ratio or programmable mechanical responses.
Today's leader: Electromagnetic. Tomorrow's challenger: Photonic.
Application:
Cost tier differentiation separates defense-qualified systems from commercial volume applications.
- Radar Systems:Cognitive architectures with microsecond reconfiguration capabilities. Software-defined metamaterial apertures absorb contract awards from conventional phased-array suppliers in North American defense programs.
- Wireless Communication:Reconfigurable intelligent surfaces for 5G base station deployments. Carrier capital allocation shifts from traditional antenna vendors toward programmable metasurface integrators.
- Antennas:Flat-panel maritime and aerospace terminals reducing vessel fuel consumption through drag elimination.
- Imaging Devices:Metamaterial-enabled lenses and super-resolution systems for medical and industrial inspection.
- Sensors:Subwavelength detection architectures for chemical, biological, and environmental monitoring.
Defense radar commands margin premiums. Telecommunications infrastructure offers volume scaling.
Product Type:
Volume concentration favors manufacturing processes compatible with semiconductor foundry economics.
- Tunable Metamaterials:Architectures with embedded varactor diodes, MEMS switches, or liquid crystal substrates enabling real-time electromagnetic response adjustment. Active tuning mechanisms displace passive designs across defense and telecommunications, compressing product lifecycles.
- Composite Metamaterials:Multi-phase structures combining metallic inclusions with polymer or ceramic matrices. Automotive OEM qualification programs for 77-81 GHz radar substrates concentrate demand from German and Japanese manufacturers.
- Resonant Metamaterials:Split-ring resonator and complementary structures operating at specific frequencies.
- Transmission Line Metamaterials:Periodic transmission line structures with engineered dispersion characteristics.
- Chiral Metamaterials:Asymmetric structures exhibiting optical activity and circular dichroism.
Tunable architectures gain share fastest. Fixed-frequency resonant structures face displacement.
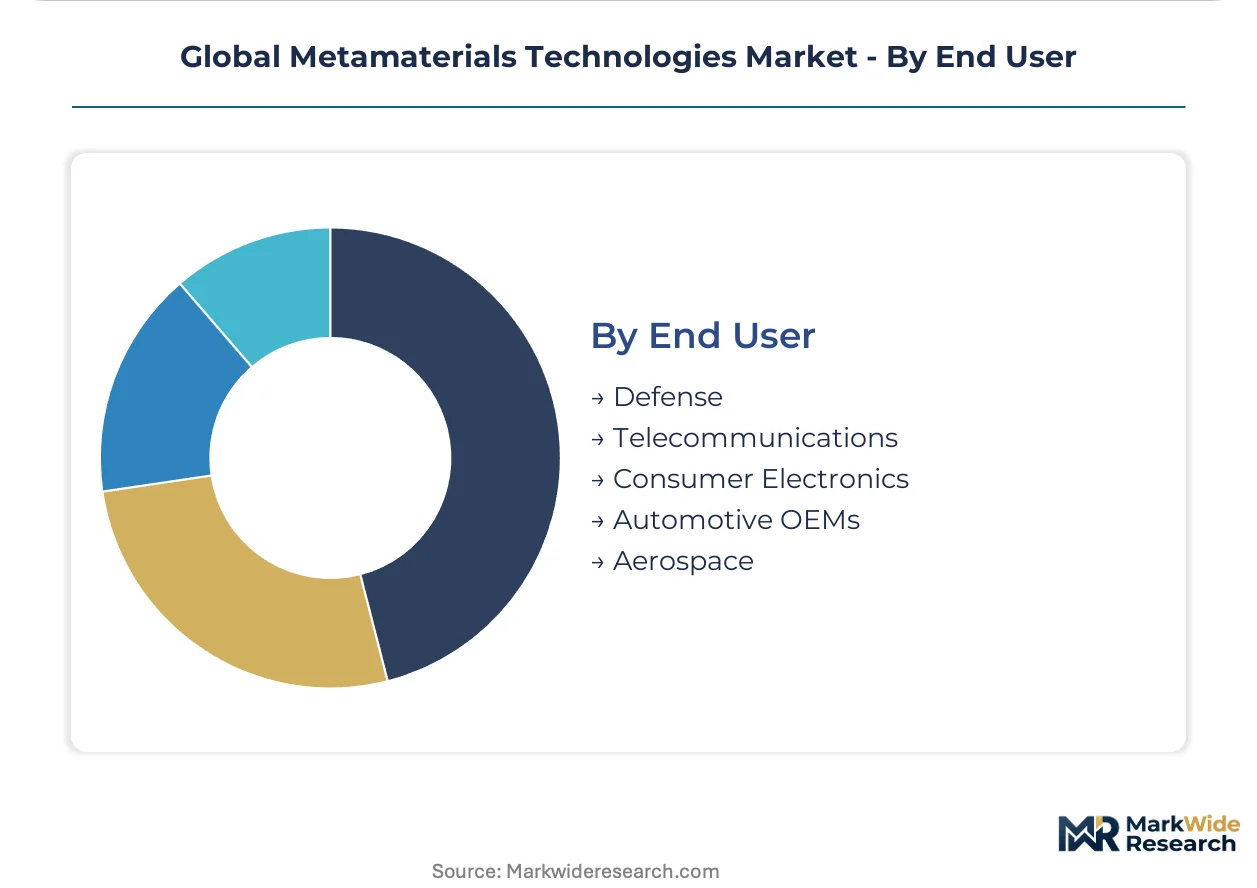
End User:
Margin structure varies sharply across customer types, with certification requirements creating tiered entry barriers.
- Defense:Radar-absorbent materials and cognitive aperture systems. Dual-use export controls under US ITAR and EU regulations delay cross-border transfers, concentrating supplier relationships with cleared domestic fabricators.
- Telecommunications:5G infrastructure and satellite terminal deployments. India's defense modernization programs under Make in India framework open lithography equipment supply opportunities.
- Automotive OEMs:77-81 GHz metamaterial antennas for adaptive cruise control and autonomous perception stacks.
- Aerospace:FAA airworthiness qualification requirements extend development cycles for commercial aviation antenna systems.
- Consumer Electronics:Miniaturized antennas and thermal management components for mobile devices.
Defense commands deepest margins. Automotive OEMs represent steepest volume trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting metamaterial fabrication investment toward jurisdictions with streamlined electromagnetic equipment certification and lower dual-use compliance burdens. Germany's F-Gas Regulation deadlines and India's Make in India defense procurement incentives are pulling capital away from US ITAR-constrained development cycles.
United States
The FAA and FCC jointly govern airspace access and spectrum allocation for metamaterial antenna deployments in commercial aviation and 5G infrastructure. ITAR export controls concentrate cleared supplier relationships with domestic fabricators for defense-adjacent radar-absorbent materials. Boston and Seattle anchor electromagnetic simulation software development clusters serving North American defense contractors.
Germany
The EU F-Gas Regulation mandates solid-state thermal management solutions for high-power radar installations by 2027, accelerating metamaterial cooling system qualifications. CE marking and RoHS directives constrain material composition for electromagnetic compatibility certification. Jena and Karlsruhe concentrate photonics lithography talent and fabrication equipment for optical metamaterial production.
China
MIIT spectrum allocation rulings govern domestic 5G base station deployments using intelligent metasurfaces, with GB standards setting electromagnetic compatibility thresholds. Rare-earth element processing concentration for magnetic metamaterials exposes supply chain vulnerabilities for Western fabricators. Yangtze River Delta cities host metasurface foundry capacity serving telecommunications infrastructure rollouts.
India
Make in India defense modernization programs create entry points for lithography equipment suppliers supporting indigenous radar-absorbent material development. TRAI spectrum management frameworks shape 5G infrastructure deployment timelines for reconfigurable intelligent surfaces. Bengaluru and Hyderabad concentrate electromagnetic simulation expertise for subwavelength structure design serving domestic procurement.
Japan
METI industrial policy directs funding toward integrated photonic-metamaterial platforms for autonomous vehicle LiDAR perception systems. JIS standards govern automotive radar substrate qualifications for 77-81 GHz adaptive cruise control applications. Nagoya and Osaka anchor automotive OEM supplier development for metamaterial antenna integration.
Global Metamaterials Technologies Market Competitive Landscape
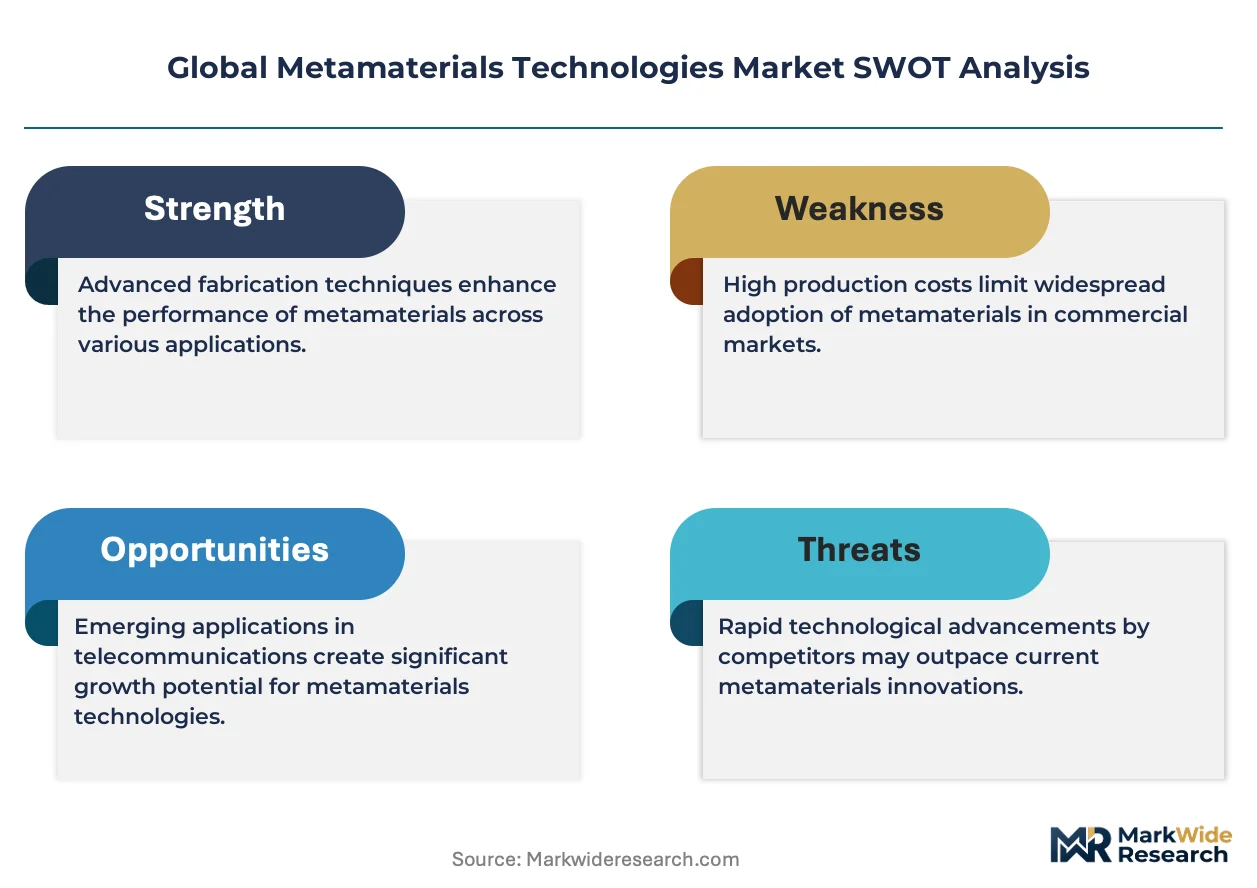
Established producers occupy the standard tier; emerging entrants pursue software-defined architectures and active tuning mechanisms. The vendor base stratifies across defense-cleared fabricators, telecommunications infrastructure integrators, and automotive-qualified substrate suppliers. Three archetypes dominate: vertically integrated antenna terminal providers, lithography equipment specialists, and reconfigurable intelligent surface deployers. Competitive moves concentrate on strategic partnerships with defense integrators and capacity expansion near Germany's photonics clusters.
Among North American defense-cleared fabricators, Kymeta Corporation and Echodyne Corp. exemplify the vertically integrated terminal provider archetype. Kymeta occupies a position serving maritime and aerospace flat-panel antenna channels, while Echodyne represents software-defined radar aperture integration. PIVOTAL COMMWARE anchors the telecommunications infrastructure tier, situating within 5G base station reconfigurable intelligent surface deployment. These three entities collectively illustrate competitive positioning across defense, satellite communications, and carrier infrastructure vectors without overlapping segment concentration.
| Leading Market Players |
|---|
| Kymeta Corporation |
| Echodyne Corp. |
| PIVOTAL COMMWARE |
| Lumotive |
| Meta Materials Inc. |
| Metamaterial Technologies Inc. |
| TeraView Limited |
| JEM Engineering LLC |
| Multiwave Technologies AG |
| Others |
Supply & Pricing Matrix
Rare-earth oxide price indices cascade through metamaterial fabrication tiers, compressing margins for Western electromagnetic substrate producers while amplifying pricing power for vertically integrated Chinese magnetic metamaterial suppliers serving defense-cleared NATO procurement channels.
Pricing Analysis
Direct-to-OEM discounts dominate volume transactions for automotive radar substrates, while distributor markups persist in defense-cleared specialty batches. Three-tier pricing structure across ITAR-compliant, CE-marked, and uncertified economy levels separates margin pools. Cost compression in standard-grade electromagnetic resonators is intensifying because Chinese foundry capacity expansion feeds spot-market neodymium pricing volatility. Tier 1 automotive OEMs exhibit highest price sensitivity, whereas NATO defense integrators accept premium positioning for cleared domestic fabrication.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale telecommunications demand for reconfigurable intelligent surfaces, while defense-cleared distributors manage ITAR-constrained radar-absorbent material flows. Raw material supply concentrates in China for rare-earth processing, Germany for photonics lithography equipment, and the United States for electromagnetic simulation software. Fabrication draws from metallic resonator blanks, dielectric substrate wafers, and varactor diode arrays. Single-source vulnerability in Chinese rare-earth oxide refining exposes Western metamaterial producers to export restriction shocks. Distribution runs through semiconductor foundry partnerships for tunable architectures and specialized job shops for defense-qualified composites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metamaterials technologies function as a stable compounder, with defense procurement cycles and telecommunications infrastructure refresh rates providing predictable demand baselines that smooth volatility across end-user segments.
For Market Incumbents: Lock in long-term rare-earth supply agreements before Chinese export license tightening accelerates. Secure lithography equipment slots at Jena and Karlsruhe clusters ahead of EU F-Gas Regulation compliance deadlines. Vertical integration into electromagnetic simulation software development defends against software-defined radar aperture displacement by Echodyne-type entrants.
For New Entrants and Emerging Players: The gap between ITAR-premium defense pricing and uncertified economy-tier commercial substrates offers entry space for mid-market automotive radar qualification programs. German and Japanese OEM 77-81 GHz adaptive cruise control specifications represent the most penetrable volume vector. A software-tunable metamaterial architecture with embedded firmware capabilities provides differentiation against fixed-frequency incumbent suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where electromagnetic simulation talent scarcity constrains foundry capacity expansion ahead of 5G base station deployment timelines. Five-to-ten year viability favors vertically integrated antenna terminal providers with satellite maritime channels and defense-cleared fabrication. The signal to monitor is FAA airworthiness qualification timeline compression for commercial aviation metamaterial antenna systems, which would unlock carrier fleet retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Processing | Captive neodymium supply secures Western electromagnetic metamaterial production against Chinese export controls. |
| Software-Defined Aperture Development | Active tuning capabilities displace passive designs in North American cognitive radar procurement programs. |
| Photonics-Metamaterial Platform Convergence | Integrated LiDAR architectures capture design wins in Japanese autonomous vehicle perception stacks. |
| CE Marking Acceleration for F-Gas Compliance | German and French defense integrators require solid-state cooling qualification before 2027 regulatory deadlines. |
| Make in India Lithography Partnership | Indigenous radar-absorbent material programs create equipment supply opportunities in Bengaluru and Hyderabad clusters. |
Research Methodology
Direct dialogue with electromagnetic simulation software developers, defense procurement officers at NATO-aligned integrators, telecommunications infrastructure engineers, and rare-earth processing specialists grounded qualitative findings. Secondary validation drew from FCC spectrum allocation rulings, ECHA F-Gas Regulation documentation, MIIT 5G deployment standards, and SEC filings of metamaterial antenna terminal providers. Bottom-up segment sizing triangulated against top-down defense budget and telecommunications capex aggregates.
Market value and volume trajectories across the analysis window emerged from segment-level modeling of technology-product-end user combinations. The framework incorporated electromagnetic versus photonic versus acoustic technology branches, tunable versus fixed-frequency product architectures, and defense versus automotive OEM versus telecommunications end-user demand pools. CAGRs derived from historical procurement cycle analysis and infrastructure deployment pipeline assessment, with rare-earth price elasticity and certification timeline assumptions as key inputs.
Caveats apply where Chinese rare-earth export license restrictions, FAA airworthiness qualification delays, or EU F-Gas Regulation enforcement intensity could materially shift the outlook. Forecasts embed assumptions regarding NATO defense spending continuity and 5G base station deployment pacing. Periodic stress-testing of base assumptions against regulatory filing updates and procurement announcement flows is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market