
 Electric Wall Heaters Market | 2026-2036
Electric Wall Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Wall Heaters Market Analytics
The capability gap between vertically integrated manufacturers and assembly-only competitors is collapsing as component costs equalize and thermal engineering talent disperses. Stiebel Eltron leverages its in-house heat pump and electric heating R&D to dominate European specification channels. Cadet anchors North American residential demand through deep distributor relationships and standardized product platforms. King Electric competes in commercial and industrial niches with higher-wattage, heavy-duty construction formats.
Electric wall heaters are self-contained heating appliances designed for permanent wall installation, typically employing resistive heating elements rated between 500 and 4,000 watts with integrated thermal cutouts and convection or radiant heat distribution methods. These units serve primary or supplemental space heating in residential, commercial, and institutional buildings where central HVAC extension proves impractical or cost-prohibitive. The product type dimension shows fan-forced configurations capturing specification share in commercial retrofit applications while infrared panels claim premium positioning in architectural residential projects. Smart and Wi-Fi enabled control types are experiencing the fastest trajectory as utility demand-response programs and consumer automation preferences reshape replacement cycles.
The US Department of Energy appliance efficiency standards and the EPA ENERGY STAR certification program establish minimum performance thresholds that filter out low-efficiency imports and reward manufacturers investing in ceramic element and advanced thermostat technologies. European regulators including Ecodesign requirements under the EU Green Deal and national building codes in France and the Netherlands mandate efficiency labeling and phase out standalone inefficient electric heating in favor of smarter, connected alternatives. Stakeholders must monitor how grid decarbonization timelines and time-of-use electricity rate structures alter the operating cost calculus that currently disadvantages electric resistance heating against heat pump alternatives.
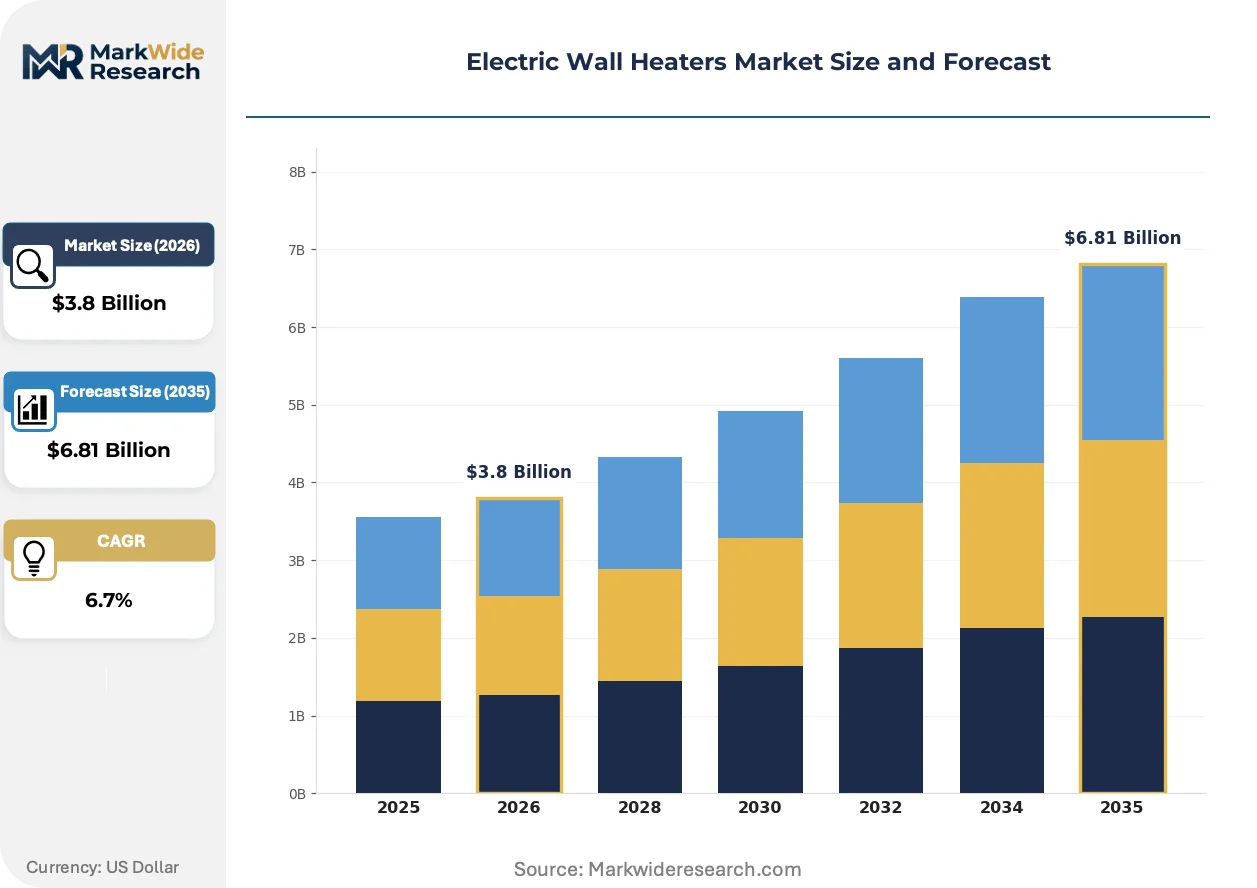
Market Dynamics
The electric wall heaters market pivots on building electrification mandates that are systematically decommissioning fossil-fuel heating infrastructure across residential and commercial building stock, forcing specification channels to prioritize connected, high-efficiency electric alternatives.
Growth Catalysts
- Gas boiler phase-outs:United Kingdom electrification mandates redirect consumer spending toward electric heating solutions as natural gas connections face prohibition in new construction.
- California Title 24:Tightening building energy codes force efficiency upgrades in older housing stock, accelerating replacement cycles for outdated resistance heating.
- Smart thermostat integration:Wi-Fi enabled control types reshape replacement cycles as utility demand-response programs incentivize connected heating infrastructure.
Market Restraints
- Electricity rate volatility:Time-of-use pricing structures disadvantage electric resistance heating against heat pump alternatives in operating cost calculus.
- Component supply concentration:Ceramic element and advanced thermostat technologies depend on concentrated Asian manufacturing clusters for semiconductor controls.
- Efficiency ceiling:Resistive heating elements face fundamental thermodynamic limits near 100% conversion efficiency, capping performance differentiation.
Strategic Opportunities
- German Ecodesign requirements:EU Green Deal mandates phase out standalone inefficient electric heating, creating specification pull for smarter, connected alternatives.
- Commercial retrofit applications:Fan-forced configurations capture specification share as building owners replace aging central HVAC extensions in office and retail spaces.
- Infrared panel premium positioning:Architectural residential projects in France and the Netherlands adopt radiant heat distribution for aesthetic and comfort advantages.
Industry Challenges
- Thermal engineering talent dispersal:The capability gap between vertically integrated manufacturers and assembly-only competitors collapses as specialized expertise diffuses across the supplier base.
- Multi-certification complexity:EPA ENERGY STAR and US Department of Energy appliance efficiency standards require parallel compliance pathways that extend product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Wall Heaters Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baseboard, Panel, Infrared, Fan-Forced Energy Source: Electric, Solar, Hybrid, Others Control Type: Manual, Thermostat-Controlled, Smart, Wi-Fi Enabled Installation Type: Wall-Mounted, Portable, Hardwired, Plug-In |
| Companies Covered | Stiebel Eltron, Dimplex, King Electric, Marley Engineered Products, Cadet, TPI Corporation, Broan-NuTone, Comfort Zone, Fahrenheat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Wall Heaters Market Evolving Landscape
Product development trajectories concentrate on connectivity integration and thermal efficiency advancement as regulatory thresholds tighten and building automation systems demand interoperable heating endpoints.
Ceramic heating elements with positive temperature coefficient properties are supplanting traditional nichrome wire configurations in specification-grade units. Commercial retrofit contractors specify these elements for faster thermal response and reduced surface temperatures. The technology is supplanting legacy metal-sheathed designs in premium residential and institutional projects where safety and efficiency ratings determine bid outcomes.
France and the Netherlands enforce national building codes that mandate efficiency labeling and connected control compatibility for new electric heating installations. These regulations compress the addressable market for basic resistance units without smart functionality. Specification channels in both countries now require modulating controls and occupancy sensing as baseline features.
Facility managers increasingly bundle heating system procurement with energy service contracts that guarantee thermal output per square meter. This purchasing model displaces traditional capital expenditure cycles in commercial and institutional verticals. The Netherlands demonstrates the most advanced adoption, where building operators prioritize outcome-based agreements over equipment ownership.
Electric Wall Heaters Market Segmentation
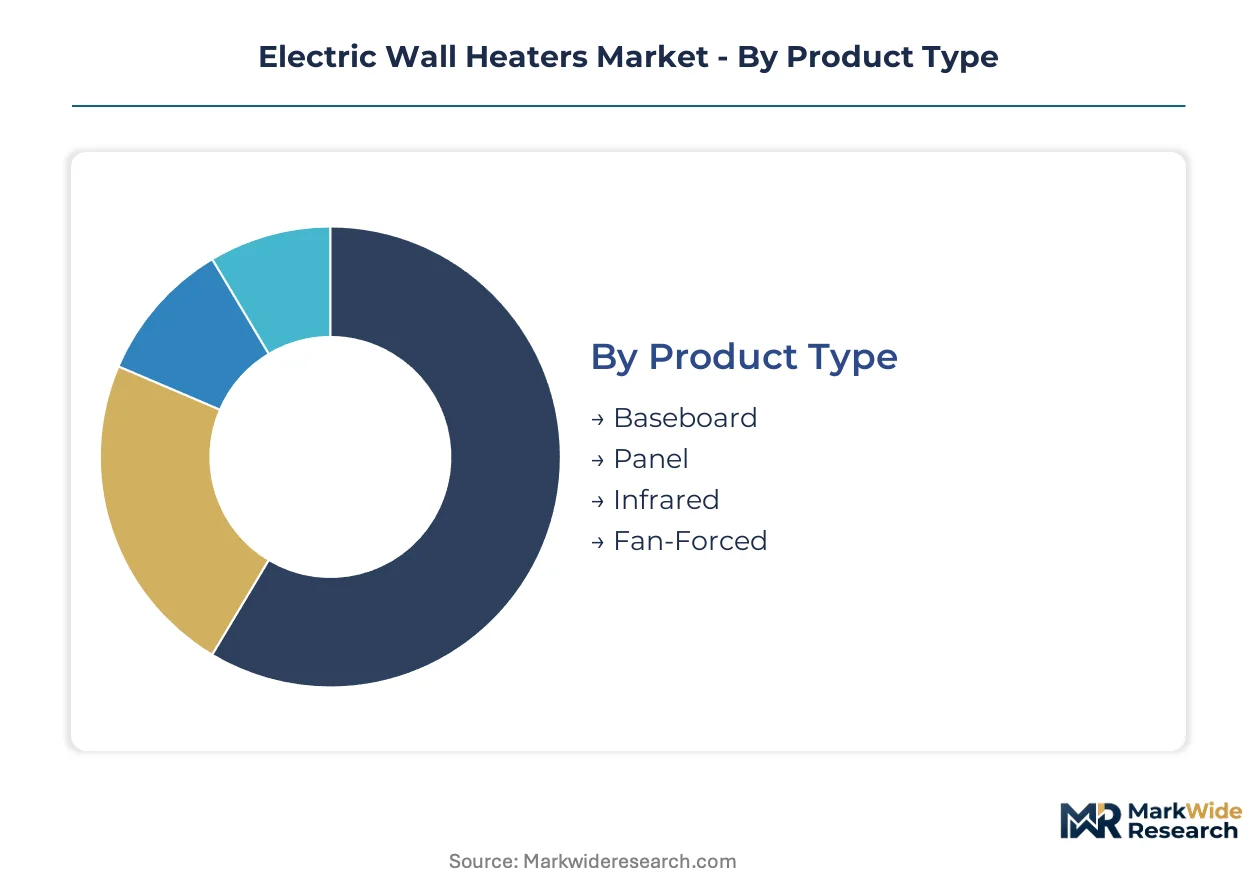
Segmentation in electric wall heaters determines specification pathways and procurement criteria across residential retrofit and commercial construction channels. Product architecture, control sophistication, and installation constraints collectively shape bid outcomes and replacement cycle timing.
Product Type:
Fan-forced configurations face the strongest substitution pressure from heat pump mini-splits in commercial applications where efficiency mandates tighten.
- Baseboard:Resistive aluminum or steel-housed elements with convection-driven heat distribution. Demand concentrates in North American residential retrofits where existing 240V circuits reduce installation costs.
- Panel:Flat-profile ceramic or mica elements with surface temperatures below 85°C for safety certification. Architectural specifications in France and the Netherlands favor these units for aesthetic integration in multifamily housing.
- Infrared:Radiant heat distribution through quartz or carbon fiber elements. Germany's Ecodesign requirements under the EU Green Deal accelerate specification for zonal heating in historic building renovations.
- Fan-Forced:Integrated blowers with nichrome or ceramic heating elements rated 1,500–4,000 watts. Office and retail retrofits in California specify these for rapid thermal response under Title 24 compliance deadlines.
Baseboard retains volume leadership; fan-forced configurations hold the steepest expansion curve.
Energy Source:
Cost tier differentiation separates premium grid-integrated systems from economy standalone units.
- Electric:Standard resistive elements drawing grid power at 120V or 240V. Residential replacements in the United Kingdom dominate as gas boiler phase-outs redirect consumer spending toward electrified heating.
- Solar:DC-coupled elements with battery storage integration for off-grid or net-zero structures. Off-grid residential construction in rural California and Arizona specifications drive niche demand.
- Hybrid:Dual-source systems combining resistive backup with heat pump primaries. Netherlands building codes mandate connected control compatibility for these configurations in new construction.
- Others:Biomass-pellet or thermal storage variants with ceramic core heat retention. District heating interconnection projects in Denmark and Sweden specify these for load-balancing applications.
Electric dominates unit volume; hybrid systems gain share fastest in new construction specifications.
Control Type:
Application maturity separates legacy manual installations from connected infrastructure demanded by utility demand-response programs.
- Manual:Rotary or toggle switches with bimetallic thermal cutouts. Economy residential replacements in aging housing stock maintain baseline demand where smart infrastructure is absent.
- Thermostat-Controlled:Integrated or remote temperature sensors with ±1°C accuracy. Commercial office specifications in Germany require these for Ecodesign compliance in building energy certification.
- Smart:Occupancy-sensing and learning algorithms with BACnet or Modbus integration. Facility management contracts in the Netherlands prioritize these for outcome-based thermal performance guarantees.
- Wi-Fi Enabled:Cloud-connected controls with utility API integration for time-of-use rate optimization. California's demand-response incentives accelerate replacement cycles toward these configurations.
Manual controls retain installed base dominance; Wi-Fi enabled systems climb the fastest in replacement specifications.
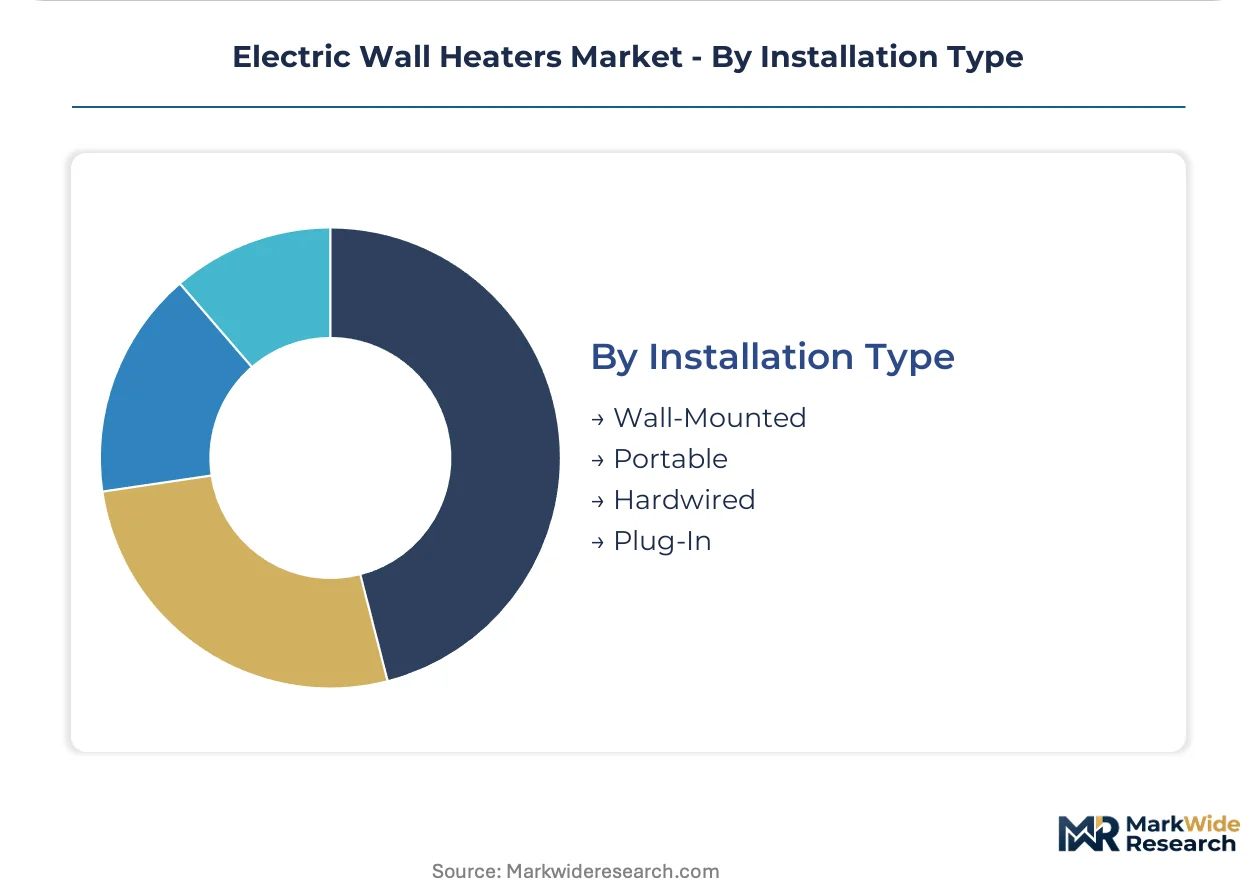
Installation Type:
Customer type segmentation separates permanent infrastructure from temporary or seasonal demand.
- Wall-Mounted:Permanent bracket or recessed cavity installation with hardwired electrical connection. Residential retrofits across the United Kingdom and California constitute primary demand as electrification mandates eliminate gas alternatives.
- Portable:Freestanding units with caster mobility and plug-in convenience. Supplementary heating in older European housing stock without central HVAC extensions maintains steady replacement demand.
- Hardwired:Direct electrical connection to dedicated circuits with junction box termination. Commercial specifications in France require these for safety compliance in institutional buildings.
- Plug-In:Standard outlet compatibility with 120V or 230V configurations. Seasonal residential demand in North American rental properties favors these for cost-minimized temporary heating.
Wall-mounted retains specification leadership; hardwired systems expand most quickly in commercial compliance-driven replacements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Chinese manufacturers dominate cross-border trade, while import dependency concentrates in markets lacking domestic thermal engineering capacity. Currency fluctuations and energy cost differentials are reshaping procurement patterns across high-income housing markets.
United States
Residential retrofit demand concentrates in California and the Northeast where aging housing stock requires electrification upgrades. The EPA ENERGY STAR certification program and DOE appliance efficiency standards filter low-efficiency imports while rewarding advanced thermostat technologies. Los Angeles and San Francisco metropolitan areas drive specification volume for Title 24 compliance deadlines.
Germany
Ecodesign requirements under the EU Green Deal accelerate replacement of standalone resistance heating in multifamily housing. The country's national building energy regulator mandates efficiency labeling and connected control compatibility for new installations. Stuttgart and Munich anchor specification activity where historic building renovations prioritize zonal electric solutions.
United Kingdom
Gas boiler phase-out mandates redirect consumer spending toward electrified heating in residential construction and retrofit channels. National electrification policy prohibits natural gas connections in new buildings from 2025 onward. London and the Southeast England corridor concentrate distributor networks and installation contractor capacity.
France
National building codes enforce efficiency labeling and connected control compatibility for electric heating in new construction. The country's construction regulator mandates modulating controls and occupancy sensing as baseline specification features. Lyon and Marseille drive demand for infrared panel installations in architectural residential projects.
Netherlands
Building operators prioritize outcome-based thermal performance agreements over equipment ownership in commercial and institutional verticals. National building codes mandate connected control compatibility for hybrid heating configurations in new construction. Amsterdam and Rotterdam concentrate facility management procurement and energy service contract structuring.
Electric Wall Heaters Market Competitive Landscape
Concentration sits with vertically integrated manufacturers possessing in-house thermal engineering capabilities and captive component supply. Assembly-only competitors face margin compression as ceramic element and semiconductor control costs equalize across sourcing bases. Three archetypes dominate: European specification-grade specialists, North American distributor-anchored volume players, and Asian component-integrated cost optimizers. Competitive moves center on backward integration into ceramic element production and strategic partnerships with building automation system vendors.
Within the European specification-grade tier, Stiebel Eltron and Dimplex exemplify vertically integrated positioning through in-house R&D infrastructure. Cadet anchors North American residential demand through standardized product platforms. King Electric occupies a position in commercial and industrial niches requiring higher-wattage formats.
| Leading Market Players |
|---|
| Stiebel Eltron |
| Dimplex |
| King Electric |
| Marley Engineered Products |
| Cadet |
| TPI Corporation |
| Broan-NuTone |
| Comfort Zone |
| Fahrenheat |
| Others |
Value Network & Pricing Analysis
Ceramic heating elements replacing traditional nichrome wire configurations simultaneously shift procurement geography toward East Asian semiconductor manufacturing clusters and compress pricing power for legacy metal-sheathed component suppliers. This substitution dynamic redistributes value capture from raw material processors to control system integrators as thermal engineering specifications tighten across European and North American regulatory regimes.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the electric wall heaters market. Price differentiation separates ENERGY STAR-certified smart configurations with BACnet integration from basic manual units without connectivity, with volume scale and after-sales service bundling as secondary drivers. Cost compression in economy tiers intensifies because Asian assembly-only competitors equalize component sourcing costs, eroding margin buffers for distributors. Residential retrofit contractors in California and the United Kingdom exhibit highest price sensitivity due to project-based procurement, while facility management firms in the Netherlands prioritize outcome-based thermal guarantees over unit economics.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates inbound logistics costs for semiconductor controls and ceramic substrates sourced from Chinese and South Korean manufacturing hubs. Component supply draws from concentrated clusters in China for ceramic elements, Taiwan for microcontroller chips, and Germany for precision thermostats, creating single-source vulnerability for advanced thermostat technologies. Distribution runs through electrical wholesale networks anchored by regional distributors in North America and specification channels in Europe. Tariff exposure on Chinese-sourced heating elements compounds logistics chokepoint risks as US customs enforcement tightens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pump mini-splits pose an existential substitution threat that electric wall heater incumbents must navigate through defensive capability building rather than price competition alone.
For Market Incumbents: Shield specification-grade positioning by deepening in-house production of ceramic heating elements and capturing captive supply of semiconductor controls. Backward integration into thermal sensor manufacturing defends margin structure against assembly-only competitors while building defensible IP around Ecodesign-compliant product architectures. Prioritize ENERGY STAR certification maintenance and EPA appliance efficiency standard compliance as non-negotiable table stakes. For New Entrants and Emerging Players: Service-layer gaps in outcome-based thermal performance contracting create white-space opportunity for new entrants targeting Dutch and German facility management procurement channels. Energy service contract structuring represents the most penetrable segment as building operators displace capital expenditure cycles. Target commercial retrofit applications in California Title 24 compliance deadlines with fan-forced configurations bundled with installation and maintenance services. For Investors and Strategic Acquirers: EU Green Deal Ecodesign requirements reshape the acquisition landscape by compressing valuations for standalone resistance heating manufacturers lacking smart functionality. Long-term viability favors vertically integrated specialists with in-house R&D infrastructure and captive component supply over assembly-only competitors. The signal to monitor is heat pump subsidy expansion timelines in Germany and the United Kingdom as inflection indicators for electric resistance heating addressable market contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Element Production | In-house manufacturing of PTC ceramic components secures supply continuity for Ecodesign-compliant specifications. |
| Smart Control Platform Integration | BACnet and Modbus interoperability opens specification channels in Dutch facility management procurement. |
| Energy Service Contract Structuring | Outcome-based thermal guarantees displace capital expenditure cycles in commercial and institutional verticals. |
| Multi-Certification Compliance Investment | Parallel EPA ENERGY STAR and DOE efficiency pathways filter low-efficiency imports from Asian competitors. |
| Specification Channel Partnership | Deep distributor relationships in California and the United Kingdom accelerate replacement cycle capture. |
Research Methodology
Operator-level perspectives from thermal engineering directors, electrical wholesale procurement managers, facility management contract officers, and building automation system integrators anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation from DOE appliance efficiency filings, EPA ENERGY STAR certification databases, EU Ecodesign regulatory texts, and national building code repositories in Germany, France, and the Netherlands. Bottom-up unit shipment estimates triangulated against top-down construction spending data across residential retrofit and commercial verticals.
Sensitivity analysis tested forecast robustness across electricity rate volatility scenarios, heat pump substitution pace variations, and regulatory timeline acceleration cases. The analytical framework modeled volume and value outputs across product type, control sophistication, installation format, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from regression analysis against construction permit flows, electrification mandate implementation schedules, and utility demand-response program expansion trajectories.
Forecasts assume regulatory continuity in EPA appliance efficiency standards, EU Ecodesign requirements, and California Title 24 provisions; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as grid decarbonization timelines and time-of-use electricity rate structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Fiberglass Electrical Enclosure Market
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Smart Heater Market
Electrical Equipment
Europe Busbar Market