
 AI Edge Computing Market | 2026-2036
AI Edge Computing Market Size, Share, and Industry Trends Forecast 2026-2036
AI Edge Computing Market Analysis
Platform licensing revenue is rewriting how silicon vendors capture lifetime value from edge deployments. NVIDIA Corporation leverages its CUDA ecosystem to lock in developer loyalty across industrial automation workloads. Intel Corporation anchors its position through OpenVINO toolkit distribution and x86 architecture dominance in legacy infrastructure retrofits. Qualcomm Incorporated specializes in low-power inference accelerators for battery-constrained devices in transportation and retail endpoints.
AI edge computing deploys machine learning inference directly on local hardware nodes, processing data within 10 milliseconds of generation to eliminate cloud round-trip latency for time-critical decisions. The architecture combines tensor processing units, embedded neural accelerators, and optimized model compression to execute predictions without persistent connectivity. On-premises and hybrid deployment configurations now command the deepest margin pools as enterprises reject pure-cloud latency for factory-floor and clinical settings. Computer vision applications in industrial automation and autonomous vehicles represent the fastest-expanding technology-application intersection, while natural language processing at the edge remains nascent outside smart home consumer devices.
FDA scrutiny of AI-enabled medical devices at the point of care is tightening validation requirements for healthcare edge deployments. The EU AI Act's conformity assessment obligations for high-risk systems are forcing European vendors to redesign certification pipelines before market access. NHTSA guidelines for autonomous vehicle onboard decision systems are simultaneously shaping hardware redundancy standards in the transportation segment. Stakeholders must now decide whether to absorb compliance costs directly or push liability upstream through chipset supplier indemnification clauses.
Market Dynamics
Automotive manufacturers deploying autonomous vehicle fleets are accelerating procurement of edge inference hardware, compressing supplier lead times and reshaping silicon allocation priorities across industrial and transportation segments.
Growth Catalysts
- EU AI Act conformity obligations:High-risk system classification is mandating edge deployment for data sovereignty compliance, forcing European enterprises to localize AI processing.
- Smart factory edge networks:Germany's industrial corridor is concentrating demand as Siemens and Bosch anchor private 5G-enabled inference clusters for predictive maintenance.
- Tensor processing unit integration:Embedded neural accelerators are achieving sub-10 millisecond latency thresholds required for real-time autonomous vehicle decisioning.
Market Restraints
- Specialized silicon supply concentration:Advanced node fabrication for inference accelerators depends on Taiwan-based foundry capacity, creating geographic single-point vulnerability.
- EU AI Act certification pipeline redesign:European vendors face 12-18 month conformity assessment delays before market access, freezing product launch timelines.
- Legacy x86 infrastructure retrofit costs:Industrial automation sites require substantial hardware replacement to deploy optimized neural accelerators alongside existing control systems.
Strategic Opportunities
- Battery-constrained transportation endpoints:Low-power inference accelerators for electric vehicle cabin monitoring and fleet telematics remain underpenetrated in commercial trucking.
- India PLI scheme for electronics manufacturing:Production-linked incentives are attracting edge hardware assembly capacity for domestic smart city and agricultural drone deployments.
- Federated learning-5G convergence:Distributed model training across edge nodes without raw data transmission is opening healthcare and financial services applications previously blocked by privacy constraints.
Industry Challenges
- Embedded systems ML engineering talent scarcity:Shortage of specialists capable of optimizing model compression for resource-constrained devices is extending development cycles.
- FDA premarket submission timelines:AI-enabled medical device edge deployments face 18-24 month validation pathways for software-as-medical-device classification.
- Multi-vendor toolchain fragmentation:Incompatibility between NVIDIA CUDA, Intel OpenVINO, and Qualcomm neural processing SDKs complicates cross-platform deployment strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Edge Computing Market |
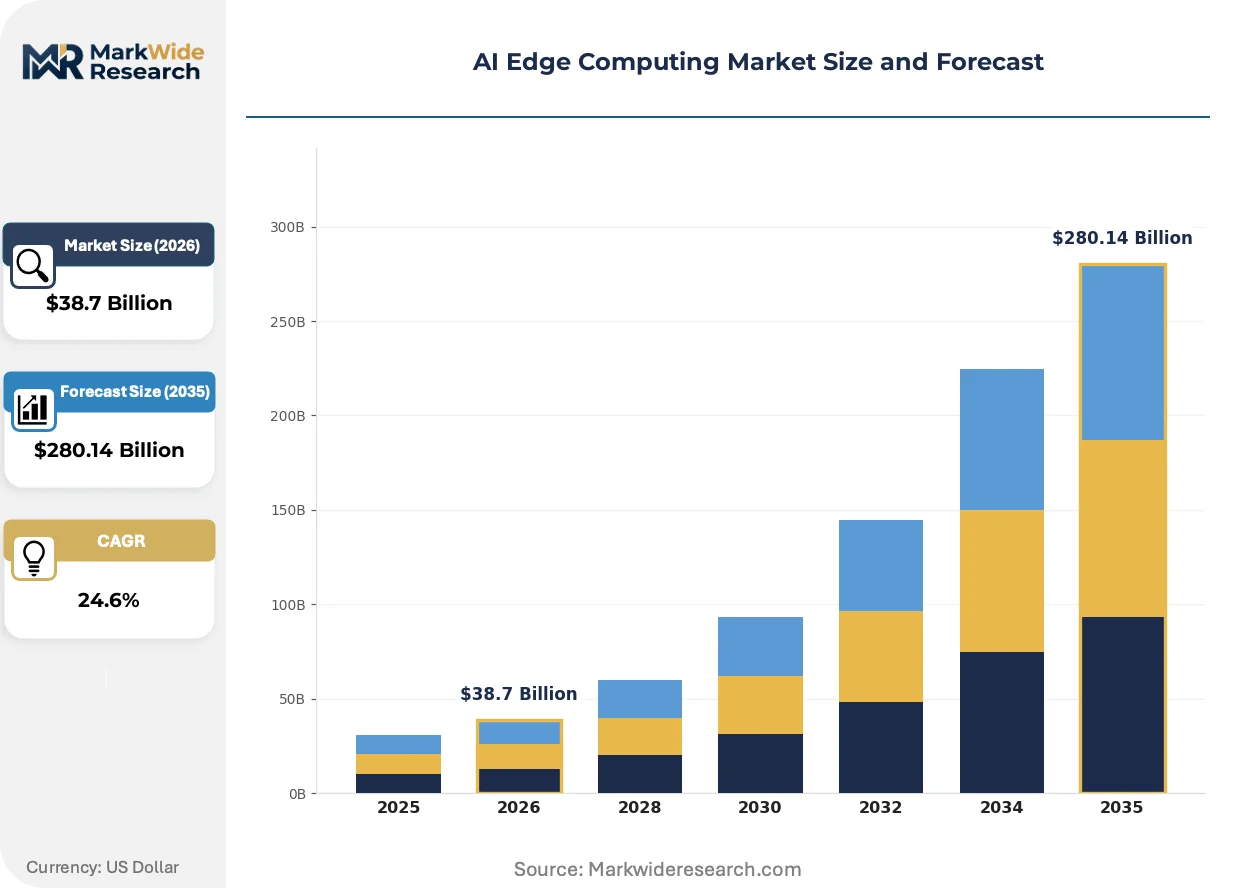
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Remote End User: Manufacturing, Healthcare, Retail, Transportation Technology: Machine Learning, Computer Vision, Natural Language Processing, Robotics Application: Smart Cities, Industrial Automation, Autonomous Vehicles, Smart Homes |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Qualcomm Incorporated, Apple Inc., Samsung Electronics Co., Ltd., Microsoft Corporation, Google, IBM, Amazon.com, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Edge Computing Market Emerging Trajectories
Software-defined edge infrastructure is virtualizing hardware abstraction layers, allowing workload portability across heterogeneous silicon while regulatory pressure on AI transparency accelerates explainable inference architectures.
Containerized edge orchestration platforms are virtualizing the traditional boundary between cloud and local processing. Automotive Tier 1 suppliers are adopting Kubernetes-based workload management for autonomous vehicle compute stacks. This virtualization is compressing the vendor lock-in advantage previously held by integrated silicon-software stacks.
The EU AI Act's risk-based classification system is mandating algorithmic transparency documentation for high-risk edge applications. Industrial automation vendors must now maintain model provenance records and decision audit trails. Medical device manufacturers face the steepest compliance burden, with point-of-care diagnostic systems requiring conformity assessment before European market entry.
Enterprise buyers are consolidating edge hardware procurement through systems integrators rather than direct silicon vendor relationships. Manufacturing conglomerates in Germany and Japan are outsourcing full-stack deployment to specialized edge infrastructure providers. This channel shift is most pronounced in pharmaceutical production lines, where validated environment requirements favor turnkey service contracts over component sourcing.
AI Edge Computing Market Segmentation
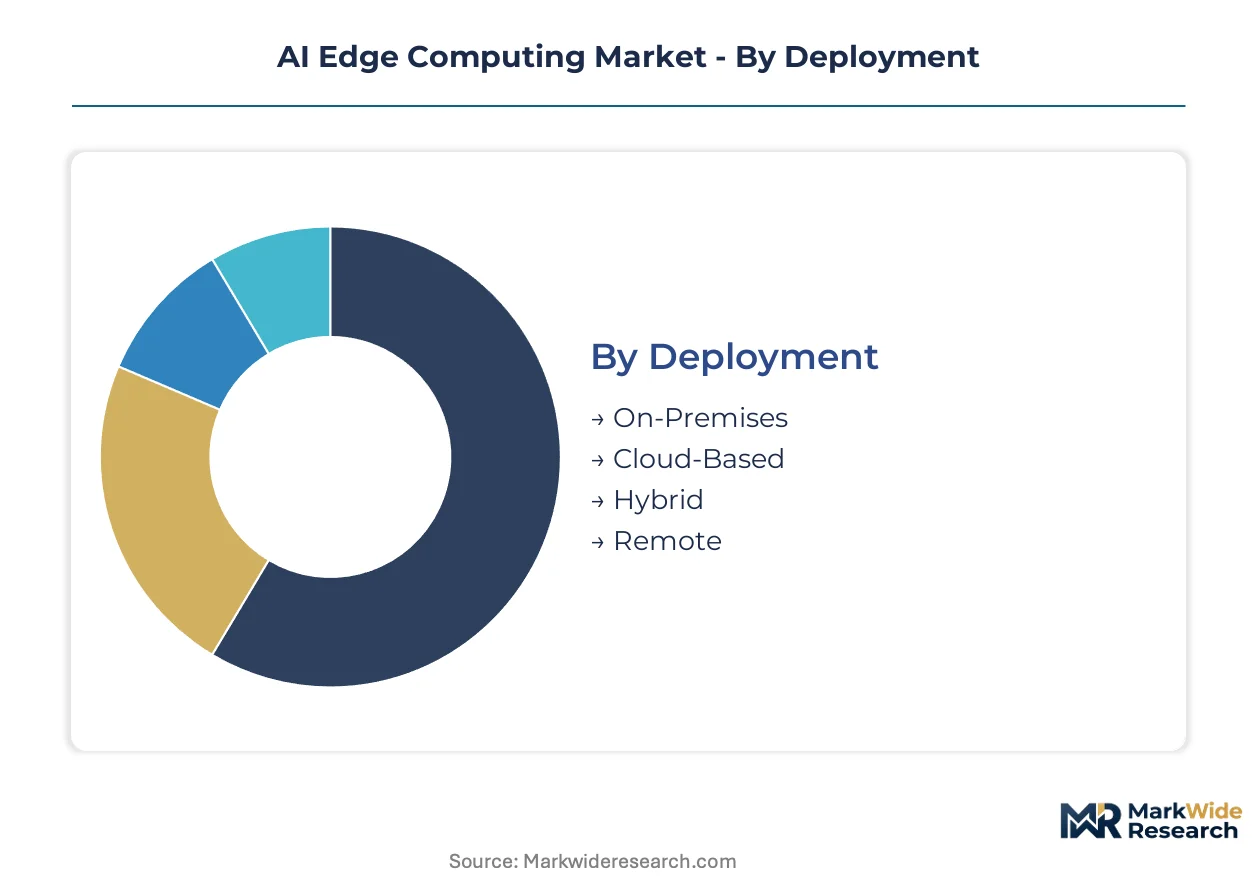
Edge computing architectures fragment across deployment topology, end-use vertical, enabling technology, and application domain. Each segmentation axis reveals distinct procurement patterns, latency requirements, and vendor competitive dynamics that determine margin capture and technology substitution risk.
Deployment:
Cycle times vary dramatically — on-premises hardware refreshes extend across 5-7 years while cloud-based orchestration layers update quarterly.
- On-Premises:Dedicated inference servers and embedded neural accelerators deployed within facility boundaries. Manufacturing conglomerates in Germany's industrial corridor favor this mode for predictive maintenance clusters to satisfy EU AI Act data sovereignty mandates.
- Hybrid:Workload-splitting architectures that route training to cloud infrastructure while retaining inference locally. Healthcare systems deploying FDA-validated diagnostic edge nodes use hybrid configurations to balance model update frequency against point-of-care latency requirements.
- Cloud-Based:Centralized processing with edge caching layers for latency-sensitive bursts. Retail chains use this for seasonal demand spikes in computer vision analytics.
- Remote:Disconnected or intermittently connected nodes operating on cached models. Agricultural drone fleets in India rely on remote deployment where cellular coverage remains patchy.
On-premises dominates installed base. Hybrid is where expansion concentrates.
End User:
Cost tiers separate capital-intensive industrial deployments from operational-expense-driven consumer-facing implementations.
- Manufacturing:Smart factory networks integrating tensor processing units for real-time quality inspection. Siemens and Bosch anchor Germany's demand concentration for private 5G-enabled inference clusters.
- Transportation:Autonomous vehicle fleets and electric vehicle cabin monitoring systems. NHTSA hardware redundancy guidelines shape procurement specifications for onboard decision systems.
- Healthcare:Point-of-care diagnostic devices and surgical robotics. FDA premarket submission timelines stretch 18-24 months for software-as-medical-device classification.
- Retail:Inventory management and customer analytics at battery-constrained endpoints. Low-power inference accelerators from Qualcomm dominate this cost-sensitive tier.
Manufacturing commands the deepest margin pools. Transportation is climbing the fastest.
Technology:
Maturity gradients separate production-hardened inference stacks from experimental deployments still seeking validation pathways.
- Computer Vision:Embedded neural accelerators executing object detection and segmentation with sub-10 millisecond latency. Industrial automation and autonomous vehicles represent the steepest expansion trajectory across all technology-application intersections.
- Machine Learning:Optimized model compression for resource-constrained devices. Federated learning-5G convergence is opening healthcare applications previously blocked by HIPAA privacy constraints.
- Natural Language Processing:Voice interfaces and real-time translation at the edge. Deployment remains nascent outside smart home consumer devices.
- Robotics:Motion planning and manipulation control with deterministic latency guarantees. Surgical and warehouse automation drive specification requirements.
Computer Vision dominates revenue concentration. Machine Learning is gaining share fastest.
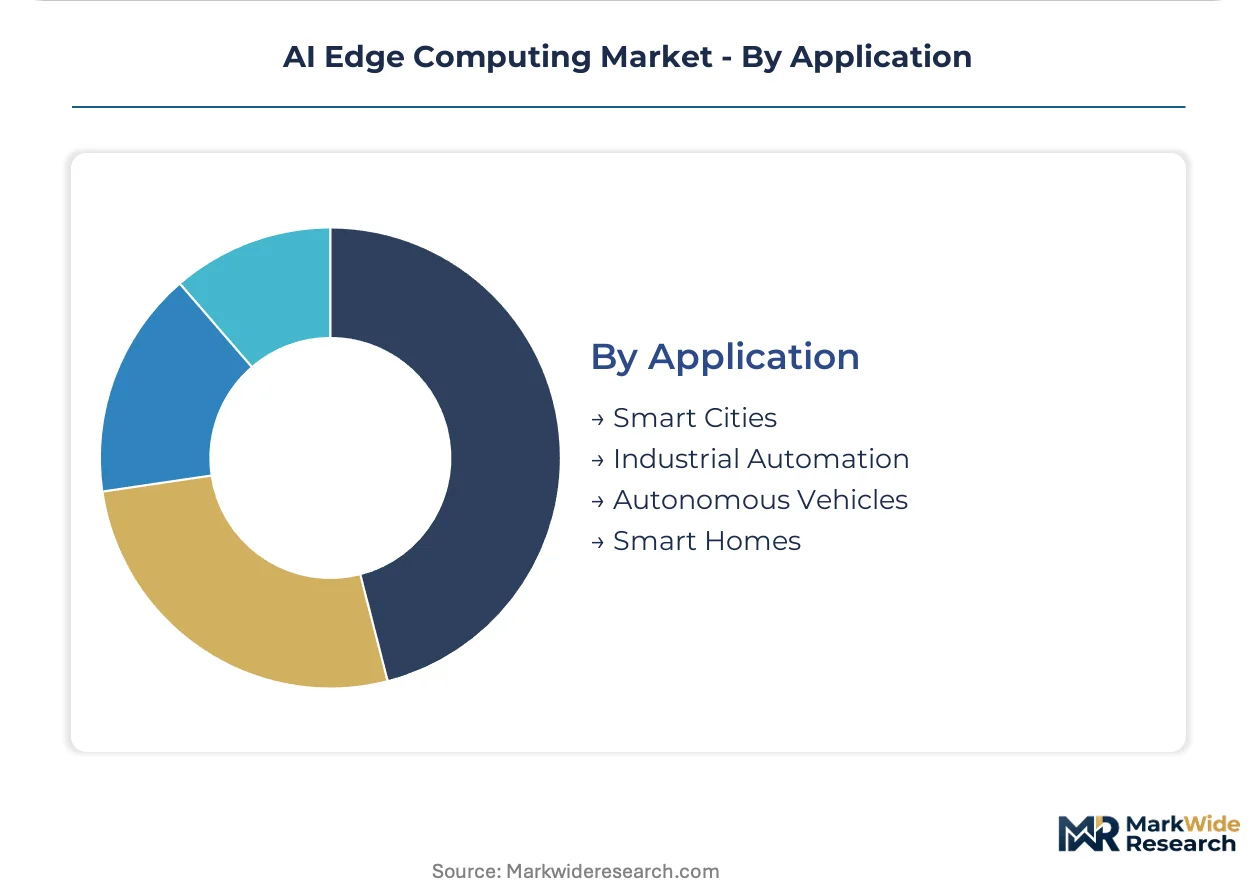
Application:
Volume scale separates mass-market consumer endpoints from specialized industrial systems with extended validation cycles.
- Industrial Automation:Predictive maintenance and quality control on factory floors. EU AI Act conformity obligations mandate edge deployment for high-risk system classification in European facilities.
- Autonomous Vehicles:Onboard decision systems with hardware redundancy for safety-critical functions. Automotive Tier 1 suppliers compress supplier lead times as fleet deployment accelerates.
- Smart Cities:Traffic management and public safety analytics. India's PLI scheme attracts assembly capacity for domestic smart city deployments.
- Smart Homes:Voice assistants and security systems with consumer-grade reliability thresholds. Lowest latency requirements enable broader silicon vendor participation.
Industrial Automation anchors procurement volume. Autonomous Vehicles is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany's industrial corridor demands deterministic latency for factory-floor robotics, while India's agricultural deployments prioritize intermittent-connectivity resilience over sub-10 millisecond response times.
United States
Autonomous vehicle fleet operators and healthcare systems anchor procurement volume. FDA premarket submission timelines stretch 18-24 months for software-as-medical-device edge classifications. Detroit's automotive cluster compresses supplier lead times as Tier 1 manufacturers accelerate hardware procurement for onboard decision systems.
Germany
Siemens and Bosch drive private 5G-enabled inference cluster deployment for predictive maintenance networks. EU AI Act conformity obligations mandate localized AI processing for high-risk industrial automation classifications. The Baden-Württemberg industrial corridor concentrates Europe's deepest smart factory edge infrastructure investment.
China
Smart city traffic management and manufacturing quality inspection absorb the majority of domestic tensor processing unit deployment. MIIT standards for embedded neural accelerators shape procurement specifications for industrial automation retrofits. The Yangtze River Delta anchors computer vision edge hardware production capacity.
India
Agricultural drone fleets and smart city deployments drive demand for battery-constrained remote inference nodes. PLI scheme production-linked incentives attract edge hardware assembly capacity for domestic consumption. Karnataka's Bangalore-Tumkur corridor concentrates software-defined edge infrastructure development.
Japan
Surgical robotics and warehouse automation specify deterministic latency guarantees for motion planning workloads. METI guidelines for AI-enabled industrial equipment shape safety certification requirements. The Chubu region around Nagoya anchors automotive Tier 1 supplier edge compute integration.
AI Edge Computing Market Vendor Landscape
Capability concentration sits with silicon vendors commanding proprietary developer ecosystems; scale advantage sits with cloud hyperscalers distributing orchestration layers across heterogeneous hardware. The market structures around three tiers: integrated silicon-software stack vendors, cloud-native platform providers, and specialized inference accelerator designers. Consolidation pressure runs highest where automotive procurement volumes compress supplier margins. Dominant competitive moves include strategic partnerships between Tier 1 automotive suppliers and silicon vendors, plus geographic expansion through India PLI scheme manufacturing partnerships.
Within the integrated stack tier, NVIDIA Corporation and Intel Corporation exemplify contrasting ecosystem strategies—CUDA developer lock-in versus x86 architecture retrofit compatibility. Qualcomm Incorporated occupies a position among low-power specialization vendors. These three entities anchor the competitive dynamics shaping procurement negotiations across transportation, industrial, and retail endpoint segments.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Qualcomm Incorporated |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Microsoft Corporation |
| IBM |
| Amazon.com, Inc. |
| Others |
Supply Flow & Price Mechanics
Taiwan's Hsinchu Science Park anchors advanced node fabrication capacity for tensor processing units, concentrating upstream supply leverage that cascades into downstream pricing power for automotive and industrial inference hardware procurement.
Pricing Analysis
Long-term offtake contracts dominate automotive Tier 1 supplier relationships, locking silicon allocation ahead of fleet deployment ramps. Pricing stratifies across automotive-grade certification tiers, FDA-validated medical device classifications, and standard industrial automation brackets. Cost compression in consumer-facing retail endpoints runs deepest as Qualcomm's low-power accelerator portfolio commoditizes battery-constrained inference. Healthcare systems deploying FDA-validated edge nodes exhibit the lowest price sensitivity due to validation pathway investments, while smart home consumer device manufacturers face acute margin pressure from chipset volume scale requirements.
Supply Chain Analysis
Advanced silicon feedstock draws from Taiwan Semiconductor Manufacturing capacity, South Korea's Samsung Foundry nodes, and Intel's Arizona and Oregon fabrication complexes. Raw material dependencies center on neon gas for lithography, high-purity silicon wafers, and specialized packaging substrates from Japan and Malaysia. Single-source vulnerability concentrates in Taiwan-based EUV lithography capacity, exposing automotive procurement timelines to geographic disruption. Distribution runs through direct silicon vendor relationships with German and Japanese manufacturing conglomerates, though systems integrator channel consolidation is accelerating in pharmaceutical production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification is compressing certification timelines and reshaping procurement priorities, creating a regulatory inflection that favors vertically integrated stack vendors over component specialists.
For Market Incumbents: Entrench CUDA ecosystem lock-in through industrial automation workload certification partnerships, while accelerating OpenVINO toolkit distribution to defend x86 retrofit positions against ARM-based neural accelerator displacement. Backward integration into advanced packaging capacity in India PLI scheme zones secures supply resilience against Taiwan concentration risk. Priority investment in FDA premarket submission expertise preserves healthcare margin pools from software-as-medical-device classification delays. For New Entrants and Emerging Players: Mid-market commercial trucking fleets in North America represent the most penetrable entry point, with electric vehicle cabin monitoring and fleet telematics endpoints still underpenetrated by low-power inference specialists. India's agricultural drone deployments under PLI scheme incentives offer second-mover assembly capacity without incumbent ecosystem switching costs. Go-to-market through Kubernetes-based containerized orchestration platforms bypasses proprietary SDK fragmentation that complicates cross-platform deployment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized inference accelerator designers with automotive-grade certification pipelines already validated, as opposed to cloud-native platform providers facing workload virtualization margin compression. Long-term viability hinges on federated learning-5G convergence traction in healthcare and financial services privacy-constrained applications. Watch for EU AI Act conformity assessment bottleneck resolution as the inflection signal for European market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Kubernetes-based orchestration virtualizes hardware abstraction layers across NVIDIA, Intel, and Qualcomm silicon stacks. |
| Regulatory Certification Pathway | FDA software-as-medical-device classification and EU AI Act conformity assessment unlock healthcare and industrial automation procurement. |
| Strategic Partnership | Automotive Tier 1 supplier alliances compress supplier lead times for autonomous vehicle fleet hardware allocation. |
| Geographic Expansion | India PLI scheme manufacturing partnerships capture domestic smart city and agricultural drone assembly demand. |
| Acquisition of Specialist Firm | Embedded systems ML engineering talent scarcity favors targeted capability consolidation for model compression optimization. |
Methodological Framework
A spread of perspectives from semiconductor vendor product managers, automotive Tier 1 procurement executives, healthcare biomedical engineers, and industrial automation plant engineers converged on the working assumptions. Primary interviews combined with secondary validation against SEC hyperscaler capex disclosures, FDA 510(k) submission databases, EU AI Act implementation guidance, and Taiwan Semiconductor Manufacturing capacity announcements. Bottom-up deployment volume estimates triangulated against top-down silicon wafer allocation data across the analysis window.
Demand-supply balance framing anchored the analytical approach, with segmentation dimensions spanning deployment topology, end-use vertical, enabling technology, and application domain. CAGRs derived from modeled inference hardware unit shipments and associated software licensing revenue across on-premises, hybrid, cloud-based, and remote configurations. Industry-specific forecast inputs included automotive fleet deployment schedules from Detroit and Nagoya clusters, plus EU AI Act conformity assessment pipeline throughput assumptions.
Stress conditions across Taiwan foundry capacity disruption, FDA premarket submission timeline extension, and EU AI Act classification scope expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about neural accelerator power efficiency trajectories and 5G private network deployment cadence. Cross-checking against IHS Markit automotive production databases and hyperscaler edge infrastructure capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Chipless RFID Market