
 Global Metamaterial Market | 2026-2036
Global Metamaterial Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metamaterial Market Foresight
Defense procurement channels is rewriting how metamaterial developers reach end customers, with prime contractor relationships now gatekeeping access to classified programs. Echodyne Corp. leverages its radar metamaterial arrays to anchor aerospace and border surveillance contracts. Kymeta Corporation sustains satellite terminal shipments through direct military and maritime fleet integrations. Metalenz, Inc. competes in consumer optics by displacing conventional lens stacks with flat metasurfaces.
Metamaterials are engineered composites with subwavelength periodic structures that manipulate electromagnetic, acoustic, or thermal waves through negative permeability or permittivity values rather than bulk composition. These structures are lithographically patterned onto dielectric or metallic substrates to achieve cloaking, perfect absorption, or beam steering functions unattainable with conventional materials. Electromagnetic metamaterials dominate current revenue as legacy defense programs scale absorber tile production, while optical metamaterials represent the fastest-expanding margin pool as smartphone camera modules adopt flat metalenses. Acoustic metamaterials remain niche but hold structural promise for noise cancellation in aviation propulsion systems.
The U.S. Department of Defense's Trusted Foundry program and ITAR export controls constrain which suppliers can fabricate classified metamaterial architectures, while the EU's REACH framework governs nanomaterial hazard classifications affecting European photonics foundries. China's MIIT technical standards for 6G antenna testing are creating parallel qualification regimes that domestic foundries exploit. Stakeholders must monitor which regulatory jurisdiction captures their manufacturing footprint before committing to billion-dollar lithography investments.
Market Dynamics
Defense procurement channels are rewriting how metamaterial developers reach end customers, with prime contractor relationships now gatekeeping access to classified programs and lithography investments requiring pre-qualified fabrication partnerships.
Growth Catalysts
- 6G Sub-Terahertz Standards:China's MIIT technical specifications for antenna testing are redirecting supplier qualification pathways toward domestic foundries, accelerating demand for precision electromagnetic architectures.
- Trusted Foundry Mandates:The U.S. Department of Defense's program constrains fabrication to ITAR-compliant suppliers, creating captive demand pools for qualified metamaterial producers.
- Photonics Cluster Concentration:Boston's integrated photonics corridor and San Diego's defense contractor ecosystem are concentrating R&D talent and prototyping infrastructure.
Market Restraints
- Lithography Equipment Scarcity:Extreme ultraviolet patterning systems face 18-month lead times from sole-source Dutch suppliers, throttling foundry expansion.
- REACH Nanomaterial Classification:The EU's ECHA framework imposes hazard documentation burdens on European photonics foundries processing subwavelength metallic structures.
- Conventional Dielectric Substitution:Legacy graded-index lenses and mechanical beam-steering assemblies retain cost advantages in non-defense consumer applications.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for telecom equipment manufacturing are attracting metamaterial antenna developers to establish domestic assembly.
- Acoustic Metamaterial Aviation:Noise cancellation architectures for jet propulsion systems represent an underpenetrated application with airframe OEM qualification windows opening.
- Optical-Thermal Convergence:Flat metalenses integrating radiative cooling functions are creating dual-purpose value propositions for satellite and unmanned aerial platforms.
Industry Challenges
- Multiphysics Simulation Talent:Electromagnetic-acoustic-thermal co-design requires rare expertise combining finite-element modeling with fabrication physics.
- ITAR Compliance Timelines:Security clearance protocols for foreign national engineers extend product development cycles by 9-14 months.
- Substrate Material Traceability:Defense programs mandate lot-level provenance documentation that legacy semiconductor supply chains cannot provide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metamaterial Market |
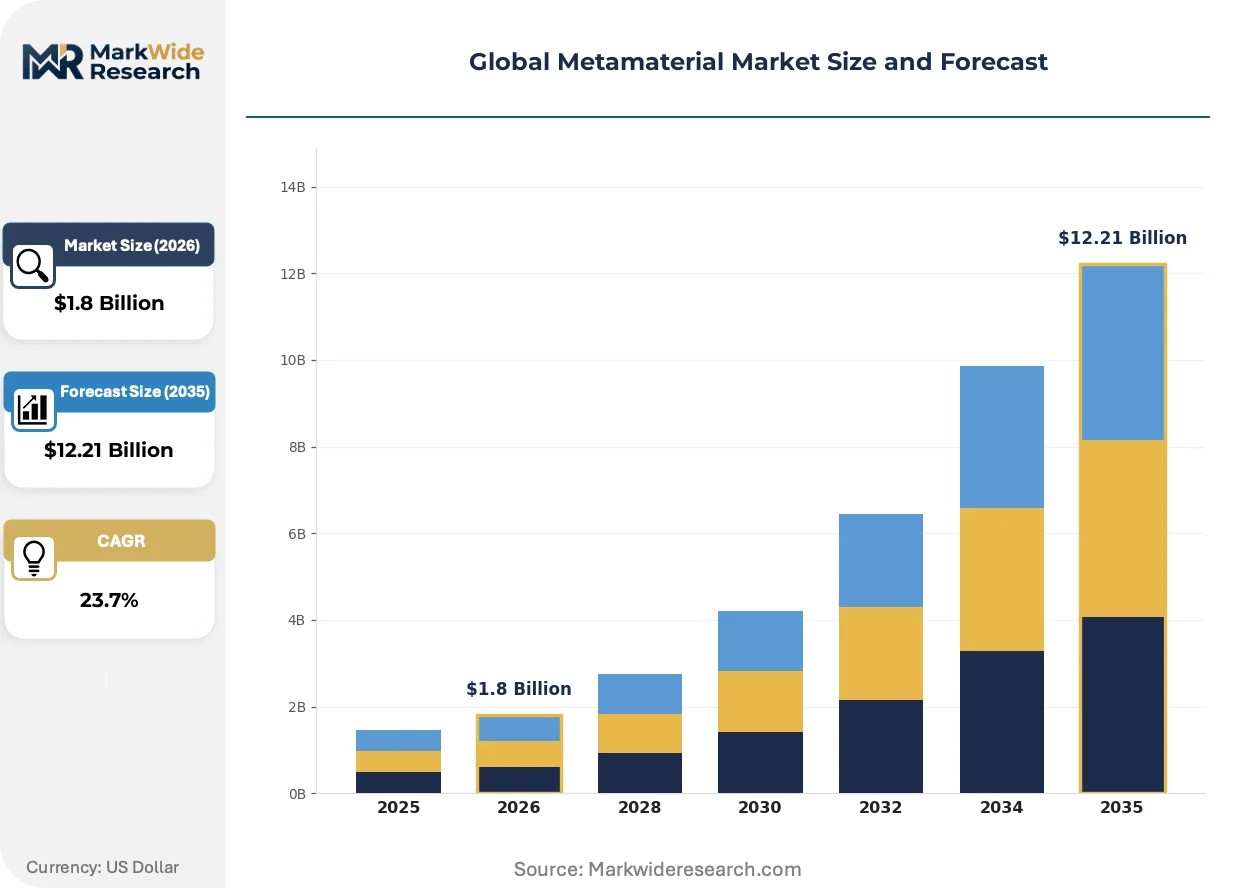
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Metamaterials, Acoustic Metamaterials, Mechanical Metamaterials, Optical Metamaterials, Thermal Metamaterials Technology: Negative Index Materials, Photonic Crystals, Split-Ring Resonators, Nanostructured Metamaterials, Plasmonic Metamaterials Application: Wireless Communication, Defense Systems, Imaging Systems, Sensors, Energy Harvesting End User: Telecommunication Operators, Aerospace & Space Agencies, Consumer Electronics Brands, Research Institutions |
| Companies Covered | Pivotal Commware, TeraView Limited, Kymeta Corporation, Fractal Antenna Systems, Multiwave Technologies AG, Echodyne Corp., NKT Photonics A/S, Metalenz, Inc., Meta Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metamaterial Market Shifts & Advancements
Computational design tools and novel patterning methods are compressing development cycles while regulatory jurisdictions compete to capture fabrication investment through divergent qualification regimes.
Digital metamaterials with programmable unit-cell responses are digitizing beam-steering functions previously requiring mechanical gimbals. Satellite terminal manufacturers are adopting these reconfigurable arrays for rapid acquisition without moving parts. This architecture is digitizing the RF front-end, collapsing multiple discrete components into software-defined surfaces.
The EU's F-Gas Regulation is phasing out fluorinated greenhouse gases used in plasma etching processes for metamaterial fabrication. European foundries are retrofitting etch chambers with alternative chemistries at capital costs exceeding €2 million per production line. German and French photonics clusters are absorbing these transitions faster than southern European facilities.
Defense primes are consolidating supplier tiers, requiring metamaterial developers to assume subsystem integration responsibilities previously handled by tier-two contractors. This channel compression forces flat metalens producers to deliver complete optical engines rather than bare components. The United States and United Kingdom exhibit the most pronounced vertical consolidation.
Global Metamaterial Market Segmentation
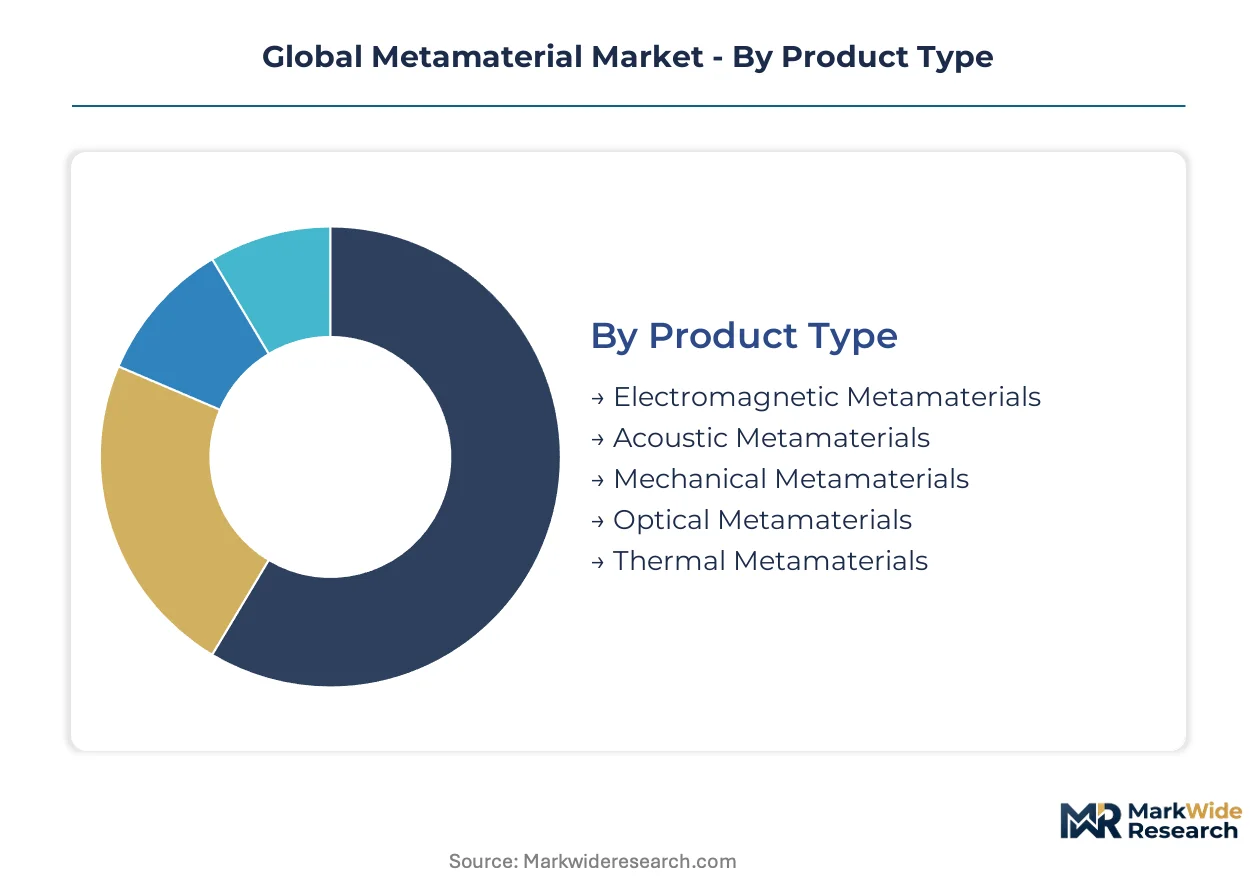
Metamaterial architectures diverge sharply across electromagnetic, acoustic, and optical domains, each demanding distinct fabrication protocols and qualification pathways. Procurement patterns in defense and telecommunications create divergent margin structures that reshape how suppliers prioritize R&D investment across these categories.
Product Type:
Electromagnetic architectures dominate defense absorption and 6G antenna applications, while optical variants capture consumer electronics volume through flat metalens substitution.
- Electromagnetic Metamaterials:Lithographically patterned metallic or dielectric substrates with subwavelength periodic structures achieve negative permeability values for radar absorption and beam steering. U.S. Department of Defense Trusted Foundry contracts concentrate fabrication demand around Boston's photonics corridor and San Diego's defense contractor ecosystem, with ITAR compliance gating access to classified programs.
- Optical Metamaterials:Flat metasurfaces manipulate visible and infrared wavefronts through nanostructured antenna arrays rather than conventional curved lenses. Consumer electronics brands in East Asia are displacing multi-element lens stacks with these architectures in smartphone camera modules, compressing z-height while expanding field-of-view performance.
- Acoustic Metamaterials:Subwavelength resonator arrays manipulate sound propagation through engineered density and bulk modulus profiles.
- Mechanical Metamaterials:Architected cellular structures achieve negative Poisson's ratio or programmable stiffness through geometric rather than compositional design.
- Thermal Metamaterials:Radiative cooling and heat-flux steering architectures integrate photonic crystal patterns for passive temperature management.
Established volume favors electromagnetic absorbers; emerging adoption favors optical metalenses.
Technology:
Patterning sophistication separates defense-qualified suppliers from commercial-tier competitors, with lithography node access determining which architectures reach production.
- Negative Index Materials:Simultaneously negative permittivity and permeability enable backward wave propagation and subwavelength focusing impossible with conventional dielectrics. China's MIIT 6G sub-terahertz testing standards are redirecting supplier qualification toward domestic foundries capable of precision electromagnetic architectures at terahertz frequencies.
- Photonic Crystals:Periodic dielectric modulations create photonic bandgaps that confine or guide light with wavelength-scale precision. Optical communications and sensing applications in the United States and Germany concentrate demand for these structures, with EU F-Gas Regulation compliance adding capital burden to European fabrication lines.
- Split-Ring Resonators:Metallic LC circuits at subwavelength scales achieve magnetic response at optical frequencies.
- Nanostructured Metamaterials:Bottom-up or top-down patterning approaches create unit cells below 100 nanometers.
- Plasmonic Metamaterials:Surface plasmon polaritons concentrate electromagnetic energy beyond the diffraction limit.
Mature defense procurement favors negative index platforms; steepest expansion trajectory sits with photonic crystal integration in datacom transceivers.
Application:
End-use requirements fragment the supplier base, with defense programs demanding ITAR-compliant traceability while consumer applications prioritize cost-scaling.
- Defense Systems:Radar-absorbent tiles, cloaking architectures, and conformal antenna arrays require lot-level substrate provenance and security-cleared engineering teams. Prime contractor consolidation in the United States and United Kingdom now forces metamaterial developers to deliver subsystem integration rather than bare components.
- Wireless Communication:Reconfigurable intelligent surfaces and 6G antenna arrays demand programmable unit-cell responses for software-defined beam steering. India's PLI scheme for telecom equipment manufacturing is attracting antenna developers to establish domestic assembly operations outside traditional U.S. and Chinese supply chains.
- Imaging Systems:Flat metalenses and computational cameras replace conventional optical stacks.
- Sensors:Subwavelength resonator arrays enable label-free biochemical detection and strain sensing.
- Energy Harvesting:Thermophotovoltaic and piezoelectric metamaterials convert waste heat or vibration into electrical power.
Defense procurement anchors current revenue; wireless infrastructure builds the fastest-climbing demand curve.
End User:
Customer sophistication and security clearance requirements stratify the supplier landscape into defense-captive and commercial-accessible tiers.
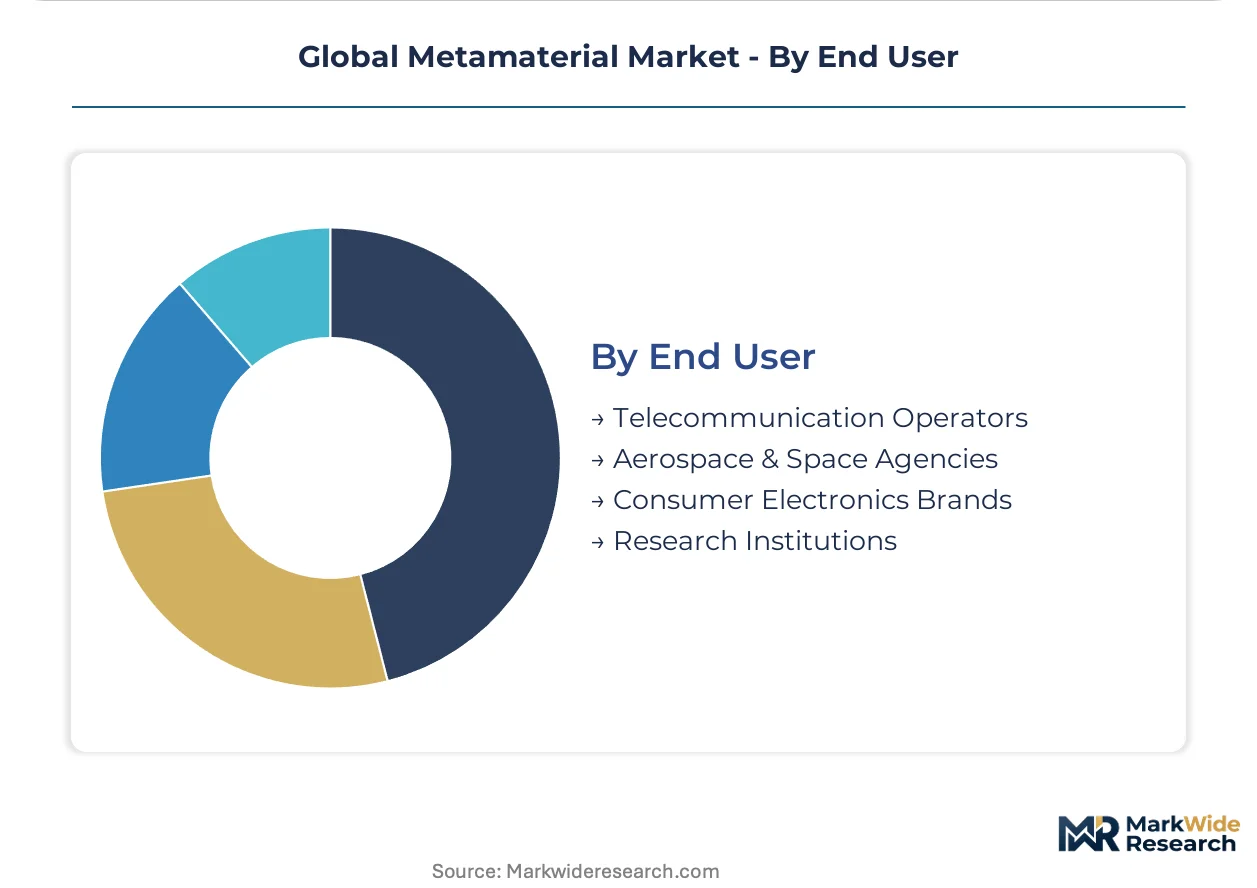
- Telecommunication Operators:5G and 6G infrastructure deployment drives demand for massive MIMO and reconfigurable intelligent surface technologies. Equipment vendors must navigate China's MIIT standards alongside U.S. FCC and European ETSI regulatory frameworks to serve multinational carrier procurement.
- Aerospace & Space Agencies:NASA, ESA, and national military space programs require radiation-hardened metamaterials with documented thermal cycling performance. Satellite terminal manufacturers adopt digital metamaterial arrays to eliminate mechanical gimbals while maintaining rapid acquisition capability.
- Consumer Electronics Brands:Smartphone and AR/VR device manufacturers prioritize metalens form-factor reduction and assembly automation.
- Research Institutions:National laboratories and university consortia advance foundational metamaterial physics and computational design tools.
Aerospace qualification windows favor established defense suppliers; consumer electronics volume favors scalable optical metalens platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The DARPA-backed photonics corridors along Interstate 95 and Interstate 5 underpin the United States' fabrication dominance. Germany's Fraunhofer network anchors European prototyping capacity. China's MIIT standards regime redirects supplier qualification toward domestic foundries.
United States
Defense procurement through the Trusted Foundry program concentrates classified absorber production around Boston's integrated photonics cluster and San Diego's defense contractor corridor. ITAR export controls gate access to lithography partnerships serving NASA and military space programs. Echodyne Corp. and Kymeta Corporation anchor radar and satellite terminal supply chains from these coastal hubs.
Germany
Photonic crystal research for datacom transceivers concentrates in the Fraunhofer Heinrich Hertz Institute corridor between Berlin and Munich. ECHA's REACH nanomaterial classification imposes hazard documentation burdens on subwavelength metallic fabrication. The EU F-Gas Regulation forces €2 million retrofits per etch chamber, accelerating consolidation in Bavarian and Baden-Württemberg foundries.
China
MIIT technical specifications for 6G sub-terahertz antenna testing redirect supplier qualification toward domestic foundries capable of precision electromagnetic architectures. The dual carbon goals framework shapes energy efficiency mandates for fabrication facilities. Yangtze River Delta and Pearl River Delta clusters absorb lithography investment diverted from ITAR-constrained Western supply chains.
United Kingdom
Prime contractor consolidation in the defense sector forces metamaterial developers to assume subsystem integration responsibilities previously handled by tier-two contractors. The UK Ministry of Defence's procurement frameworks emphasize lot-level substrate provenance documentation. Cambridge and Oxford photonics clusters feed engineering talent into BAE Systems and QinetiQ supply chains.
India
Production-linked incentives for telecom equipment manufacturing attract metamaterial antenna developers to establish domestic assembly outside traditional U.S. and Chinese supply chains. TRAI spectrum allocation frameworks shape 5G and 6G infrastructure deployment timelines. Karnataka and Telangana absorb R&D investment targeting massive MIMO and reconfigurable intelligent surface technologies.
Global Metamaterial Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying patterned substrates and metasurface wafers. The vendor base stratifies between ITAR-captive defense suppliers and commercial-accessible optical metalens producers. Three archetypes dominate: lithography-anchored foundries serving classified programs, flat optics specialists displacing smartphone lens stacks, and reconfigurable antenna developers digitizing RF front-ends. Competitive moves concentrate on prime contractor partnership formation and EUV capacity reservation.
Among U.S.-based platform developers, Echodyne Corp. and Kymeta Corporation exemplify the defense-captive archetype through radar and satellite terminal integration. Metalenz, Inc. occupies a position within the consumer-optics tier, representing flat metalens specialists targeting smartphone camera module substitution. Meta Materials Inc. and Multiwave Technologies AG sit within the materials-architecture segment, supplying substrate technologies that downstream integrators pattern into finished metamaterial systems.
| Leading Market Players |
|---|
| Pivotal Commware |
| TeraView Limited |
| Kymeta Corporation |
| Fractal Antenna Systems |
| Multiwave Technologies AG |
| Echodyne Corp. |
| NKT Photonics A/S |
| Metalenz, Inc. |
| Meta Materials Inc. |
| Others |
Supply & Pricing Matrix
Trans-Pacific lithography equipment corridors from Dutch suppliers to U.S. and East Asian foundries impose freight premiums that compound with EUV tool scarcity, concentrating supply-side leverage among ITAR-qualified fabricators while forcing downstream price stratification between defense-captive and commercial-accessible tiers.
Pricing Analysis
Volume-discount tiering structures separate defense procurement contracts from commercial optical metalens orders, with Trusted Foundry qualification premiums anchoring the highest tier and smartphone camera module suppliers competing on wafer-scale cost compression. Price differentiation rests on ITAR compliance certification and lithography node access, with defense programs absorbing security-cleared engineering premiums while consumer electronics buyers drive standard-tier pricing downward. Cost compression in commercial electromagnetic absorbers intensifies because conventional dielectric substitutes retain assembly-line familiarity. Research institutions exhibit highest price sensitivity; aerospace prime contractors demonstrate lowest sensitivity due to mission-critical specification mandates.
Supply Chain Analysis
Extended payment terms from Dutch lithography equipment vendors to U.S. and Chinese foundries stretch working capital cycles, with supply-chain finance facilities increasingly intermediating between capital-constrained patterning houses and defense prime contractors. Geographic supply concentration centers on the United States, China, and Germany, with substrate material traceability requirements favoring domestic foundries in each jurisdiction. Raw material dependencies draw from specialized dielectric substrates, noble metal thin-film precursors, and fluorinated etch chemistries facing EU F-Gas phaseouts. Single-source vulnerability permeates extreme ultraviolet lithography tool availability. Distribution runs through prime contractor integration channels rather than component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metamaterial incumbents confront substitution defense against conventional graded-index lenses and mechanical beam-steering assemblies that exploit established manufacturing scale and assembly automation.
For Market Incumbents: Build ITAR-captive moats through lithography partnership pre-qualification and lot-level substrate provenance systems that emerging competitors cannot replicate. Deepen backward integration into specialized dielectric substrate production to secure supply continuity against REACH nanomaterial classification delays. Channel control through prime contractor subsystem integration responsibilities now gates classified program access, making tier-two supplier relationships a vulnerability point. For New Entrants and Emerging Players: Pursue acoustic metamaterial aviation applications where airframe OEM qualification windows remain underpenetrated and noise cancellation specifications are hardening. Target India's PLI scheme for telecom equipment manufacturing to establish assembly operations outside ITAR-constrained supply chains. Go-to-market positioning through reconfigurable intelligent surface demonstrations for 5G infrastructure trials accelerates carrier procurement engagement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lithography-anchored foundries with Trusted Foundry credentials and existing prime contractor relationships over speculative optical metalens plays. Long-term viability across the projection horizon hinges on regulatory jurisdiction capture rather than pure technical differentiation. Watch for MIIT qualification pathway announcements as inflection indicators for supplier geographic rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Foundry Qualification | ITAR compliance unlocks DOD absorber tile contracts and NASA space program lithography partnerships. |
| EUV Capacity Reservation | Pre-commitment to Dutch lithography tool slots secures patterning throughput for defense procurement cycles. |
| Prime Contractor Integration | Subsystem delivery responsibilities replace component supply relationships in U.S. and UK defense channels. |
| Optical-Thermal Convergence | Flat metalens radiative cooling integration creates dual-purpose satellite payload value propositions. |
| Computational Design Platform | Multiphysics simulation tools compress electromagnetic-acoustic-thermal co-design cycles for rare engineering talent. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers, photonics foundry operations directors, and satellite terminal engineering leads and refined through secondary validation against SEC filings from publicly traded metamaterial developers, DOD Trusted Foundry program documentation, and EU ECHA REACH nanomaterial classification registers. Bottom-up triangulation across wafer shipment volumes and top-down reconciliation against prime contractor absorption program budgets anchored market sizing.
Demand-supply-balance framing modeled electromagnetic, optical, and acoustic product type segments across defense systems, wireless communication, and imaging system applications, with lithography node access and regulatory jurisdiction qualification serving as cross-cutting supply constraints. CAGRs were derived from patterning capacity buildout trajectories and carrier infrastructure deployment schedules. Forecast inputs incorporated MIIT 6G sub-terahertz testing standard implementation timelines and F-Gas Regulation etch chemistry retrofit compliance costs.
Sensitivities concentrate around EUV tool delivery delays, REACH nanomaterial reclassification rulings, and prime contractor consolidation pacing that could accelerate or compress subsystem integration requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Asia Pacific Quantum Computing Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market