
 Global Transparent Display Market | 2026-2036
Global Transparent Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transparent Display Market Foresight
Specialized photonics engineering talent is bifurcating the competitive landscape between established panel makers and emerging microLED specialists. Samsung Electronics leverages its vertically integrated semiconductor foundry network to sustain leadership in OLED transparent display yields. BOE Technology Group anchors massive Gen-10.5 fab capacity in Hefei and competes aggressively on cost for LCD transparent variants in Chinese smart retail deployments. LG Display differentiates through automotive-qualified transparent OLED panels and occupies premium positions in European luxury vehicle HUD programs.
Transparent display refers to emissive or transmissive screen technologies permitting simultaneous content visibility and see-through viewing of background objects, typically achieving 30-70% optical transparency depending on pixel density and backlight architecture. These systems serve retail merchandising, vehicular safety interfaces, and architectural integration by overlaying digital information without obstructing physical sightlines. OLED transparent panels currently lead commercial shipments due to self-emissive pixel structures eliminating backlight layers, while microLED segments represent the fastest-growing category as chip-scale transfer yields improve and luminance efficiency surpasses incumbent alternatives. Resistive touch technology retains mature cost advantages in industrial kiosk applications, whereas projected capacitive layers dominate consumer-facing smart retail installations where multi-gesture responsiveness commands margin premiums.
The US Federal Communications Commission regulates electromagnetic emissions from transparent display modules, while the EU RoHS directive restricts hazardous substances in panel substrates and driver IC packaging. South Korea's Ministry of Trade, Industry and Energy administers national R&D consortia advancing next-generation display standards through K-Display initiatives. Japan's METI coordinates industry-academic partnerships targeting microLED mass transfer equipment localization. Stakeholders must monitor evolving automotive safety certifications for head-up display transparency thresholds and brightness regulations across target export markets.
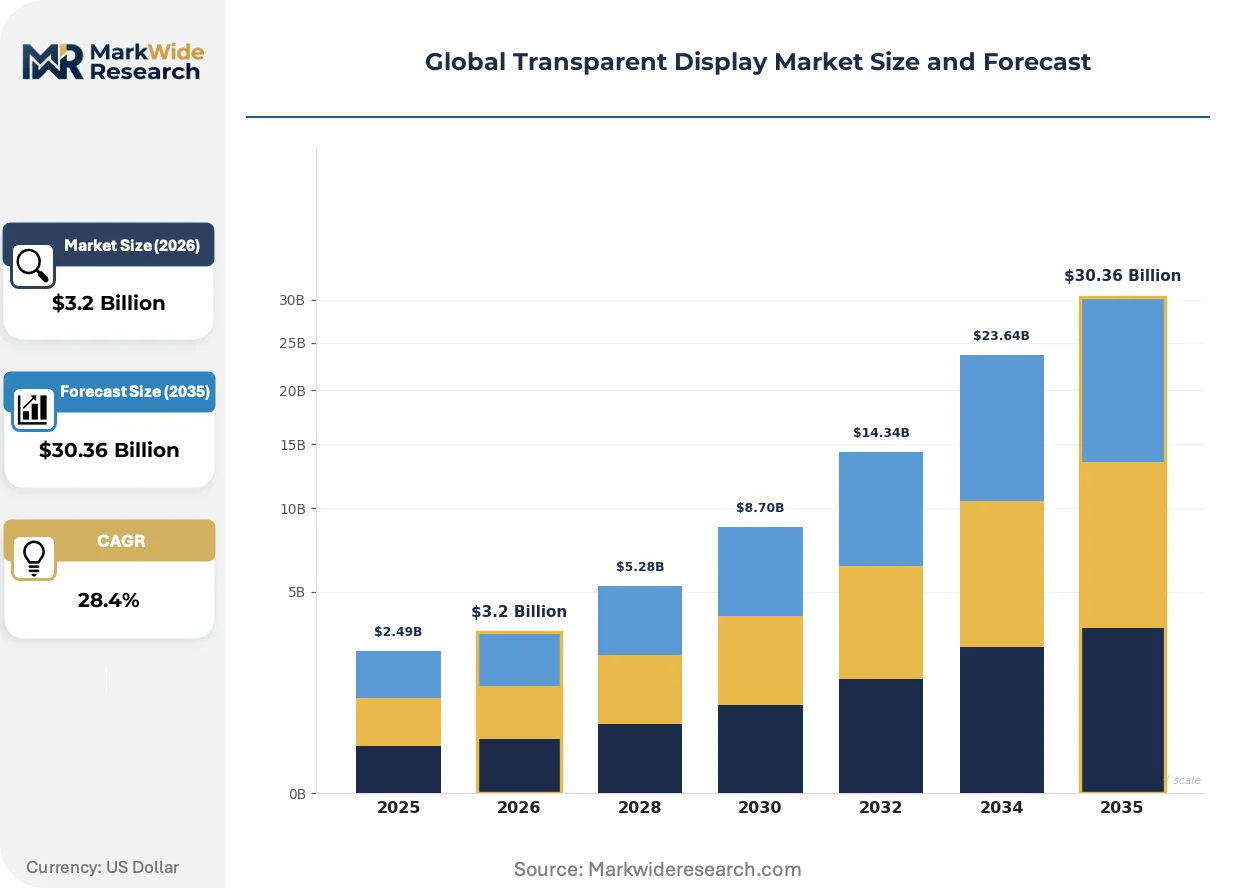
Market Dynamics
The transparent display market is undergoing a fundamental restructuring as microLED chip-scale transfer yields cross commercial viability thresholds, compressing the traditional OLED-dominated supply base and redrawing competitive boundaries between semiconductor foundries and legacy panel manufacturers.
Growth Catalysts
- K-Display R&D Consortia:South Korea's Ministry of Trade, Industry and Energy channels public-private funding into next-generation display standards, accelerating domestic pilot line deployment for automotive-qualified transparent OLED panels.
- Automotive HUD Integration:Premium vehicle OEMs are mandating augmented reality windshields as standard equipment in luxury segments, creating sustained pull for high-brightness transparent display modules.
- Smart Retail Deployment:Chinese commercial real estate operators are installing transparent LCD variants in flagship storefronts, leveraging established Gen-10.5 fab capacity for cost-competitive digital merchandising solutions.
Market Restraints
- Indium Tin Oxide Supply Concentration:Over 80% of refined indium processing occurs in Chinese smelter complexes, exposing transparent electrode costs to geopolitical supply disruptions and export licensing volatility.
- MicroLED Mass Transfer Yield Limitations:Chip placement accuracy below 99.999% at production speeds creates unrecoverable yield loss, constraining viable output to prototype and low-volume specialty applications.
- EU RoHS Substance Restrictions:Hazardous substance limits in panel substrates and driver IC packaging impose compliance costs and disqualify certain phosphor-based emitters from European consumer electronics channels.
Strategic Opportunities
- Architectural Glass Integration:Underpenetrated commercial building retrofits in Germany and France present demand for transparent display facades that merge digital signage with structural glazing.
- Dual Carbon Policy Alignment:China's MIIT energy efficiency mandates for display manufacturing create preferential market access for low-power microLED technologies versus incumbent OLED alternatives.
- Medical Imaging Overlays:Surgical navigation systems in Japanese university hospitals are piloting transparent OLED panels for real-time volumetric data projection without obstructing operative fields.
Industry Challenges
- Photonics Engineering Scarcity:The specialized workforce for microLED epitaxy and transfer process optimization remains concentrated in Hsinchu and Seoul, constraining global fab expansion timelines.
- Automotive Certification Complexity:Head-up display transparency thresholds and brightness regulations vary across NHTSA, KBA, and Japan's MLIT, fragmenting product qualification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transparent Display Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $30.36 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, LCD, MicroLED, LED, Electrochromic, Electroluminescent Technology: Capacitive Touch, Resistive Touch, Infrared Touch, Optical Imaging, Surface Acoustic Wave, Projected Capacitive Application: Advertising Displays, Smart Retail Shelves, Automotive HUDs, Wearable Electronics, Architectural Windows, Public Information Kiosks End User: Consumer Electronics Manufacturers, Automotive Tier-1 Suppliers, Retail Chain Operators, Building Automation Integrators, Government Agencies, Event Management Firms |
| Companies Covered | AU Optronics, Panasonic Holdings Corporation, Samsung Electronics, Japan Display Inc., Innolux Corporation, LG Display, Sharp Corporation, Planar Systems Inc., BOE Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transparent Display Market Shifts & Advancements
Transparent display technology is bifurcating into two parallel development tracks: refinement of self-emissive architectures for premium applications and radical simplification of backlit systems for cost-sensitive volume deployment.
MicroLED transparent panels are displacing OLED alternatives in high-brightness automotive and outdoor signage applications. Tier-1 automotive suppliers in Stuttgart and Nagoya are qualifying microLED prototypes for next-generation HUD programs. The structural consequence is a compression of OLED pricing power in segments above 5,000 nits luminance requirements.
Japan's METI coordinates industry-academic partnerships targeting domestic mass transfer equipment localization. The initiative reduces reliance on Dutch and American pick-and-place tool vendors. Korean and Taiwanese foundries are responding by accelerating proprietary transfer process development to maintain equipment supply chain leverage.
Hospital procurement departments in Seoul and Boston are unbundling transparent display hardware from integrated surgical system contracts. This shift enables direct sourcing from panel specialists rather than through OEM intermediaries. The pattern is most pronounced in academic medical centers with dedicated biomedical engineering evaluation teams.
Global Transparent Display Market Segmentation
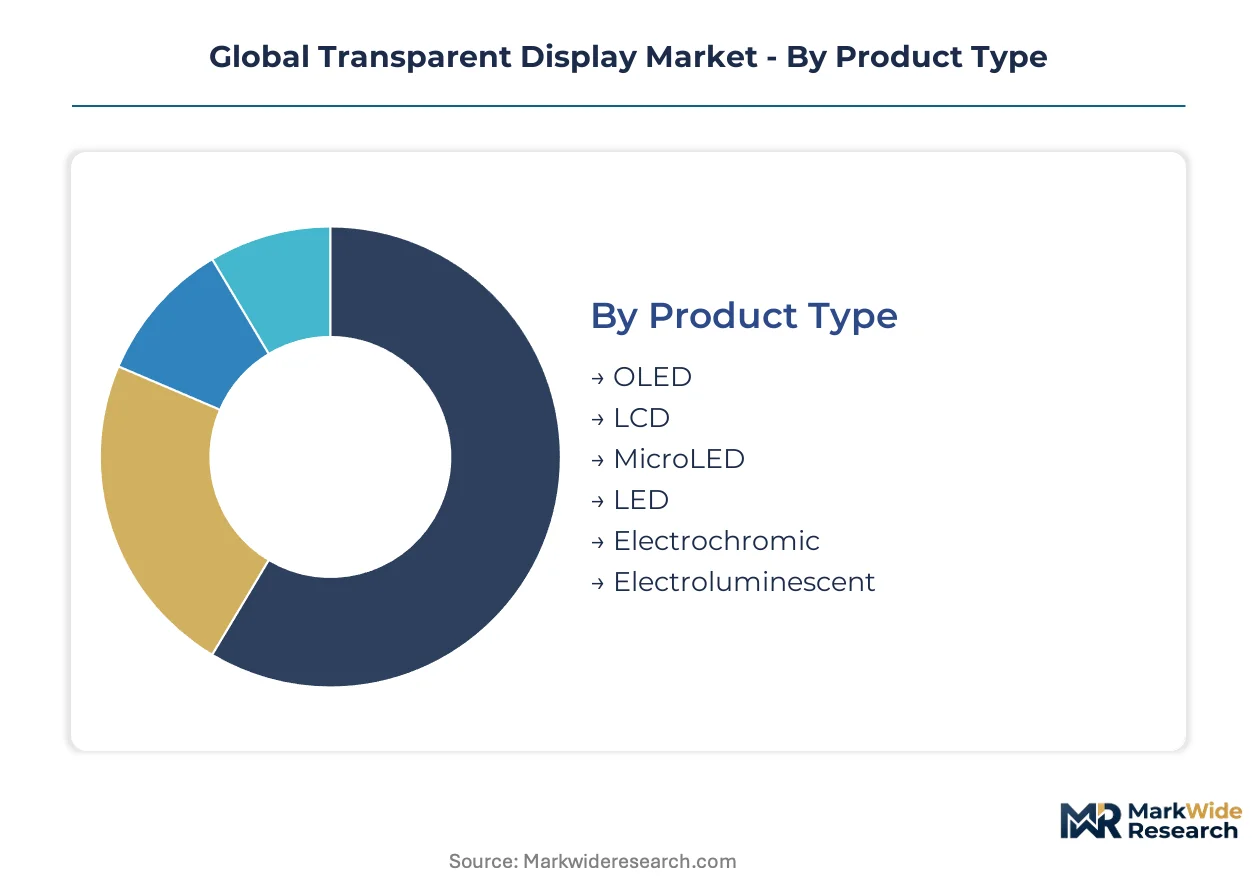
Transparent display procurement channels diverge sharply by product maturity and application criticality. Automotive HUDs flow through qualified Tier-1 supplier networks with multi-year validation cycles, while retail deployments leverage direct OEM relationships for rapid storefront retrofits.
Product Type:
OLED panels dominate premium channels serving automotive and medical applications, while LCD variants capture high-volume smart retail contracts through established distributor networks.
- OLED:Self-emissive pixel structures eliminate backlight layers, achieving 40-45% optical transparency. Demand concentrates in Stuttgart and Nagoya automotive programs where augmented reality windshields require high contrast ratios and sub-millisecond response times.
- MicroLED:Chip-scale architectures deliver luminance efficiency exceeding 10,000 nits with superior transparency ratios. Korean foundries in Hsinchu and Seoul are scaling pilot lines for next-generation HUD qualification, though mass transfer yield limitations constrain volume deployment.
- LCD:Backlit transmissive panels leverage mature Gen-10.5 fab capacity in Hefei for cost-competitive digital merchandising solutions.
- LED:Discrete emitter arrays serve large-format architectural installations with modular scaling flexibility.
- Electrochromic:Voltage-controlled opacity modulation targets smart window applications in commercial building retrofits.
- Electroluminescent:Thin-film phosphor layers occupy niche industrial indicator and emergency signage segments.
By volume, LCD leads through retail channel penetration. By growth pace, MicroLED is climbing fastest as automotive luminance requirements escalate.
Technology:
Touch interface selection tracks end-use durability requirements and gesture complexity, with projected capacitive layers commanding margin premiums in consumer-facing deployments.
- Projected Capacitive:Multi-gesture recognition enables sophisticated retail interactions. Smart shelf installations in Chinese flagship stores specify this technology for swipe, pinch, and hover responsiveness.
- Resistive Touch:Pressure-activated layers withstand harsh industrial environments. Factory floor kiosks and outdoor public information terminals in German municipal deployments prioritize this mature, cost-optimized architecture.
- Capacitive Touch:Surface-based field detection serves standard consumer electronics interfaces.
- Infrared Touch:Frame-mounted emitter-receiver arrays enable large-format interactive displays.
- Optical Imaging:Camera-based touch detection supports variable-size installations without overlay modification.
- Surface Acoustic Wave:Ultrasonic transduction delivers high optical clarity for premium retail showcases.
By installed base, resistive touch retains the largest footprint. By replacement velocity, projected capacitive is gaining share fastest in new construction.
Application:
Application segmentation reveals divergent procurement authority structures, with automotive OEMs centralizing HUD specifications while retail operators delegate to regional facilities managers.
- Automotive HUDs:Windshield-integrated projection systems overlay navigation and safety data within driver sightlines. European luxury vehicle programs in Stuttgart and Munich mandate augmented reality transparency thresholds exceeding 70% for regulatory compliance.
- Smart Retail Shelves:Transparent product facades merge physical inventory with dynamic pricing overlays. Chinese commercial real estate operators in Shanghai and Shenzhen are deploying these at scale through direct BOE procurement agreements.
- Advertising Displays:Storefront digital signage targets pedestrian engagement in high-traffic urban corridors.
- Wearable Electronics:Head-mounted and wrist-worn form factors prioritize weight minimization and power efficiency.
- Architectural Windows:Structural glazing integration merges building envelope functions with information display.
- Public Information Kiosks:Transit hub and municipal wayfinding terminals emphasize vandal resistance and sunlight readability.
By revenue concentration, automotive HUDs command premium positioning. By deployment velocity, smart retail shelves are expanding most quickly across Asian commercial real estate.
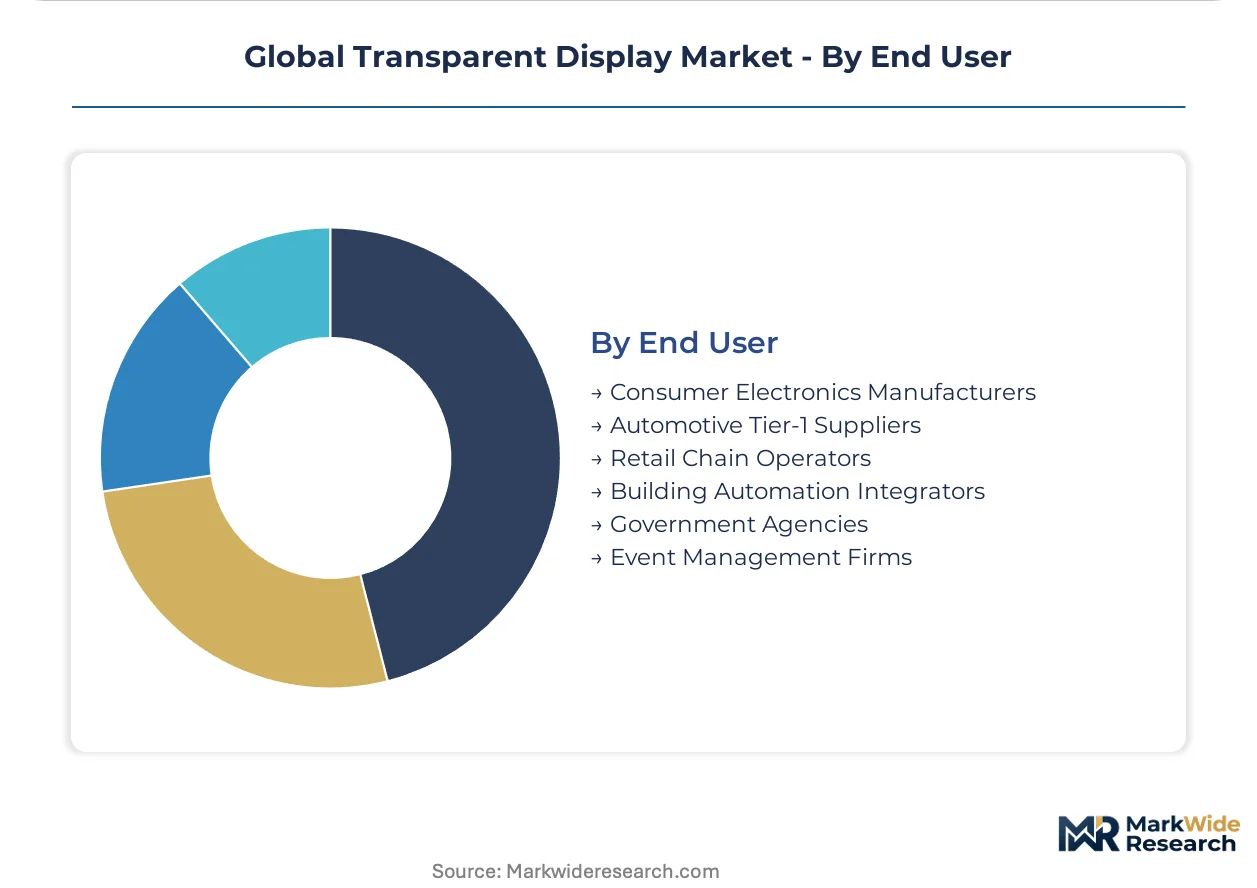
End User:
End user procurement sophistication varies dramatically, with automotive Tier-1 suppliers operating dedicated display engineering teams while event management firms rely on rental house intermediaries.
- Automotive Tier-1 Suppliers:Continental, Bosch, and Denso maintain captive transparent display qualification laboratories. These organizations enforce automotive-grade reliability standards including temperature cycling from -40°C to 85°C and mechanical shock resistance.
- Retail Chain Operators:Fast-fashion and luxury cosmetics brands in Paris, Milan, and Tokyo deploy transparent merchandising as competitive differentiation. Procurement decisions increasingly centralize at headquarters level rather than through regional franchisees.
- Consumer Electronics Manufacturers:Smartphone and laptop OEMs evaluate transparent panels for next-generation product differentiation.
- Building Automation Integrators:Commercial construction specialists specify transparent facades during new build and major renovation phases.
- Government Agencies:Transit authorities and municipal information services deploy public-facing transparent kiosks.
- Event Management Firms:Temporary installation specialists prioritize rapid deployment and rental flexibility over ownership economics.
By contract value, automotive Tier-1 suppliers dominate. By transaction frequency, retail chain operators are scaling fastest through standardized storefront specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transparent display consumption patterns diverge sharply across geographies. South Korea and China prioritize automotive HUD integration and smart retail deployment respectively, while Germany and Japan concentrate on industrial and medical qualification standards. The United States exhibits fragmented demand across defense, commercial signage, and emerging architectural applications.
South Korea
Automotive HUD programs and government-backed R&D consortia dominate procurement. The Ministry of Trade, Industry and Energy channels public-private funding through K-Display initiatives, accelerating pilot line deployment for automotive-qualified transparent OLED panels. Samsung Electronics and LG Display anchor production clusters in Gyeonggi-do and Paju, supplying European luxury vehicle programs.
China
Smart retail installations and commercial real estate retrofits absorb the majority of domestic transparent LCD output. MIIT energy efficiency mandates for display manufacturing create preferential market access for low-power technologies. BOE Technology Group operates massive Gen-10.5 fab capacity in Hefei, serving flagship storefront deployments in Shanghai and Shenzhen.
Germany
Automotive Tier-1 suppliers centralize transparent display qualification for augmented reality windshields. KBA enforces head-up display transparency thresholds and brightness regulations that exceed 70% for regulatory compliance. Stuttgart and Munich host captive engineering laboratories at Continental and Bosch, validating panels for temperature cycling from -40°C to 85°C.
Japan
Medical imaging overlays and surgical navigation systems drive premium transparent OLED demand. METI coordinates industry-academic partnerships targeting domestic microLED mass transfer equipment localization. Nagoya-based automotive suppliers qualify next-generation HUD prototypes, while Tokyo and Osaka university hospitals pilot real-time volumetric data projection without obstructing operative fields.
United States
Defense applications and commercial architectural integration represent emerging demand pockets. The FCC regulates electromagnetic emissions from transparent display modules, while NHTSA maintains distinct automotive safety certifications from European and Asian regulators. Boston and Seattle academic medical centers evaluate surgical navigation hardware, with procurement departments increasingly unbundling display components from integrated system contracts.
Global Transparent Display Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive dynamics shaped by semiconductor foundry access and automotive qualification capabilities. Samsung Electronics and LG Display occupy positions anchored by captive OLED yields and automotive program wins, while BOE Technology Group competes aggressively on cost through massive Gen-10.5 fab scale. Three archetypes define the landscape: vertically integrated panel makers with semiconductor foundry networks, display specialists focused on automotive and medical qualification, and emerging microLED fabricators building chip-scale transfer expertise. Dominant competitive moves include backward integration into driver IC design and strategic partnerships with Tier-1 automotive suppliers to secure multi-year validation cycles.
Among Asia-Pacific panel manufacturers, Samsung Electronics, LG Display, and BOE Technology Group exemplify the integrated-leader archetype. Samsung Electronics represents the foundry-integrated model, leveraging semiconductor fabrication networks to sustain leadership in OLED transparent display yields. LG Display occupies a position differentiated through automotive-qualified transparent OLED panels and premium European luxury vehicle program participation. BOE Technology Group anchors the cost-competitive vector, deploying massive Gen-10.5 fab capacity for high-volume smart retail and digital merchandising deployments. Japan Display Inc. and Sharp Corporation sit within the specialist tier, with geographic concentration in Japanese industrial and medical qualification channels. Panasonic Holdings Corporation and AU Optronics represent diversified electronics conglomerates with display divisions competing across multiple regional markets.
| Leading Market Players |
|---|
| AU Optronics |
| Panasonic Holdings Corporation |
| Samsung Electronics |
| Japan Display Inc. |
| Innolux Corporation |
| LG Display |
| Sharp Corporation |
| Planar Systems Inc. |
| BOE Technology Group |
| Others |
Supply & Pricing Matrix
Massive Gen-10.5 fab utilization rates in Hefei and Gyeonggi-do concentrate transparent LCD output among three integrated leaders, compressing price floors for backlit variants while self-emissive OLED panels sustain premium positioning through yield-constrained supply.
Pricing Analysis
Long-term offtake agreements dominate automotive HUD procurement, with Tier-1 suppliers locking multi-year contracts for qualified transparent OLED panels. Three-tier pricing structure across automotive-grade, commercial retail, and industrial kiosk tiers separates certification level from volume scale. Cost compression in LCD variants is intensifying because BOE's Hefei capacity expansion floods smart retail channels. Retail chain operators exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize reliability over unit economics.
Supply Chain Analysis
Strategic stockpiling of indium tin oxide feedstock prevails among Korean and Japanese panel makers confronting Chinese smelter concentration. Taiwan, South Korea, and China anchor transparent display manufacturing, with Hsinchu and Seoul housing specialized photonics engineering talent. Production draws from indium tin oxide, OLED emitter materials, and microLED epitaxial wafers. Single-source vulnerability in refined indium processing exposes electrode costs to export licensing volatility. Distribution runs through qualified Tier-1 networks for automotive, direct OEM relationships for retail, and distributor channels for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transparent display incumbents face substitution pressure from microLED chip-scale architectures as mass transfer yields improve, requiring defensive repositioning to protect OLED-derived revenue streams.
For Market Incumbents: Compound automotive qualification advantages by deepening captive driver IC design and securing KBA-validated transparency thresholds above 70%. Expand pilot line capacity in Gyeonggi-do to preempt microLED displacement in high-brightness HUD segments. MicroLED mass transfer yield breakthroughs represent the primary substitution threat demanding process R&D acceleration.
For New Entrants and Emerging Players: Lead with architectural glass integration in German and French commercial building retrofits, where incumbent penetration remains underdeveloped. Target medical imaging overlay pilots in Boston and Seoul academic medical centers unbundling display hardware from surgical system contracts. Pursue direct hospital procurement relationships bypassing OEM intermediaries as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive-qualified panel specialists with multi-year Tier-1 contracts. Long-term viability over the projection horizon favors foundry-integrated manufacturers with captive semiconductor fabrication networks. Acquisition focus should center on microLED transfer process specialists in Hsinchu and Seoul. Watch microLED mass transfer yield thresholds crossing commercial viability as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Certification Investment | KBA-validated transparency thresholds above 70% unlock European luxury OEM programs. |
| MicroLED Mass Transfer Scale-Up | Pilot line deployment in Seoul accelerates displacement of OLED in high-brightness HUDs. |
| Backward Integration into Driver ICs | Captive semiconductor design reduces dependency on external foundry allocation. |
| Direct Hospital Procurement Channel | Boston and Seoul academic centers unbundle display hardware from surgical system contracts. |
| Architectural Facade Partnership | German and French commercial retrofits merge digital signage with structural glazing. |
Research Methodology
A standing panel of automotive Tier-1 procurement directors, display panel yield engineers, smart retail facilities managers, and biomedical engineering evaluation teams provided ongoing calibration across the study. Primary interviews with these stakeholders combined with secondary validation from FCC electromagnetic emission filings, EU RoHS substance restriction databases, K-Display initiative progress reports, and MIIT energy efficiency mandate disclosures. Bottom-up capacity utilization data from Hefei, Gyeonggi-do, and Paju production clusters triangulated against top-down automotive HUD installation forecasts.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor foundry capex disclosures and automotive OEM platform content specifications. The analytical framework modeled transparent display demand across product type, application criticality, touch interface technology, and regional regulatory cluster throughout the forecast period. CAGRs derived from segment-level growth trajectory analysis incorporating automotive HUD penetration curves, smart retail deployment velocities, and microLED yield improvement timelines.
The analysis sits within stated boundaries; outcomes outside sustained K-Display funding levels or stable indium tin oxide supply flows would require recalibration. Forecasts reflect assumptions regarding mass transfer yield progression, automotive qualification cycle durations, and retail procurement centralization trends. Revision becomes warranted when microLED placement accuracy crosses 99.999% at production speeds or when EU RoHS substance restrictions expand to additional phosphor-based emitters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Automotive LCD Display Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
North America Industrial Display Market
Display Technologies
Global OLED Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Rugged Display Market
Display Technologies
Display Material Market
Display Technologies
United States Microdisplay Market
Display Technologies
LCD Panel Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Microdisplay Market
Display Technologies
QLED Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
Interactive Video Wall Market
Display Technologies
Thin Display Technology Market