
 Switchable Smart Film Market | 2026-2036
Switchable Smart Film Market Size, Share, and Industry Trends Forecast 2026-2036
Switchable Smart Film Market Intelligence
Electrochromic coating integration with low-emissivity glass substrates is fragmenting the traditional switchable film supply chain into module-level and component-level value pools. Intelligent Glass specializes in architectural privacy installations across European commercial developments. Madico, Inc. anchors the North American automotive glazing aftermarket with SPD-based solutions. 3M Company leverages its materials science portfolio to sustain R&D intensity across multiple electro-optic film chemistries.
Switchable smart film comprises electrically responsive multilayer laminates that modulate light transmission through applied voltage, thermal stimulus, or ambient conditions, typically incorporating indium tin oxide conductors with liquid crystal, suspended particle, or electrochromic active layers to achieve variable opacity states from transparent to opaque within seconds. Polymer Dispersed Liquid Crystal formulations dominate current architectural privacy glass volumes due to mature manufacturing economics, while Electrochromic Film commands premium positioning in energy-efficient windows where solar heat gain coefficient modulation drives utility savings. Suspended Particle Devices compete most aggressively in automotive glazing applications requiring rapid switching speeds under extreme temperature cycling.
Building codes under the EU Green Deal, Japan's METI efficiency standards, and China's GB rating system for curtain wall performance are converging to mandate dynamic solar control in new commercial construction above specified floor areas. The US Department of Energy window certification program and California Title 24 provisions further shape product qualification requirements for North American market access. Stakeholders must monitor evolving harmonization between regional energy labeling schemes and smart film interoperability standards to anticipate certification cost trajectories and specification gatekeeping dynamics.
Market Dynamics
Electrochromic coating integration with low-emissivity glass substrates is fragmenting the traditional switchable film supply chain into module-level and component-level value pools, forcing manufacturers to choose between vertical specialization and full-stack integration strategies.
Growth Catalysts
- EU Green Deal thermal mandates:Energy efficiency requirements under the EU Green Deal are compelling commercial developers to specify dynamic solar control glazing in new construction above threshold floor areas.
- China smart city infrastructure:Premium residential tower construction and municipal building retrofits in Chinese metropolitan clusters are absorbing significant polymer-dispersed liquid crystal film volumes.
- Suspended particle device automotive adoption:SPD technology is penetrating luxury vehicle glazing segments where rapid switching speed under thermal cycling provides measurable occupant comfort advantages.
Market Restraints
- Indium tin oxide supply concentration:ITO conductor deposition relies on concentrated rare earth processing capacity, creating input cost volatility exposure for electro-optic laminate manufacturers.
- Electrochromic film manufacturing scale limitations:Vacuum deposition throughput constraints and yield variability limit cost-down trajectories for energy-efficient window applications.
- Regional certification fragmentation:Divergent testing protocols between US Department of Energy window certification, California Title 24, and China's GB rating system inflate qualification costs for multi-territory product launches.
Strategic Opportunities
- India building efficiency codes:BIS energy conservation building code adoption creates first-mover positioning for dynamic glazing suppliers in commercial high-rise developments across Mumbai, Delhi, and Bangalore.
- Healthcare privacy retrofit demand:Hospital and clinic renovation cycles in Japan and South Korea are generating specification pull for instant-opacity partition systems replacing conventional blinds.
- Photovoltaic-integrated smart glass convergence:Building-integrated photovoltaics manufacturers are partnering with electrochromic film suppliers to develop self-powered tinting systems eliminating wired electrical infrastructure.
Industry Challenges
- Specialized coating technician scarcity:Vacuum deposition and liquid crystal alignment process expertise resides within a limited pool of trained operators, constraining production ramp rates for qualified manufacturers.
- Multi-certification timeline compression:Simultaneous pursuit of EU CE marking, US NFRC ratings, and China CCC approval creates resource allocation conflicts for product engineering teams.
- Legacy glazing contractor training gaps:Conventional glass installation networks lack electrical integration competency, slowing field deployment of wired smart film systems and elevating callback rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switchable Smart Film Market |
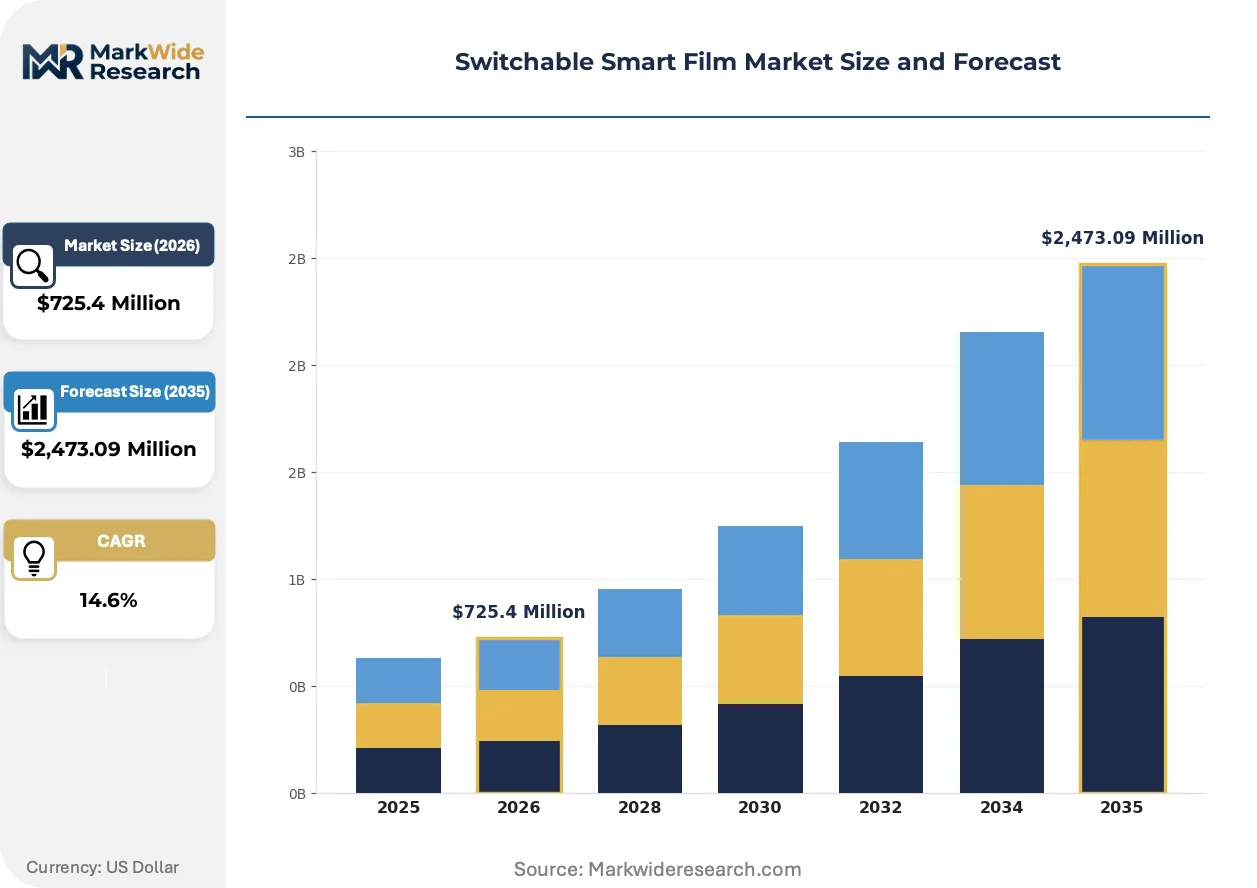
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $2,473.09 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Dispersed Liquid Crystal, Suspended Particle Devices, Electrochromic Film, Thermochromic Film, Microblinds Technology: Liquid Crystal Technology, SPD Technology, Electrochromic Technology, Suspended Particle Technology, Thermochromic Technology Application: Privacy Glass, Energy-efficient Windows, Projection Screens, Automotive Glazing, Partition Walls End User: Construction Contractors, Automotive Manufacturers, Media Production Companies, Interior Designers, Aerospace Integrators |
| Companies Covered | Intelligent Glass, Madico, Inc., Filmbase, Smart Tint, Johnson Window Films, Inc., 3M Company, Kehui, Guardian Industries, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switchable Smart Film Market Strategic Shifts & Innovations
Digital control architectures and wireless power delivery are transforming switchable film from passive glazing components into intelligent building envelope nodes, enabling centralized energy management and predictive maintenance capabilities.
Self-tinting electrochromic stacks incorporating photovoltaic harvesting layers are digitizing the window as an active grid-responsive asset. Large-scale commercial developers in Germany and the Netherlands are specifying these systems for net-zero building certifications. The technology is digitizing traditional static glazing procurement into dynamic envelope-as-a-service contracting models.
Japan's METI efficiency standards and South Korea's building energy codes are mandating dynamic solar control in new commercial construction above specified gross floor areas. These regulations are accelerating specification velocity for electrochromic and SPD solutions in curtain wall applications. Japanese general contractors are pre-qualifying smart film suppliers through integrated design-build contracts to ensure code compliance at project inception.
Healthcare and hospitality procurement teams are consolidating vendor relationships around full-service smart glass packages bundling installation, commissioning, and multi-year maintenance. This consolidation is displacing fragmented material-only purchasing through regional glass distributors. The shift is most pronounced in US acute care facility construction and UAE luxury hospitality developments where operational uptime guarantees drive supplier selection criteria.
Switchable Smart Film Market Segmentation
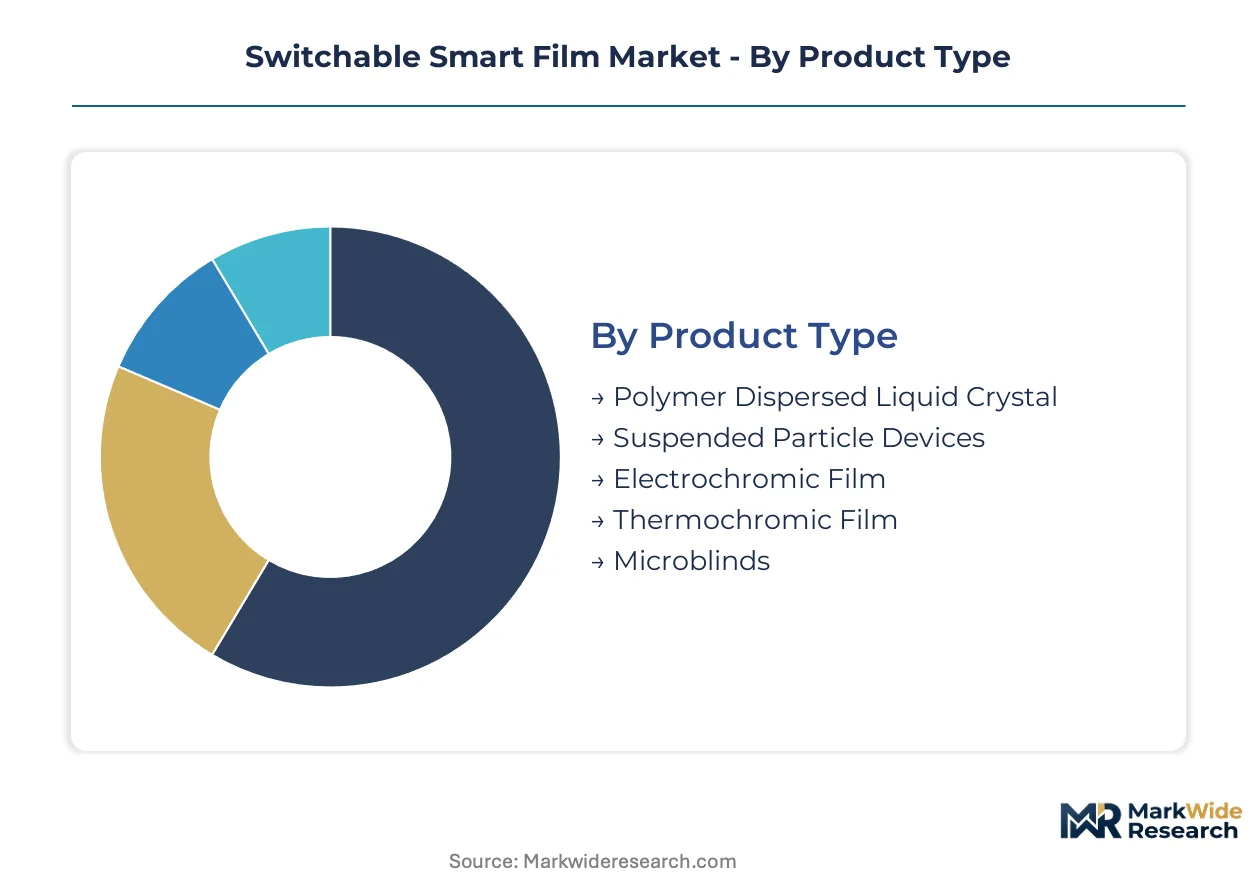
Segmentation in switchable smart film markets reveals divergent service intensity requirements across technology platforms. After-sales obligations vary sharply between architectural retrofit deployments demanding multi-year maintenance contracts and automotive OEM supply arrangements centered on warranty coverage.
Product Type:
After-sales service intensity correlates directly with film complexity and switching mechanism durability.
- Polymer Dispersed Liquid Crystal:Mature polymer matrix formulations align liquid crystal droplets within conductive substrates for instant opacity modulation. Construction contractors in China specify PDLC for premium residential tower privacy glass where rapid switching and manufacturing scale drive procurement economics.
- Suspended Particle Devices:Nanoparticle suspensions in organic gel matrices deliver sub-second switching speeds under thermal cycling extremes. SPD films penetrate luxury automotive glazing segments where KBA-certified suppliers meet German OEM durability specifications.
- Electrochromic Film:Solid-state ionic conductor stacks enable gradual tint transitions with superior energy performance. Vacuum deposition constraints limit production scale for building-integrated applications.
- Thermochromic Film:Passive temperature-responsive coatings eliminate electrical infrastructure requirements. Deployment concentrates in climate-responsive facade retrofits with minimal maintenance obligations.
- Microblinds:MEMS-actuated microscopic shutter arrays provide mechanical light modulation. Niche positioning in aerospace integrator specifications where electromagnetic interference resistance outweighs cost premiums.
Polymer Dispersed Liquid Crystal holds the largest share; momentum sits with Suspended Particle Devices.
Technology:
Cost tier stratification separates premium electrochromic stacks from commoditized liquid crystal laminates.
- Liquid Crystal Technology:Established alignment processes and roll-to-roll manufacturing enable competitive pricing for high-volume architectural privacy applications.
- SPD Technology:Proprietary nanoparticle formulation expertise creates supplier concentration in automotive glazing qualification programs.
- Electrochromic Technology:Multi-layer vacuum deposition of tungsten oxide and nickel oxide active layers commands premium positioning in EU Green Deal-compliant commercial developments.
- Suspended Particle Technology:Identical functional mechanism to SPD with alternative encapsulation approaches for aftermarket retrofit channels.
- Thermochromic Technology:Vanadium dioxide phase-change coatings respond to ambient thermal conditions without control systems. Limited addressable market in jurisdictions lacking dynamic glazing incentives.
Electrochromic Technology captures premium project value; Liquid Crystal Technology dominates volume deployment.
Application:
Application segmentation tracks divergent specification authority between owner-operators and design-build contractors.
- Privacy Glass:PDLC laminates switch from transparent to opaque within milliseconds for instant spatial reconfiguration. Hospital renovation cycles in Japan generate specification pull for healthcare partition retrofits replacing conventional blinds.
- Energy-efficient Windows:Electrochromic stacks modulate solar heat gain coefficients to reduce HVAC loads. Netherlands commercial developers specify these systems for net-zero building certifications.
- Projection Screens:Rear-projection surfaces leveraging switchable opacity for dual-use conference and presentation spaces. Corporate interior fit-out demand concentrates in UAE luxury hospitality developments.
- Automotive Glazing:SPD sunroofs and side windows penetrate luxury vehicle segments where occupant comfort differentiation justifies cost premiums.
- Partition Walls:Demountable office systems integrating smart film for flexible workspace configuration. US acute care facility construction drives vendor consolidation around full-service installation and commissioning packages.
Privacy Glass maintains established revenue concentration; Energy-efficient Windows are climbing the fastest on regulatory mandate expansion.
End User:
End user segmentation reflects procurement sophistication variance from commodity purchasing to engineered system integration.
- Construction Contractors:General contractors in Germany and Netherlands pre-qualify smart film suppliers through integrated design-build contracts ensuring code compliance at project inception.
- Automotive Manufacturers:German and Japanese OEMs impose thermal cycling and optical durability standards exceeding architectural specifications.
- Media Production Companies:Broadcast studio designers specify switchable projection surfaces for rapid set reconfiguration without physical infrastructure changes.
- Interior Designers:Specification influence in premium residential and hospitality segments where aesthetic integration drives material selection.
- Aerospace Integrators:EMI-resistant microblind systems for cabin window applications with extreme reliability requirements.
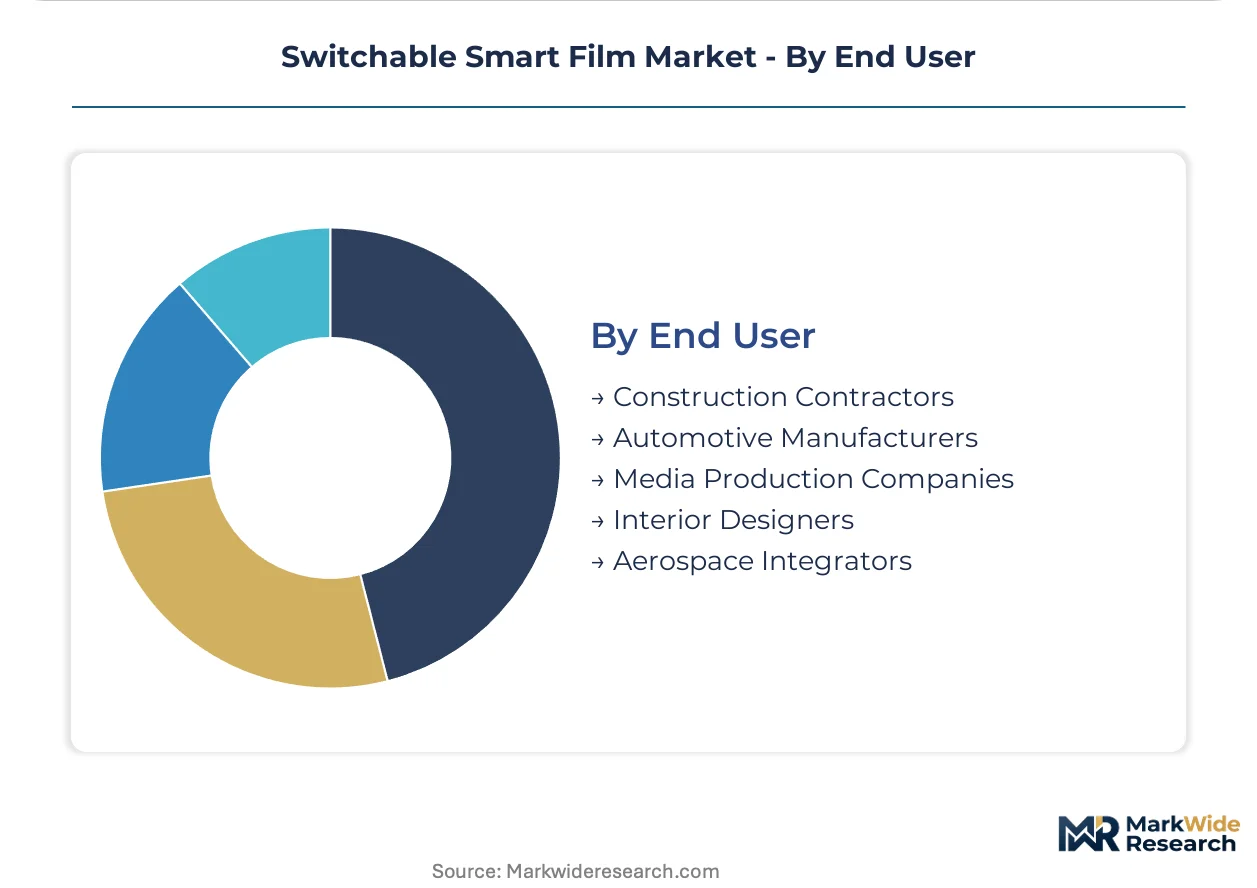
Construction Contractors represent the deepest specification penetration; Aerospace Integrators present the steepest expansion trajectory on emerging platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in switchable smart film track manufacturing concentration against regional demand intensity. China maintains net export dominance through integrated ITO deposition capacity, while Germany and the United States absorb premium electrochromic imports for commercial facade specifications.
China
Smart city infrastructure investments and premium residential tower construction in Shanghai, Shenzhen, and Beijing absorb substantial polymer-dispersed liquid crystal volumes. GB standards for curtain wall thermal performance mandate dynamic solar control in commercial developments above specified floor areas. The Yangtze River Delta manufacturing cluster hosts roll-to-roll coating facilities supplying domestic architectural retrofit demand.
Germany
Net-zero building certification requirements in commercial developments drive specification of electrochromic-integrated glazing systems. The EU Green Deal thermal performance mandates compel dynamic solar control adoption in new construction above threshold floor areas. KBA-certified suppliers in Bavaria and Baden-Württemberg serve luxury automotive OEM qualification programs for suspended particle device integration.
United States
California Title 24 provisions and Department of Energy window certification programs shape product qualification requirements for market access. Healthcare facility construction in Texas and Florida generates vendor consolidation around full-service smart glass installation packages. The Pacific Northwest hosts thin-film deposition specialists supplying electrochromic stack components.
Japan
Hospital and clinic renovation cycles in Tokyo and Osaka generate specification pull for instant-opacity partition systems replacing conventional blinds. METI efficiency standards mandate dynamic solar control in new commercial construction above specified gross floor areas. Kanto region general contractors pre-qualify smart film suppliers through integrated design-build contracts ensuring code compliance.
Netherlands
Commercial developers in Amsterdam and Rotterdam specify self-tinting electrochromic systems for net-zero building certifications. EU Green Deal energy efficiency requirements accelerate curtain wall specification velocity for dynamic glazing. The Randstad construction cluster integrates smart film procurement into envelope-as-a-service contracting models.
Switchable Smart Film Market Key Industry Players
On the supply side, the industry is structured around three distinct capability tiers. Materials science conglomerates with captive ITO deposition capacity occupy the upstream position. Specialized electro-optic laminate fabricators concentrate in the mid-tier, serving qualified installation networks. Component-level value pools attract regional glass processors seeking technology licensing arrangements. Dominant competitive moves include strategic partnerships between film suppliers and building-integrated photovoltaic manufacturers, plus capacity expansion in roll-to-roll coating lines for architectural volume segments.
Among UK-based specialists, Intelligent Glass exemplifies the architectural privacy installation archetype through European commercial development positioning. Madico, Inc. anchors the North American automotive glazing aftermarket archetype with SPD-based solution representation. 3M Company occupies the diversified materials science conglomerate tier, sustaining R&D intensity across multiple electro-optic film chemistries through its established industrial portfolio.
| Leading Market Players |
|---|
| Intelligent Glass |
| Madico, Inc. |
| Filmbase |
| Smart Tint |
| Johnson Window Films, Inc. |
| 3M Company |
| Kehui |
| Guardian Industries |
| Eastman Chemical Company |
| Others |
Cost & Logistics Intelligence
Indium tin oxide supply concentration in Chinese rare earth processing corridors determines both pricing tier spreads and supply chain shape, forcing electro-optic laminate manufacturers into long-term offtake commitments or captive sourcing investments to manage input cost volatility exposure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the switchable smart film market. Three-tier pricing structure across premium electrochromic stacks, standard PDLC laminates, and economy-grade thermochromic films reflects certification grade differentiation and after-sales service bundling. Cost compression in standard architectural privacy tiers is intensifying because roll-to-roll manufacturing scale advantages concentrate procurement leverage with Chinese construction contractors. Automotive glazing OEMs demonstrate least price sensitivity due to thermal cycling durability requirements and KBA qualification barriers.
Supply Chain Analysis
Roll-to-roll coating contract manufacturers in the Yangtze River Delta, Bavaria, and the US Pacific Northwest hold dominant electro-optic laminate fabrication capacity. The supply chain draws from indium tin oxide sputtering targets, liquid crystal monomers, and suspended particle gel matrices as critical inputs. Single-source vulnerability in ITO conductor deposition creates structural risk for manufacturers lacking backward integration into rare earth processing. Distribution runs through qualified glazing contractor networks requiring electrical integration competency certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal thermal mandate expansion fragments specification authority between energy consultants and design-build contractors, creating niche positioning opportunities for technology-specialist suppliers across multiple certification jurisdictions.
For Market Incumbents: Insulate module-level value capture by deepening captive ITO deposition capacity or securing exclusive rare earth offtake agreements with Chinese processors. Expand electrochromic stack production in Germany and the Netherlands to defend margin position against emerging PDLC commoditization from Yangtze River Delta manufacturers. For New Entrants and Emerging Players: Pursue healthcare privacy retrofit demand in Japanese hospital renovation cycles where instant-opacity partition specifications displace conventional blind suppliers. Target BIS energy conservation building code adoption curves in Indian commercial high-rise developments across Mumbai and Delhi through design-build contractor pre-qualification programs. For Investors and Strategic Acquirers: EU Green Deal implementation milestones reshape the acquisition landscape toward electrochromic technology suppliers with CE marking pathways and net-zero building certification track records. Viable targets include vacuum deposition specialists with tungsten oxide stack expertise and established relationships with Netherlands envelope-as-a-service contractors. Watch METI efficiency standard enforcement velocity in Japan as the inflection signal for Asian specification pull timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into ITO Deposition | Captive rare earth processing control insulates input cost volatility for electro-optic laminate manufacturers. |
| Healthcare Privacy Retrofit Specialization | Hospital renovation cycles in Japan generate specification pull for instant-opacity partition system suppliers. |
| Net-Zero Building Certification Alignment | Netherlands commercial developers specify self-tinting electrochromic stacks for envelope-as-a-service contracts. |
| Automotive OEM Qualification Expansion | KBA-certified suppliers in Bavaria serve German luxury vehicle glazing segments requiring thermal cycling durability. |
| Photovoltaic-Integrated Smart Glass Partnership | Building-integrated photovoltaics manufacturers partner with electrochromic film suppliers for self-powered tinting systems. |
Research Approach
A standing panel of glazing contractor procurement directors, electro-optic film R&D leads, architectural specification consultants, and building-integrated photovoltaics project developers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Green Deal implementation tracking, GB standards documentation, METI efficiency standard filings, and customs trade data for ITO sputtering target flows. Bottom-up volume modeling triangulated against top-down construction spend allocation across commercial high-rise and healthcare facility segments.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions modeled encompassed technology platform, application function, end-user procurement archetype, and regional regulatory framework cluster. CAGRs derived from installation volume trajectories weighted by technology-specific average selling price evolution, with electrochromic stack yield improvement curves and PDLC roll-to-roll throughput expansion as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates, rare earth export quota enforcement, and EU carbon border adjustment implementation would shift the trajectory. Cross-checking against building permit databases and curtain wall procurement pipeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Asia-Pacific MPU Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
Laser Technology Market