
 Ultra-Thin Solar Cells Market | 2026-2036
Ultra-Thin Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Thin Solar Cells Market Intelligence
Specialist manufacturing capacity in Europe and North America is broadening the supply base beyond traditional silicon PV hubs in Asia. Kaneka Corporation leverages its deep materials science expertise to produce highly flexible solar solutions for niche applications. First Solar sustains its market leadership through large-scale, cost-effective production of its proprietary CdTe thin-film modules. Hanwha Qcells competes across the value chain, offering a diverse portfolio that includes advanced thin-film and crystalline technologies.
Ultra-thin solar cells are photovoltaic devices with a light-absorbing layer measuring just a few micrometers thick, often deposited on flexible substrates. This construction allows for light weight and integration into unconventional surfaces like textiles, vehicles, and portable electronics where traditional panels are impractical. Perovskite technology represents the fastest-growing segment due to rapid efficiency gains and potential for low-cost, roll-to-roll manufacturing. Demand for building-integrated installations is also expanding, creating new applications for thin-film product types.
The EU's RoHS directive restricts hazardous materials, influencing the material science of CIGS and CdTe cells. In the United States, tax incentives under the IRA support domestic production, while China's dual carbon goals mandate greater renewable energy deployment. Stakeholders must now decide whether to prioritize investments in scaling nascent perovskite manufacturing or optimizing established thin-film production lines.
Market Dynamics
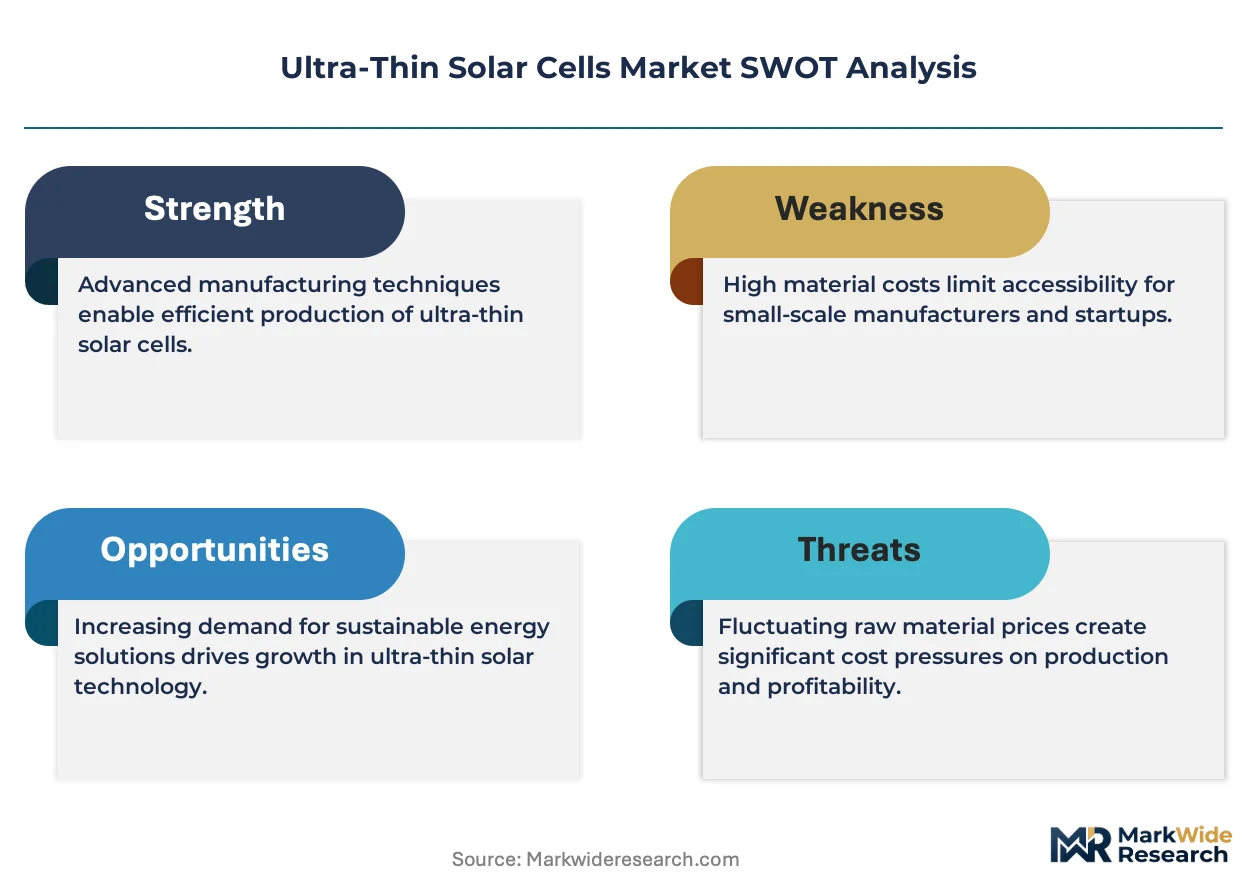
The central dynamic in the ultra-thin solar cell market is the strategic divergence between scaling nascent perovskite technologies and optimizing established thin-film production. This creates a critical investment decision for stakeholders, balancing perovskite's high-efficiency potential against the proven scalability and bankability of CdTe and CIGS technologies.
Growth Catalysts
- Portable Electronics Integration:Demand from consumer electronics and Internet of Things (IoT) sectors for lightweight, flexible power sources to extend battery life in wearables, sensors, and portable chargers accelerates product development.
- National Energy Mandates:Policies such as China's dual carbon goals and renewable energy portfolio standards in various countries mandate increased solar capacity, creating large-scale demand for building-integrated photovoltaics (BIPV).
- Perovskite Efficiency Gains:Continuous improvements in the power conversion efficiency of perovskite materials are unlocking new performance tiers, making them viable for applications previously dominated by traditional silicon PV.
Market Restraints
- Material Stability and Longevity:Perovskite solar cells exhibit degradation when exposed to moisture, oxygen, and heat, posing a significant barrier to long-term reliability and commercial bankability without advanced encapsulation.
- Hazardous Material Content:The presence of lead in high-efficiency perovskites and cadmium in CdTe cells faces regulatory scrutiny under frameworks like the EU's RoHS directive, restricting market access and requiring material science innovation.
- Input Material Scarcity:The supply of critical raw materials, including indium and gallium for CIGS cells or high-purity precursors for perovskites, can be volatile and concentrated in a few regions, creating price and supply risks.
Strategic Opportunities
- Vehicle-Integrated Photovoltaics (VIPV):The expansion of the electric vehicle market creates a significant opportunity for integrating flexible, lightweight solar cells into vehicle roofs, hoods, and body panels to extend range and power auxiliary systems.
- Domestic Manufacturing Incentives:Tax credits and manufacturing subsidies under the US Inflation Reduction Act (IRA) provide a strong financial incentive for establishing or expanding thin-film and perovskite production capacity in North America.
- Smart Textile and Wearable Power:Converging ultra-thin solar technology with flexible electronics and textiles enables the development of self-powered smart fabrics, medical sensors, and military gear, opening a new application frontier.
Industry Challenges
- Manufacturing Scalability:Transitioning promising lab-scale perovskite processes to high-volume, high-yield roll-to-roll manufacturing while maintaining cell efficiency and uniformity presents a major capital and engineering challenge.
- Standardization and Certification Gaps:The absence of universally accepted testing protocols and bankability standards for novel flexible and transparent solar technologies slows down adoption by conservative industries like construction and insurance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Thin Solar Cells Market |
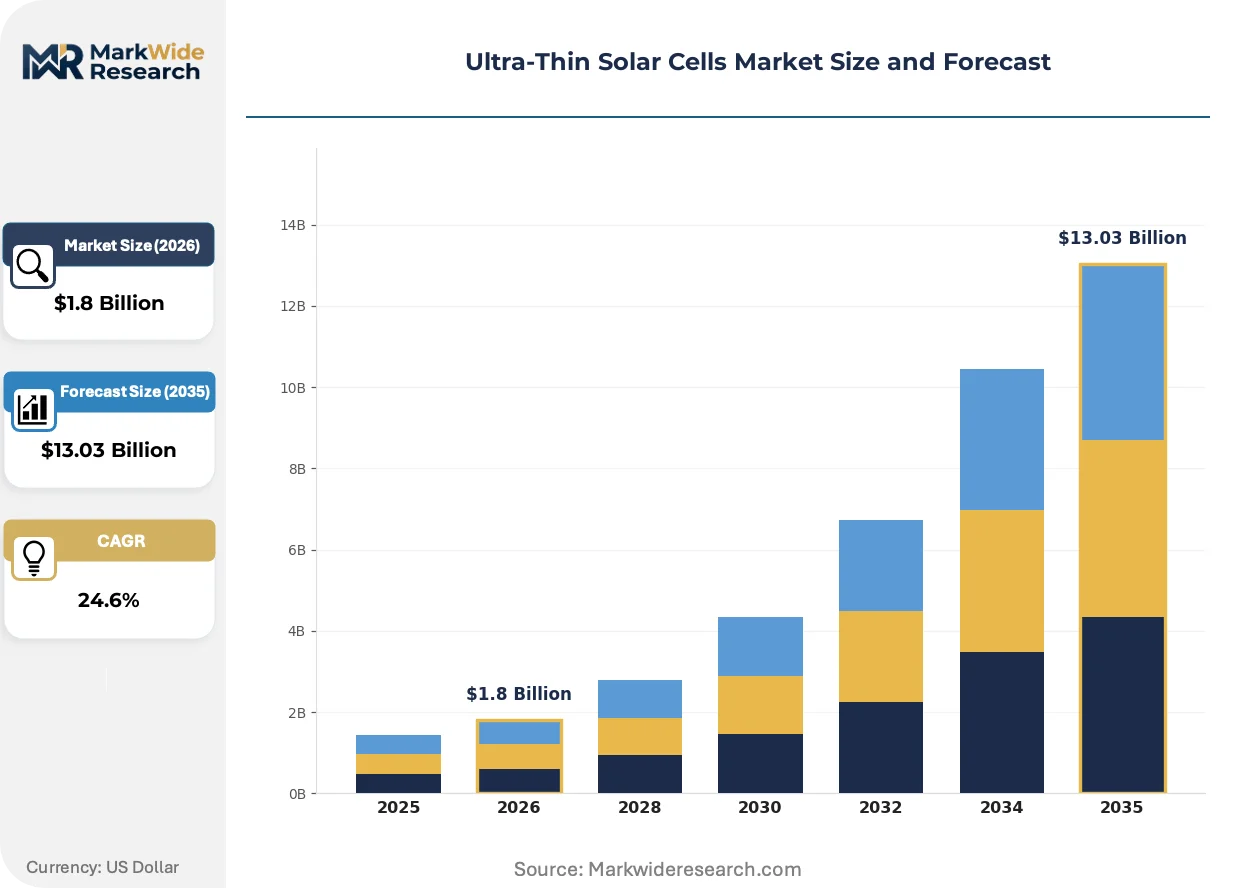
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Technology: CIGS, CdTe, Organic Photovoltaic, Perovskite End User: Residential, Commercial, Industrial, Utility Installation: Rooftop, Ground Mounted, Building Integrated, Portable |
| Companies Covered | First Solar, Ascent Solar Technologies, Kaneka Corporation, Hanwha Qcells, Oxford PV, Swift Solar, PowerFilm Solar, SunPower Corporation, MiaSolé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Thin Solar Cells Market Strategic Shifts & Innovations
Material science breakthroughs are colliding with industrial-scale manufacturing demands, forcing a re-evaluation of production economics and technology roadmaps. This dynamic is particularly evident as next-generation materials challenge incumbent thin-film chemistries for dominance in flexible and integrated applications.
Perovskite-on-silicon tandem cells combine a perovskite top layer with a traditional silicon base to capture a wider portion of the solar spectrum, boosting overall efficiency. High-value sectors like aerospace and specialized building-integrated photovoltaics are early adopters, pursuing maximum power generation per unit of area. This tandem approach is modularizing cell design, allowing manufacturers to upgrade existing silicon production lines instead of constructing entirely new factories for perovskite-only products.
Regulatory mandates like the European Union's RoHS directive directly influence material selection by restricting substances such as lead and cadmium. This forces manufacturers of lead-based perovskite and CdTe cells to either develop alternative, less-toxic formulations or invest in robust encapsulation to prevent leaching. Consequently, inherently compliant technologies like organic photovoltaics (OPV) and CIGS gain a competitive advantage within the large European market.
Demand from end-users in architecture and product design is shifting from procuring discrete solar modules to specifying fully integrated, power-generating surfaces. This pattern disrupts traditional distribution channels, fostering direct collaboration between cell manufacturers and the designers of buildings, vehicles, and electronic devices. The trend is most pronounced in the European BIPV sector and within Asia's consumer electronics design hubs.
Ultra-Thin Solar Cells Market Segmentation
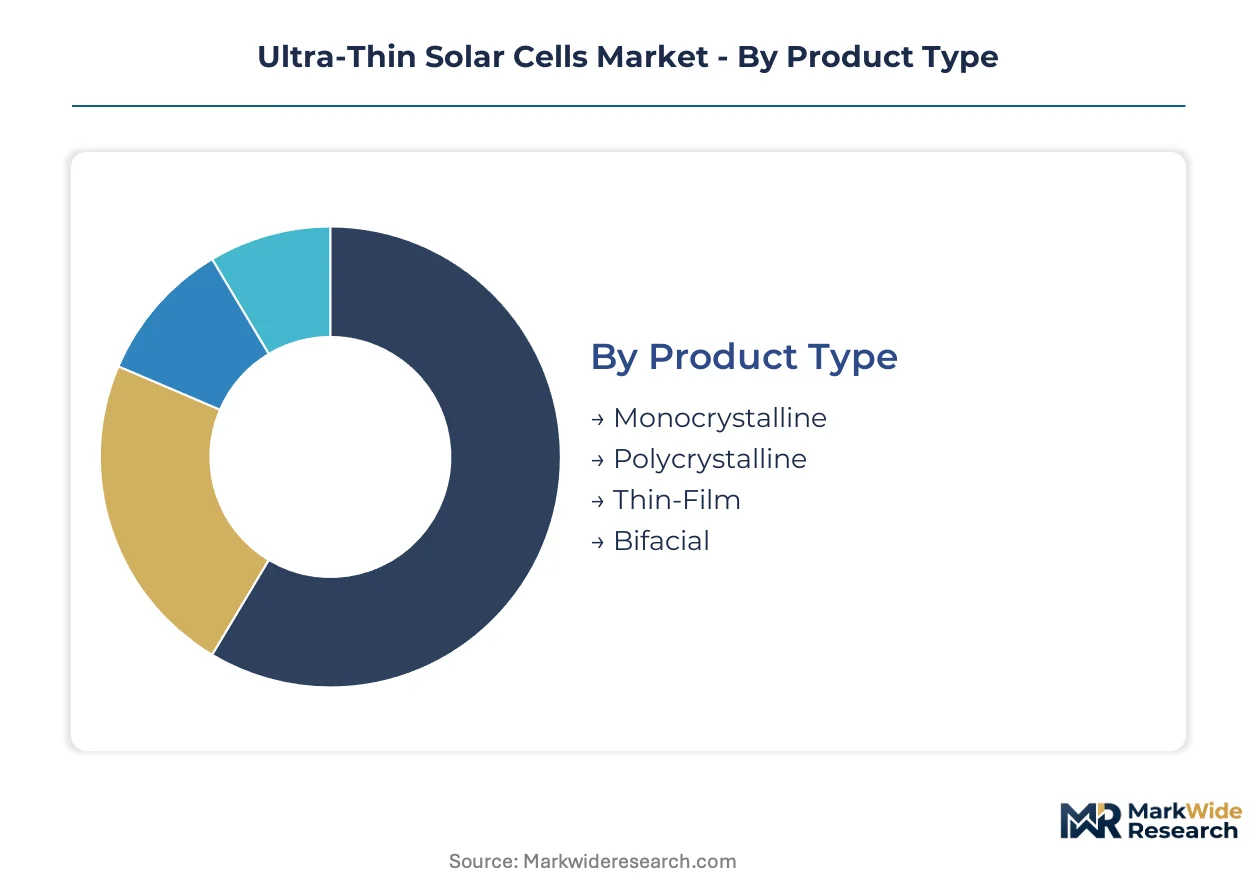
Understanding the segmentation of the ultra-thin solar cells market is crucial for stakeholders to identify specific growth vectors and investment priorities. Different product types, technologies, end-users, and installation methods dictate varying performance requirements and commercialization strategies. This detailed breakdown illuminates where innovation and demand converge.
Product Type:
The product type segmentation highlights the spectrum from highly standardized, mature offerings to specialized, customizable solutions tailored for specific applications.
- Monocrystalline:These cells are made from a single, continuous crystal structure, offering high efficiency and a uniform appearance.
- Polycrystalline:Composed of multiple silicon crystals, polycrystalline cells are less efficient but more cost-effective to produce.
- Thin-Film:Characterized by light-absorbing layers just micrometers thick, these cells are flexible and lightweight, enabling integration into unconventional surfaces. Demand accelerates in portable electronics and building-integrated photovoltaics within China, driven by consumer preference for sleek, integrated power solutions.
- Bifacial:These modules capture sunlight from both their front and rear sides, significantly boosting energy yield, especially when installed over reflective surfaces. Utility-scale projects in the US are adopting bifacial technology to maximize power output per land area, supported by federal tax incentives.
Most installed capacity flows through Polycrystalline products. Expansion is steepest in Bifacial technologies.
Technology:
Technology segmentation reflects the maturity curve of various material science innovations, from established chemistries to nascent, high-potential compounds.
- CIGS:Copper Indium Gallium Selenide (CIGS) cells are known for their high efficiency among thin-film technologies.
- CdTe:Cadmium Telluride (CdTe) cells offer a cost-effective manufacturing process and strong performance in hot, humid climates, making them ideal for large-scale solar farms. First Solar sustains its market leadership with CdTe modules in the United States, benefiting from economies of scale.
- Organic Photovoltaic:OPVs use organic polymers as the active material, offering extreme flexibility, transparency, and customizable colors.
- Perovskite:These next-generation materials offer rapid efficiency gains and potential for low-cost, roll-to-roll manufacturing, challenging incumbent technologies. China's electronics industry is investing heavily in perovskite research for flexible power sources, aiming for manufacturing scalability.
CdTe dominates established applications. Perovskite is gaining share fastest.
End User:
The end-user segmentation reveals distinct demand patterns and purchasing behaviors across different sectors, influencing product design and deployment strategies.
- Residential:This segment includes solar installations on individual homes, primarily for self-consumption and reducing electricity bills.
- Commercial:Commercial end-users encompass businesses, offices, and retail establishments seeking to lower operating costs and achieve sustainability targets. Building-integrated photovoltaics in the European Union are gaining traction for commercial properties driven by EU Green Deal mandates.
- Industrial:Industrial applications involve large-scale energy consumption for manufacturing plants and heavy industry, requiring robust and reliable power solutions.
- Utility:The utility sector deploys vast solar farms to generate electricity for the national grid, emphasizing cost-effectiveness and long-term reliability. Large-scale projects in the United States benefit from tax incentives under the IRA, supporting significant renewable energy deployment.
Demand for Utility installations drives significant volume. Commercial presents high-value opportunities.
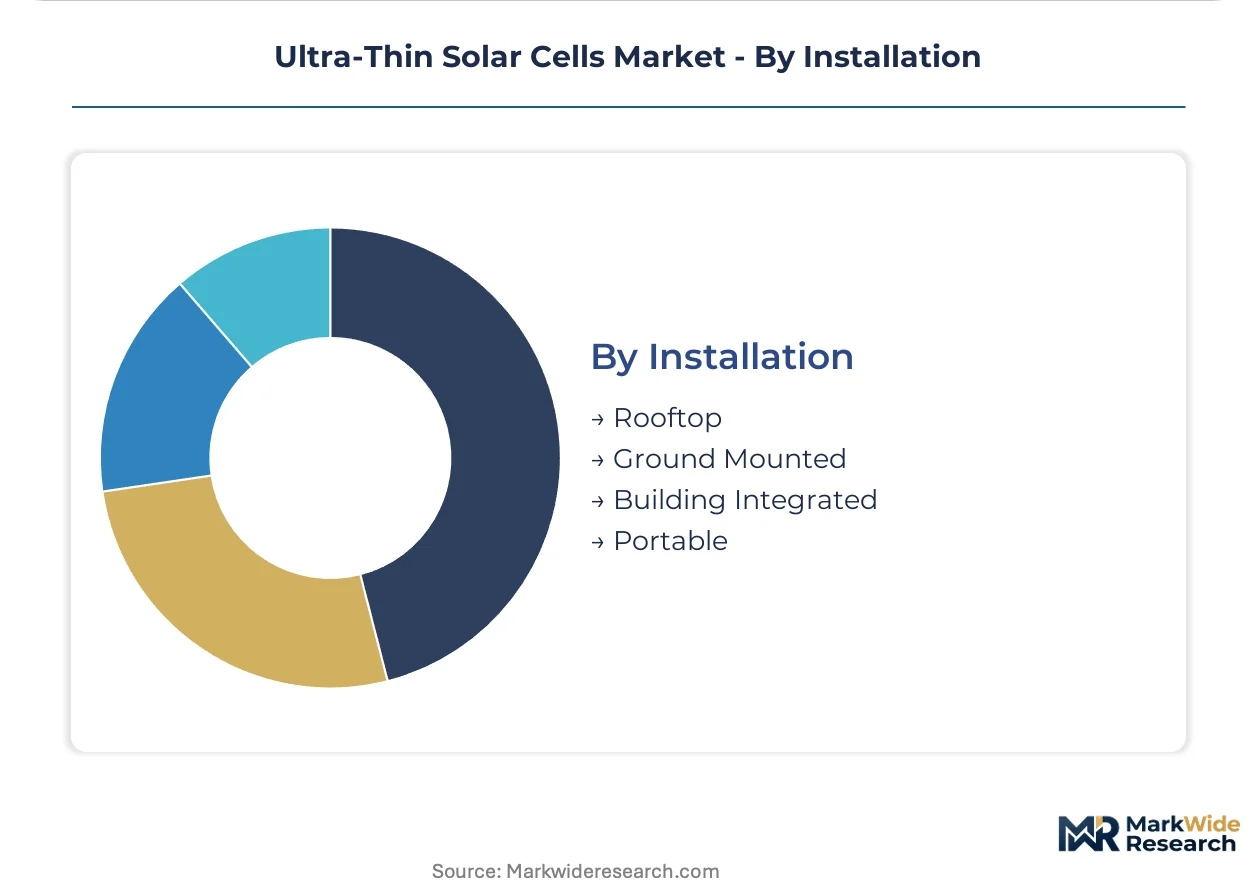
Installation:
Installation methods differentiate how ultra-thin solar cells are physically integrated, from fixed structures to mobile and embedded solutions.
- Rooftop:Solar panels installed on the roofs of residential, commercial, and industrial buildings to generate localized power.
- Ground Mounted:These installations involve large arrays of solar panels fixed to the ground, typically for utility-scale power generation.
- Building Integrated:BIPV solutions replace conventional building materials with solar cells, serving both aesthetic and power generation functions. New architectural designs in Europe increasingly feature BIPV elements to meet stringent energy efficiency standards.
- Portable:This category includes small, lightweight solar cells designed for mobile applications, such as charging consumer electronics or powering remote sensors. The Internet of Things sector globally drives demand for portable solar solutions for off-grid devices.
Rooftop accounts for the largest installed base. Portable is experiencing rapid growth in niche markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rapid expansion in manufacturing capacity contrasts with the United States' emphasis on domestic production incentives for ultra-thin solar cells. European markets prioritize stringent environmental compliance, shaping material science innovations for sustainable photovoltaic solutions. Japan maintains a strong focus on advanced materials research for high-efficiency applications.
United States
Demand for utility-scale bifacial projects is substantial, driven by the need for maximum energy yield. The US Inflation Reduction Act (IRA) provides significant tax credits for domestic solar manufacturing and deployment. California and Texas lead in large-scale solar farm development, integrating advanced thin-film modules across vast land areas.
China
Portable electronics integration and building-integrated photovoltaics drive significant demand for flexible solar solutions. China's dual carbon goals mandate greater renewable energy deployment across industrial and residential sectors. Manufacturing hubs in Jiangsu and Guangdong concentrate production, aiming for perovskite manufacturing scalability and cost reduction.
Germany
Commercial building-integrated photovoltaics are gaining traction for sustainability targets and energy efficiency mandates. The EU's RoHS directive directly influences material selection, restricting hazardous substances like lead and cadmium. Bavaria and North Rhine-Westphalia house research institutes and specialized manufacturers for advanced PV technologies.
Japan
High-value sectors like aerospace and specialized building-integrated photovoltaics drive demand for maximum power generation per unit area. METI promotes research and development in advanced materials for next-generation solar cells, including perovskite technology. Tokyo and Osaka host key electronics and materials science clusters, focusing on perovskite-on-silicon tandem cell development.
India
National energy mandates and renewable energy portfolio standards create large-scale demand for solar capacity across the country. The PLI scheme encourages domestic manufacturing of solar PV modules and cells, fostering local industry growth. Gujarat and Rajasthan are central to utility-scale solar projects, deploying cost-effective thin-film technologies for grid integration.
Ultra-Thin Solar Cells Market Key Industry Players
Asian producers anchor one tier, emphasizing high-volume manufacturing and cost efficiency for global distribution channels. European and North American specialists hold another, focusing on niche applications and advanced material science for integrated solutions. The market exhibits a tiered structure, with established thin-film manufacturers coexisting with innovative perovskite developers. Companies pursue portfolio diversification and strategic partnerships to navigate technological shifts and expand their geographic footprints.
Established thin-film module producers, such as First Solar, exemplify the focus on large-scale, cost-effective production of proven technologies like CdTe, serving utility-scale projects. Japan-based Kaneka Corporation represents deep materials science expertise, developing highly flexible solar solutions for specialized applications in niche markets. Hanwha Qcells, a diversified energy company, occupies a position across the value chain, offering a broad portfolio that includes both advanced thin-film and crystalline technologies to address various end-user segments.
| Leading Market Players |
|---|
| First Solar |
| Ascent Solar Technologies |
| Kaneka Corporation |
| Hanwha Qcells |
| Oxford PV |
| Swift Solar |
| PowerFilm Solar |
| SunPower Corporation |
| MiaSolé |
| Others |
Cost & Logistics Intelligence
The EU's RoHS directive influences material science choices for ultra-thin solar cells, forcing suppliers to innovate with compliant formulations. This shift impacts production costs and pricing, favoring inherently compliant technologies.
Pricing Analysis
Direct-to-OEM discounts characterize pricing for integrated ultra-thin solar cells in sectors like automotive and building-integrated photovoltaics. The dominant pricing model is project-based for large installations, shifting to per-unit transactional for consumer electronics. Price differentiation stems from power conversion efficiency, material compliance, and customization level. Pricing softness reflects manufacturing scale for established technologies, while early-stage perovskites command a premium; utility buyers are highly price-sensitive, contrasting with niche aerospace applications valuing performance.
Supply Chain Analysis
Single-source vulnerability sits with critical raw materials like indium and gallium for CIGS cells, and high-purity precursors for perovskites. Supply concentrates heavily in China for general manufacturing, while the United States anchors CdTe production. Regulatory restrictions, such as the EU's RoHS directive on cadmium, present a significant supply chain risk. Distribution runs through direct channels for large-scale BIPV and portable electronics integrators, alongside specialized distributors for niche markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultra-thin solar cells market represents a late-cycle quality story, driven by a demand-shift towards premium, integrated power solutions in building-integrated photovoltaics. End-users increasingly prioritize aesthetics, efficiency, and seamless integration over basic cost per watt.
For Market Incumbents: Deepen materials science expertise to address perovskite stability challenges and develop lead-free formulations, mitigating RoHS regulatory scrutiny. Consolidate market share by expanding cost-effective CdTe production capacity in North America, leveraging IRA incentives. Invest in advanced encapsulation technologies to extend product longevity. Secure long-term supply agreements for critical raw materials to ensure production continuity against input scarcity.
For New Entrants and Emerging Players: The US Inflation Reduction Act (IRA) in the United States opens a window for new entrants to establish domestic thin-film and perovskite manufacturing capacity. Target white-space opportunities in vehicle-integrated photovoltaics and smart textiles, where flexibility and light weight are paramount. The portable electronics segment offers a penetrable entry point due to demand for flexible power sources. Pursue direct collaboration with product designers and architects, emphasizing custom integration and aesthetic value.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized materials science firms possessing proprietary perovskite formulations or advanced encapsulation technologies. Long-term viability, over the next decade, hinges on scalable manufacturing and proven product longevity in demanding environments. Target acquisition profiles include companies with intellectual property in lead-free perovskites or roll-to-roll production processes. The signal to watch is the successful completion of bankability standards and certification for novel flexible solar products.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Manufacturing Scale-Up | Accelerates commercialization of high-efficiency cells, challenging incumbent thin-film technologies for market share. |
| Advanced Encapsulation R&D | Improves perovskite cell longevity, addressing critical stability concerns for long-term deployment and bankability. |
| BIPV Product Co-Development | Fosters direct collaboration with architects and developers, integrating solar cells into new building designs. |
| Domestic Production Capacity Expansion | Leverages tax incentives under the US Inflation Reduction Act, boosting regional supply chain resilience. |
| Lead-Free Material Innovation | Ensures compliance with strict regulations like the EU's RoHS directive, expanding market access in Europe. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. We conducted interviews with R&D directors, manufacturing plant managers, BIPV architects, and utility procurement officers. Secondary data sources included SEC filings, academic literature on perovskite technology, government energy reports, and industry trade publications. This approach ensured comprehensive bottom-up and top-down triangulation of market data.
The segment-weighting approach integrated product type, technology, end-user, and installation method dimensions across the modeling period. Our analytical framework derived compound annual growth rates from historical trends, projected technology adoption curves, and policy impact assessments. Key forecast inputs included perovskite efficiency milestones and building-integrated photovoltaics integration rates. This provided a granular view of market evolution throughout the forecast period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid regulatory shifts or unforeseen material science breakthroughs. Forecasts reflect assumptions regarding technology commercialization and policy enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Asia-Pacific MPU Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Deep Tech Market