
 Asia Pacific Wigig Market | 2026-2036
Asia Pacific Wigig Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Wigig Market Analysis
Enterprise wireless backhaul is expanding faster than residential deployments across the Asia Pacific Wigig Market. Qualcomm Technologies anchors its position through upstream control over 802.11ad/ay baseband silicon design. Intel Corporation sustains R&D intensity in integrated radio solutions for enterprise access points. Broadcom Inc. dominates merchant switch silicon that feeds Wigig-enabled network fabrics.
Asia Pacific Wigig denotes 60 GHz millimeter-wave wireless technology operating in the unlicensed 57-71 GHz range, delivering multi-gigabit throughput over short distances through beamforming antenna arrays. It primarily serves high-density indoor connectivity, low-latency VR streaming, and cable-replacement backhaul in commercial environments. Access points and routers capture the largest hardware revenue pools, while adapters represent the fastest-growing product category as legacy devices require bridge connectivity. Enterprise end users generate the steepest demand trajectory, though education and healthcare verticals are accelerating procurement for wireless display and imaging applications.
Japan's Ministry of Internal Affairs and Communications governs 60 GHz spectrum licensing, while South Korea's Radio Research Agency enforces equipment certification for Wigig devices deployed in smart manufacturing zones. China's MIIT coordinates GB standards alignment with international 802.11ay specifications, shaping import compliance for foreign chipset vendors. Stakeholders must monitor evolving national spectrum harmonization decisions that determine cross-border product interoperability and certification cost structures.
Market Dynamics
Enterprise wireless backhaul demand in South Korea and Japan is compressing deployment timelines, forcing chipset vendors to accelerate 802.11ay certification cycles while spectrum harmonization debates across MIC, RRA, and MIIT reshape cross-border equipment flows.
Growth Catalysts
- Japan's MIC 60 GHz spectrum liberalization:The Ministry of Internal Affairs and Communications expanded unlicensed band access, enabling higher-density access point deployments in Tokyo and Osaka commercial corridors.
- South Korean smart manufacturing zones:Semiconductor fabrication facilities in Gyeonggi Province are deploying Wigig for low-latency equipment monitoring, creating anchor demand for 802.11ay infrastructure.
- Beamforming antenna miniaturization:Phased-array module cost curves are steepening, reducing radio unit bill-of-materials for enterprise access point manufacturers serving education and healthcare verticals.
Market Restraints
- Silicon supply concentration:Baseband SoC fabrication depends on a narrow set of advanced-node foundries concentrated in Taiwan, exposing procurement timelines to geopolitical friction.
- Range-versus-throughput tradeoff:60 GHz signal attenuation through physical barriers limits Wigig to single-room or line-of-sight deployments, constraining campus-scale network architectures.
- China's MIIT certification complexity:GB standards alignment with 802.11ay specifications creates extended type-approval timelines for foreign chipset vendors seeking mainland market access.
Strategic Opportunities
- India's industrial corridor digitization:Tamil Nadu and Karnataka manufacturing clusters lack dense fiber infrastructure, creating white space for wireless backhaul solutions in automotive and electronics assembly plants.
- Healthcare imaging unification:Australian and Singaporean hospital networks are piloting Wigig for uncompressed 4K surgical video transport, opening premium equipment procurement channels.
- Wi-Fi 7 convergence architectures:Dual-radio access points integrating 6 GHz and 60 GHz bands are enabling seamless handoff protocols for mixed-device enterprise environments.
Industry Challenges
- Millimeter-wave RF engineering scarcity:Phased-array calibration and beam-tracking algorithm development require specialized talent pools concentrated in Seoul, Tokyo, and Hsinchu, constraining vendor R&D scaling.
- Legacy Ethernet integration complexity:Enterprise IT departments face protocol-stack mismatches when bridging Wigig radios into existing 10G/25G switch fabrics, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Wigig Market |
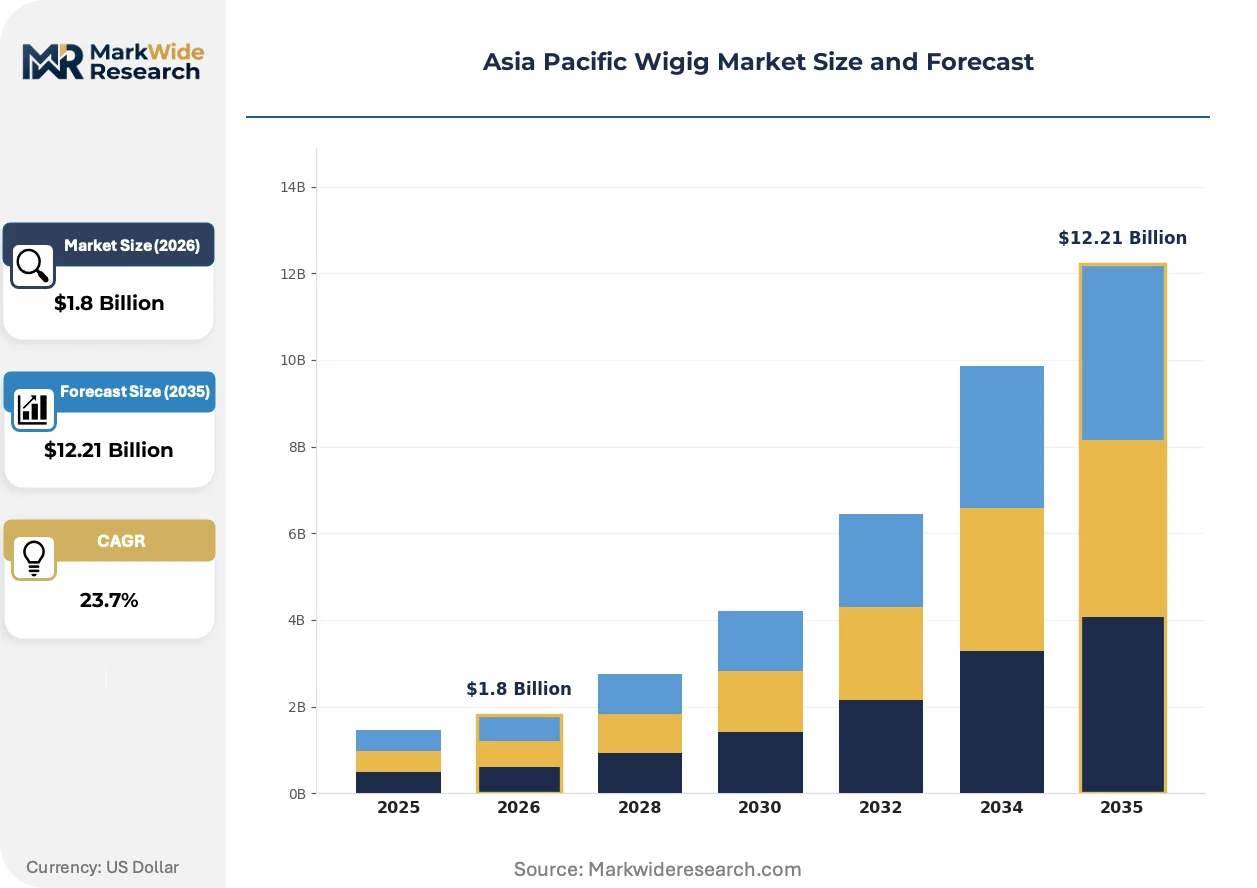
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Points, Adapters, Routers, Switches Use Case: High-Definition Streaming, Virtual Reality, Gaming, Smart Homes End User: Enterprise, Residential, Education, Healthcare Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Qualcomm Technologies, Inc., Intel Corporation, Broadcom Inc., MediaTek Inc., Panasonic Corporation, Huawei Technologies Co., Ltd., Fujikura Ltd, ASUSTeK Computer Inc., Samsung Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Wigig Market Emerging Trajectories
Beamforming silicon integration and spectrum policy coordination are compressing equipment form factors while expanding addressable use cases beyond traditional cable-replacement scenarios.
802.11ay baseband SoCs with integrated MAC-layer processing are electrifying enterprise access point designs, enabling single-chip solutions that previously required discrete RF and baseband components. Network equipment manufacturers in South Korea and Japan are absorbing these designs at accelerated cadences. The technology is electrifying price-performance benchmarks across indoor backhaul segments, pressuring merchant silicon vendors to consolidate roadmap investments.
South Korea's Radio Research Agency has tightened electromagnetic compatibility certification requirements for 60 GHz devices deployed in smart factory environments, extending pre-market testing timelines by several months. Industrial automation integrators now face additional documentation burdens when importing Wigig-enabled sensors. Semiconductor vendors are responding by establishing captive testing facilities in Gyeonggi Province to compress RRA approval cycles.
Hospital procurement committees across Australia and Singapore are unbundling wireless display infrastructure from traditional AV vendor contracts, creating direct purchasing relationships with enterprise networking specialists. Systems integrators that historically dominated healthcare IT deployments are losing equipment specification control. This behavioral shift is most visible in Melbourne and Sydney hospital network tenders, where technical evaluation criteria now prioritize 802.11ay latency specifications over incumbent vendor relationships.
Asia Pacific Wigig Market Segmentation
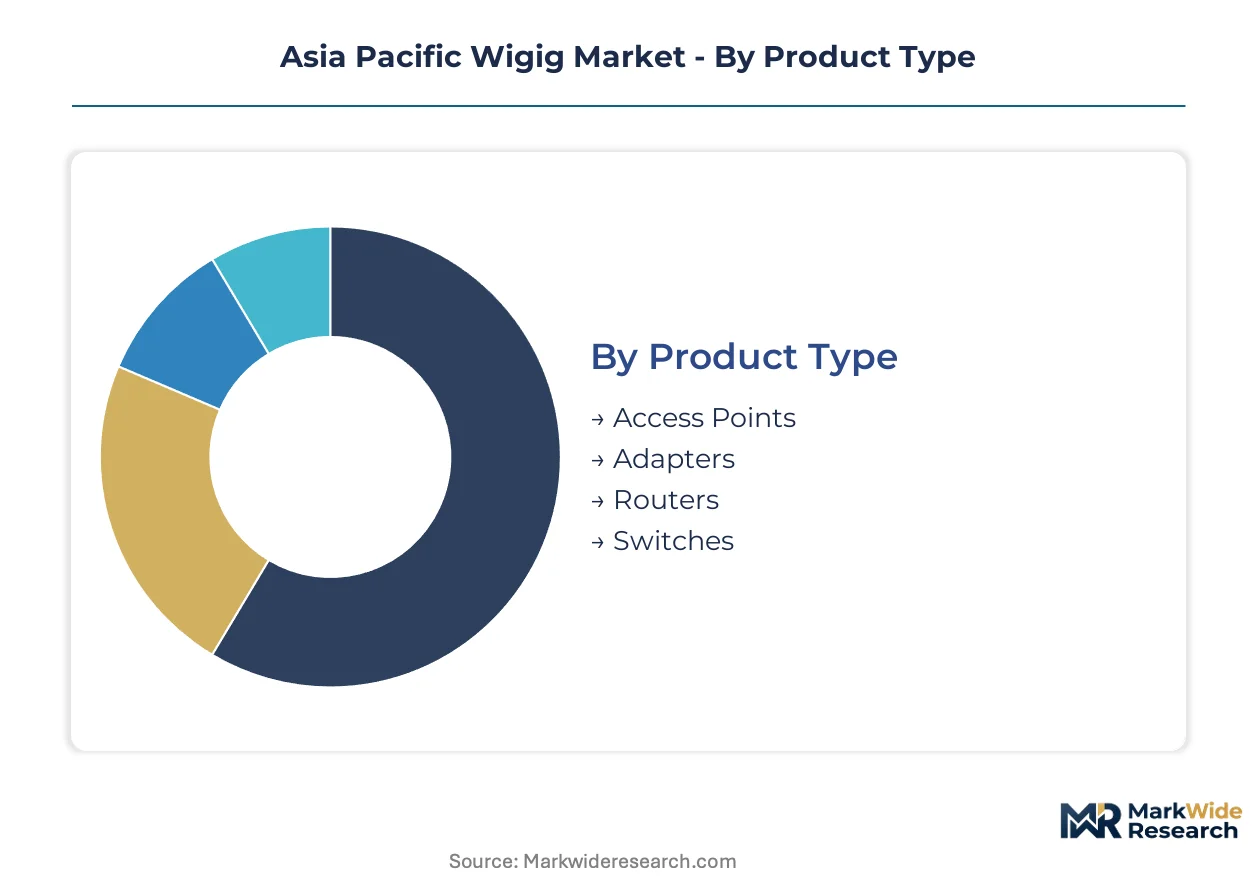
Wigig market segmentation reveals divergent procurement patterns across hardware categories, use intensities, and operational environments. Buyers prioritize throughput specifications, deployment complexity, and integration with existing network fabrics when selecting 60 GHz solutions across the Asia Pacific region.
Product Type:
Cost tier differentiation separates enterprise-grade infrastructure from consumer bridge hardware, with procurement committees weighing total cost of ownership against performance benchmarks.
- Access Points:Enterprise-grade 802.11ay radios with integrated phased-array antennas serve as anchor infrastructure for high-density indoor deployments. Demand concentrates in Tokyo and Osaka commercial corridors following Japan's MIC spectrum liberalization, with procurement timelines compressing as facility managers replace legacy 802.11ad installations.
- Adapters:USB and PCIe bridge devices enable legacy equipment connectivity without full infrastructure replacement. South Korean semiconductor fabrication facilities in Gyeonggi Province are accelerating adapter procurement to retrofit existing monitoring equipment for low-latency Wigig backhaul.
- Routers:Integrated gateway devices combining 60 GHz millimeter-wave with sub-6 GHz fallback bands for residential and small-office environments.
- Switches:Merchant silicon-based fabric equipment feeding Wigig-enabled network backbones in enterprise data centers.
Volume sits with Access Points; growth tilts toward Adapters.
Use Case:
Application intensity determines antenna configuration requirements and beamforming algorithm sophistication across deployment scenarios.
- High-Definition Streaming:Uncompressed 4K video transport demands sub-millisecond latency and sustained multi-gigabit throughput. Australian hospital networks in Melbourne and Sydney are piloting surgical video distribution systems with direct procurement from enterprise networking specialists.
- Virtual Reality:Tethered VR systems require consistent 7 Gbps+ throughput to eliminate motion-to-photon latency. Education technology procurement committees across Singapore are specifying 802.11ay latency benchmarks for immersive learning laboratory installations.
- Gaming:Low-latency competitive multiplayer environments drive consumer-grade router demand in South Korean metropolitan markets.
- Smart Homes:Whole-home audio-visual distribution and IoT sensor backhaul in high-density residential complexes.
Procurement volume clusters in High-Definition Streaming; Virtual Reality claims the steepest expansion trajectory as education and healthcare verticals accelerate specification.
End User:
Customer type dictates integration complexity, with enterprise IT departments demanding managed service overlays that residential buyers typically bypass.
- Enterprise:Campus-scale deployments requiring centralized network management and 10G/25G switch fabric integration. Semiconductor manufacturing corridors across South Korea and Japan are compressing deployment timelines for smart factory wireless backhaul.
- Residential:Consumer-grade equipment for cable-replacement and high-bandwidth home networking in urban apartment complexes.
- Education:Immersive learning laboratory infrastructure with specific latency requirements for VR content delivery.
- Healthcare:Wireless display and uncompressed imaging systems for surgical and diagnostic applications.
Enterprise captures dominant procurement volume; Healthcare is gaining share fastest as Australian and Singaporean hospital networks unbundle AV infrastructure from traditional vendor contracts.
Deployment:
Operational model selection reflects internal IT capability maturity and preference for capital expenditure versus operational expenditure structures.
- On-Premise:Customer-owned infrastructure with direct hardware procurement and internal management. Dominates in South Korean smart manufacturing zones where data sovereignty requirements preclude cloud-dependent architectures.
- Cloud-Based:Centralized controller platforms enabling multi-site policy management and over-the-air firmware updates.
- Hybrid:Split architectures with local radio units and cloud-orchestrated management planes for distributed enterprises.
- Managed Services:Third-party operation and maintenance contracts with service-level agreement guarantees.
On-Premise retains volume leadership; Managed Services is climbing the fastest as healthcare and education verticals outsource RF engineering complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi Province's semiconductor special economic zones concentrate Wigig infrastructure procurement, while Japan's MIC spectrum liberalization and China's MIIT certification frameworks reshape equipment deployment patterns across the Asia Pacific region.
Japan
Enterprise wireless backhaul demand from Tokyo and Osaka commercial corridors drives access point procurement acceleration. MIC's 60 GHz unlicensed band expansion enables higher-density deployments without individual licensing requirements. Kansai manufacturing clusters are retrofitting legacy 802.11ad installations with 802.11ay infrastructure to support smart factory connectivity.
South Korea
Semiconductor fabrication facilities in Gyeonggi Province require low-latency equipment monitoring through Wigig-enabled sensor networks. RRA tightened electromagnetic compatibility certification requirements, extending pre-market testing timelines for industrial automation integrators. Samsung Electronics anchors domestic supply chains while captive testing facilities compress RRA approval cycles in Pangyo Techno Valley.
China
GB standards alignment with 802.11ay specifications shapes import compliance for foreign chipset vendors seeking mainland market access. MIIT coordinates national spectrum harmonization decisions that determine cross-border product interoperability. Yangtze River Delta electronics manufacturing hubs face extended type-approval timelines, constraining deployment velocity for enterprise networking specialists.
Australia
Hospital networks in Melbourne and Sydney unbundle wireless display infrastructure from traditional AV vendor contracts, creating direct procurement relationships with enterprise networking specialists. TGA medical device regulations intersect with telecommunications certification for surgical video transport systems. Healthcare procurement committees now prioritize 802.11ay latency specifications over incumbent vendor relationships in tender evaluations.
Singapore
Education technology procurement committees specify 802.11ay latency benchmarks for immersive learning laboratory installations. Infocomm Media Development Authority coordinates 60 GHz spectrum policy with enterprise deployment incentives. Research-intensive districts around One-North and Jurong Innovation District concentrate pilot programs for uncompressed 4K video distribution in medical and educational settings.
Asia Pacific Wigig Market Vendor Landscape
Top-tier vendors anchor baseband silicon design, while merchant switch fabric specialists and integrated radio solution providers occupy differentiated competitive positions. The vendor base stratifies across three archetypes: upstream semiconductor designers controlling 802.11ad/ay protocol stacks, network equipment manufacturers absorbing reference designs, and systems integrators managing enterprise deployment complexity. Competitive moves concentrate on R&D intensity acceleration and captive testing facility establishment to compress certification timelines.
Among US-based semiconductor architects, Qualcomm Technologies, Inc. and Intel Corporation exemplify the upstream control archetype over millimeter-wave baseband silicon. Broadcom Inc. occupies a distinct position in merchant switch silicon that feeds Wigig-enabled network fabrics. These three entities represent the foundational layer upon which Asia Pacific equipment manufacturers build differentiated access point and adapter portfolios.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| Intel Corporation |
| Broadcom Inc. |
| MediaTek Inc. |
| Panasonic Corporation |
| Huawei Technologies Co., Ltd. |
| Fujikura Ltd |
| ASUSTeK Computer Inc. |
| Samsung Electronics |
| Others |
Supply Flow & Price Mechanics
802.11ay baseband SoC integration into single-chip designs is collapsing radio unit manufacturing costs while simultaneously concentrating procurement leverage among enterprise access point manufacturers in Tokyo and Osaka. This technology transition rewards vendors with captive testing facilities and punishes those dependent on third-party foundry scheduling.
Pricing Analysis
Short lead-time premiums command substantial markups as South Korean semiconductor fabrication facilities compress deployment timelines for smart factory wireless backhaul. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade 802.11ay infrastructure with integrated phased-array antennas from consumer bridge hardware. Price differentiation hinges on RRA certification status and volume procurement scale. Cost compression in the adapter tier is intensifying because Gyeonggi Province manufacturing clusters are retrofitting legacy equipment at scale. Residential buyers exhibit the highest price sensitivity, while enterprise IT departments prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based advanced-node foundries fabricating baseband SoCs for Qualcomm Technologies and MediaTek. Component sourcing draws from South Korean memory suppliers, Japanese phased-array antenna specialists, and Chinese PCB substrate manufacturers. Gallium arsenide wafers, beamforming controller ICs, and millimeter-wave filter modules constitute critical input dependencies. Tariff exposure on semiconductor fabrication equipment imports threatens procurement timelines for mainland Chinese vendors. Distribution runs through direct enterprise networking specialists rather than traditional AV systems integrators in Australian and Singaporean hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where Japan's MIC spectrum liberalization and South Korea's RRA certification tightening erect barrier-to-entry moats for vendors with established regulatory relationships. Compliant players capture pricing premiums while challengers absorb extended approval timelines.
For Market Incumbents: Cement regulatory positioning by establishing captive electromagnetic compatibility testing facilities in Gyeonggi Province to compress RRA approval cycles. Deepen upstream control over beamforming silicon design through exclusive partnerships with Hsinchu-based phased-array specialists. The threat of Wi-Fi 7 convergence architectures displacing standalone 60 GHz deployments demands accelerated 802.11ay-integrated dual-radio development. For New Entrants and Emerging Players: Launch via direct procurement relationships with Australian hospital networks unbundling wireless display infrastructure from traditional AV vendor contracts. Target India's Tamil Nadu and Karnataka manufacturing clusters lacking dense fiber infrastructure for wireless backhaul white space. White space concentrates in healthcare imaging unification and industrial corridor digitization segments underserved by incumbent enterprise networking specialists. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by baseband silicon architects seeking downstream integration into enterprise access point manufacturing. Long-term viability hinges on regulatory compliance infrastructure rather than pure technology differentiation. Acquisition targets should display captive testing capabilities and established MIC, RRA, or MIIT certification relationships. The signal to watch is spectrum harmonization coordination across Japanese, South Korean, and Chinese regulators that would compress cross-border equipment flow friction.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Facility Establishment | Compresses RRA approval cycles for Gyeonggi Province smart factory deployments. |
| Dual-Radio Access Point Development | Enables seamless 6 GHz and 60 GHz handoff for mixed-device enterprise environments. |
| Healthcare Procurement Committee Engagement | Captures Melbourne and Sydney hospital network tenders prioritizing latency specifications. |
| Phased-Array Antenna Miniaturization | Reduces bill-of-materials costs for education and healthcare vertical access points. |
| India Industrial Corridor Partnership | Addresses Tamil Nadu automotive assembly plant wireless backhaul infrastructure gaps. |
Methodological Framework
Independent corroboration across primary interviews with enterprise networking procurement managers, RF engineering directors at access point manufacturers, and semiconductor foundry operations executives underwrites the qualitative findings. Secondary validation incorporates MIIT GB standards documentation, RRA electromagnetic compatibility certification records, and MIC spectrum allocation filings. Bottom-up triangulation across equipment shipment data and top-down reconciliation against enterprise IT expenditure surveys anchor the market sizing.
Comparable-period anchoring to historical 802.11ad deployment trajectories in Tokyo commercial corridors and Gyeonggi Province semiconductor facilities shapes the projection horizon. Segmentation dimensions modeled include product type, use case intensity, end-user vertical, and deployment operational model. CAGRs derive from equipment procurement timeline compression observed in South Korean smart manufacturing zones and Australian healthcare network tenders. Industry-specific inputs incorporate beamforming silicon cost curves and spectrum harmonization policy velocity.
The model assumes a particular technology adoption path; alternative pathways for Wi-Fi 7 convergence architectures would alter the outlook. Forecasts reflect assumptions regarding RRA certification timeline stability and MIC spectrum policy continuity. Semiconductor supply concentration risk and millimeter-wave RF engineering scarcity constitute primary revision factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Flexible Electronics Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market