
 Deep Tech Market | 2026-2036
Deep Tech Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Tech Market Analysis
Israeli quantum computing foundries is rebalancing capacity toward photonic qubit fabrication. Helion Energy sustains plasma confinement R&D intensity in Redmond, Washington. Mistral AI competes on open-weight model differentiation against closed-source rivals. Cohere leverages enterprise NLP specialization to anchor recurring revenue in regulated sectors.
Deep tech encompasses capital-intensive technologies built on fundamental scientific breakthroughs, typically requiring sustained R&D cycles and specialized manufacturing infrastructure such as cryogenic systems or cleanroom fabrication. Its primary purpose is solving complex industrial problems through novel physics, biology, or computation rather than incremental software improvement. AI deployment within financial services generates the deepest margin pools due to compliance-sensitive customization requirements. Quantum computing for industrial automation remains nascent but occupies the fastest-expanding investment bandwidth. Blockchain applications in smart cities have matured into pilot-phase standardization, constraining near-term pricing power.
The EU AI Act, FDA software-as-medical-device guidance, and ISO 42001 artificial intelligence management standards collectively shape product certification pathways and cross-border market access. NHTSA autonomous vehicle frameworks in the United States further constrain robotics deployment timelines through safety validation requirements. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance cost escalations that could redirect capital toward less fragmented deployment geographies.
Market Dynamics
Defense procurement of quantum sensing systems is compressing commercialization timelines while the EU AI Act forces algorithmic transparency investments across high-risk applications.
Growth Catalysts
- Defense quantum sensing procurement:United States contractors are accelerating volume commitments for navigation and timing systems. Military validation creates technology spillover into civilian industrial automation.
- EU AI Act compliance mandates:Algorithmic transparency requirements for high-risk applications are forcing enterprise AI vendors to upgrade documentation and audit infrastructure. This creates recurring revenue in compliance tooling.
- Tel Aviv cybersecurity corridor concentration:Israel's specialized talent density in offensive security is attracting sovereign wealth deployment. Government co-investment funds de-risk early-stage quantum cryptography ventures.
Market Restraints
- Cryogenic infrastructure cost volatility:Helium-3 and dilution refrigerator supply constraints are inflating superconducting qubit fabrication costs. Limited foundry capacity concentrates pricing power with two European suppliers.
- Cleanroom fabrication bottlenecks:Photonic qubit foundries in Israel and the Netherlands face 18-month order backlogs. Equipment lead times from ASML and Applied Materials extend capacity expansion timelines.
- FDA software-as-medical-device friction:AI diagnostic tools face protracted premarket review pathways. Validation requirements for continuously learning algorithms create regulatory uncertainty that delays commercial deployment.
Strategic Opportunities
- India PLI scheme for semiconductor manufacturing:Production-linked incentives for compound semiconductors attract photonics packaging investments. Domestic fab capacity reduces import dependency for quantum component sourcing.
- Quantum-classical algorithm hybridization:Variational quantum eigensolvers integrated with GPU clusters address molecular simulation in pharmaceuticals. Convergence compresses time-to-insight for materials discovery pipelines.
- ISO 42001 certification services:Enterprise demand for artificial intelligence management system audits outstrips accredited assessor supply. First-mover certification bodies capture margin in regulated financial services verticals.
Industry Challenges
- Cryogenic engineering talent scarcity:PhD-level expertise in dilution refrigerator operation and microwave engineering commands premium compensation. University pipeline output lags commercial demand by approximately five years.
- Cross-jurisdiction compliance fragmentation:Divergent NHTSA autonomous vehicle frameworks and EU AI Act requirements force dual-track product development. Engineering resources split across incompatible validation protocols.
- Legacy system integration complexity:Industrial automation deployments require retrofitting quantum sensors into PLC-controlled environments. Protocol translation and real-time synchronization consume implementation bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Tech Market |
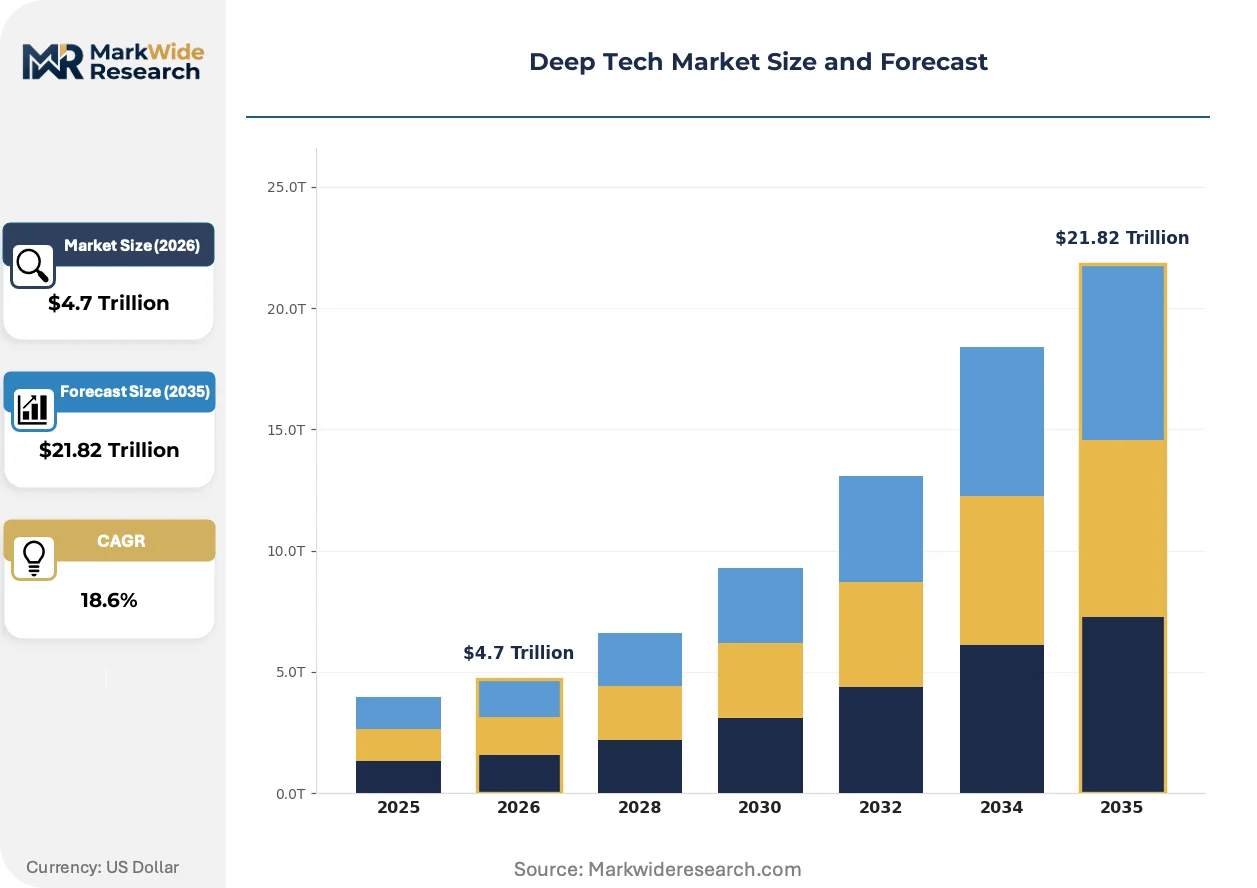
| Market Size in 2026 | $4.7 Trillion |
| Market Size in 2035 | $21.82 Trillion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, AI, Quantum Computing, Robotics Application: Financial Services, Healthcare Solutions, Industrial Automation, Smart Cities End User: Enterprises, Startups, Government Agencies, Academic Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Synthace, Cohere, Helion Energy, Bit.bio, Alice & Bob, Sky Engine AI, Mistral AI, Equal1, 1X Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Tech Market Emerging Trajectories
Photonic qubit fabrication is displacing superconducting approaches in commercial roadmaps while regulatory fragmentation forces multi-jurisdiction compliance architecture.
Photonic integrated circuits using silicon nitride waveguides are overtaking superconducting transmon architectures in foundry scalability. Industrial automation vendors in Germany and Japan are piloting room-temperature quantum sensors for precision positioning. This technology compression is collapsing the cost curve for quantum-enhanced navigation systems.
The EU AI Act's risk-tier classification system mandates conformity assessments for biometric identification and critical infrastructure AI. High-risk application vendors must maintain technical documentation and human oversight protocols. Financial services deployments in Frankfurt and Paris are restructuring procurement to prioritize CE-marked algorithmic systems.
Enterprise buyers are consolidating vendor relationships around full-stack quantum computing providers rather than hardware-only suppliers. Defense contractors and pharmaceutical firms now demand integrated software-hardware-service contracts with guaranteed uptime. This preference concentration is most visible in United States federal procurement and European pharmaceutical R&D outsourcing.
Deep Tech Market Segmentation
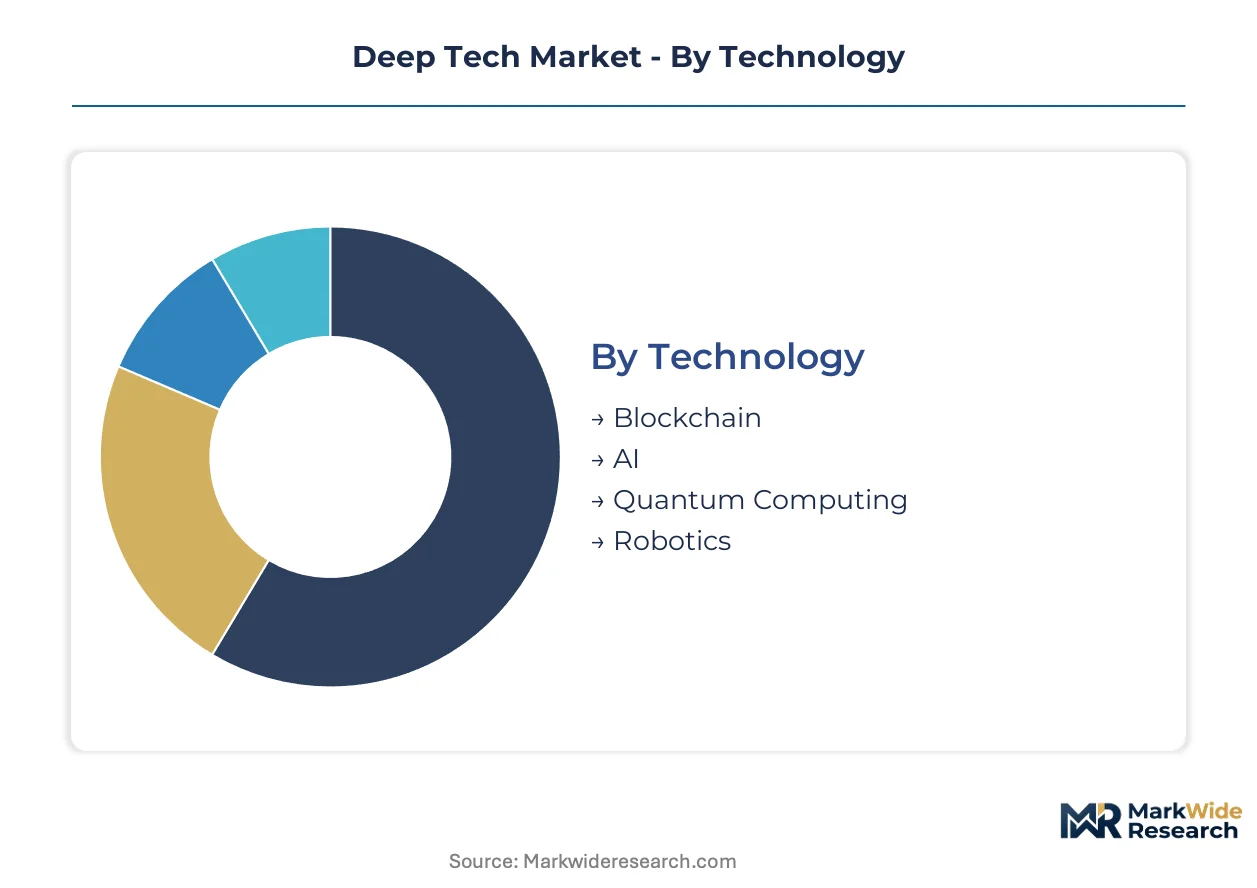
Deep tech segmentation reveals divergent capital intensity and regulatory exposure across technology layers. Deployment mode selection directly determines compliance architecture and infrastructure amortization schedules for end users.
Technology:
Volume concentration clusters in AI deployment, while premium pricing attaches to quantum computing infrastructure due to cryogenic engineering requirements.
- AI:Machine learning systems dominate enterprise procurement volumes, with natural language processing and computer vision absorbing the largest share of R&D expenditure. Financial services institutions in Frankfurt and Singapore drive compliance-sensitive customization demand. FDA software-as-medical-device guidance and EU AI Act risk-tier classifications force dual-track documentation investments.
- Quantum Computing:Superconducting and photonic qubit architectures require dilution refrigeration or silicon nitride foundry access. Defense contractors in the United States compress commercialization timelines through navigation and timing system procurement. Helium-3 supply constraints inflate operational costs for superconducting approaches.
- Blockchain:Distributed ledger applications in smart cities have matured into pilot-phase standardization. Municipal procurement in Dubai and Singapore constrains near-term pricing power through specification harmonization.
- Robotics:Autonomous systems face NHTSA validation requirements in the United States and divergent safety frameworks across jurisdictions. Industrial automation vendors in Germany pilot room-temperature quantum sensors for precision positioning integration.
Mature deployment sits with AI. Newer deployment is concentrated in quantum computing.
Application:
Margin distribution favors financial services due to compliance-sensitive customization, while industrial automation absorbs the steepest expansion trajectory in investment bandwidth.
- Financial Services:Algorithmic trading and risk management systems generate recurring revenue through regulatory audit requirements. ISO 42001 certification demand outstrips accredited assessor supply in Frankfurt and Paris. CE-marked algorithmic systems now structure procurement priorities.
- Industrial Automation:Quantum-enhanced navigation and precision positioning systems attract defense and logistics procurement. PLC-controlled environment retrofits consume implementation bandwidth through protocol translation requirements. Room-temperature quantum sensors collapse cost curves for commercial deployment.
- Healthcare Solutions:AI diagnostic tools face protracted FDA premarket review pathways for continuously learning algorithms. Validation uncertainty delays commercial deployment despite pharmaceutical R&D outsourcing demand.
- Smart Cities:Blockchain-enabled infrastructure and IoT integration have achieved pilot standardization. Municipal procurement cycles constrain vendor pricing power through competitive tender specifications.
Revenue concentration anchors in financial services. Investment bandwidth is expanding most quickly in industrial automation.
End User:
Government procurement drives volume for quantum sensing, while enterprise demand concentrates compliance tooling revenue.
- Government Agencies:Defense departments in the United States accelerate quantum sensing volume commitments. Sovereign wealth deployment in Israel de-risks early-stage quantum cryptography ventures through co-investment funds.
- Enterprises:Full-stack vendor consolidation demands integrated software-hardware-service contracts with guaranteed uptime. Procurement restructuring in European pharmaceutical R&D outsourcing prioritizes CE-marked systems.
- Startups:Venture deployment concentrates in Tel Aviv's cybersecurity corridor and Netherlands photonic foundry access. Cleanroom fabrication bottlenecks extend 18-month order backlogs for equipment from ASML and Applied Materials.
- Academic Institutions:University pipeline output for cryogenic engineering and microwave expertise lags commercial demand by approximately five years. PhD-level talent commands premium compensation in dilution refrigerator operation.
Procurement volume concentrates with government agencies. Compliance tooling revenue anchors in enterprises.
Deployment:
Cloud-based architectures capture standard AI workloads, while hybrid configurations address quantum-classical algorithm integration.
- Cloud-Based:Enterprise NLP and computer vision deployment favors scalable infrastructure without cryogenic constraints. Cohere and Mistral AI compete on open-weight differentiation for regulated sector access.
- Hybrid:Variational quantum eigensolvers integrated with GPU clusters address molecular simulation in pharmaceuticals. Quantum-classical convergence compresses materials discovery timelines.
- On-Premises:Superconducting qubit systems require captive dilution refrigeration infrastructure. Two European suppliers concentrate pricing power due to limited foundry capacity.
- Edge Computing:Autonomous vehicle and robotics deployment face NHTSA framework constraints in the United States. Real-time synchronization requirements consume engineering bandwidth for PLC integration.
Standard AI workloads dominate cloud deployment. Quantum-classical integration is expanding most quickly in hybrid configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium-3 isotope extraction in Qatar and cryogenic equipment manufacturing in Finland anchor the geographic distribution of deep tech infrastructure. Defense procurement corridors in the United States and photonics foundry clusters in the Netherlands concentrate capital deployment. Regulatory divergence between Washington, Brussels, and Beijing fragments compliance architecture across jurisdictions.
United States
Defense contractors accelerate quantum sensing volume commitments for navigation and timing systems. NHTSA autonomous vehicle frameworks constrain robotics deployment timelines through safety validation requirements. Redmond, Washington sustains plasma confinement R&D intensity for fusion energy development.
Germany
Industrial automation vendors pilot room-temperature quantum sensors for precision positioning integration. The country's national technology regulator enforces CE marking requirements for AI-enabled manufacturing equipment. Frankfurt financial institutions drive compliance-sensitive algorithmic trading procurement.
Israel
Sovereign wealth deployment de-risks early-stage quantum cryptography ventures through government co-investment funds. The country's central bank monitors cybersecurity standards for fintech integration. Tel Aviv's cybersecurity corridor concentrates offensive security talent density attracting venture capital.
Netherlands
Photonic qubit foundries face 18-month order backlogs for silicon nitride waveguide fabrication. The country's national standards body implements EU AI Act conformity assessment protocols. Eindhoven Region anchors ASML equipment supply chains for cleanroom capacity expansion.
India
Production-linked incentives for compound semiconductors attract photonics packaging investments. The Bureau of Indian Standards certifies quantum component import specifications. Karnataka and Telangana host domestic fab capacity reducing dependency on European quantum hardware sourcing.
Deep Tech Market Vendor Landscape
Global majors compete with regional champions across cryogenic infrastructure and photonics fabrication capabilities. The vendor base organizes around three strategic tiers: full-stack quantum computing providers, specialized AI model developers, and defense-integrated sensing specialists. Consolidation pressures favor integrated software-hardware-service contracts with guaranteed uptime. Dominant competitive moves include strategic partnerships for foundry access and geographic expansion toward India PLI scheme jurisdictions.
Within the full-stack quantum tier, Helion Energy and Alice & Bob exemplify capital-intensive infrastructure plays requiring sustained R&D cycles. Among AI model specialists, Cohere and Mistral AI occupy positions differentiated by open-weight versus enterprise NLP specialization. Synthace represents the biological automation archetype integrating computational design with laboratory execution. These anchors reflect the market's segmentation between hardware-heavy quantum systems and software-centric AI deployment.
| Leading Market Players |
|---|
| Synthace |
| Cohere |
| Helion Energy |
| Bit.bio |
| Alice & Bob |
| Sky Engine AI |
| Mistral AI |
| Equal1 |
| 1X Technologies |
| Others |
Supply Flow & Price Mechanics
Helium-3 spot market volatility cascades through superconducting qubit fabrication costs, compressing margins for captive dilution refrigeration operators while photonic foundry alternatives capture pricing power through silicon nitride waveguide scalability. Buyers face bifurcated procurement economics between cryogenic-dependent superconducting systems and room-temperature photonic architectures.
Pricing Analysis
Warranty bundling separates full-stack quantum computing contracts from hardware-only transactions, with uptime guarantees commanding premium positioning against unbundled equipment sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 42001-accredited AI management systems anchoring top-tier valuations. Cost compression in superconducting hardware intensifies because helium-3 supply constraints inflate operational expenditure. Government defense contractors exhibit lowest price sensitivity due to mission-critical procurement mandates, while academic institutions face steepest budget constraints.
Supply Chain Analysis
India's PLI scheme for compound semiconductors reshapes sourcing patterns for photonics packaging investments, redirecting capital from European foundry dependency toward Karnataka and Telangana domestic fab capacity. Geographic supply concentration clusters in the Netherlands, Israel, and Finland for silicon nitride waveguide fabrication, dilution refrigeration manufacturing, and cryogenic equipment engineering respectively. Raw material dependencies center on helium-3 isotope extraction, ASML lithography systems, and Applied Materials deposition equipment. Single-source vulnerability concentrates with two European suppliers controlling dilution refrigerator output. Distribution runs through direct procurement contracts for defense integrators and pharmaceutical R&D outsourcers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-tier classification system erects compliance cost barriers that favor incumbents with established audit infrastructure and documented technical protocols, creating sustainable moats against undercapitalized challengers.
For Market Incumbents: Hedge against photonic qubit displacement by securing foundry partnerships in Eindhoven Region and Tel Aviv corridor before equipment lead times extend further. Consolidate around full-stack software-hardware-service contracts with guaranteed uptime to capture procurement preference concentration among United States defense contractors and European pharmaceutical R&D outsourcers.
For New Entrants and Emerging Players: Mid-tier industrial automation vendors in Germany and Japan represent the most penetrable buyer archetype for room-temperature quantum sensor integration, given PLC retrofit complexity that incumbents underprice. Pursue ISO 42001 certification services white space in Frankfurt and Paris financial services verticals, where accredited assessor supply constraints create immediate revenue capture opportunity.
For Investors and Strategic Acquirers: The window for entry favors cryogenic engineering talent platforms and photonic foundry access plays before university pipeline output catches commercial demand. Long-term viability hinges on vertical integration into helium-3 sourcing or silicon nitride fabrication capabilities. Watch for defense procurement volume acceleration as inflection signal for quantum sensing commercialization spillover timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Foundry Partnership | Silicon nitride waveguide access in Netherlands and Israel compresses superconducting cost disadvantage. |
| ISO 42001 Certification Investment | Accredited AI management system audits capture margin in Frankfurt and Paris financial services procurement. |
| Helium-3 Supply Agreement | Long-term isotope sourcing from Qatar anchors superconducting qubit operational economics. |
| Defense Contractor Integration | Navigation and timing system validation creates technology spillover into civilian industrial automation. |
| India PLI Scheme Localization | Compound semiconductor packaging capacity in Karnataka reduces European quantum hardware import dependency. |
Methodological Framework
Independent corroboration across cryogenic engineering executives, defense procurement officers, quantum computing R&D directors, and AI compliance consultants underwrites the qualitative findings. Primary interviews with dilution refrigerator operators, photonic foundry managers, and pharmaceutical outsourcing procurement leads combined with secondary validation from SEC filings of listed quantum hardware vendors, EIA energy infrastructure disclosures, and EU AI Act implementation guidance documents. Bottom-up vendor capacity assessments and top-down defense budget allocation analysis triangulate volume estimates.
Rate-of-change decomposition across technology adoption curves, regulatory implementation timelines, and capital deployment cycles structures the analytical framework over the projection horizon. Segmentation dimensions modeled include technology layer, application vertical, end-user archetype, and deployment mode complexity. CAGRs derive from installed base growth rates and average revenue per unit trajectories, with quantum-classical algorithm hybridization adoption and EU AI Act compliance cost pass-through representing key industry-specific forecast inputs.
Revisions become necessary when helium-3 supply disruptions, ASML equipment export restrictions, or divergent NHTSA autonomous vehicle framework implementations materialize. Forecasts reflect documented assumptions regarding defense procurement continuity and cleanroom fabrication capacity expansion schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Asia Pacific Quantum Computing Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market