
 Transmission Sales Market | 2026-2036
Transmission Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Sales Market Intelligence
The rising prominence of commercial vehicles and agricultural machinery in the end-use mix is rebalancing the transmission sales market away from a historical passenger car focus. Allison Transmission Inc. specializes in rugged automatic transmissions for heavy-duty applications. ZF Friedrichshafen AG competes across a wider spectrum, leveraging its portfolio in passenger cars, commercial transport, and industrial technology. Eaton Corporation plc differentiates with its advanced automated manual transmissions for the trucking industry.
Transmission sales involve the commerce of systems that transfer an engine's power to the driven wheels, managing torque and rotational speed. These systems utilize a series of gear ratios to optimize vehicle performance and fuel consumption. While Automatic Transmission units command a significant portion of sales, Dual-Clutch Transmission technology is expanding rapidly in performance-oriented passenger vehicles. The commercial vehicles application segment requires units engineered for higher torque capacity and durability.
Regulatory frameworks from the US EPA and the European Union, such as CO2 emission standards for new vehicles, are central to market evolution. These rules compel manufacturers to develop more efficient transmissions that reduce fuel consumption and emissions. China's GB standards also set stringent performance and efficiency requirements. Key decisions for manufacturers revolve around balancing investment in advanced internal combustion engine transmissions against the accelerating transition toward electric vehicle powertrains.
Market Dynamics
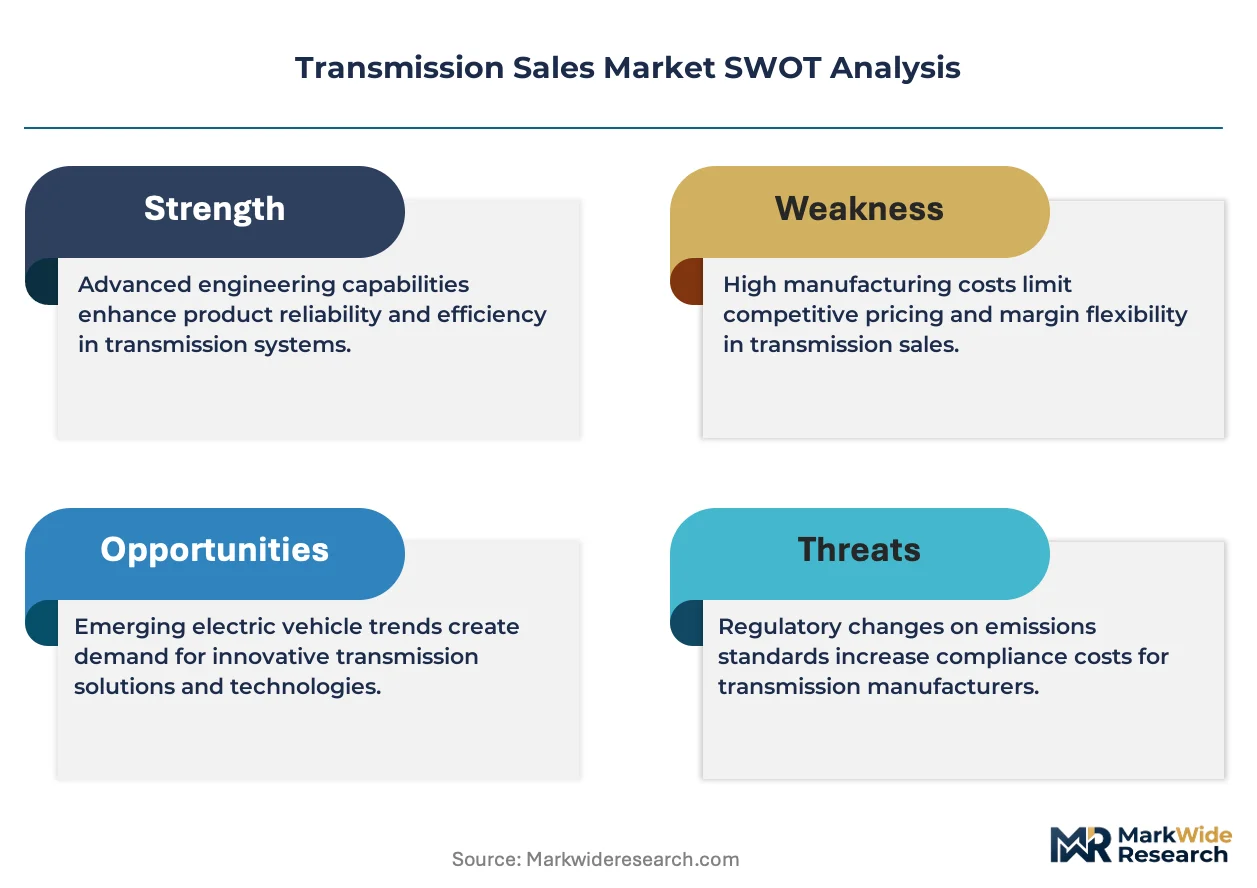
The transmission sales market is defined by a fundamental tension between optimizing internal combustion engine (ICE) powertrains and pivoting to electric vehicle (EV) architectures. This dynamic is forcing manufacturers to allocate capital between refining mature technologies for emissions compliance and developing new systems for electrification.
Growth Catalysts
- Stringent Emission Standards:Regulations like the EU's CO2 rules for heavy-duty vehicles and China's GB standards compel the adoption of more efficient transmissions, such as automated manuals and multi-speed automatics, to reduce fuel consumption.
- Commercial Fleet Expansion:Growth in industrial and logistics hubs across Southeast Asia is driving demand for durable and high-torque capacity transmissions specifically engineered for long-haul freight and commercial vehicle applications.
- Performance Vehicle Technology:The demand for enhanced driving dynamics and fuel efficiency in the passenger car segment is expanding the market for advanced systems like Dual-Clutch Transmissions (DCTs).
Market Restraints
- High Capital Investment:The significant capital expenditure required to retool production lines for new, complex transmission architectures or shift manufacturing towards EV powertrain components constrains rapid market-wide transitions.
- Threat of Substitution:The rise of battery electric vehicles with single-speed or direct-drive systems fundamentally threatens the market for traditional multi-speed transmissions, especially in passenger cars.
- Raw Material Price Volatility:Fluctuations in the cost of specialty steels, aluminum, and rare earth magnets used in transmission components and electronic controls create pricing and margin pressure for manufacturers.
Strategic Opportunities
- Aftermarket Services in Emerging Economies:Expanding logistics and construction sectors in countries like India and Brazil create opportunities for transmission remanufacturing and dedicated service networks to support commercial fleets.
- Hybrid Powertrain Systems:The development of specialized transmissions that can efficiently manage power from both an internal combustion engine and an electric motor presents a key opportunity in hybrid commercial and off-highway vehicles.
- Predictive Maintenance Integration:Embedding sensor technology and AI-driven analytics into transmission control units (TCUs) enables predictive maintenance services, creating new recurring revenue streams for suppliers and fleet operators.
Industry Challenges
- Software and Calibration Expertise:A shortage of software engineers with the specialized skills to program and calibrate complex transmission control units for optimal performance, efficiency, and emissions compliance is a critical bottleneck.
- System Integration Complexity:Ensuring seamless hardware and software interoperability between advanced transmissions, engines, and hybrid-electric components from different suppliers presents a significant technical hurdle for vehicle OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Sales Market |
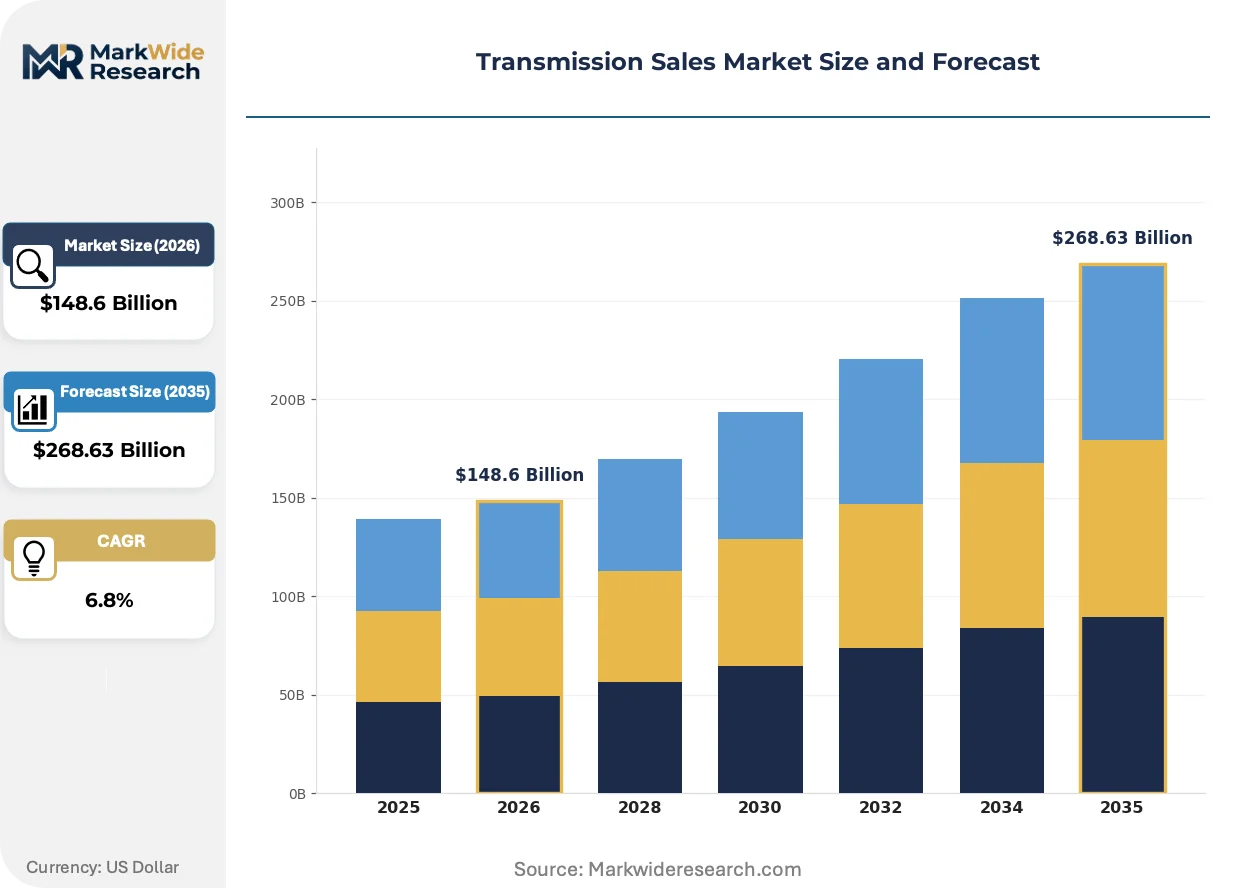
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Transmission, Manual Transmission, Continuously Variable Transmission, Dual-Clutch Transmission, Automated Manual Transmission Application: Passenger Vehicles, Commercial Vehicles, Construction Equipment, Agricultural Machinery, Mining Equipment End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Fleet Operators, Specialty Vehicle Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retailers, Authorized Dealers, Independent Workshops |
| Companies Covered | Caterpillar Inc., Cummins Inc., Siemens AG, General Electric Company, Allison Transmission Inc., ZF Friedrichshafen AG, ABB Ltd., Eaton Corporation plc, Gazprom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Sales Market Strategic Shifts & Innovations
Powertrain diversification is reshaping the market's technological trajectory. Manufacturers are simultaneously pursuing incremental efficiency gains in conventional transmissions to meet immediate regulations while investing in novel solutions for hybrid and fully electric vehicle platforms, creating a complex innovation landscape.
Multi-speed transmissions designed for electric vehicles improve motor efficiency at higher vehicle speeds and provide superior torque for towing or hauling. Premium and performance EV manufacturers are adopting these systems to extend vehicle range and enhance acceleration beyond the capabilities of single-speed gearboxes. This technology is absorbing research and development investment that previously focused on refining conventional automatic transmissions for ICEs.
The US EPA's stringent greenhouse gas emissions standards for heavy-duty trucks are a primary regulatory driver. These rules mandate progressive reductions in CO2 emissions and fuel consumption, directly influencing powertrain design choices for OEMs. The North American long-haul trucking segment is most affected, spurring the adoption of highly efficient automated manual transmissions (AMTs) and predictive cruise control systems.
Fleet operators are increasingly favoring whole-unit replacement strategies over in-shop component repairs to maximize vehicle uptime and operational availability. This behavioral shift is disrupting the business model for smaller, independent repair garages while benefiting OEM-authorized service centers and specialized remanufacturing firms. This trend is particularly evident in the European commercial vehicle market, where total cost of ownership is a primary procurement driver.
Transmission Sales Market Segmentation
Understanding the distinct segments within the transmission sales market is critical for manufacturers and suppliers to align product development and sales strategies. This granular view helps identify where technological investments yield the highest returns and where demand patterns for upgrades or replacements are most pronounced.
Product Type:
The upgrade and replacement cycles for transmission units are heavily influenced by the distinct technological characteristics of each product type.
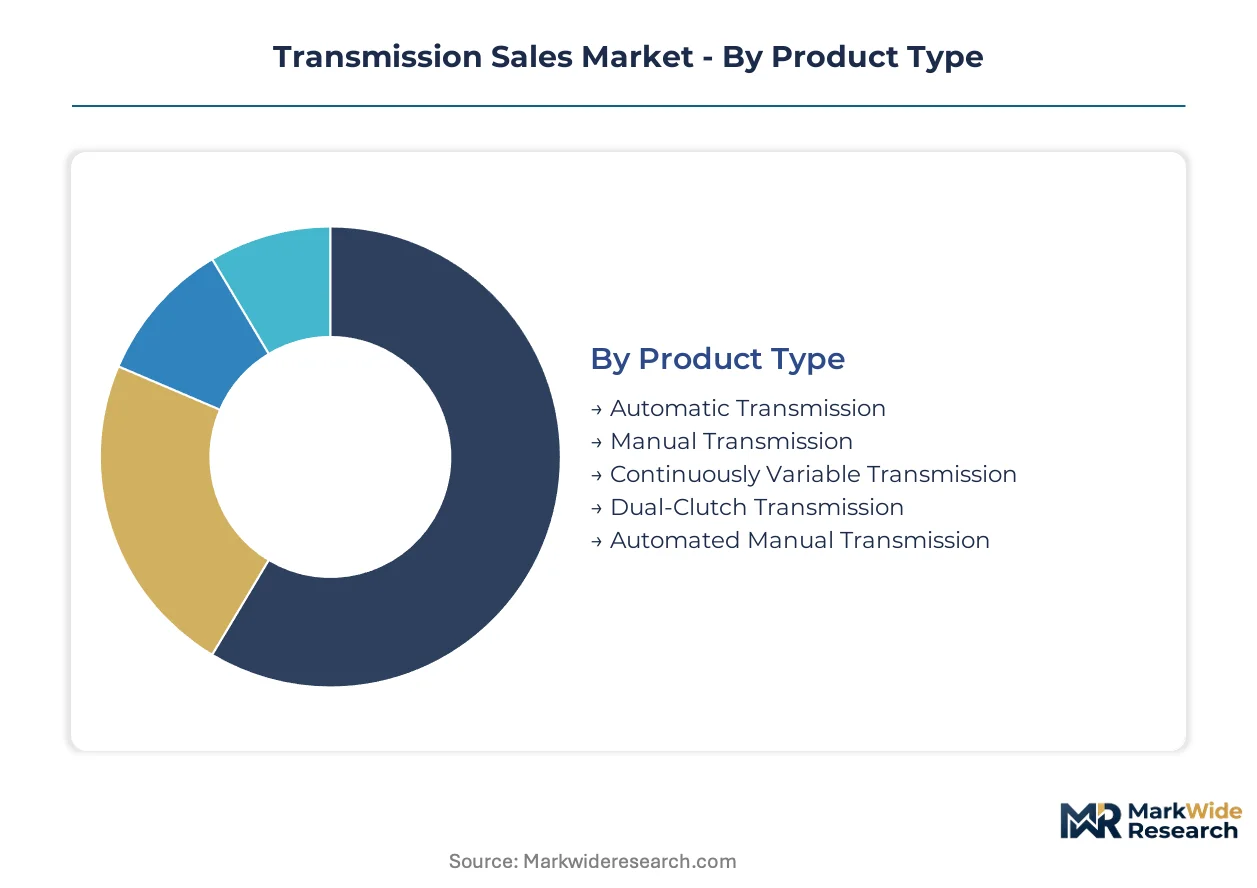
- Automatic Transmission:These systems automatically change gear ratios as the vehicle moves, optimizing engine speed and torque output without driver intervention, widely adopted in passenger cars and increasingly in commercial vehicles for ease of operation and efficiency. Demand is strong in North America and Europe, driven by driver comfort and regulatory push for efficiency.
- Dual-Clutch Transmission:DCTs utilize two separate clutches for odd and even gear sets, allowing for faster and smoother gear changes, enhancing performance and fuel economy, particularly in performance-oriented passenger vehicles. The technology is gaining traction in premium segments across Germany and China, where driving dynamics are a key differentiator.
- Manual Transmission:These transmissions require the driver to manually select gears using a clutch pedal and gear stick, offering direct control and often lower manufacturing costs.
- Continuously Variable Transmission:CVTs provide an infinite number of gear ratios within a fixed range, delivering smooth acceleration and improved fuel efficiency, primarily found in smaller passenger vehicles.
- Automated Manual Transmission:AMTs combine the mechanical efficiency of a manual transmission with automatic shifting capabilities, offering a cost-effective solution for fuel efficiency in heavy-duty commercial vehicles.
Automatic Transmission sits at the top of the volume ranking, with Dual-Clutch Transmission climbing the fastest.
Application:
Application-specific demands dictate the engineering and cost structures of transmission units across the market.
- Commercial Vehicles:Transmissions for commercial vehicles are engineered for high torque capacity, durability, and fuel efficiency to support heavy loads and long-haul operations in sectors like logistics and construction. The segment sees significant demand from fleet operators in Southeast Asia and North America, supporting expanding supply chain infrastructure.
- Passenger Vehicles:These applications require transmissions that balance performance, fuel economy, and driver comfort, ranging from compact cars to luxury sedans, often incorporating advanced technologies like DCTs and CVTs. European and Japanese markets continue to prioritize advanced passenger vehicle transmission technologies for emissions compliance and driving experience.
- Agricultural Machinery:Transmissions in agricultural equipment must withstand harsh operating conditions and provide robust power transfer for tasks like plowing and harvesting.
- Construction Equipment:This segment demands heavy-duty transmissions capable of handling extreme loads and continuous operation in challenging environments, such as excavators and loaders.
- Mining Equipment:Transmissions for mining machinery are designed for maximum durability and reliability in arduous conditions, often involving very high torque and power requirements.
Demand for transmissions in commercial vehicles is expanding significantly, while agricultural machinery applications also show consistent growth.
End User:
Customer type segmentation reveals distinct procurement strategies and service requirements for transmission solutions.
- OEMs:Original Equipment Manufacturers integrate transmissions directly into new vehicles during the assembly process, requiring large volumes, specific technical specifications, and just-in-time delivery. OEMs in Germany and Japan are increasingly focused on modular transmission designs to support diverse powertrain architectures.
- Fleet Operators:These end-users purchase transmissions for their vehicle fleets, prioritizing durability, fuel efficiency, and ease of maintenance to minimize downtime and total cost of ownership. Large logistics companies in the US and China are driving demand for highly efficient automated manual transmissions.
- Aftermarket Suppliers:These entities provide replacement transmissions and components for vehicles already in operation, serving repair shops and individual consumers.
- Vehicle Assemblers:Companies that assemble vehicles from components sourced from various suppliers, including transmissions, cater to niche markets or specific regional demands.
- Specialty Vehicle Manufacturers:These manufacturers produce vehicles for specific purposes, such as emergency services or custom industrial applications, requiring tailored transmission solutions.
OEMs remain the largest purchasers of new transmission units, with fleet operators increasingly influencing aftermarket service demands.
Distribution Channel:
Distribution channels reflect the varying maturity and complexity of sales, from direct manufacturer relationships to specialized aftermarket support.
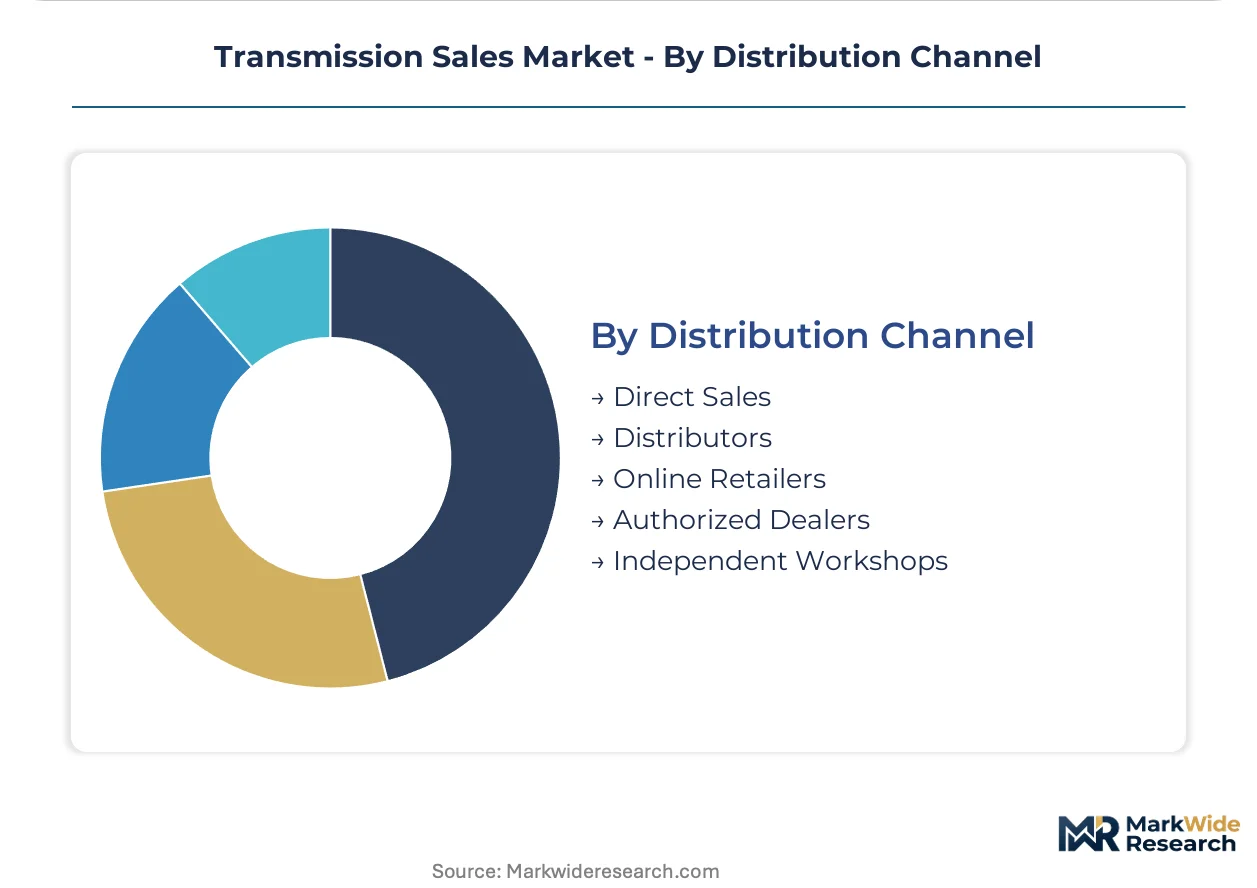
- Direct Sales:Manufacturers sell transmissions directly to large OEMs or fleet operators, often involving long-term contracts, custom specifications, and integrated supply chain management. This channel is dominant for new commercial vehicle transmissions in North America and Europe, facilitating close collaboration.
- Authorized Dealers:These entities sell new vehicles equipped with transmissions and often provide official replacement parts and service, maintaining brand standards and customer relationships. Authorized dealer networks in developed markets like Germany and Japan play a key role in both new vehicle sales and certified aftermarket support.
- Distributors:Independent companies that purchase transmissions from manufacturers and resell them to a network of smaller dealers, repair shops, or industrial clients.
- Online Retailers:E-commerce platforms facilitate the sale of aftermarket transmission parts and sometimes complete units, offering convenience and competitive pricing to a broad customer base.
- Independent Workshops:These service centers purchase transmissions and components from various suppliers for repairs and maintenance of vehicles from multiple manufacturers.
Direct sales channels handle the majority of new unit transactions, while independent workshops provide critical support for the installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage, where production migrates due to differing cost-of-compliance gaps, significantly influences the transmission sales market. Manufacturers often strategically locate facilities to balance stringent emission standards against operational costs and market access. This dynamic shapes investment patterns and technology deployment across key global regions.
United States
Demand for heavy-duty commercial vehicle transmissions is strong, driven by long-haul freight applications. The US EPA's stringent greenhouse gas emissions standards compel manufacturers to develop more efficient powertrain solutions. Major automotive and trucking manufacturing centers in Michigan focus on advanced transmission assembly.
Germany
The market benefits from strong demand for advanced passenger vehicle and commercial transport transmissions. EU CO2 emission standards for heavy-duty vehicles drive innovation in automated manual transmissions. The Baden-Württemberg region, home to major automotive OEMs, leads in R&D for next-generation transmission technologies.
China
A rapidly expanding commercial vehicle fleet and domestic passenger car market fuel demand for diverse transmission types. China's GB standards set performance and efficiency requirements, pushing local manufacturers towards advanced designs. Industrial clusters in the Yangtze River Delta concentrate on high-volume production of powertrain components.
India
Expanding logistics and construction sectors create substantial demand for durable commercial vehicle transmissions and aftermarket services. The Indian government's PLI scheme encourages local manufacturing and technological upgrades. Automotive hubs in Chennai are developing capabilities for transmission remanufacturing and service networks.
Thailand
The country's position as a regional logistics hub in Southeast Asia drives consistent demand for robust commercial vehicle transmissions. Government incentives for electric vehicle production are indirectly influencing local transmission component suppliers. Automotive manufacturing zones in Rayong are attracting investment for powertrain assembly.
Transmission Sales Market Key Industry Players
Portfolio diversification dominates the current landscape, as manufacturers broaden their offerings beyond traditional internal combustion engine transmissions. The market structure exhibits characteristics of both consolidation among established players and fragmentation with niche specialists. Strategic archetypes include global diversified industrial conglomerates, heavy-duty transmission specialists, and emerging EV powertrain integrators. Capacity expansion and strategic partnerships represent two dominant competitive moves.
Specialists in heavy-duty applications include Allison Transmission Inc., which represents the archetype of a rugged automatic transmission provider for commercial vehicles. ZF Friedrichshafen AG exemplifies a diversified approach, offering solutions across passenger cars, commercial transport, and industrial technology, reflecting its broad market presence. Eaton Corporation plc differentiates with its advanced automated manual transmissions for the trucking industry, anchoring a key segment focused on efficiency. These companies collectively illustrate the varied strategic positions within the market.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Siemens AG |
| General Electric Company |
| Allison Transmission Inc. |
| ZF Friedrichshafen AG |
| ABB Ltd. |
| Eaton Corporation plc |
| Gazprom |
| Others |
Cost & Logistics Intelligence
Product performance divergence, particularly between advanced automated manual transmissions for heavy-duty commercial vehicles and sophisticated dual-clutch units for premium passenger cars, significantly influences both pricing and supply chain configurations. This distinction drives different manufacturing complexities and distribution strategies.
Pricing Analysis
Direct-to-OEM discount structures dominate pricing for high-volume transmission units. Contract-based long-term offtake agreements define the primary pricing model for new transmissions supplied to vehicle manufacturers. Performance specifications and torque capacity serve as key price differentiation drivers, alongside customization levels for specific vehicle platforms. Pricing softness reflects the intense competition among established transmission suppliers. Fleet operators exhibit the highest price sensitivity, constantly evaluating total cost of ownership, while premium passenger vehicle OEMs prioritize technology and brand value.
Supply Chain Analysis
Direct-to-OEM channels handle the majority of new unit transactions, ensuring integrated logistics and just-in-time delivery for vehicle assembly lines. Geographic supply concentration centers on automotive component manufacturing hubs in Germany, China, and Japan. Specialty steels, aluminum alloys, and electronic control units represent critical raw material and component dependencies. Single-source vulnerability for advanced electronic components poses a structural supply chain risk. The aftermarket distribution model relies on authorized dealers and independent workshops for replacement parts and service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transmission sales market remains a stable compounder, driven by the continuous global expansion of commercial vehicle fleets and the persistent demand for powertrain efficiency improvements.
For Market Incumbents: Cement market leadership by investing heavily in hybrid powertrain system development, particularly for heavy-duty and off-highway applications. Deepen vertical integration into advanced electronic control unit manufacturing to mitigate raw material price volatility and enhance system integration complexity. This strategy helps counter the threat of substitution from single-speed EV architectures in specific segments.
For New Entrants and Emerging Players: The EU's stringent CO2 emission standards for heavy-duty vehicles in Europe opens a window for specialized automated manual transmission developers. Target the aftermarket services segment in emerging economies like India and Brazil, which are experiencing commercial fleet expansion. A go-to-market angle focusing on cost-effective remanufacturing and robust service networks can establish a foothold.
For Investors and Strategic Acquirers: Consolidation pressure builds where technological diversification requires significant capital allocation between ICE and EV powertrain development. Seek out mid-cap specialists with proven expertise in multi-speed EV transmissions or advanced hybrid solutions. The signal to watch is the acceleration of OEM commitments to multi-speed EV platforms beyond premium passenger vehicles.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Multi-Speed EV Transmissions | This enhances electric vehicle range and torque capabilities, meeting evolving performance demands from OEMs. |
| Expand Aftermarket Service Networks | This captures recurring revenue streams from an expanding installed base, particularly in commercial vehicle segments. |
| Deepen Hybrid Powertrain Integration | This addresses the immediate regulatory push for efficiency in internal combustion engine and off-highway applications. |
| Develop Advanced Predictive Maintenance | This leverages sensor technology and AI to reduce vehicle downtime for fleet operators, creating value-added services. |
| Secure Long-Term Raw Material Contracts | This mitigates pricing and margin pressure from volatility in specialty steels and rare earth magnets for critical components. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region's automotive and commercial vehicle sectors. The analysis combined extensive primary interviews with industry stakeholders, including OEM procurement managers, fleet operators, and R&D leads, with secondary validation from regulatory filings, industry association reports, and technical publications. Bottom-up and top-down triangulation ensured data consistency.
The rate-of-change decomposition framing informs the analytical framework, assessing market shifts across the analysis window. Segmentation dimensions modeled include product type, application, end-user, and distribution channel, alongside a specific focus on powertrain architecture. Compound annual growth rates were derived by analyzing historical performance and projecting future demand based on regulatory trajectories and technological adoption curves. Vehicle production forecasts and fleet expansion plans serve as key forecast inputs.
Revisions become necessary when significant policy changes, unforeseen technological breakthroughs, or macroeconomic shifts materialize. Forecasts reflect assumptions documented regarding regulatory enforcement and adoption rates of new transmission technologies. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Steering Damper Market
Powertrain
Automotive Fuel Cock Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Global Driveline Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Torque Limiter Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Global Automotive Pumps Market
Powertrain
Reciprocating Engine Market
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Automotive Brake Booster Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Automotive Haptic Accelerator Pedal Market