
 Rocker Arm Assembly Market | 2026-2036
Rocker Arm Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Rocker Arm Assembly Market Analysis
Commercial vehicle OEM procurement is repositioning toward lightweight valvetrain architectures that reduce parasitic engine losses. BorgWarner Inc. leverages its powertrain integration expertise to supply modular rocker arm solutions across multiple engine platforms. Schaeffler Technologies AG anchors its position through advanced surface coating technologies that extend component durability under high-cycle fatigue. Mahle GmbH competes on thermal management synergies between its piston and valvetrain product portfolios.
A rocker arm assembly translates camshaft lobe motion into valve lift through a lever mechanism, typically machined from forged steel or aluminum alloy with hardened contact pads or roller bearings to withstand cyclic loads exceeding 10^8 operations. Its primary purpose is to enable precise control of intake and exhaust valve timing in reciprocating internal combustion engines. Roller rocker arms command premium positioning due to their friction reduction benefits in high-RPM automotive applications, while shaft-mounted configurations dominate heavy-duty commercial and marine engines where structural rigidity outweighs cost sensitivity. Steel remains the baseline material for cost-optimized volume production, though aluminum variants gain traction in passenger car downsized turbocharged engines where reciprocating mass reduction directly improves throttle response.
The EPA enforces Corporate Average Fuel Economy standards that compel OEMs to prioritize valvetrain efficiency gains, while the EU Green Deal framework accelerates scrutiny of embedded carbon in forged steel components through CBAM reporting requirements. Japan's METI administers fuel efficiency benchmarking that rewards sub-system innovations including low-friction rocker arm geometries. Stakeholders must monitor how electrification timelines in key automotive markets reshape internal combustion engine component procurement strategies and aftermarket replacement cycle economics.
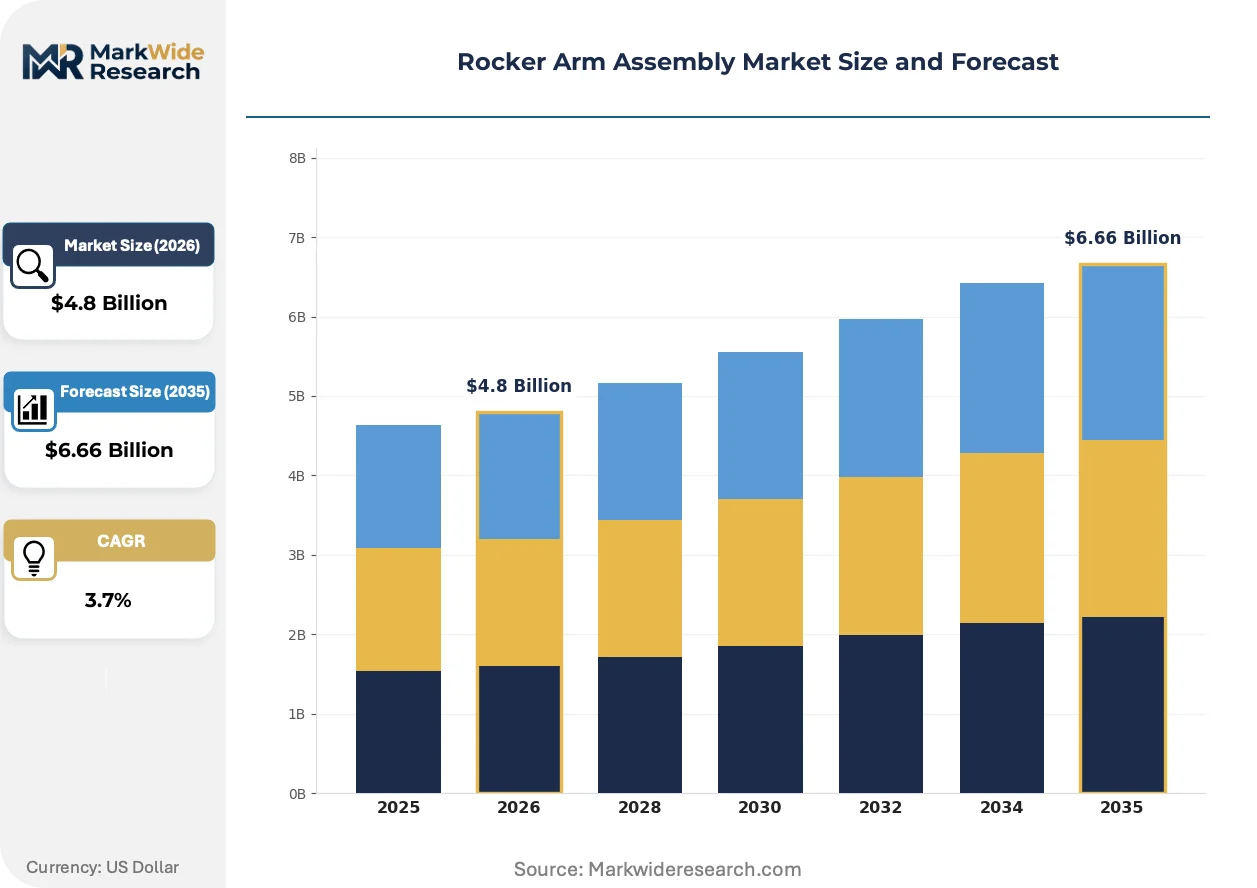
Market Dynamics
The EPA Tier 4 and Euro 7 emissions frameworks are forcing valvetrain suppliers to engineer sub-micron tolerance components that eliminate parasitic friction losses across diesel and gasoline engine architectures.
Growth Catalysts
- Lightweight Material Substitution:Aluminum alloy rocker arms are displacing forged steel in passenger car turbocharged engines where reciprocating mass reduction improves throttle response metrics demanded by Japan's METI fuel efficiency benchmarking.
- EU Green Deal CBAM Reporting:Embedded carbon disclosure requirements for forged steel components are accelerating supplier investment in electric induction heating and closed-loop forging processes to maintain OEM qualification status.
- Commercial Vehicle OEM Consolidation:Heavy-duty engine manufacturers in Germany and the United States are standardizing shaft-mounted rocker arm configurations across platform families to reduce service part complexity and inventory carrying costs.
Market Restraints
- Specialized Alloy Input Volatility:Hardened tool steel and micro-alloyed forgings face price pressure from scrap metal flow disruptions and energy-intensive electric arc furnace operating costs concentrated in European foundry clusters.
- Precision Machining Concentration:Sub-micron grinding and superfinishing capacity for roller bearing contact surfaces concentrates among Japanese and German machine tool operators, creating single-source vulnerability for tier-two component suppliers.
- Electrification Timeline Compression:Battery electric vehicle production ramps in key automotive markets are compressing internal combustion engine platform development budgets and shortening component amortization horizons.
Strategic Opportunities
- Marine and Stationary Engine Aftermarket:Diesel-powered commercial marine vessels and backup power generators in Southeast Asian ports represent underpenetrated replacement cycle demand as EPA Tier 4 retrofit deadlines approach.
- Additive Manufacturing Convergence:Hybrid production combining near-net-shape metal additive with precision CNC finishing is enabling complex internal oil gallery geometries that reduce lubrication system pressure drops.
- US Inflation Reduction Act Domestic Content:Commercial vehicle OEMs are qualifying North American forged component sources to capture clean vehicle tax credit supply chain incentives, creating qualification windows for new entrants.
Industry Challenges
- Metallurgical Talent Scarcity:High-cycle fatigue analysis and thermal-mechanical processing expertise for advanced surface coatings is concentrating among retiring specialists at German and Japanese research institutes.
- Multi-Platform Validation Burden:OEM demand for modular rocker arm solutions across gasoline, diesel, and alternative fuel engines is multiplying homologation testing matrices and extending program launch timelines.
- Legacy Equipment Integration:Shaft-mounted rocker arm architectures in existing heavy-duty engine families require backward-compatible design iterations that constrain geometric optimization for friction reduction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rocker Arm Assembly Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Rocker Arm, Shaft Rocker Arm, Stud Rocker Arm, Adjustable Rocker Arm Material: Aluminum, Steel, Titanium, Composite End User: OEMs, Aftermarket Providers, Racing Teams, Repair Shops Application: Automotive, Aviation, Marine, Industrial Engines |
| Companies Covered | BorgWarner Inc., Hitachi Automotive Systems, Schaeffler Technologies AG, Rane Group, Aisin Seiki Co., Ltd., Federal-Mogul Motorparts (Tenneco Inc.), Mahle GmbH, Comp Cams, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rocker Arm Assembly Market Emerging Trajectories
Diamond-like carbon and physical vapor deposition surface treatments are migrating from racing applications into production valvetrains as OEMs pursue wear resistance without lubricant viscosity increases.
DLC-coated contact pads are expanding into mass-market passenger car rocker arms where reduced boundary friction supports 0W-16 and 0W-8 oil grade adoption. Toyota and Honda powertrain divisions have qualified these coatings for 300,000-kilometer durability cycles. The technology is expanding into cost-optimized segment production as Chinese coating equipment suppliers enter the European supply base.
REACH Annex XIV authorization requirements for hexavalent chromium plating are eliminating traditional hard chrome surface treatments from European-sourced valvetrain components by 2027. Plasma electrolytic oxidation and thermal spray alternatives are achieving comparable hardness with reduced environmental compliance burden. German OEM procurement teams are mandating chrome-free surface specifications across global supplier networks to simplify variant management.
Powertrain engineering departments are unbundling valvetrain subsystem sourcing from historical engine block supplier relationships. Tier-one component specialists now contract directly with OEM technical centers for modular rocker arm assembly design and validation. This pattern is most visible in United States commercial vehicle programs where vertical integration strategies are reversing and specialist suppliers gain direct platform access.
Rocker Arm Assembly Market Segmentation
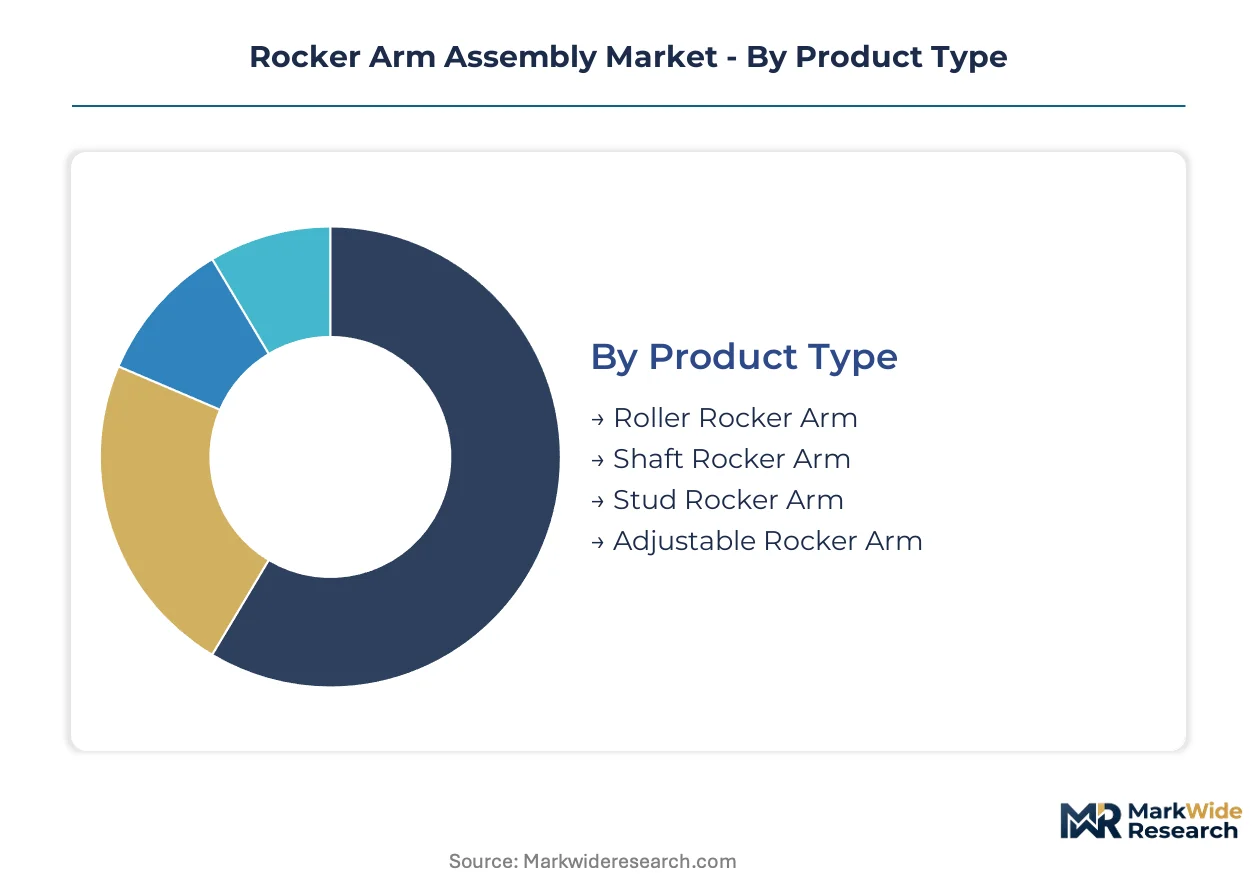
Rocker arm assembly procurement patterns diverge sharply across product architectures, with EPA Tier 4 and Euro 7 certification burdens concentrating on friction-critical segments. Material selection and end-user channel dynamics create distinct margin profiles that reshape supplier qualification strategies.
Product Type:
Certification requirements vary by contact mechanism, with roller bearing surfaces demanding sub-micron tolerance validation under EPA durability protocols while stud-mounted variants face simpler homologation matrices.
- Roller Rocker Arm:Hardened steel or needle bearing contact surfaces reduce boundary friction in high-RPM gasoline architectures. Passenger car OEMs in Japan and Germany prioritize these configurations where METI fuel efficiency benchmarking rewards parasitic loss reduction.
- Shaft Rocker Arm:One-piece cast or forged construction mounts on a stationary shaft for heavy-duty diesel platforms. Demand concentrates among commercial vehicle manufacturers in the United States and Germany standardizing across engine families to compress service part inventories.
- Stud Rocker Arm:Individual stud mounting suits pushrod V8 architectures in aftermarket performance applications.
- Adjustable Rocker Arm:Built-in lash compensation serves racing and high-performance rebuild segments requiring rapid valve train geometry modification.
Shaft rocker arms sit at the top of the volume ranking, with roller configurations climbing the fastest.
Material:
Cost tier stratification separates forged steel baselines from aluminum and titanium premiums, with composite variants occupying an emerging niche.
- Steel:Micro-alloyed forgings dominate commercial vehicle and industrial engine production where fatigue life exceeds 10^8 cycles. European foundry clusters face CBAM reporting pressure on embedded carbon, accelerating electric induction heating investment.
- Aluminum:A356-T6 and comparable alloys displace steel in passenger car turbocharged engines where reciprocating mass reduction improves throttle response. Japanese OEM powertrain divisions specify these for downsized direct-injection platforms.
- Titanium:Ti-6Al-4V and near-alpha alloys serve racing and limited-production exotic applications where cost sensitivity vanishes against specific power targets.
- Composite:Carbon fiber reinforced polymer prototypes are emerging in conceptual valvetrains for range-extender hybrid architectures.
Steel retains the dominant volume position, with aluminum expanding most quickly.
End User:
Customer type determines warranty liability exposure and technical specification depth, with OEM direct contracts demanding full traceability.
- OEMs:Passenger car and commercial vehicle manufacturers specify modular rocker arm assemblies validated across multiple engine platforms. Direct supplier relationships now bypass historical engine block integrators, particularly visible in United States heavy-duty truck programs.
- Aftermarket Providers:Independent distributors and private-label suppliers serve replacement cycles in aging vehicle parcs. Marine and stationary engine retrofit demand in Southeast Asian ports represents underpenetrated opportunity as EPA Tier 4 deadlines approach.
- Racing Teams:NASCAR, Formula 1, and grassroots motorsport competitors drive coating technology migration from track to production.
- Repair Shops:Independent service facilities source replacement rocker arms through jobber distribution networks with compressed technical support.
OEM direct procurement sits at the top of the volume ranking, with aftermarket channels climbing the fastest.
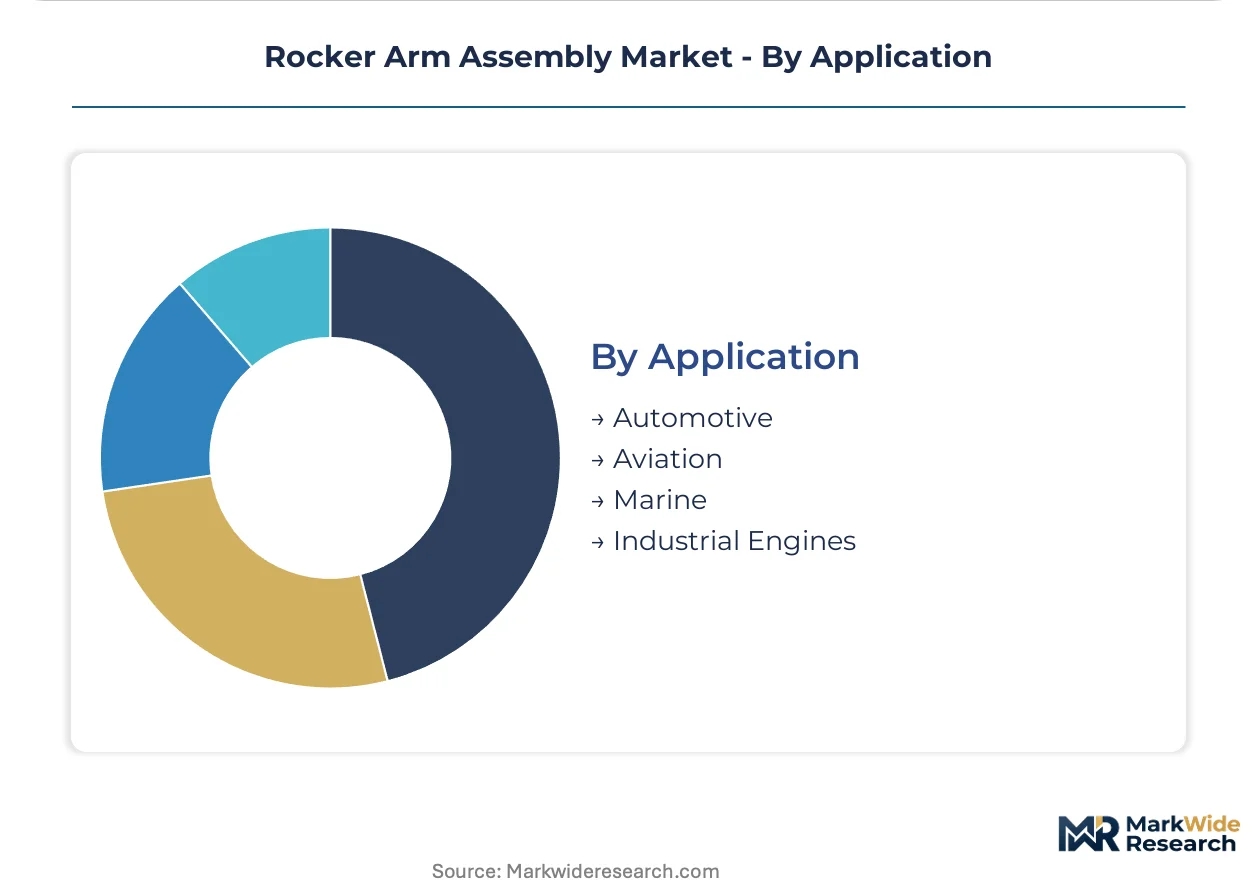
Application:
Application scope spans mobility and stationary power generation, with marine and industrial segments exhibiting divergent replacement cycle economics.
- Automotive:Light-duty passenger cars and commercial trucks consume the majority of production volume. Downsized turbocharged gasoline and EPA Tier 4 diesel architectures drive friction-reduction specifications.
- Aviation:Piston engine general aviation and emerging urban air mobility concepts require weight-optimized valvetrain components.
- Marine:Commercial diesel propulsion and auxiliary generators in Southeast Asian and Mediterranean ports face accelerating retrofit demand.
- Industrial Engines:Backup power generators, oilfield equipment, and agricultural machinery operate on extended amortization horizons with aftermarket replacement concentration.
Automotive sits at the top of the volume ranking, with marine applications climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision engine manufacturing clusters in Germany, Japan, and the United States concentrate global rocker arm assembly procurement, with regulatory pressure from EPA Tier 4 and Euro 7 standards reshaping supplier qualification requirements across all three markets.
United States
Commercial vehicle OEMs in Detroit and the Midwest are standardizing shaft-mounted rocker arm configurations across heavy-duty engine platforms to compress service part inventories. EPA Tier 4 emissions enforcement compels sub-micron tolerance validation for friction-reducing components. The Inflation Reduction Act's domestic content provisions are qualifying North American forged component sources for clean vehicle tax credit supply chains.
Germany
Automotive powertrain engineering in Stuttgart and Munich drives demand for advanced surface coating technologies that extend component durability under high-cycle fatigue. EU Green Deal CBAM reporting requirements accelerate investment in electric induction heating and closed-loop forging processes to maintain OEM qualification status. Baden-Württemberg foundry clusters face embedded carbon disclosure pressure on micro-alloyed steel inputs.
Japan
Passenger car OEMs in Toyota City and Nagoya specify aluminum alloy rocker arms for downsized turbocharged engines where reciprocating mass reduction improves throttle response. METI fuel efficiency benchmarking rewards sub-system innovations including low-friction rocker arm geometries. Japanese machine tool operators in Aichi Prefecture concentrate sub-micron grinding capacity for roller bearing contact surfaces.
China
Domestic automotive production in Shanghai and the Yangtze River Delta generates volume demand for cost-optimized steel rocker arm configurations. Dual carbon goals under MIIT oversight are pressuring foundry energy intensity in Jiangsu and Zhejiang provinces. Local coating equipment suppliers are entering the European supply base with diamond-like carbon deposition systems.
South Korea
Hyundai Motor Group and Kia powertrain procurement in Ulsan and the Seoul Capital Area prioritizes roller rocker arm designs for high-RPM gasoline architectures. MFDS-equivalent automotive component standards align with EPA durability protocols for export qualification. Busan-Gyeongnam industrial corridors host precision machining capacity serving both domestic OEM and marine aftermarket channels.
Rocker Arm Assembly Market Vendor Landscape
Portfolio diversification dominates the current landscape as tier-one suppliers reposition around modular valvetrain subsystems. The vendor base organizes around three strategic archetypes: integrated powertrain specialists, precision component fabricators, and aftermarket performance distributors. M&A activity and technology licensing agreements represent the dominant competitive moves, with particular intensity around surface coating and lightweight material capabilities.
Among German-anchored powertrain integrators, Schaeffler Technologies AG and Mahle GmbH exemplify the specialist tier that has secured direct OEM technical center contracts bypassing historical engine block supplier relationships. BorgWarner Inc. occupies a position on the North American commercial vehicle vector where unbundled valvetrain sourcing is most visible. These three entities represent the consolidation pressure that mid-scale fabricators face as OEM procurement centralizes around platform-spanning modular solutions.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Hitachi Automotive Systems |
| Schaeffler Technologies AG |
| Rane Group |
| Aisin Seiki Co., Ltd. |
| Federal-Mogul Motorparts (Tenneco Inc.) |
| Mahle GmbH |
| Comp Cams |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
Micro-alloyed steel ingot costs cascade through three distinct pricing tiers as forged components move from Baden-Württemberg foundry clusters through tier-two machining operations to OEM direct procurement contracts. Energy-intensive electric arc furnace operations in European foundries concentrate pricing power upstream while downstream buyers negotiate long-term offtake agreements to buffer scrap metal flow volatility.
Pricing Analysis
Distributor markups separate premium roller bearing configurations from standard stud-mounted variants across aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation with EPA Tier 4 validation commanding substantial premiums over non-certified alternatives. Cost compression in economy-tier steel configurations is intensifying because Chinese coating equipment suppliers are entering European supply bases with competitive DLC deposition systems. Aftermarket repair shops exhibit highest price sensitivity while commercial vehicle OEMs prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Detroit and Stuttgart powertrain engineering centers while aftermarket distributors serve fragmented marine and stationary engine replacement cycles. Geographic concentration centers on Germany, Japan, and the United States for precision grinding capacity and surface coating expertise. Raw material flows draw from hardened tool steel suppliers in European foundry clusters and aluminum alloy producers serving Japanese OEM specifications. Single-source vulnerability concentrates among Japanese and German machine tool operators controlling sub-micron superfinishing capacity for roller bearing contact surfaces. Distribution runs through tier-one modular subsystem specialists that have displaced historical engine block integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rocker arm assembly market functions as a stable compounder anchored by marine and stationary engine aftermarket replacement cycles that extend revenue visibility beyond automotive electrification timelines.
For Market Incumbents: Cement platform-spanning modular qualifications across gasoline, diesel, and alternative fuel architectures to amortize homologation investments. Deepen backward integration into electric induction heating and closed-loop forging processes to satisfy EU Green Deal CBAM reporting requirements. Prioritize direct technical center contracts with commercial vehicle OEMs in the United States where unbundled valvetrain sourcing is accelerating.
For New Entrants and Emerging Players: Launch via marine aftermarket distribution networks in Southeast Asian ports where EPA Tier 4 retrofit deadlines are concentrating replacement demand. Target shaft-mounted rocker arm configurations for heavy-duty diesel platforms where German and US OEMs are standardizing across engine families to compress service inventories. Pursue qualification under US Inflation Reduction Act domestic content provisions to access clean vehicle tax credit supply chains.
For Investors and Strategic Acquirers: Roll-up economics work for precision machining specialists with captive sub-micron grinding capacity because Japanese and German machine tool operators face no near-term replication threat from emerging competitors. Five-to-ten year viability hinges on aftermarket exposure to marine and industrial segments with extended replacement cycles. Monitor battery electric vehicle production ramp announcements in key automotive markets as the critical signal for internal combustion engine platform development budget compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Surface Coating Technology Licensing | DLC and PVD deposition capabilities differentiate suppliers under EPA Tier 4 durability protocols. |
| Platform Standardization | Shaft-mounted configurations across heavy-duty engine families reduce service part complexity for commercial vehicle OEMs. |
| Long-term Supply Agreement | Direct OEM contracts bypass historical engine block integrators and secure volume commitments. |
| Geographic Manufacturing Footprint | North American forged component qualification captures Inflation Reduction Act domestic content incentives. |
| Joint Venture | Technology partnerships with Chinese coating equipment suppliers accelerate cost-optimized DLC production scale. |
Methodological Framework
Direct dialogue with powertrain engineering directors, tier-one supplier procurement managers, aftermarket distribution heads, and foundry operations leaders grounded qualitative assessment in operational reality. Secondary validation drew from EPA certification databases, EU ETS emissions records, METI fuel efficiency benchmarking reports, and automotive production registration data. Bottom-up and top-down triangulation reconciled component-level shipment estimates with aggregate OEM platform production schedules.
Bottom-up volume modeling segmented by contact mechanism, material grade, end-user channel, and application vertical across the analysis window. Top-down demand calibration referenced powertrain platform development budgets and aftermarket replacement cycle economics by vehicle parc age distribution. CAGRs were derived from regression analysis against historical production correlations with vehicle sales and industrial engine installation rates. Forecast inputs incorporated electrification timeline scenarios and regulatory phase-in schedules for emissions standards.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated battery electric vehicle adoption or extended internal combustion engine platform lifecycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Africa Automotive Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market