
 Electric Drive Mining Truck Market | 2026-2036
Electric Drive Mining Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Drive Mining Truck Market Analysis
Open-pit copper mining is pivoting toward electrified haulage as ore depths expand and diesel cost volatility erodes operating budgets. Caterpillar dominates the ultra-class segment through its integrated powertrain development and field validation programs. Komatsu leverages its autonomous haulage architecture to anchor electric drive retrofits across Australian and South American mine sites. BELAZ sustains its position in high-latitude operations through cold-climate battery thermal management specialization.
Electric drive mining trucks employ wheel-motor or axle-mounted electric propulsion systems, typically powered by onboard battery packs or trolley-assist infrastructure, with regenerative braking recovering kinetic energy during downhill loaded haul cycles to extend range and reduce thermal load on friction brakes. Heavy-duty trucks and ultra-class trucks concentrate current revenue as tier-one miners replace diesel mechanical drive fleets in high-tonnage, low-gradient applications. Battery electric technology leads capital deployment, while hybrid electric configurations retain share in remote deposits lacking grid interconnection or charging infrastructure.
EPA greenhouse gas standards for heavy-duty vehicles and the EU Green Deal industrial emissions framework are tightening compliance windows for mining equipment procurement, effectively mandating electrification pathways in jurisdictions with enforceable carbon pricing. China's MIIT dual carbon goals and GB standards for new energy commercial vehicles are reshaping export specifications from dominant manufacturing clusters in Xuzhou and Changsha. Stakeholders must monitor trolley-assist infrastructure buildout timelines and battery swap standardization across OEM platforms to de-risk fleet conversion economics.
Market Dynamics
Trolley-assist infrastructure deployment is compressing total cost of ownership curves for battery-electric haulage in deep open-pit operations, redirecting capital from diesel fleet renewal toward grid interconnection and charging hardware.
Growth Catalysts
- EPA greenhouse gas standards:Heavy-duty vehicle tailpipe limits in the United States are compelling open-pit operators to accelerate electrification procurement timelines.
- Regenerative braking systems:Kinetic energy recovery during downhill loaded haul cycles extends battery range and reduces friction brake maintenance in Pilbara iron ore operations.
- Copper extraction depth expansion:Chilean open-pit operations are electrifying haul fleets as ore body depletion increases diesel fuel consumption per ton-mile.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack manufacturing clusters in China create input cost volatility and geopolitical exposure for fleet operators.
- Grid interconnection deficits:Remote deposits lacking transmission infrastructure cannot support pure battery-electric configurations without diesel hybrid fallback.
- REACH chemical compliance:EU battery recycling and end-of-life directives impose material traceability costs that inflate European procurement premiums.
Strategic Opportunities
- Battery swap standardization:Interoperable fast-exchange protocols across OEM platforms would de-risk fleet conversion economics for tier-one miners.
- MIIT dual carbon goals:China's manufacturing export specifications are reshaping equipment standards for battery-electric commercial vehicles globally.
- Trolley-assist retrofit kits:Pantograph infrastructure for existing diesel-electric trucks creates a bridge technology for mines with partial grid access.
Industry Challenges
- High-voltage technician scarcity:Battery-electric truck maintenance requires specialized electrical safety certification that mining labor pools currently lack.
- Legacy fleet integration:Mixed diesel-electric and battery-electric parcs complicate haul road scheduling and maintenance bay configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Drive Mining Truck Market |
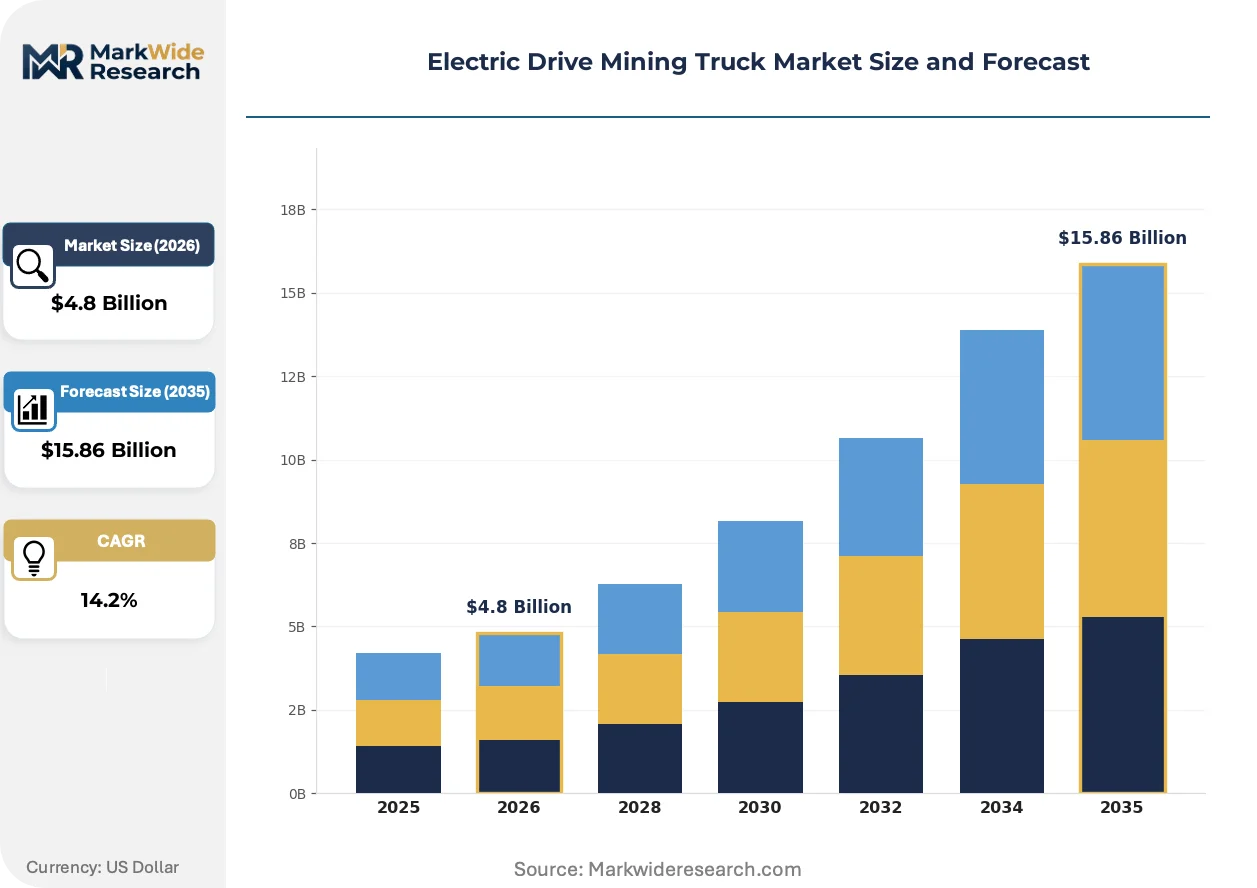
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Trucks, Articulated Trucks, Rigid Trucks, Ultra-Class Trucks Application: Open-Pit Mining, Underground Mining, Quarrying, Mineral Extraction End User: Mining Companies, Contractors, Service Providers, Government Entities Technology: Battery Electric, Hybrid Electric, Fuel Cell Electric, Regenerative Braking |
| Companies Covered | SANY, BELAZ, XCMG Group, LiuGong Machinery, Liebherr, Caterpillar, Yutong Heavy Industries, Zoomlion, Komatsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Drive Mining Truck Market Emerging Trajectories
Powertrain electrification is fragmenting competitive advantage away from engine manufacturing toward battery thermal management and charging infrastructure integration. Equipment suppliers are repositioning around energy system architecture rather than mechanical drive expertise.
Immersion cooling for battery packs is expanding into ultra-class haul trucks operating in high-ambient-temperature desert environments. Australian iron ore operators are piloting submerged cell architectures to sustain discharge rates during continuous duty cycles. This thermal approach is expanding into equipment specifications previously dominated by air-cooled diesel-electrics.
The EU Green Deal industrial emissions framework is tightening compliance windows for mining equipment procurement in European jurisdictions. Carbon pricing mechanisms are effectively mandating electrification pathways for new fleet investments. Open-pit operators in EU member states are responding by front-loading battery-electric pilot programs ahead of binding 2030 thresholds.
Buyers are unbundling after-sales service contracts from initial equipment procurement, forcing OEMs to price maintenance and battery replacement separately. Mining houses in Chile and Australia are negotiating power-by-the-hour agreements that transfer operational risk to suppliers. This contractual shift is most visible in Pilbara operations where Rio Tinto and BHP have structured autonomous electric drive programs around performance guarantees rather than asset ownership.
Electric Drive Mining Truck Market Segmentation
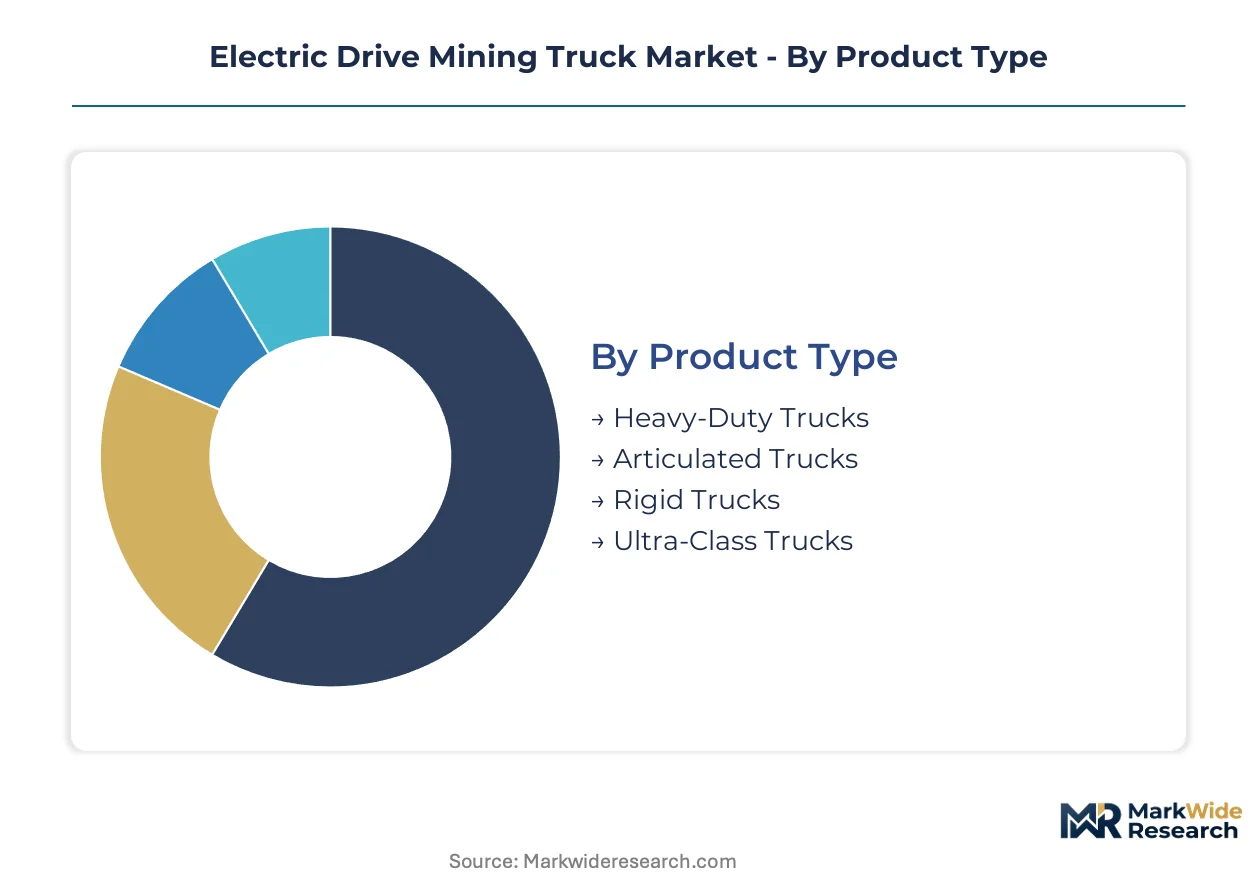
Segmentation in electric drive mining trucks reveals how electrification pathways diverge across operational contexts. Product configurations, deployment environments, and technology choices each impose distinct capital requirements and performance trade-offs that shape procurement decisions.
Product Type:
Volume concentrates in established payload classes where diesel replacement economics prove most favorable, while premium positioning clusters in emerging ultra-class platforms.
- Heavy-Duty Trucks:These vehicles integrate battery-electric powertrains into conventional 100-200 ton payload architectures, leveraging proven chassis designs with electric axle-mounted motors. Demand clusters in Australian iron ore surface operations where Rio Tinto and BHP have validated regenerative braking performance on fixed haul routes. Operating cost compression from eliminated diesel fuel drives fleet conversion timelines.
- Ultra-Class Trucks:Next-generation 300+ ton platforms employ immersion-cooled battery packs and high-voltage wheel motors to sustain continuous duty cycles in high-ambient desert environments. Chilean copper operators in the Atacama are accelerating procurement as ore depth expansion erodes diesel haulage margins. Thermal management sophistication distinguishes competitive positioning.
- Articulated Trucks:Maneuverable six-wheel-drive configurations serve narrow-vein underground extraction where turning radius constraints dominate equipment selection. Scandinavian underground contractors favor these platforms for battery-electric retrofits.
- Rigid Trucks:Fixed-frame haulers dominate high-volume, low-gradient surface applications with simplified maintenance access. Quarrying operations in Germany and France specify rigid electric platforms under EU Green Deal procurement mandates.
Today's leader: Heavy-Duty Trucks. Tomorrow's challenger: Ultra-Class Trucks.
Application:
Surface extraction commands equipment volumes while underground deployment accelerates fastest as ventilation cost reduction becomes decisive.
- Open-Pit Mining:Large-scale surface operations with fixed haul routes optimize trolley-assist infrastructure investment, enabling battery-electric trucks to draw grid power on uphill segments. Australian Pilbara iron ore belt installations demonstrate this hybrid electrification model at commercial scale. Regenerative braking recovery on downhill loaded cycles extends effective range without battery capacity expansion.
- Underground Mining:Confined-space extraction benefits from eliminated diesel particulate emissions, reducing ventilation infrastructure capital and operating costs. Canadian hard-rock operators in Ontario and Quebec are front-loading battery-electric procurement ahead of provincial carbon pricing thresholds. Diesel exhaust exposure regulations tighten compliance windows.
- Quarrying:Aggregate extraction near population centers faces community pressure and local air quality enforcement that favors zero-tailpipe configurations. UK and German limestone quarries specify battery-electric fleets under national industrial emissions frameworks.
- Mineral Extraction:Diverse commodity recovery operations spanning potash, lithium, and rare earth deposits employ specialized truck configurations matched to ore body characteristics. Chilean lithium brine operations in the Salar de Atacama pilot fuel-cell electric alternatives.
Surface extraction dominates current deployment. Underground applications are expanding most quickly as ventilation economics improve.
End User:
Integrated mining houses drive specification standards while contractor fleets prioritize interoperability across multiple client sites.
- Mining Companies:Vertically integrated operators with captive haul routes invest in purpose-built electric fleets with dedicated charging infrastructure. BHP and Rio Tinto in Australia structure autonomous electric programs around performance guarantees rather than asset ownership.
- Contractors:Third-party haulage providers require battery swap standardization across OEM platforms to service diversified client portfolios. Chilean copper contractors negotiate power-by-the-hour agreements that transfer operational risk to suppliers.
- Service Providers:Maintenance and logistics specialists acquire electric support vehicles for pit operations, though primary haulage remains outside their scope.
- Government Entities:State-owned mining enterprises in China and Kazakhstan specify domestic battery-electric platforms under MIIT dual carbon procurement guidelines.
Integrated miners set technology direction. Contractor adoption depends on standardization progress.
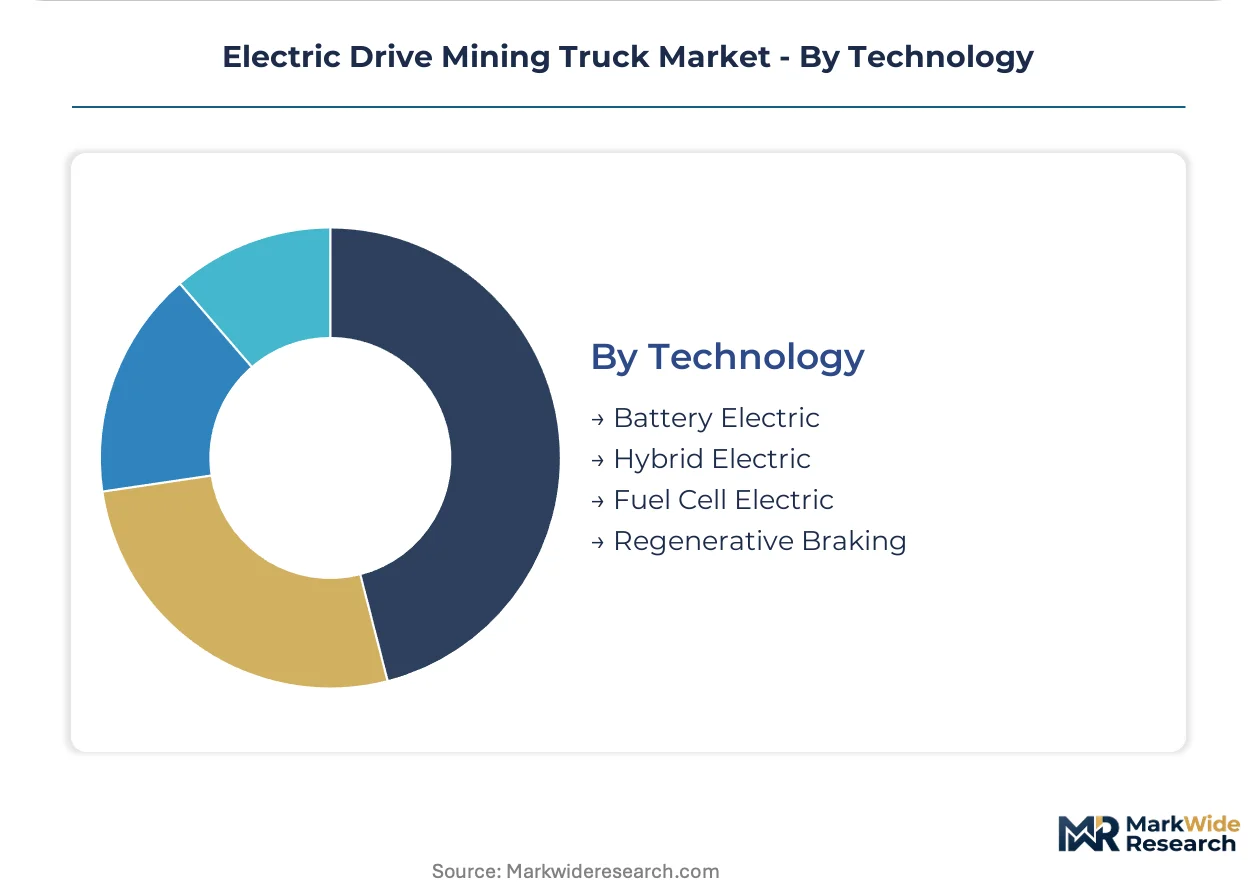
Technology:
Battery electric captures capital deployment while hybrid configurations retain share in grid-deficient locations.
- Battery Electric:Onboard lithium-ion packs power wheel motors with regenerative braking recovery, eliminating tailpipe emissions entirely. Australian and Chilean surface operations lead commercial deployment where grid interconnection supports charging infrastructure.
- Hybrid Electric:Diesel range extenders or fuel cells supplement battery capacity for remote deposits lacking transmission access. Canadian Arctic and Mongolian operations specify hybrid fallback for grid-deficient sites.
- Fuel Cell Electric:Hydrogen proton-exchange membrane systems enable rapid refueling for continuous-duty applications where battery swap logistics prove prohibitive. South African platinum miners pilot fuel-cell trucks to align with national hydrogen economy strategies.
- Regenerative Braking:Kinetic energy recovery systems are standard across all electric architectures, extending range 15-25% on net-elevation-drop haul routes. Pilbara iron ore operations validate this technology at scale.
Battery electric leads current investment. Fuel cell configurations are gaining share fastest where charging infrastructure constraints bite hardest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting equipment procurement toward jurisdictions with enforceable carbon pricing and grid infrastructure investment, compressing electrification timelines in compliant markets while deferring conversion in enforcement gaps.
Australia
The Pilbara iron ore belt anchors commercial deployment of autonomous electric haul fleets, with Rio Tinto and BHP validating regenerative braking performance on fixed downhill routes. TGA-aligned mining safety standards and state-level carbon reduction mandates in Western Australia accelerate fleet conversion timelines. Perth-based engineering clusters specialize in trolley-assist infrastructure integration for ultra-class platforms.
Chile
Atacama Desert copper operations are electrifying haul fleets as ore body depletion increases diesel consumption per ton-mile. National mining regulators enforce progressive emissions thresholds that compel open-pit operators to front-load battery-electric procurement. Antofagasta and Calama industrial zones concentrate thermal management engineering for high-ambient desert environments.
United States
EPA greenhouse gas standards for heavy-duty vehicles are compelling open-pit operators in Arizona and Nevada to accelerate electrification procurement. Stricter tailpipe limits effective through 2027 compress compliance windows for diesel fleet renewal. Tucson and El Paso engineering corridors develop retrofit kits for existing diesel-electric trucks.
China
MIIT dual carbon goals and GB standards for new energy commercial vehicles reshape domestic and export equipment specifications. State-owned mining enterprises in Inner Mongolia and Shanxi specify battery-electric platforms under national procurement guidelines. Xuzhou and Changsha manufacturing clusters dominate global supply of ultra-class electric drive powertrains.
Canada
Ontario and Quebec hard-rock operators front-load battery-electric procurement ahead of provincial carbon pricing thresholds, driven by diesel exhaust exposure regulations in confined underground environments. Health Canada and provincial mining regulators tighten ventilation cost accounting that favors zero-tailpipe configurations. Sudbury and Val-d'Or mining technology corridors specialize in cold-climate battery thermal management.
Electric Drive Mining Truck Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated powertrain developers commanding premium positioning in ultra-class applications while regional fabricators capture retrofit and mid-payload niches. Market structure concentrates around three strategic archetypes: diversified industrial conglomerates with captive mining equipment divisions, pure-play mining truck specialists with deep desert or arctic operational expertise, and construction equipment crossovers leveraging shared electric axle platforms. Competitive dynamics center on M&A activity targeting battery thermal management capabilities and strategic partnerships for trolley-assist infrastructure deployment.
Within the diversified industrial tier, Caterpillar and Komatsu anchor global positioning through integrated autonomous haulage architectures and field validation programs across Australian and South American mine sites. BELAZ occupies a distinct specialization tier focused on high-latitude and extreme-climate operations, exemplifying how geographic operational focus can sustain defensible positioning against broader-portfolio competitors. SANY and XCMG Group represent the Chinese manufacturing cluster that is reshaping export specifications through MIIT-aligned dual carbon production standards.
| Leading Market Players |
|---|
| SANY |
| BELAZ |
| XCMG Group |
| LiuGong Machinery |
| Liebherr |
| Caterpillar |
| Yutong Heavy Industries |
| Zoomlion |
| Komatsu |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate spot indices cascading from Chinese battery-grade benchmarks compress procurement premiums for tier-one miners while amplifying volatility exposure for operators locked into single-source cell contracts. This input cost structure stratifies equipment pricing across three distinct tiers: integrated powertrain packages with captive thermal management, modular retrofit architectures with third-party battery integration, and basic electric axle conversions retaining legacy chassis.
Pricing Analysis
Distributor margins for ultra-class platforms absorb 12-18 points before mine-site delivery, compressing OEM net pricing power and forcing direct-to-fleet negotiations for volume deployments. Three-tier pricing structure across premium, standard, and economy levels separates immersion-cooled integrated systems from air-cooled modular retrofits and basic axle-swap configurations. Cost compression in the mid-tier is intensifying because Chinese manufacturing clusters are exporting GB-standard platforms at reduced certification overhead. Contractor fleets exhibit highest price sensitivity due to multi-client interoperability requirements, while integrated mining houses prioritize performance guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from Australian and Chilean procurement teams require battery cell qualification across at least two manufacturing clusters, typically pairing Chinese cylindrical cell supply with South Korean prismatic alternatives. Geographic supply concentration centers on China for lithium-ion pack assembly, South Korea for high-nickel cathode chemistry, and Japan for battery management system semiconductors. Raw material dependencies draw from Chilean lithium brine, Indonesian nickel laterite, and DRC cobalt hydroxide. Single-source vulnerability concentrates in high-voltage power electronics where European and Japanese suppliers dominate insulated-gate bipolar transistor fabrication. Distribution runs through OEM-authorized service depots in Perth, Santiago, and Tucson before final mine-site commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in electric drive mining trucks rests on battery pack cost-down curves and the shift toward power-by-the-hour service contracts that capture aftermarket value. Equipment suppliers capturing thermal management IP and charging infrastructure integration command sustainable premium positioning.
For Market Incumbents: Acquire battery thermal management engineering capabilities to defend against modular retrofit specialists eroding integrated powertrain premiums. Prioritize backward integration into immersion cooling system production to lock in high-ambient desert performance advantages. Capacity addition in Perth and Antofagasta service corridors reinforces proximity to Pilbara and Atacama fleet concentrations. Certification investment in TGA-aligned safety standards creates procurement friction against unvalidated entrants.
For New Entrants and Emerging Players: Cold-climate battery preconditioning technology offers a technology-first wedge into Canadian and Scandinavian underground markets where incumbent desert specialization underperforms. Target narrow-vein articulated truck retrofits in Ontario and Quebec hard-rock operations as the most penetrable segment before surface haulage scale. Channel partnership with established underground mining contractors accelerates reference validation without captive fleet capital.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier battery pack assemblers possessing OEM-agnostic swap standardization protocols. Long-term viability hinges on interoperability certification across Caterpillar, Komatsu, and SANY platform architectures. Acquisition target archetype: regional engineering firms with trolley-assist pantograph integration expertise and existing mine-site relationships. Battery swap standardization announcements from MIIT or EPA serve as the critical inflection signal to monitor.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Thermal Management Acquisition | Secures high-ambient performance differentiation in Atacama and Pilbara operations. |
| Trolley-Assist Infrastructure Partnership | Enables hybrid electrification for grid-constrained Chilean copper deposits. |
| Battery Swap Standardization Development | Reduces contractor fleet interoperability costs across multi-OEM parcs. |
| Cold-Climate Platform Engineering | Opens Ontario and Quebec underground markets with ventilation cost advantages. |
| Power-by-the-Hour Service Launch | Transfers operational risk from BHP and Rio Tinto to equipment suppliers. |
Methodological Framework
Direct dialogue with mine maintenance directors, OEM procurement teams, battery system engineers, and aftermarket service heads grounded qualitative findings in operational constraints and fleet conversion timelines. Secondary validation drew from EPA regulatory filings, MIIT equipment certification databases, Australian TGA safety standards, and Chilean mining ministry emissions disclosures. Bottom-up unit economics modeling triangulated against top-down carbon pricing scenario analysis.
Installed base projections and revenue estimates emerged from segmented modeling across payload class, propulsion architecture, mine type, and regional regulatory framework throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, diesel-electric parity threshold tracking, and infrastructure investment pipeline assessment. Key inputs included lithium carbonate price volatility bands, grid interconnection project timelines, and autonomous haulage adoption rates.
The model holds under stable battery chemistry cost curves and progressive carbon pricing enforcement; deviation in raw material supply disruption or regulatory rollback would shift the outlook materially. Deviation in trolley-assist infrastructure deployment schedules or battery swap standardization consensus would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Van Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Farm Trucks Market