
 Automotive Knock Sensor Market | 2026-2036
Automotive Knock Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Knock Sensor Market Analysis
Aftermarket sensor replacement revenue is rewriting margin distribution across the value chain. Robert Bosch GmbH leverages its integrated powertrain electronics portfolio to dominate OEM supply contracts for piezoelectric knock modules. Continental AG anchors its position through captive semiconductor design via Infineon Technologies AG, which sustains die-level cost control for resonant frequency sensing elements.
An automotive knock sensor detects abnormal combustion events through piezoelectric crystal vibration measurement, typically operating across a resonant frequency range of 5 to 15 kHz to trigger engine control unit timing retard and prevent piston damage. The device serves the essential commercial purpose of enabling higher compression ratios and turbocharged operation without destructive detonation. Piezoelectric sensors occupy the mature volume tier where unit economics favor established ceramic manufacturing processes, while smart sensors represent the fastest-expanding technology segment as embedded signal processing reduces wiring complexity and enables predictive diagnostics. Passenger vehicles generate the dominant application demand due to four-cylinder turbocharged engine proliferation, though performance vehicles concentrate the premium sensor tier where motorsport-derived calibration tolerances command superior pricing.
The EPA in the United States and the EU Green Deal framework in Europe enforce emissions thresholds that tighten knock margin tolerances and expand sensor specification requirements across vehicle classes. Japan's METI coordinates domestic standards alignment with ISO knock test protocols, ensuring Japanese Tier-1 suppliers maintain cross-border certification efficiency. Stakeholders must monitor how software-defined engine calibration platforms displace hardware-dedicated knock channels, as ECU consolidation threatens standalone sensor unit volumes while creating openings for multi-function integrated modules.
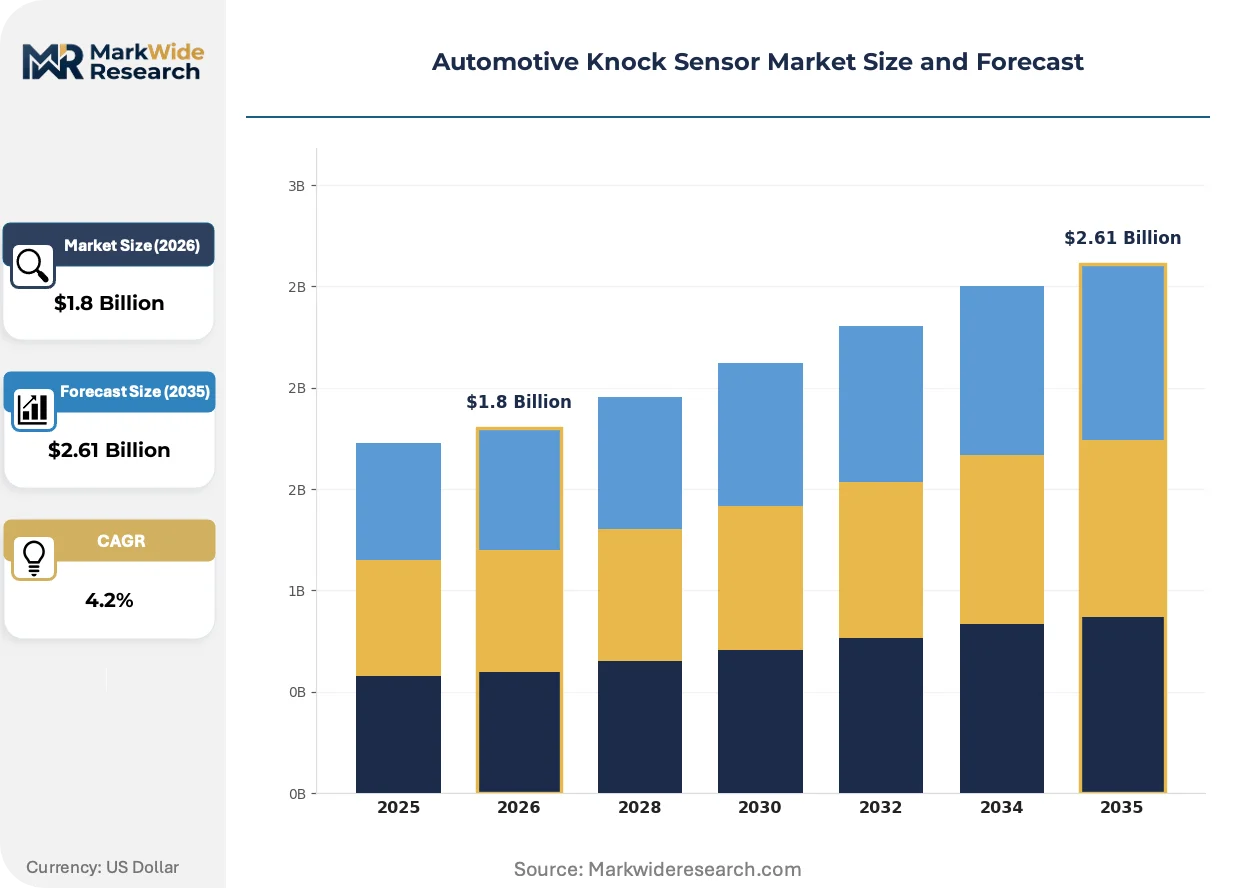
Market Dynamics
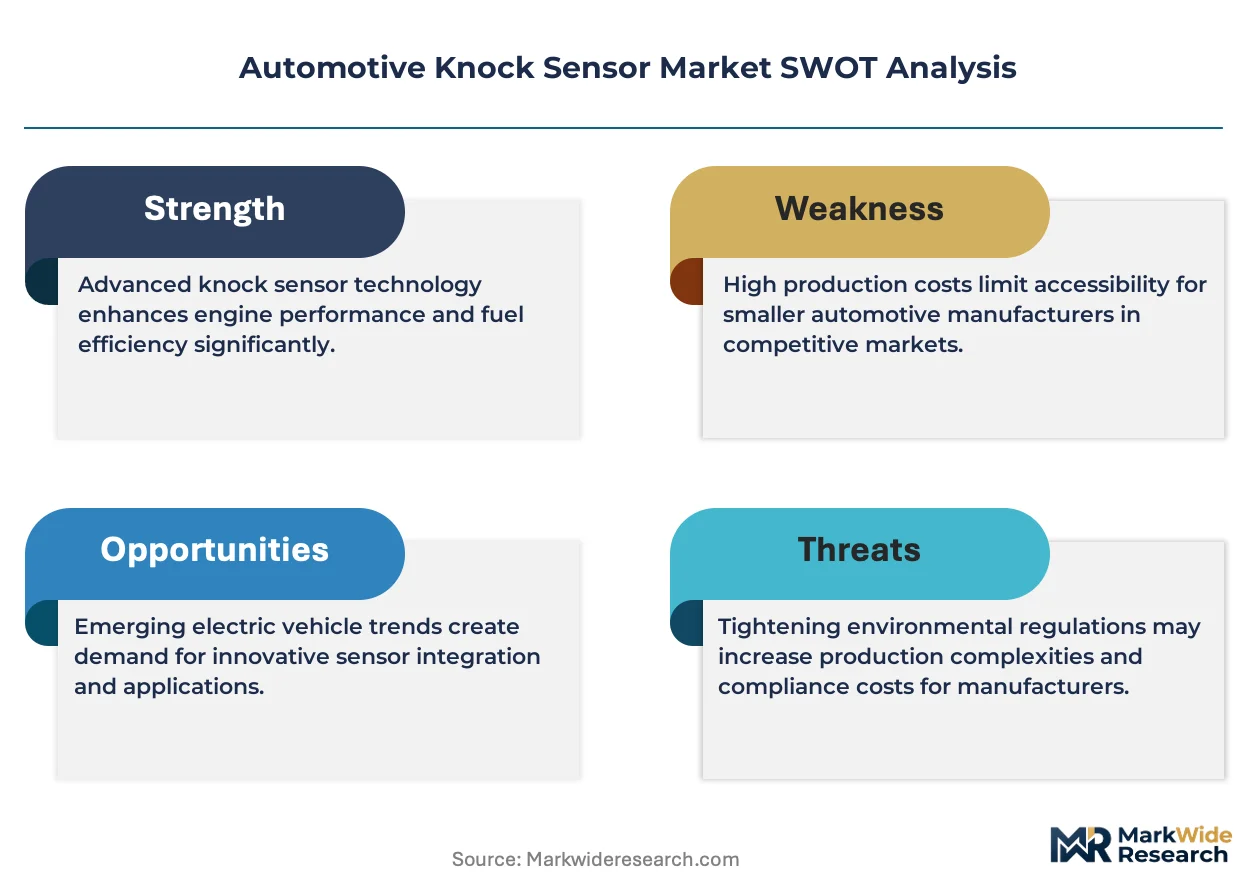
The automotive knock sensor market is being fundamentally restructured by ECU consolidation architectures that compress standalone sensor channels into multi-function integrated modules, forcing suppliers to pivot from discrete component sales toward embedded system partnerships.
Growth Catalysts
- Turbocharged engine proliferation:OEMs in Germany, Japan, and the United States are specifying higher compression ratios that demand precise detonation detection, expanding sensor attach rates across passenger vehicle lineups.
- EU Green Deal enforcement:The framework's tightening tailpipe emissions thresholds mandate calibration precision that relies on accurate knock detection for combustion optimization.
- Piezoelectric ceramic manufacturing scale:Mature ceramic processing in established production clusters delivers unit economics that sustain volume tier competitiveness for resonant frequency sensing elements.
Market Restraints
- ECU channel consolidation:Software-defined engine calibration platforms are compressing dedicated knock sensor volumes as multi-function modules absorb discrete detection functions.
- Raw material concentration:Lead zirconate titanate piezoelectric crystal supply concentrates in East Asian ceramic foundries, creating input vulnerability for Western module assemblers.
- Smart sensor cost premium:Embedded signal processing and predictive diagnostics capabilities carry die-level cost penalties that limit penetration in economy vehicle segments.
Strategic Opportunities
- Predictive diagnostics integration:Smart sensors combining vibration measurement with onboard algorithms open aftermarket service revenue streams through failure prediction capabilities.
- Performance vehicle premium tier:Motorsport-derived calibration tolerances in high-performance engines command superior pricing for sensors meeting tighter specification bands.
- ISO knock test protocol alignment:Japan's METI coordination of domestic standards with international certification frameworks enables Japanese suppliers to maintain cross-border market access efficiency.
Industry Challenges
- Signal processing engineering scarcity:Embedded firmware development for resonant frequency analysis competes with broader automotive electronics talent pools, extending R&D timelines.
- Legacy ECU integration complexity:Backward compatibility requirements with established engine control architectures constrain smart sensor architecture decisions and delay platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Knock Sensor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Piezoelectric Sensors, MEMS Sensors, Capacitive Sensors, Inductive Sensors Technology: Analog Sensors, Digital Sensors, Wireless Sensors, Smart Sensors End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Performance Vehicles |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Delphi Technologies, Sensata Technologies Inc., NGK Spark Plugs, Hitachi Ltd., Infineon Technologies AG, CTS Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Knock Sensor Market Emerging Trajectories
Knock detection technology is converging with powertrain electronics consolidation, compressing the traditional boundary between standalone sensors and integrated control modules while enabling new diagnostic capabilities.
Capacitive MEMS-based knock sensing is rendering obsolete conventional piezoelectric crystal assemblies in next-generation engine architectures. Tier-1 suppliers in Germany and Japan are qualifying MEMS devices for 2027+ vehicle platforms. The shift is rendering obsolete the ceramic resonator supply chain that has dominated volume production for three decades.
EPA emissions enforcement in the United States is mandating tighter knock margin tolerances across light-duty vehicle classes. The regulatory pressure forces calibration precision that expands sensor specification requirements and accelerates smart sensor adoption. Powertrain engineering centers in Detroit and Stuttgart are responding with enhanced detection bandwidth specifications.
Fleet operators are unbundling sensor replacement from full powertrain service contracts, creating direct procurement relationships with component suppliers. Independent repair networks in North America and Western Europe are capturing aftermarket volume previously channeled through dealer service departments. The disintermediation is most visible in commercial vehicle segments where total cost of ownership optimization drives component-level sourcing decisions.
Automotive Knock Sensor Market Segmentation
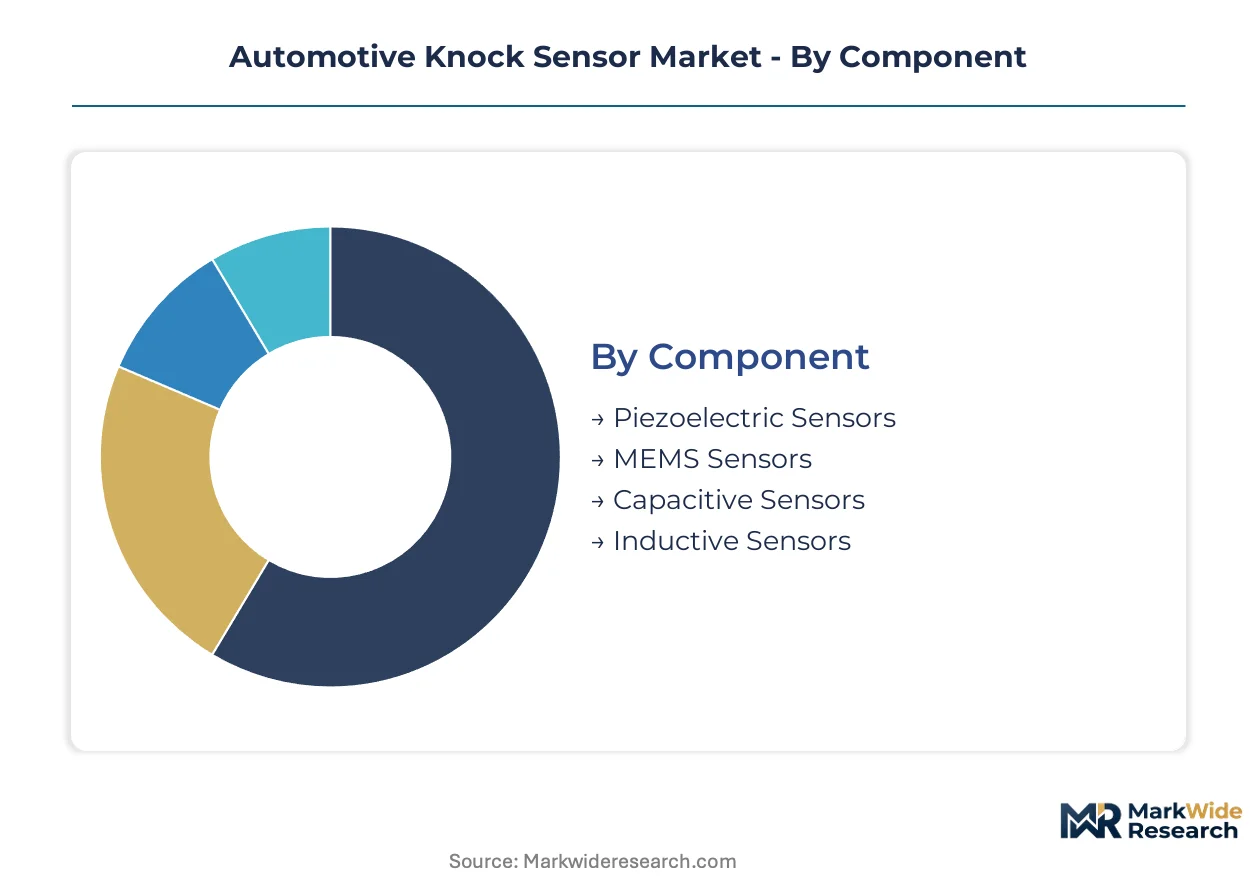
Knock sensor procurement patterns diverge sharply between OEM specification cycles and aftermarket replacement demand, with service intervals and failure modes determining margin capture across distinct channel configurations. Understanding how component technologies, digital architectures, and end-user procurement behaviors fragment the addressable market enables suppliers to align R&D investment with revenue concentration points.
Component:
After-sales service intensity varies dramatically by sensing element type, with piezoelectric modules dominating warranty replacement volumes while MEMS devices concentrate diagnostic-related service events in newer vehicle populations.
- Piezoelectric Sensors:Ceramic crystal assemblies utilizing lead zirconate titanate compounds generate electrical signals through mechanical vibration stress, operating reliably across the 5-15 kHz resonant band essential for detonation detection. Demand concentrates in Germany, Japan, and the United States where established powertrain engineering centers specify mature ceramic manufacturing processes for volume passenger vehicle programs, though ECU consolidation pressures threaten standalone unit growth.
- MEMS Sensors:Micro-electromechanical systems fabricated through semiconductor lithography integrate capacitive sensing structures with onboard signal conditioning, enabling smaller form factors and reduced wiring complexity. Passenger vehicle turbocharged engine proliferation in Stuttgart and Detroit engineering clusters is accelerating qualification timelines for 2027+ platform integration, displacing traditional ceramic resonator supply chains.
- Capacitive Sensors:Electrostatic field variation detection offers alternative vibration transduction with reduced temperature sensitivity.
- Inductive Sensors:Electromagnetic coil assemblies provide legacy compatibility for established engine control architectures with minimal calibration disruption.
By volume, Piezoelectric Sensors leads. By growth pace, MEMS Sensors is ahead.
Technology:
Signal processing architecture determines the cost tier and diagnostic capability boundary, with analog foundations sustaining economy segment penetration while embedded intelligence commands premium positioning.
- Smart Sensors:Integrated microcontrollers execute resonant frequency analysis algorithms onboard, enabling predictive failure diagnostics and reduced ECU communication overhead. OEM procurement in Japan and Germany favors these modules for premium vehicle lineups where warranty cost reduction justifies die-level cost premiums, particularly as EPA emissions enforcement tightens calibration precision requirements.
- Digital Sensors:Serialized output protocols eliminate analog signal degradation across harness lengths, improving detection bandwidth for high-compression turbocharged applications. Powertrain engineering centers in the United States specify these for light-duty truck platforms where electromagnetic interference resilience is critical.
- Analog Sensors:Continuous voltage output interfaces with legacy engine control units through established hardware channels.
- Wireless Sensors:RF communication eliminates physical harness connections for simplified assembly and modular powertrain architectures.
Smart Sensors capture the steepest expansion trajectory as embedded processing displaces discrete detection hardware.
End User:
Procurement authority fragmentation across the value chain creates divergent pricing power dynamics, with vehicle assemblers consolidating specification control while aftermarket channels unbundle component sourcing from dealer service networks.
- OEMs:Original equipment manufacturers in Germany, Japan, and the United States direct powertrain specification through captive engineering centers, locking in multi-year supply agreements for piezoelectric and smart sensor variants. EU Green Deal enforcement is expanding sensor attach rates across vehicle classes as emissions thresholds mandate combustion optimization precision.
- Aftermarket Providers:Independent repair networks and direct procurement relationships with fleet operators are capturing replacement volume previously channeled through franchised dealers, particularly in North American commercial vehicle segments where total cost of ownership optimization drives component-level sourcing.
- Vehicle Assemblers:Contract manufacturing arrangements delegate final integration authority with limited component selection autonomy.
- Tier-1 Suppliers:Module integrators intermediate between sensor manufacturers and vehicle assemblers, consolidating specification influence.
OEMs dominate specification authority. Aftermarket Providers are gaining share fastest through channel disintermediation.
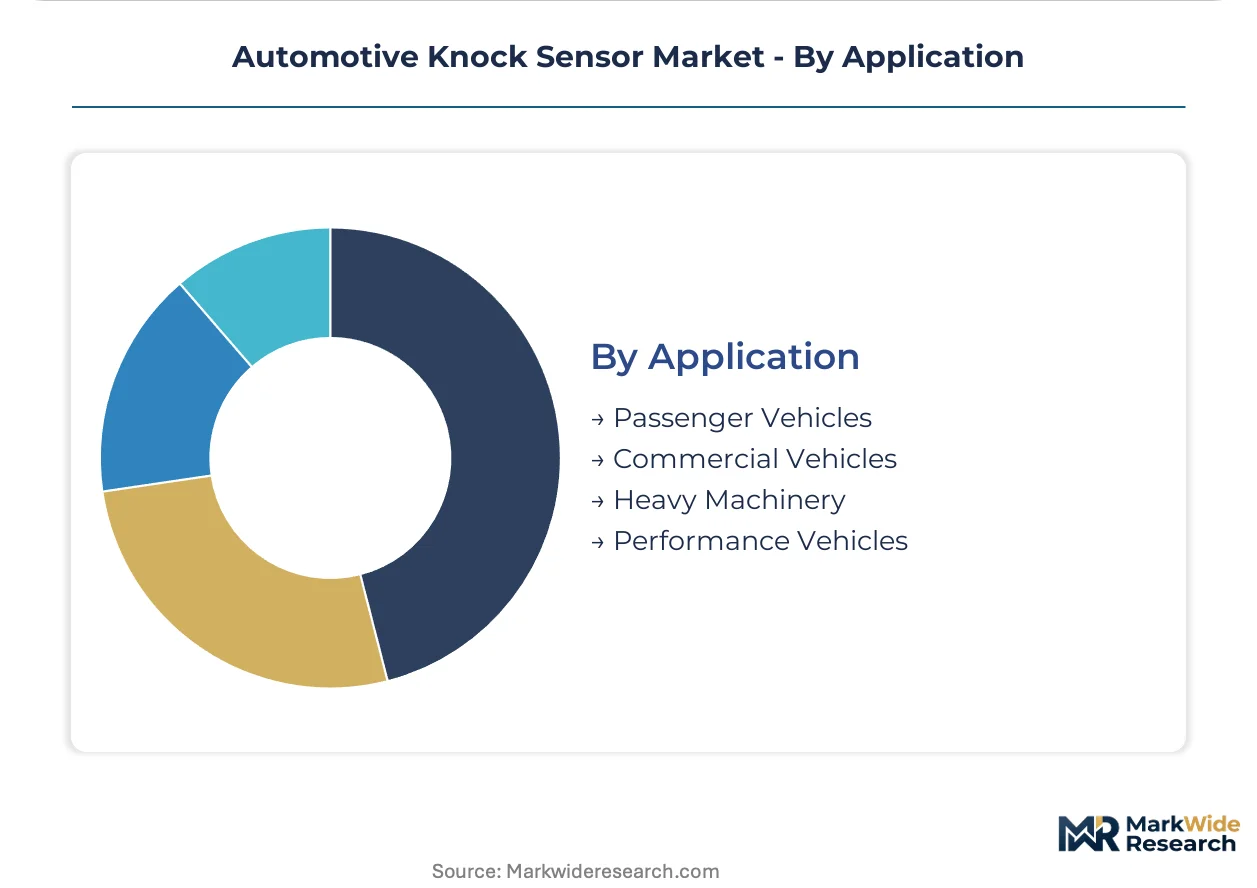
Application:
Engine duty cycle severity and calibration tolerance requirements stratify the market into volume, premium, and industrial tiers with distinct sensor specification bands and replacement frequency profiles.
- Passenger Vehicles:Four-cylinder turbocharged engine proliferation across compact and mid-size segments generates the dominant demand volume, with piezoelectric sensors satisfying cost targets for economy and standard trim levels while smart sensors penetrate premium lineups. Engineering centers in Germany and Japan specify these applications with tightening knock margin tolerances driven by EU and Japanese regulatory frameworks.
- Performance Vehicles:Motorsport-derived calibration tolerances and high-compression racing engine architectures command superior pricing for sensors meeting tighter specification bands, with demand concentrating in Stuttgart, Modena, and Detroit specialty vehicle programs where detection bandwidth and response latency are critical.
- Commercial Vehicles:Heavy-duty cycle accumulation accelerates wear-related replacement demand through aftermarket channels.
- Heavy Machinery:Off-highway equipment applications prioritize environmental sealing and mechanical durability over detection bandwidth.
Passenger Vehicles leads by installed base. Performance Vehicles commands the highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Knock sensor procurement patterns diverge sharply across geographies, with turbocharged gasoline engine penetration driving specification intensity in Germany and Japan while the United States emphasizes emissions-driven calibration precision.
United States
EPA enforcement mandates tighter knock margin tolerances across light-duty vehicle classes, expanding sensor specification requirements for domestic manufacturers. The Inflation Reduction Act's clean vehicle provisions accelerate turbocharged engine adoption in Detroit engineering clusters. Powertrain development centers in Michigan specify enhanced detection bandwidth for high-compression truck platforms.
Germany
EU Green Deal emissions thresholds force combustion optimization precision that relies on accurate knock detection for higher compression ratios. The KBA enforces type-approval standards that align with ISO knock test protocols for cross-border certification efficiency. Stuttgart-based engineering centers dominate smart sensor specification for premium vehicle lineups.
Japan
METI coordinates domestic standards alignment with international certification frameworks, ensuring Japanese suppliers maintain efficient cross-border market access. The country's powertrain engineering centers specify piezoelectric modules for volume passenger vehicle programs. Nagoya and Tokyo clusters concentrate qualification timelines for next-generation MEMS device integration.
China
MIIT fuel consumption regulations and dual carbon goals tighten engine efficiency requirements that expand knock sensor attach rates across domestic vehicle production. The country's automotive electronics supply chain concentrates ceramic resonator manufacturing for cost-competitive module assembly. Yangtze River Delta engineering centers accelerate smart sensor adoption for export-oriented vehicle platforms.
South Korea
Domestic manufacturers specify knock detection modules for turbocharged engine proliferation across compact and mid-size vehicle segments. The Seoul Capital Area anchors powertrain electronics development with integrated semiconductor design capabilities. Busan-Ulsan manufacturing clusters concentrate module assembly for both domestic OEM supply and regional export.
Automotive Knock Sensor Market Vendor Landscape
Capability concentration sits with integrated electronics specialists; scale advantage sits with established automotive component conglomerates. The market structure reflects a tiered hierarchy where captive semiconductor design and ceramic manufacturing processes create distinct competitive moats. Three archetypes dominate: diversified Tier-1 suppliers with powertrain electronics portfolios, specialized sensor manufacturers with resonant frequency expertise, and semiconductor firms supplying die-level sensing elements. Consolidation pressure manifests through ECU integration partnerships and multi-year OEM supply agreement extensions.
Within the diversified Tier-1 tier, Robert Bosch GmbH and Continental AG exemplify integrated powertrain electronics positioning, while DENSO Corporation anchors the specialized sensor manufacturer archetype with Japanese engineering center proximity. These three occupy positions where captive technology control and geographic clustering to OEM specification centers sustain contract renewal rates.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Delphi Technologies |
| Sensata Technologies Inc. |
| NGK Spark Plugs |
| Hitachi Ltd. |
| Infineon Technologies AG |
| CTS Corp. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in East Asian ceramic foundries is compressing input costs for piezoelectric crystal assemblies while forcing Western module assemblers into aggressive contract negotiations to defend margin structures.
Pricing Analysis
Long-term offtake agreements dominate procurement between OEMs and Tier-1 suppliers, with multi-year contracts locking in volume commitments for piezoelectric modules. Three-tier pricing structure across premium, standard, and economy levels separates motorsport-derived calibration tolerances from volume passenger vehicle specifications. Pricing pressure stems from ECU consolidation architectures that reduce standalone sensor attach rates. Economy vehicle segments exhibit highest price sensitivity, while performance vehicle programs tolerate die-level cost premiums for enhanced detection bandwidth.
Supply Chain Analysis
Extended payment terms from German and Japanese OEMs are squeezing working capital for module assemblers, accelerating supply-chain finance facility adoption among mid-tier suppliers. Lead zirconate titanate crystal production concentrates in China, Japan, and South Korea, creating geographic dependency for resonant frequency sensing elements. The supply chain rests on ceramic powder processing, semiconductor lithography equipment, and precision assembly tooling. Single-source vulnerability in East Asian ceramic foundries threatens input security. Distribution runs through captive Tier-1 integration partnerships and independent aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS-based knock sensing is disrupting three decades of piezoelectric dominance, with EPA emissions enforcement accelerating the technology inflection across Detroit and Stuttgart engineering clusters.
For Market Incumbents: Entrench position through backward integration into ceramic resonator manufacturing and captive semiconductor design partnerships. Defend against MEMS displacement by extending smart sensor firmware capabilities for predictive diagnostics. Prioritize certification investment for ISO knock test protocol alignment to sustain cross-border contract renewal rates.
For New Entrants and Emerging Players: Build out aftermarket diagnostic service platforms targeting fleet operator direct procurement relationships. The commercial vehicle segment offers lowest competitive density for failure prediction capabilities. Pursue white-label partnerships with independent repair networks in North America to bypass dealer service channel control.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MEMS fabrication capacity as semiconductor lithography equipment requirements displace ceramic processing infrastructure. Five-to-ten-year viability favors suppliers with integrated signal processing firmware stacks. Acquisition targets should demonstrate resonant frequency algorithm expertise. Monitor EPA enforcement intensity as regulatory acceleration signal.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Platform Qualification | Semiconductor lithography integration displaces ceramic resonator supply chains for 2027+ vehicle programs. |
| Smart Sensor Firmware Development | Embedded predictive diagnostics open aftermarket revenue streams through failure anticipation capabilities. |
| ISO Knock Test Certification Investment | Cross-border certification efficiency sustains Japanese supplier market access under METI coordination. |
| Aftermarket Channel Disintermediation | Fleet operator direct procurement bypasses dealer service networks in North American commercial segments. |
| ECU Consolidation Partnership | Multi-function module integration secures volume despite standalone sensor channel compression. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, vehicle production databases, and Tier-1 supplier disclosures. Interviews with OEM platform engineers, aftermarket distribution managers, and powertrain electronics procurement leads informed demand-side validation. Customs records, IHS Markit registration data, and EPA enforcement actions provided supply-side triangulation. Bottom-up sensor attach rate modeling and top-down powertrain electronics market sizing were cross-referenced for convergence.
Forecast inputs include turbocharged engine penetration rates, ECU consolidation adoption curves, and emissions threshold enforcement intensity across the analysis window. Segmentation dimensions span component technology, signal processing architecture, end-user procurement authority, and application duty cycle severity. CAGRs were derived from vehicle production forecasts, content-per-vehicle trajectory analysis, and replacement frequency modeling for aftermarket channels. MEMS qualification timelines and smart sensor cost curve assumptions shaped technology transition assumptions.
Practitioners should monitor EPA enforcement intensity, EU Green Deal implementation pace, and MEMS device qualification outcomes for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Global Airbag Systems Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Vehicle Barrier System Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market