
 Automotive Thrust Washer Market | 2026-2036
Automotive Thrust Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Thrust Washer Market Analysis
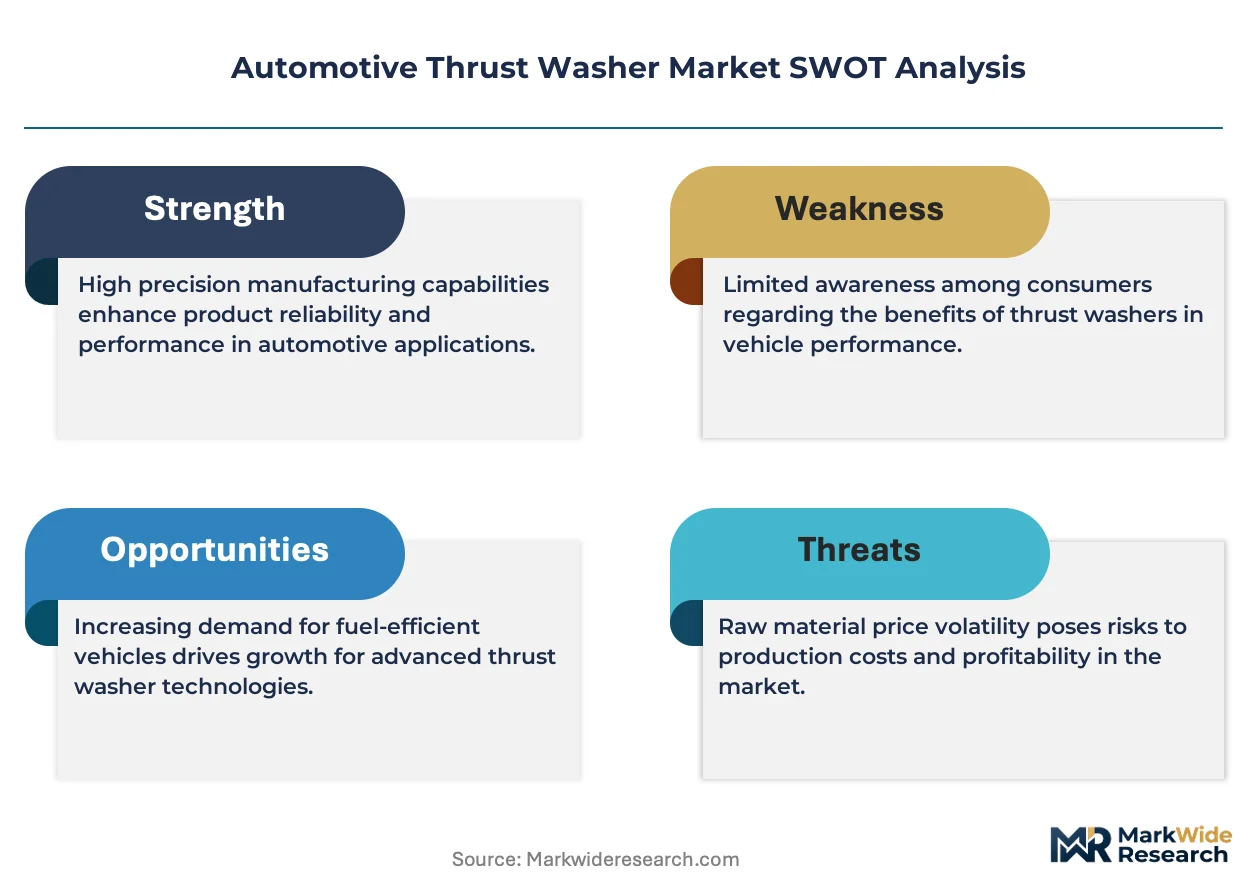
Electrification of powertrain architectures is tilting thrust washer specifications toward hybrid-compatible materials that tolerate mixed lubrication regimes. SKF leverages its bearing systems expertise to integrate thrust washers into modular e-axle packages. Schaeffler anchors European supply through its specialized transmission component division in Germany. Timken Company sustains North American manufacturing scale with vertically controlled steel processing for heavy-duty applications.
An automotive thrust washer is an annular disc positioned between rotating and stationary components to absorb axial loads and maintain critical end-play clearances, typically manufactured from hardened steel, bronze-aluminum alloys, or engineered polymers with thickness tolerances below 25 microns. Flat washers retain the largest volume share across transmission and engine applications where standardized dimensions dominate procurement. Tapered washers represent the fastest-growing product configuration as axle assemblies adopt preload-adjusted bearing arrangements for improved efficiency. Steel remains the primary material selection for OEMs, though bronze variants capture margin pools in aftermarket rebuild channels where wear resistance commands premium positioning.
EPA tailpipe regulations and the EU Green Deal's embodied-carbon requirements are reshaping material qualification protocols for powertrain suppliers seeking multi-jurisdiction market access. NHTSA safety standards for commercial vehicle drivetrain durability indirectly govern thrust washer fatigue-life testing thresholds in the US market. OEMs and tier suppliers must monitor evolving Euro 7 proposals and corresponding EPA harmonization talks, as divergent tolerance standards would fragment tooling investments and complicate platform-sharing strategies across Atlantic supply chains.
Market Dynamics
EPA emissions standards and Euro 7 proposals are tightening powertrain tolerances, forcing OEMs to specify precision-engineered thrust washers with sub-25-micron thickness control. This regulatory compression is accelerating material qualification cycles and reshaping supplier-OEM technical collaboration models.
Growth Catalysts
- Euro 7 tolerance mandates:Proposed particulate and NOx limits require tighter axial load management in transmissions, expanding demand for precision thrust washers in European drivetrain assemblies.
- Heavy-duty fleet procurement:North American commercial vehicle operators are extending service intervals through upgraded thrust washer specifications to reduce downtime costs.
- Hybrid powertrain proliferation:Mixed lubrication regimes in electrified axles necessitate bronze-aluminum alloy washers that tolerate intermittent oil film conditions.
Market Restraints
- Steel input volatility:Hardened steel thrust washers face margin pressure from fluctuating alloy steel prices and energy-intensive heat treatment costs.
- German supply concentration:Precision transmission component manufacturing clusters heavily in Baden-Württemberg and Bavaria, creating geographic vulnerability to regional disruptions.
- Polymer substitution ceiling:Engineered polymer thrust washers fail to meet fatigue-life thresholds for commercial vehicle preload-adjusted bearing arrangements.
Strategic Opportunities
- Indian commercial vehicle expansion:Bharat Stage VI Phase II implementation creates demand for upgraded drivetrain components in domestic truck and bus manufacturing.
- E-axle module integration:Thrust washer suppliers can embed components into modular electric axle packages, capturing value from powertrain electrification.
- EU Green Deal embodied-carbon protocols:Low-carbon steel qualification opens premium positioning for suppliers with verified Scope 3 emissions data.
Industry Challenges
- Metrology talent scarcity:Sub-25-micron thickness tolerance verification requires specialized coordinate measuring machine operators that OEMs and tier suppliers struggle to recruit.
- Cross-Atlantic standard divergence:Misalignment between EPA harmonization talks and finalized Euro 7 text risks fragmenting tooling investments for dual-certification thrust washer platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Thrust Washer Market |
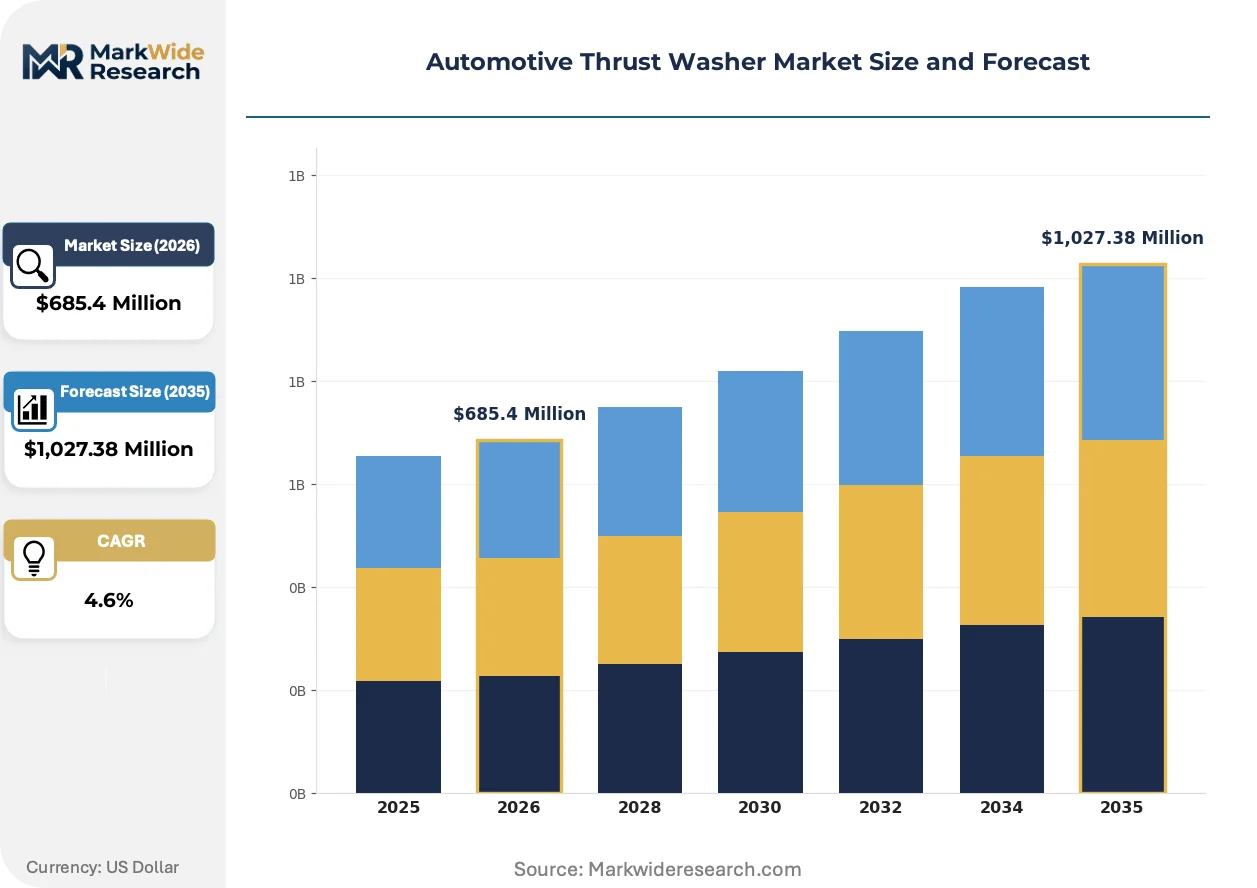
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,027.38 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Washers, Tapered Washers, Groove Washers, Custom Washers Material: Steel, Aluminum, Bronze, Plastic End User: OEMs, Aftermarket Providers, Auto Parts Distributors, Vehicle Assemblers Application: Transmission Systems, Engine Components, Axle Assemblies, Chassis |
| Companies Covered | SKF, Schaeffler, Timken Company, NTN Corporation, JTEKT Corporation, BOWMAN International, Northern Industrial Manufacturing, DuPont de Nemours, Inc., Sonnax Transmission Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Thrust Washer Market Emerging Trajectories
Material science advances and regulatory precision demands are converging to redefine thrust washer specifications across powertrain architectures. Three developments are restructuring competitive technical requirements.
Polymer-composite thrust washers with embedded solid lubricant phases are migrating from prototype evaluation to series production in light-duty hybrid transmissions. Japanese OEMs have accelerated validation timelines for these components. This migration is compressing the traditional bronze-steel material hierarchy in applications below 15 kN axial load.
REACH substance restriction proposals for persistent organic pollutants are forcing reformulation of traditional bronze-aluminum alloy chemistries. European suppliers must recertify material streams ahead of anticipated 2026 enforcement windows. German transmission specialists face the steepest requalification burden given their premium drivetrain export volumes.
Consolidated fleet procurement departments now specify thrust washer fatigue-life documentation as a contract prerequisite rather than a nominal rating. Direct sourcing from component specialists is displacing traditional tier-1 bundling in North American heavy-duty channels. This pattern is most pronounced among operators with EPA SmartWay certification obligations seeking verifiable component traceability.
Automotive Thrust Washer Market Segmentation
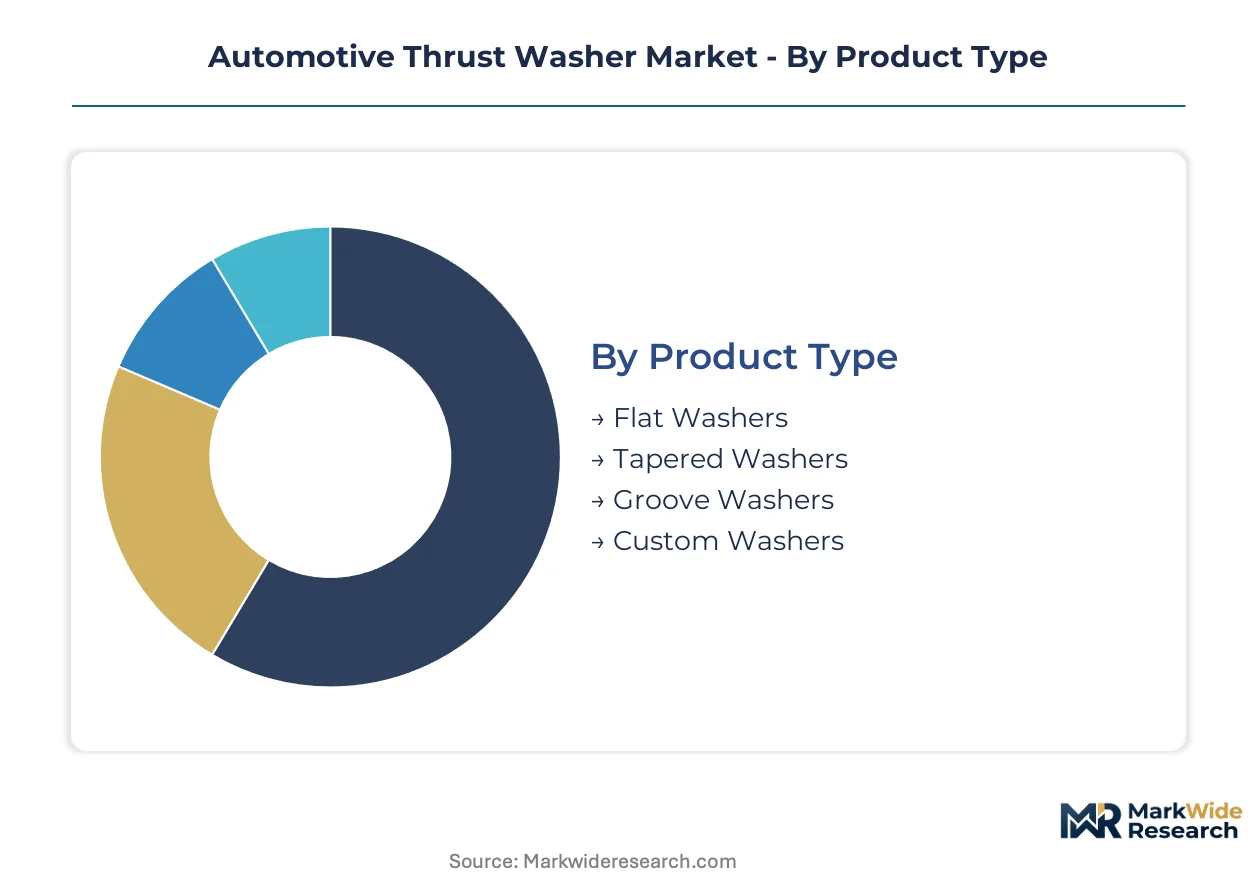
Thrust washer procurement patterns diverge sharply across powertrain architectures and supply chain tiers. Specification requirements vary by load regime, thermal environment, and whether components ship to assembly lines or service channels.
Product Type:
Use cases span standardized transmission interfaces to precision-adjusted axle assemblies with divergent tolerance demands.
- Flat Washers:Annular discs with parallel faces dominate high-volume transmission and engine applications where standardized dimensions simplify procurement. Demand concentrates in North American heavy-duty manufacturing corridors where fleet operators specify extended service intervals.
- Tapered Washers:Conical profiles enable preload adjustment in bearing arrangements, gaining share fastest in electrified axle assemblies seeking efficiency gains through optimized end-play control. European transmission specialists specify these for premium drivetrain exports.
- Groove Washers:Circumferential oil channels improve lubricant distribution in high-speed engine applications.
- Custom Washers:Application-specific geometries serve prototype powertrain development and low-volume performance vehicle programs.
Established volume favors flat washers; emerging adoption favors tapered washers.
Material:
Cost tiers separate commodity steel procurement from premium alloy positions in aftermarket rebuild channels.
- Steel:Hardened carbon and alloy grades retain OEM dominance due to fatigue-life performance in commercial vehicle preload arrangements. North American manufacturers maintain captive heat treatment capacity to control tolerance consistency.
- Bronze:Aluminum-bronze alloys tolerate mixed lubrication regimes in hybrid powertrains where intermittent oil films occur. REACH substance restrictions are forcing European suppliers toward reformulated chemistries ahead of enforcement windows.
- Aluminum:Lightweight variants serve rotational inertia-sensitive applications in performance transmissions.
- Plastic:Engineered polymer composites with solid lubricant phases penetrate light-duty hybrid transmissions below 15 kN axial load thresholds.
Steel commands OEM volume; bronze captures aftermarket premium positioning.
End User:
Customer type determines specification authority and documentation requirements across supply tiers.
- OEMs:Original equipment manufacturers specify sub-25-micron tolerance bands and mandate fatigue-life traceability for EPA SmartWay-certified fleet programs.
- Aftermarket Providers:Independent rebuild channels prioritize wear-resistant bronze variants with premium positioning in extended-warranty service contracts.
- Auto Parts Distributors:Inventory breadth requirements favor standardized flat washer dimensions with rapid availability commitments.
- Vehicle Assemblers:Final assembly operations source through modular e-axle integrators rather than direct component procurement.
Direct OEM specification dominates premium tiers; distributor channels handle volume replacement demand.
Application:
Maturity gradients separate established transmission applications from electrification-driven axle growth.
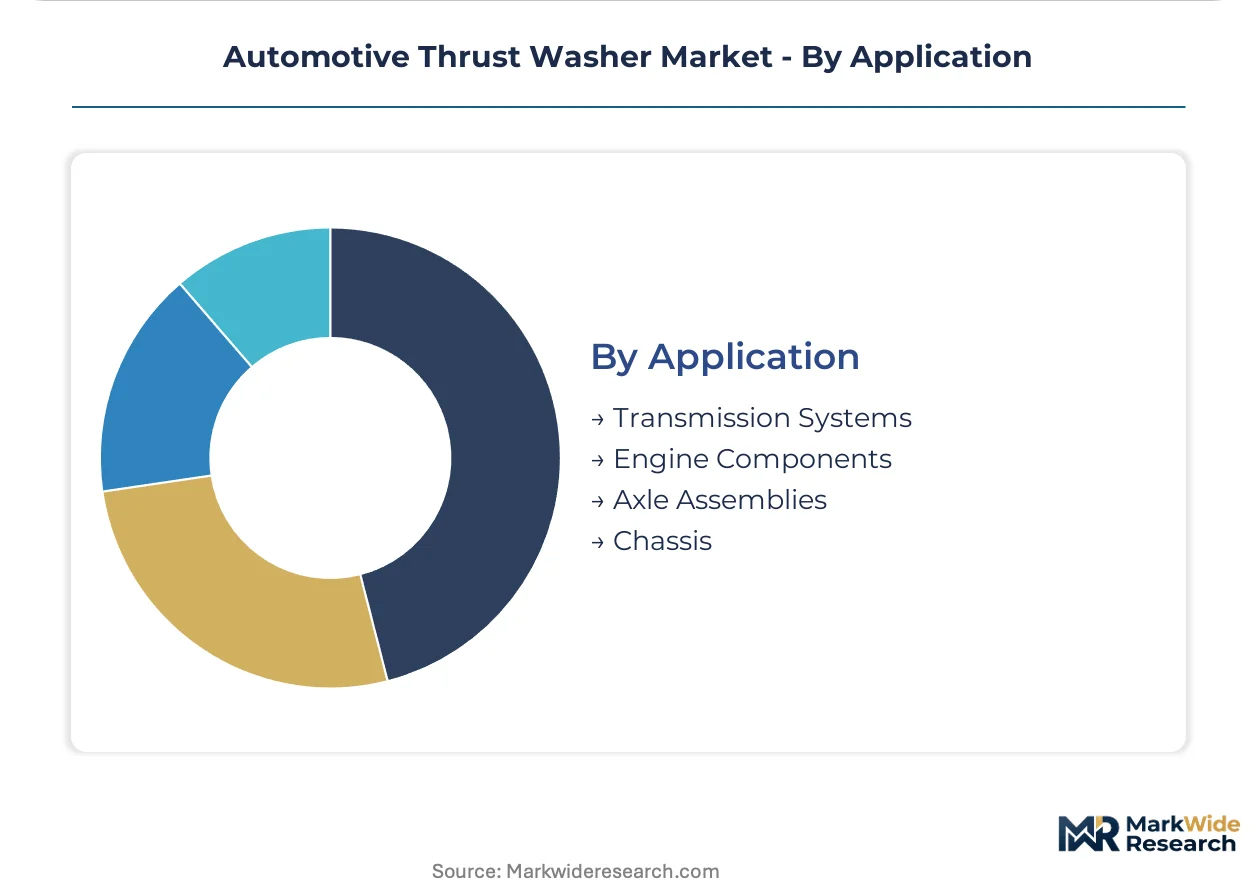
- Transmission Systems:Synchronized gearboxes represent the most penetrated application with established steel flat washer specifications across manual and automated manual architectures.
- Axle Assemblies:Preload-adjusted bearing arrangements in electrified drivetrains are expanding tapered washer specifications fastest as efficiency optimization pressures intensify.
- Engine Components:Camshaft and crankshaft thrust faces require groove-enhanced lubrication designs in high-rpm gasoline direct injection engines.
- Chassis:Steering gear and suspension pivot applications represent specialized low-volume demand with custom geometry requirements.
Transmission volume anchors current procurement; axle assemblies show steepest specification expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German transmission specialists export precision thrust washer assemblies to North American heavy-duty vehicle assemblers, establishing the primary transatlantic trade corridor in premium drivetrain components.
United States
Heavy-duty commercial fleets in Michigan and Ohio extend service intervals through upgraded thrust washer specifications. NHTSA durability standards govern fatigue-life testing thresholds for commercial vehicle drivetrains. Detroit-area manufacturing clusters source precision components through direct procurement from transmission specialists.
Germany
Baden-Württemberg and Bavaria concentrate precision transmission component manufacturing for European OEM exports. REACH substance restrictions force reformulation of traditional bronze-aluminum alloy chemistries ahead of enforcement windows. Stuttgart-based drivetrain engineers supply tapered washer configurations for electrified axle assemblies.
China
Domestic commercial vehicle manufacturers scale procurement of hardened steel flat washers for synchronized gearbox production. MIIT fuel efficiency mandates tighten tolerance requirements on powertrain components. Yangtze River Delta foundries expand heat treatment capacity for sub-25-micron thickness control.
Japan
Light-duty hybrid transmission producers validate polymer-composite thrust washers with embedded solid lubricant phases. METI technology roadmaps prioritize mixed lubrication regime compatibility. Nagoya-area automotive suppliers compress material qualification cycles for electrified powertrain architectures.
India
Domestic truck and bus manufacturers upgrade drivetrain specifications to meet Bharat Stage VI Phase II implementation. CEA industrial efficiency guidelines influence component sourcing decisions for commercial vehicle assemblers. Tamil Nadu and Maharashtra manufacturing corridors attract precision component investments from European transmission specialists.
Automotive Thrust Washer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around bearing-system integrators, precision component specialists, and material science developers. Three archetypes dominate: modular e-axle packagers, transmission-focused precision engineers, and captive steel processors. Consolidation pressure intensifies through strategic partnerships and backward integration into heat treatment capacity.
Among European precision engineering groups, Schaeffler exemplifies the transmission-specialist archetype through its German GmbH structure. SKF represents the bearing-system integrator model with modular packaging capabilities. Timken Company anchors the North American scale-driven tier with vertically controlled steel processing. These three occupy distinct competitive positions without direct segment overlap.
| Leading Market Players |
|---|
| SKF |
| Schaeffler |
| Timken Company |
| NTN Corporation |
| JTEKT Corporation |
| BOWMAN International |
| Northern Industrial Manufacturing |
| DuPont de Nemours, Inc. |
| Sonnax Transmission Company, Inc. |
| Others |
Supply Flow & Price Mechanics
The Hamburg-Detroit maritime corridor carries precision transmission components across the Atlantic at freight rates that compress margins for European exporters while enabling North American assemblers to source German-engineered thrust washers at competitive landed costs. This logistics dynamic concentrates pricing power among Baden-Württemberg specialists who control sub-25-micron tolerance production, forcing downstream buyers to accept premium positioning or accept quality downgrades from alternative suppliers.
Pricing Analysis
Technology-generation pricing gaps separate legacy steel flat washers from emerging bronze-aluminum hybrid-compatible variants and next-generation polymer-composite configurations. The market operates through contract-based long-term offtake agreements with volume-scale and certification-grade drivers differentiating tiers. Pricing pressure stems from alloy steel input volatility and energy-intensive heat treatment costs compressing margins on commodity-grade products. Aftermarket rebuild channels exhibit highest price sensitivity as independent distributors prioritize inventory velocity over premium specifications, while OEM direct procurement shows lowest sensitivity given EPA SmartWay traceability mandates.
Supply Chain Analysis
Contract manufacturing concentrates among German transmission specialists, Yangtze River Delta foundries, and Detroit-area heat treatment facilities. Geographic supply concentration centers on Germany, China, and the United States. Raw material dependencies draw from specialty alloy steel mills, aluminum-bronze ingot suppliers, and engineered polymer resin streams. Single-source vulnerability risks emerge from Baden-Württemberg's dominance in precision taper grinding equipment. Distribution runs through modular e-axle integrators and tier-1 transmission assemblers rather than direct component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive thrust washer demand tracks heavy-duty commercial vehicle fleet replacement cycles, with North American procurement accelerating as post-pandemic deferred maintenance converts to capital expenditure.
For Market Incumbents:Harden defensive positions by securing captive heat treatment capacity in Michigan and Ohio manufacturing corridors to insulate against energy cost volatility. Deepen backward integration into specialty alloy steel supply through long-term offtake agreements with European mills. Polymer-composite substitution in light-duty hybrid transmissions represents the most pressing technology threat requiring accelerated bronze-aluminum reformulation investment ahead of REACH enforcement windows.
For New Entrants and Emerging Players:Indian commercial vehicle manufacturing clusters in Tamil Nadu and Maharashtra represent the most penetrable entry point as Bharat Stage VI Phase II implementation forces drivetrain specification upgrades. Bronze-aluminum alloy thrust washers for mixed lubrication hybrid axles offer technical differentiation against entrenched steel competitors. A go-to-market partnership with European transmission specialists seeking local content qualification provides fastest route to OEM validation.
For Investors and Strategic Acquirers:Precision component specialists with verified Scope 3 emissions data and EU Green Deal qualification protocols command premium positioning in consolidation scenarios. Long-term viability hinges on electrification exposure through e-axle module integration rather than legacy transmission dependence. The signal to monitor is OEM procurement department consolidation of direct sourcing contracts displacing tier-1 bundling, which accelerates margin capture by component specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive energy-intensive processing insulates margin from European natural gas volatility. |
| Bronze-Aluminum Alloy Reformulation | REACH-compliant chemistries preserve German export access ahead of enforcement windows. |
| E-Axle Module Integration Partnership | SKF and Schaeffler packaging strategies capture value from powertrain electrification. |
| Indian Manufacturing Footprint Expansion | Tamil Nadu precision component investments align with Bharat Stage VI Phase II demand. |
| Scope 3 Emissions Verification Program | EU Green Deal embodied-carbon protocols open premium positioning for qualified suppliers. |
Methodological Framework
Cross-validation between OEM procurement director interviews and tier-1 supplier production data anchors the qualitative findings in operational reality. Primary fieldwork engaged transmission component engineers, drivetrain platform architects, aftermarket distribution managers, and commercial fleet maintenance directors across Germany, the United States, China, and India. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA SmartWay certification records, and SEC filings of bearing-system integrators. Bottom-up component demand modeling and top-down powertrain production forecasts triangulate volume estimates.
Calibration against historical tolerance adoption curves and regulatory implementation timelines shapes the analytical framework across the analysis window. Segmentation dimensions include product configuration, material chemistry, end-user procurement authority, and powertrain application maturity. CAGRs derive from regression analysis of procurement volume against fleet replacement cycles and electrification penetration rates. Industry-specific inputs incorporate NHTSA durability testing thresholds and Euro 7 proposal harmonization progress.
Practitioners should monitor EPA-Euro 7 harmonization talks, alloy steel price indices, and OEM e-axle sourcing announcements for early signals of forecast revision. Assumptions reflect current regulatory trajectories and technology adoption patterns subject to policy acceleration or supply disruption. Quarterly review of fleet procurement contract awards and REACH substance restriction final texts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Sway Bar Bushing Market
Powertrain
Yaw Damper Market
Powertrain
Brazil Automotive Actuators Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Transmission Fluids Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Automotive Power Modules Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
LNG Engine Market
Powertrain
Transmission Control System Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Torque Converter Market