
 Steering Damper Market | 2026-2036
Steering Damper Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Damper Market Analytics
Off-road vehicle applications are recalibrating demand profiles across the steering damper landscape as recreational and commercial fleet operators specify heavier-duty stabilization hardware. Öhlins Racing leverages its motorsport heritage to dominate premium motorcycle and off-road racing channels. BILSTEIN sustains manufacturing scale across European and North American OEM supply chains. Tenneco Inc. anchors its position through integrated suspension system bundling that reduces customer procurement complexity.
A steering damper is a hydraulic or pneumatic stabilization device mounted between a vehicle's steering linkage and chassis, typically operating at damping coefficients between 200-800 Ns/m to suppress oscillation and feedback forces transmitted from road irregularities or large tire contact patches. Electronic damper variants now integrate sensor arrays that adjust damping resistance in milliseconds based on vehicle speed and terrain input, serving critical safety and handling functions in heavy machinery and high-displacement motorcycles. Hydraulic dampers retain the largest installed base across automotive and motorcycle applications where cost sensitivity limits electronic migration. Adjustable dampers command premium positioning in aftermarket channels where off-road enthusiasts demand terrain-specific tuning capability. OEMs and Tier-1 Suppliers concentrate procurement volumes for electronic and semi-active steering technologies as vehicle electrification architectures create shared control bus opportunities.
NHTSA Federal Motor Vehicle Safety Standards, EU CE marking requirements under the General Product Safety Directive, and Japan's METI technical standards collectively mandate steering stability verification for on-highway motorcycles and light trucks, directly shaping product certification costs and design validation timelines. EPA emissions compliance for heavy machinery indirectly influences damper specification as engine-downsizing trends increase chassis vibration frequencies that steering systems must attenuate. Stakeholders must monitor regulatory divergence between North American self-certification and European type-approval frameworks when planning platform standardization strategies.
Market Dynamics
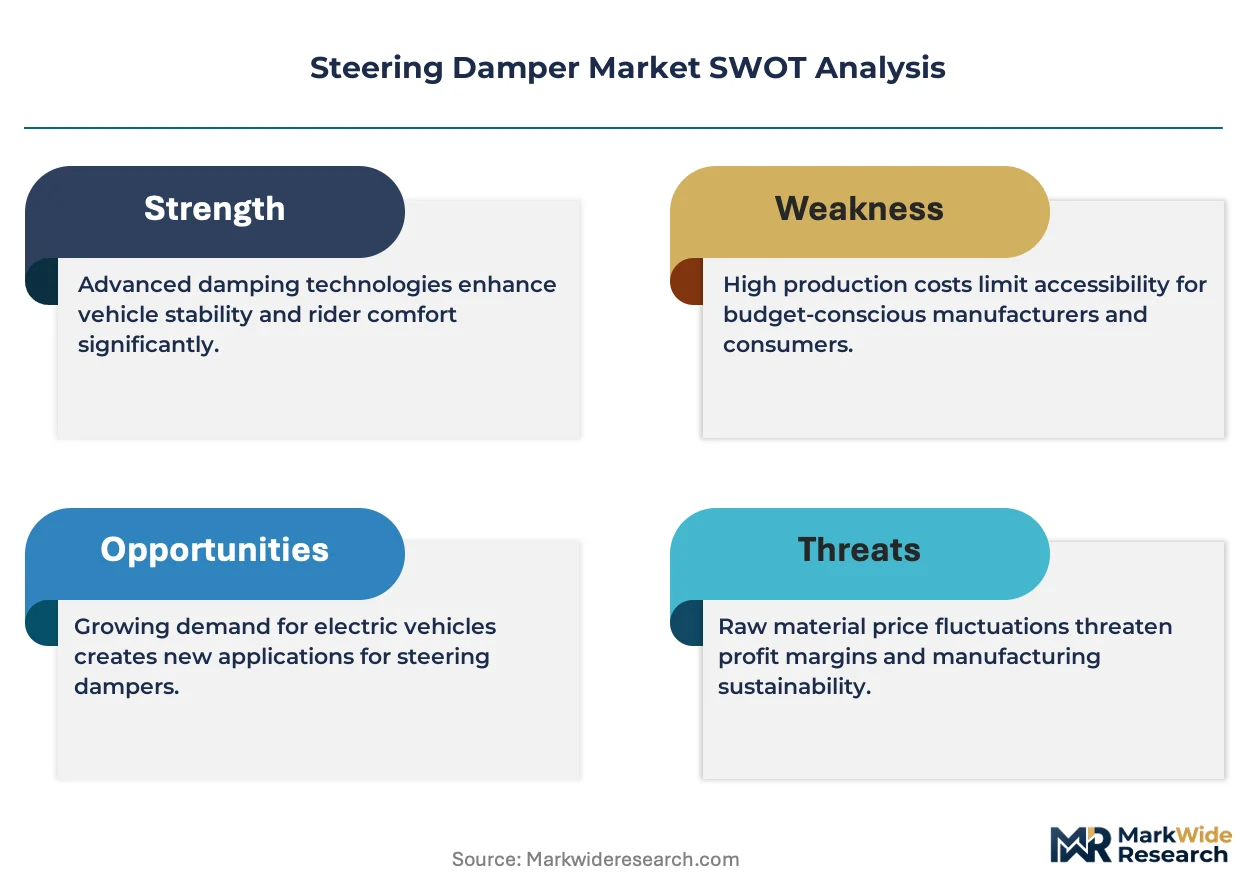
Electronic steering damper architectures are displacing hydraulic hardware across heavy machinery and high-performance motorcycle platforms, compressing OEM validation timelines while expanding sensor integration requirements for chassis control networks.
Growth Catalysts
- NHTSA Stability Mandates:Federal Motor Vehicle Safety Standards for on-highway motorcycles and light trucks mandate steering oscillation suppression, accelerating electronic damper fitment rates across North American production lines.
- Off-Road Fleet Expansion:Commercial and recreational operators in mining, agriculture, and powersports are specifying adjustable damper variants to manage terrain-specific feedback forces and reduce operator fatigue.
- Electrification Convergence:Shared vehicle control bus architectures in electric powertrains enable steering damper integration with stability control and active suspension modules, reducing wiring complexity.
Market Restraints
- Input Cost Volatility:Precision-machined aluminum housings and specialized hydraulic fluids face price pressure from energy-intensive smelting and petrochemical feedstock fluctuations.
- Supplier Concentration:High-pressure seal manufacturing and electronic sensor calibration capabilities cluster in German and Japanese component networks, creating single-source vulnerabilities.
- Regulatory Divergence:North American self-certification frameworks and European type-approval processes impose incompatible validation protocols, fragmenting platform standardization efforts.
Strategic Opportunities
- India Two-Wheeler Market:Domestic motorcycle production exceeding twenty million units annually presents untapped demand for cost-optimized hydraulic dampers as displacement segments rise.
- EU Green Deal Procurement:Public fleet electrification mandates create specification windows for lightweight electronic dampers that reduce unsprung mass in municipal service vehicles.
- Agricultural Autonomy:Autonomous tractor and harvester platforms require predictive steering stabilization algorithms that adjust damping before terrain contact, opening software-hardware bundled contracts.
Industry Challenges
- Embedded Systems Talent Gap:Firmware development for real-time damping adjustment competes with broader automotive electronics hiring pools, extending recruitment cycles for control algorithm specialists.
- Multi-Protocol Certification:Simultaneous validation against NHTSA, EU CE marking, and Japan METI technical standards stretches engineering bandwidth and delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Damper Market |
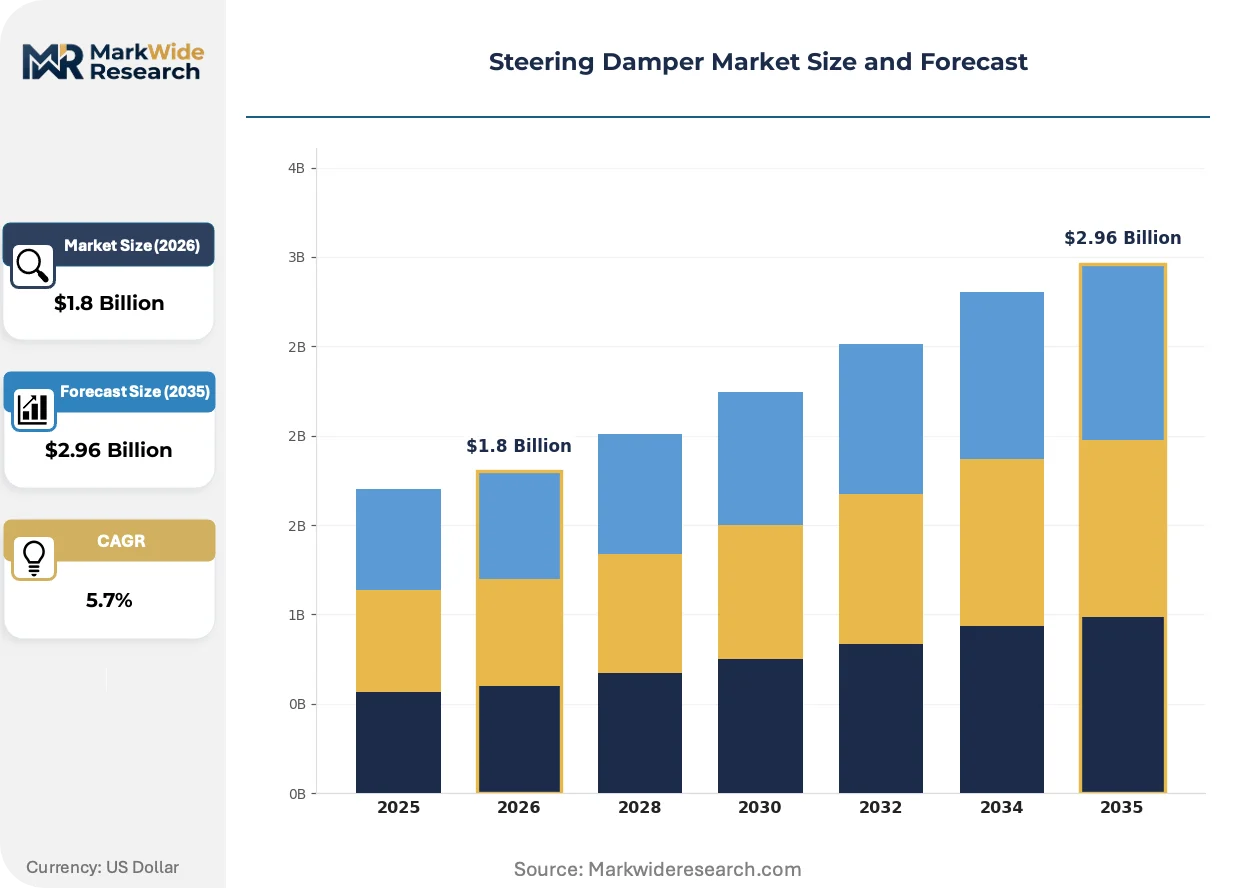
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Dampers, Adjustable Dampers, Pneumatic Dampers, Electronic Dampers Application: Automotive, Off-Road Vehicles, Motorcycles, Heavy Machinery Technology: Active Steering, Passive Steering, Semi-Active Steering, Adaptive Suspension End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Öhlins Racing, BILSTEIN, Skyjacker, Tenneco Inc., Pro Comp USA, Hyperpro Sales B.V., Rough Country Suspension Systems, Scotts Performance Products, Fox Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Damper Market Evolving Landscape
Sensor fusion architectures and additive manufacturing techniques are compressing development cycles while enabling damper designs that adapt to individual vehicle dynamics profiles rather than platform averages.
Magnetorheological fluid technology is modularizing steering damper construction by separating the electromagnetic control module from the hydraulic cylinder body. Heavy machinery OEMs in construction and mining are adopting this split architecture to field-replace control electronics without disturbing sealed fluid systems. The separation of sensing and actuation functions is modularizing supplier tiers, allowing chassis integrators to source electronic controllers from semiconductor specialists while retaining hydraulic hardware from traditional damper manufacturers.
EU CE marking requirements under the General Product Safety Directive now explicitly address steering stability verification for light commercial vehicles, forcing recertification of legacy hydraulic designs that lacked oscillation testing documentation. The industrial consequence is a documentation burden that favors larger suppliers with established homologation departments. Motorcycle and light truck categories face the steepest compliance costs, with Italian and Spanish manufacturers accelerating migration to electronic variants that generate automated test logs.
Fleet operators in commercial construction and agricultural contracting are unbundling steering damper specification from bundled suspension system procurement, issuing separate RFPs for stabilization hardware to capture aftermarket service revenue. This disintermediation disrupts traditional Tier-1 bundling arrangements and channels volume toward specialized damper manufacturers with direct technical support capabilities. The pattern is most visible in German and US Midwest equipment markets where large contractor fleets maintain in-house maintenance operations.
Steering Damper Market Segmentation
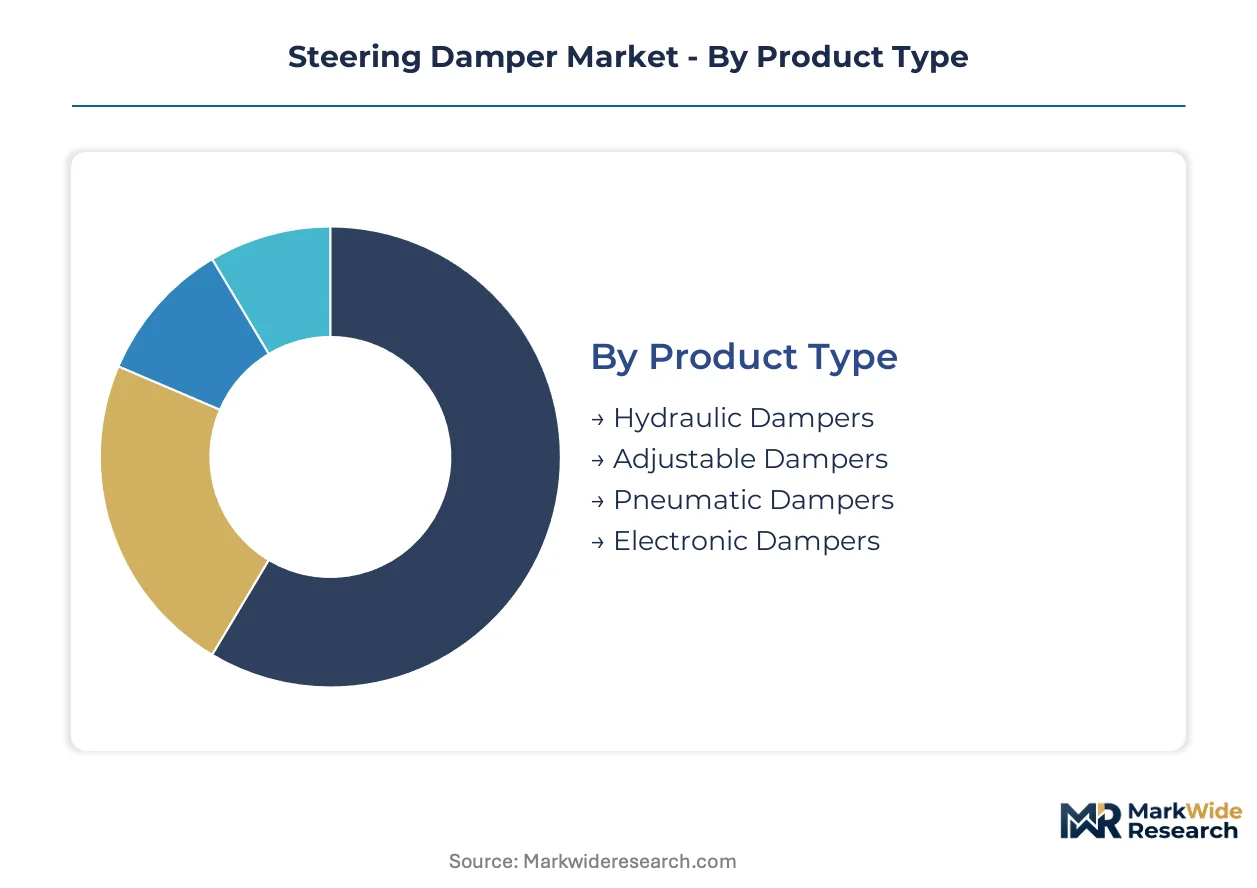
Steering damper procurement patterns diverge sharply across product architectures and customer types, with electronic variants commanding premium positioning while hydraulic hardware retains volume dominance. Technology selection directly determines validation timelines, sensor integration requirements, and regulatory compliance pathways.
Product Type:
Hydraulic architectures anchor the installed base through cost-optimized cylinder-and-piston designs, while electronic modules introduce programmable damping curves that integrate with vehicle control networks.
- Hydraulic Dampers:Sealed fluid chambers with fixed orifice plates deliver damping coefficients between 200-600 Ns/m. Fleet operators in United States commercial trucking specify these for predictable maintenance cycles and field-serviceable seals.
- Electronic Dampers:Sensor-integrated units adjust resistance in milliseconds via solenoid valves or magnetorheological fluids. German motorcycle OEMs mandate these for high-displacement platforms subject to NHTSA oscillation standards.
- Adjustable Dampers:Manual or remotely tunable valving allows terrain-specific calibration. Powersports enthusiasts in Japan and United States aftermarket channels drive specification for off-road motorcycles.
- Pneumatic Dampers:Compressed air chambers provide lightweight alternatives for specialized racing applications. Limited adoption outside motorsport due to pressure maintenance requirements.
Hydraulic dampers lead on scale; electronic dampers lead on momentum.
Application:
End-use environments dictate durability specifications, with mining and agricultural machinery demanding heavier-duty hardware than on-highway passenger vehicles.
- Automotive:Light trucks and passenger cars specify compact hydraulic units for steering column stabilization. United States OEM procurement concentrates on NHTSA-compliant designs with automated test documentation.
- Off-Road Vehicles:Recreational ATVs and UTVs require adjustable damping to manage terrain feedback forces. Commercial mining fleets in Australia and Canada specify sealed electronic variants for contamination resistance.
- Motorcycles:Performance and touring segments drive electronic damper adoption above 800cc displacement. Italian and Japanese manufacturers integrate these with IMU-based stability control systems.
- Heavy Machinery:Construction equipment and agricultural tractors specify high-capacity hydraulic dampers rated above 800 Ns/m. Autonomous platform development in Germany and United States is accelerating predictive damping algorithm demand.
Automotive leads on scale; heavy machinery leads on momentum.
Technology:
Control architecture sophistication determines integration depth with chassis electronics and shared vehicle bus systems.
- Passive Steering:Fixed-rate hydraulic damping without external control inputs. Retains dominant share in cost-sensitive automotive and motorcycle segments where electronic migration proceeds slowly.
- Semi-Active Steering:Electronically modulated damping with limited sensor feedback. German Tier-1 suppliers bundle these with active suspension modules for luxury vehicle platforms.
- Active Steering:Full closed-loop control with predictive algorithms adjusting damping before road input. Heavy machinery autonomy programs in United States and Japan specify these for operator fatigue reduction.
- Adaptive Suspension:Integrated chassis control coordinating steering damping with ride height and brake torque vectoring. Premium automotive OEMs in Germany and Japan pursue these for electrified platform differentiation.
Passive steering leads on scale; active steering leads on momentum.
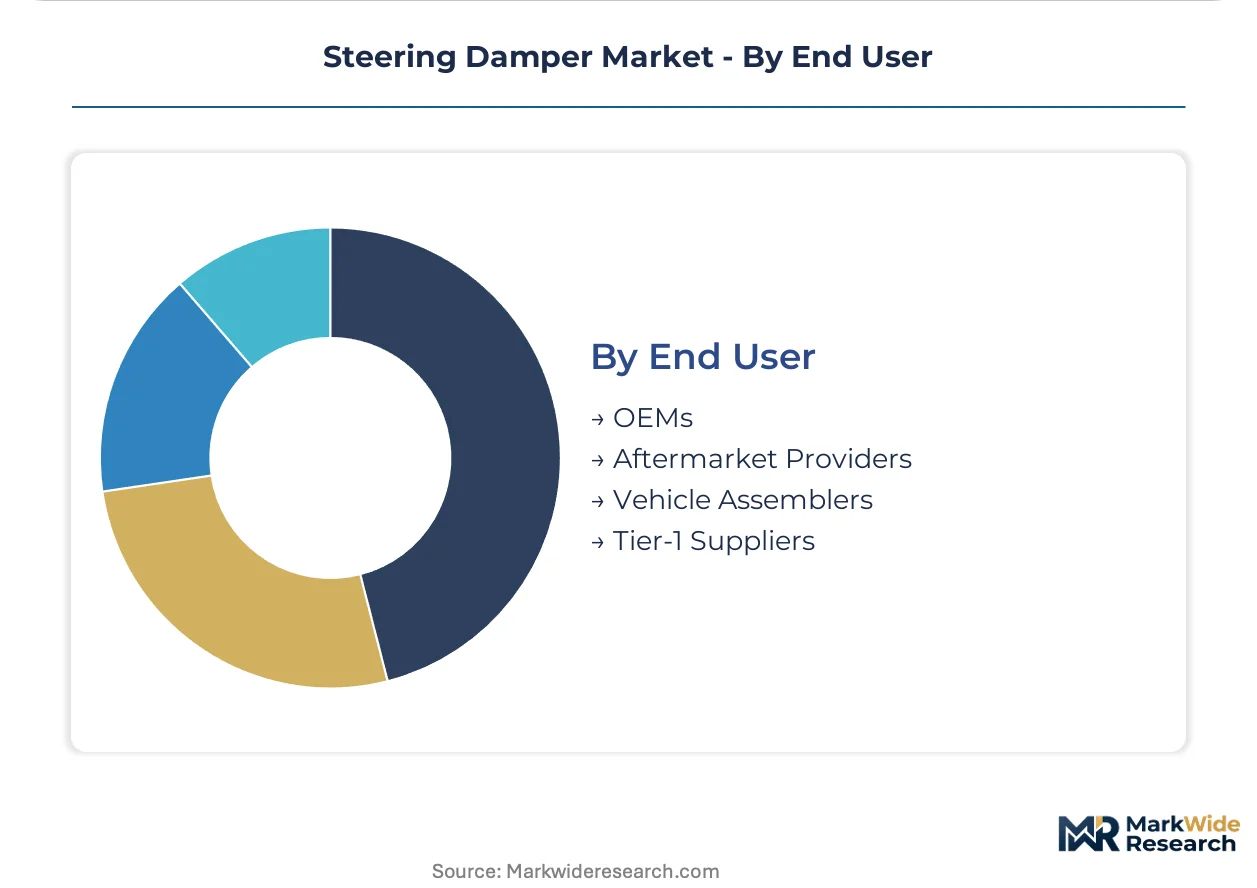
End User:
Procurement authority distribution shapes pricing structures and technical support requirements, with direct OEM relationships commanding volume discounts.
- OEMs:Original equipment manufacturers specify damper performance curves during platform development. Japanese and German automotive OEMs conduct joint validation with Tier-1 suspension integrators.
- Tier-1 Suppliers:Chassis system integrators bundle steering dampers with strut assemblies and control arms. These suppliers manage homologation documentation for EU CE marking and NHTSA self-certification.
- Aftermarket Providers:Independent distributors serve powersports enthusiasts and commercial fleet maintenance operations. United States and German channels show strongest demand for adjustable and rebuildable damper variants.
- Vehicle Assemblers:Regional assembly plants source dampers from approved supplier lists for localized production. Indian two-wheeler assemblers represent expanding volume opportunity for cost-optimized hydraulic designs.
OEMs lead on scale; aftermarket providers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between NHTSA self-certification and EU type-approval frameworks creates compliance-cost arbitrage that steers manufacturing investment toward jurisdictions with streamlined validation pathways. Production clusters in Germany, Japan, and the United States retain premium electronic damper capacity while cost-optimized hydraulic assembly migrates to emerging manufacturing bases.
United States
NHTSA Federal Motor Vehicle Safety Standards mandate steering oscillation suppression for on-highway motorcycles and light trucks, accelerating electronic damper fitment rates across domestic production lines. EPA emissions compliance for heavy machinery indirectly shapes damper specification as engine-downsizing trends amplify chassis vibration frequencies. The Midwest industrial corridor hosts heavy machinery OEMs specifying high-capacity hydraulic dampers for agricultural and construction equipment platforms.
Germany
EU CE marking requirements under the General Product Safety Directive explicitly address steering stability verification for light commercial vehicles, forcing recertification of legacy hydraulic designs lacking oscillation test documentation. The country's national automotive regulator enforces type-approval protocols that fragment platform standardization efforts with North American frameworks. Bavaria and Baden-Württemberg concentrate Tier-1 suspension integrators conducting joint validation with domestic OEMs for active steering technologies.
Japan
METI technical standards mandate steering stability verification for on-highway motorcycles, directly shaping product certification costs and design validation timelines for domestic manufacturers. The regulator's requirements converge with NHTSA standards in ways that advantage suppliers with dual-compliance capabilities. The Kanto region around Tokyo anchors motorcycle OEM procurement for electronic dampers integrated with IMU-based stability control systems.
India
Domestic motorcycle production exceeding twenty million units annually generates untapped demand for cost-optimized hydraulic dampers as displacement segments rise. The country's national standards body maintains certification frameworks that attract manufacturers seeking lower validation burdens than EU or North American markets. Maharashtra and Tamil Nadu host two-wheeler assemblers representing expanding volume opportunity for entry-level steering stabilization hardware.
China
GB standards for automotive steering systems create a parallel regulatory universe that domestic manufacturers navigate with lower compliance overhead than export-oriented competitors. The Ministry of Industry and Information Technology oversees technical specifications that favor local supply chain integration for hydraulic damper components. The Yangtze River Delta concentrates manufacturing capacity serving both domestic vehicle assembly and export markets for aftermarket replacement dampers.
Steering Damper Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium motorcycle and motorsport channels rewarding heritage positioning while automotive OEM procurement favors scale and bundling capabilities. The vendor base concentrates around three strategic tiers: integrated suspension system suppliers, specialized damper manufacturers with direct technical support operations, and regional fabricators serving cost-sensitive aftermarket channels. Dominant competitive moves include portfolio diversification into electronic control modules and geographic expansion through approved supplier list penetration in emerging vehicle assembly markets.
Among European heritage brands, Öhlins Racing and BILSTEIN occupy positions that exemplify divergent scale strategies within the premium tier. Öhlins Racing represents the specialized motorsport-to-OEM pathway, leveraging technical credibility in racing channels to command specification in high-performance motorcycle platforms. BILSTEIN anchors the volume-capable industrial model, sustaining manufacturing scale across multiple continental supply chains. Tenneco Inc. sits within the integrated systems tier, bundling steering dampers with broader chassis component portfolios to reduce customer procurement complexity. These three archetypes—racing-specialist, scale-manufacturer, and system-integrator—structure competitive positioning across price-performance segments.
| Leading Market Players |
|---|
| Öhlins Racing |
| BILSTEIN |
| Skyjacker |
| Tenneco Inc. |
| Pro Comp USA |
| Hyperpro Sales B.V. |
| Rough Country Suspension Systems |
| Scotts Performance Products |
| Fox Factory |
| Others |
Value Network & Pricing Analysis
Fleet unbundling of steering damper procurement from bundled suspension systems is forcing suppliers to reconfigure fulfillment models and accept compressed channel margins. NHTSA oscillation mandates and EU CE marking recertification requirements simultaneously elevate specification costs while constraining premium pricing power across North American and European supply chains.
Pricing Analysis
Distributor margins on electronic damper variants absorb the steepest compression as OEMs consolidate procurement volumes and negotiate direct technical support contracts. Three-tier pricing structure across premium electronic, standard hydraulic, and economy fixed-orifice designs reflects certification grade and sensor integration depth. Cost compression in entry-level hydraulic tiers intensifies because Indian two-wheeler assemblers demand sub-premium positioning. Aftermarket enthusiasts show least price sensitivity for adjustable rebuildable units with terrain-specific calibration capability.
Supply Chain Analysis
Specialized workforce availability for high-pressure seal manufacturing and electronic sensor calibration clusters in German and Japanese industrial corridors, constraining capacity expansion elsewhere. Precision-machined aluminum housings draw from German and Chinese smelting networks, while magnetorheological fluid formulations hinge on petrochemical feedstocks from South Korean and Japanese specialty chemical producers. Single-source vulnerability in electromagnetic control module sourcing creates tariff exposure risk. Distribution runs through Tier-1 suspension integrators bundling dampers with strut assemblies for OEM fitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The steering damper market compounds steadily as regulatory mandates for steering oscillation suppression create irreversible specification upgrades across motorcycle and heavy machinery production lines.
For Market Incumbents: Extend electronic damper controller development capabilities to capture software-hardware bundled contracts from autonomous tractor platforms in Germany and the United States. Deepen backward integration into high-pressure seal manufacturing to reduce single-source vulnerability from Japanese component networks. Certification investment in dual NHTSA-EU compliance capabilities defends position against emerging Asian competitors lacking homologation infrastructure. For New Entrants and Emerging Players: Direct-to-fleet digital channels bypass Tier-1 bundling arrangements and capture aftermarket service revenue from commercial construction operators in the US Midwest. Target India's two-wheeler assembler market with cost-optimized hydraulic designs as displacement segments rise above 150cc. White-space exists in predictive damping algorithms for agricultural autonomy programs seeking pre-terrain adjustment capability. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized damper manufacturers possessing direct technical support operations and established racing heritage credibility. Long-term viability centers on sensor fusion integration depth rather than commodity hydraulic hardware scale. Watch for inflection signals in agricultural OEM autonomous platform procurement volumes indicating algorithmic steering stabilization demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Integration | Magnetorheological control modules enable millisecond damping adjustment for autonomous heavy machinery. |
| Dual-Compliance Certification | Simultaneous NHTSA self-certification and EU type-approval reduces platform fragmentation costs. |
| Aftermarket Channel Expansion | Direct fleet relationships capture service revenue unbundled from Tier-1 suspension integrators. |
| Predictive Algorithm Development | Pre-terrain damping adjustment addresses operator fatigue in autonomous agricultural platforms. |
| Regional Manufacturing Footprint | Indian assembly capacity serves cost-optimized hydraulic demand from domestic two-wheeler production. |
Research Methodology
Bottom-up motorcycle and heavy machinery modeling reconciled against top-down suspension component tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 procurement leads, aftermarket distributors, and powersports enthusiasts validated specification trends and pricing dynamics. Secondary sources include NHTSA FMVSS documentation, EU CE marking directives under the General Product Safety Directive, vehicle production databases, and customs trade records for aluminum housing and hydraulic fluid inputs.
Historical trendline analysis across damper technology transitions informed projection frameworks over the analysis window. Segmentation modeling captured product architecture, application environment, control technology sophistication, and end-user procurement authority. CAGRs derived from fitted adoption curves for electronic versus hydraulic displacement, cross-referenced against regulatory mandate implementation timelines and OEM platform electrification roadmaps. Industry-specific inputs incorporated IMU integration rates in high-displacement motorcycles and autonomous tractor development milestones.
The model assumes a particular technology adoption path; alternative pathways for magnetorheological fluid commercialization would alter the outlook. Forecasts reflect assumptions regarding NHTSA enforcement consistency, EU type-approval documentation burdens, and sensor fusion cost curves. Material deviation in agricultural autonomy procurement triggers or motorcycle displacement segment migration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Torque Vectoring System Market
Powertrain
Engine Actuators Market
Powertrain
Automotive Hydraulic Lash Adjuster Market
Powertrain
Yaw Damper Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Automotive Powertrain Components Market
Powertrain
Transmission Fluids Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Clutch Hub Puller Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Diesel Engine Market
Powertrain
Fuel Injection Systems Market
Powertrain
Europe Electro Hydraulic Power Steering Market
Powertrain
Engine Tuner Market