
 Reciprocating Engine Market | 2026-2036
Reciprocating Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Reciprocating Engine Market Analysis
Utility procurement of large-bore reciprocating generators is decoupling from traditional grid-connected power plant economics as industrial buyers prioritize energy security over marginal cost. Caterpillar Inc. leverages its integrated financing arm to anchor captive power contracts across mining and oilfield segments. Cummins Inc. sustains technology leadership in high-speed diesel architectures for data center backup. Wärtsilä Corporation dominates the dual-fuel segment through its ability to navigate marine decarbonization mandates.
A reciprocating engine converts linear piston motion into rotary mechanical work through a crankshaft, operating on Otto, Diesel, or dual-fuel combustion cycles with typical bore diameters ranging from under 100 mm to over 900 mm for stationary power applications. Diesel engines occupy the largest installed base in heavy-duty transportation and remote power generation where fuel availability and torque density outweigh first-cost premiums. Natural gas engines represent the fastest-expanding product category as methane infrastructure expands and dual-fuel flexibility becomes a margin pool for operators hedging fuel price volatility. Turbocharged technology leads across all power classes where specific output and altitude derating compensation create measurable operational value.
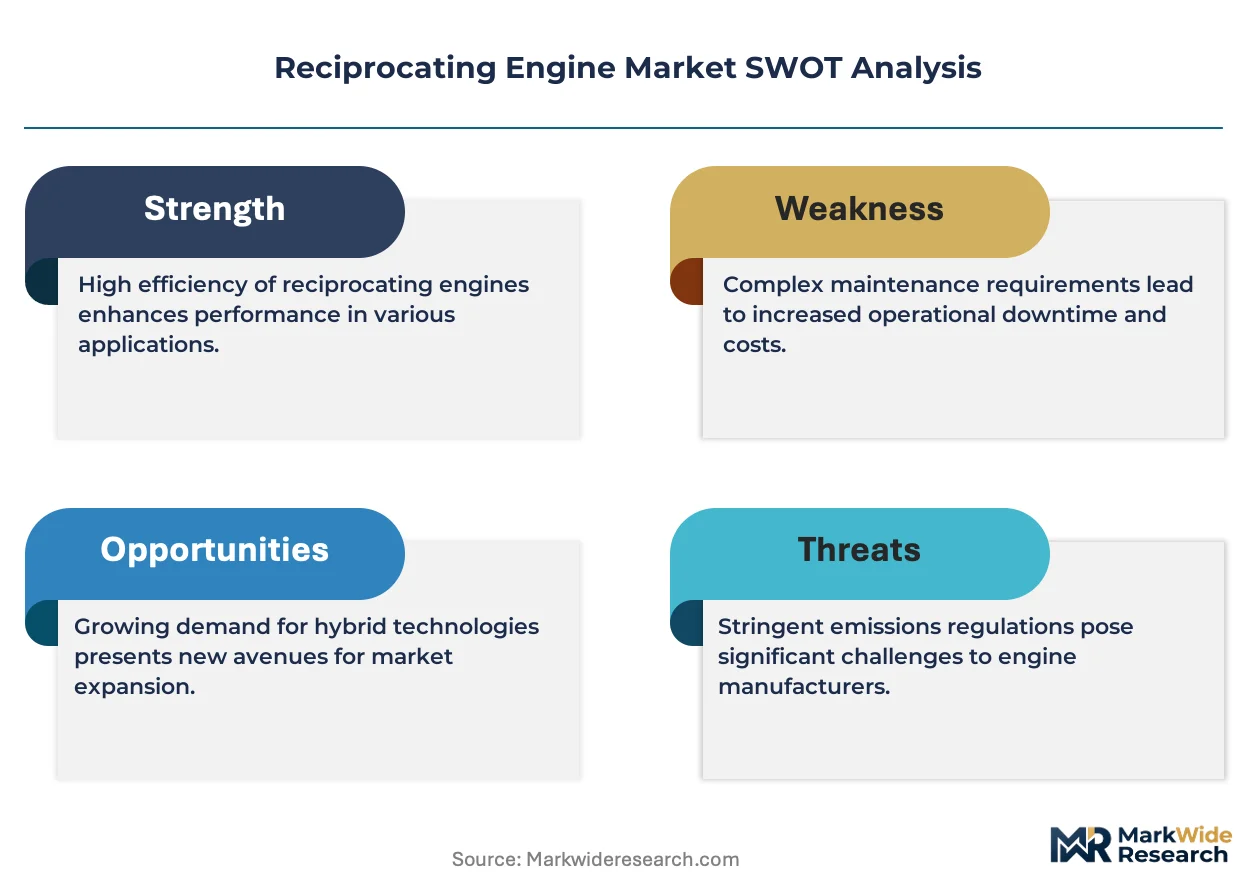
The EPA enforces Tier 4 Final emission standards for non-road diesel engines, forcing manufacturers to integrate selective catalytic reduction and diesel particulate filters that add cost and complexity to new installations. The EU's F-Gas Regulation and MEE requirements in China are converging on stricter methane slip limits for gas-fired engines, reshaping combustion chamber design priorities across export-oriented suppliers. ISO 8178 test cycles govern exhaust emission certification for reciprocating engines in international commerce, creating a baseline for market access that favors R&D-intensive producers. Stakeholders must monitor the pace of ammonia and hydrogen pilot projects in marine and stationary applications to assess whether reciprocating architectures can retain their position against fuel-cell alternatives in zero-carbon scenarios.
Market Dynamics
Dual-fuel combustion architectures are compressing the addressable market for pure diesel engines as industrial buyers prioritize fuel arbitrage flexibility over single-fuel reliability guarantees. This technology pivot is redistributing engineering resources across the supplier base.
Growth Catalysts
- EPA Tier 4 Final:Stringent non-road emission ceilings are accelerating selective catalytic reduction adoption, creating aftermarket retrofit demand for existing stationary installations.
- Data center captive power:Hyperscale operators in Northern Virginia and Frankfurt are commissioning gas-fired reciprocating units to isolate critical loads from grid instability.
- Methane infrastructure expansion:Pipeline density improvements in Gujarat and Maharashtra are enabling industrial clusters to switch from diesel backup to continuous-duty natural gas engines.
Market Restraints
- Platinum-group metal cost volatility:Diesel particulate filter substrates and SCR catalysts depend on palladium and rhodium, exposing OEMs to raw material price swings that compress margin on Tier 4 Final compliant units.
- Marine engine supplier concentration:Dual-fuel medium-speed architectures for deep-sea vessels concentrate among three European manufacturers, creating procurement bottlenecks for shipyards in South Korea and Japan.
- Fuel-cell substitution threat:Solid-oxide fuel cells achieving 60% electrical efficiency in pilot stationary applications threaten reciprocating engines in zero-carbon microgrid configurations.
Strategic Opportunities
- Ammonia combustion pilots:Marine classification societies in Norway and Japan are certifying ammonia-fueled reciprocating engines for deep-sea shipping, opening a fuel pathway that sidesteps methane slip concerns.
- EU F-Gas Regulation:Tightening hydrofluorocarbon phase-down schedules are incentivizing natural gas engine adoption in commercial refrigeration and cold-chain applications as compressor alternatives.
- Remote mining electrification:Off-grid mineral extraction in Western Australia and Chilean Atacama is creating demand for modular reciprocating-genset hybrids integrated with battery storage.
Industry Challenges
- Combustion calibration expertise:Dual-fuel engine tuning requires simultaneous optimization of diesel pilot injection and gas premixing, a skill set scarce among traditional diesel service technicians.
- ISO 8178 certification timelines:Exhaust emission type-approval test cycles for export markets extend product development schedules by months, delaying revenue recognition for new engine platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reciprocating Engine Market |
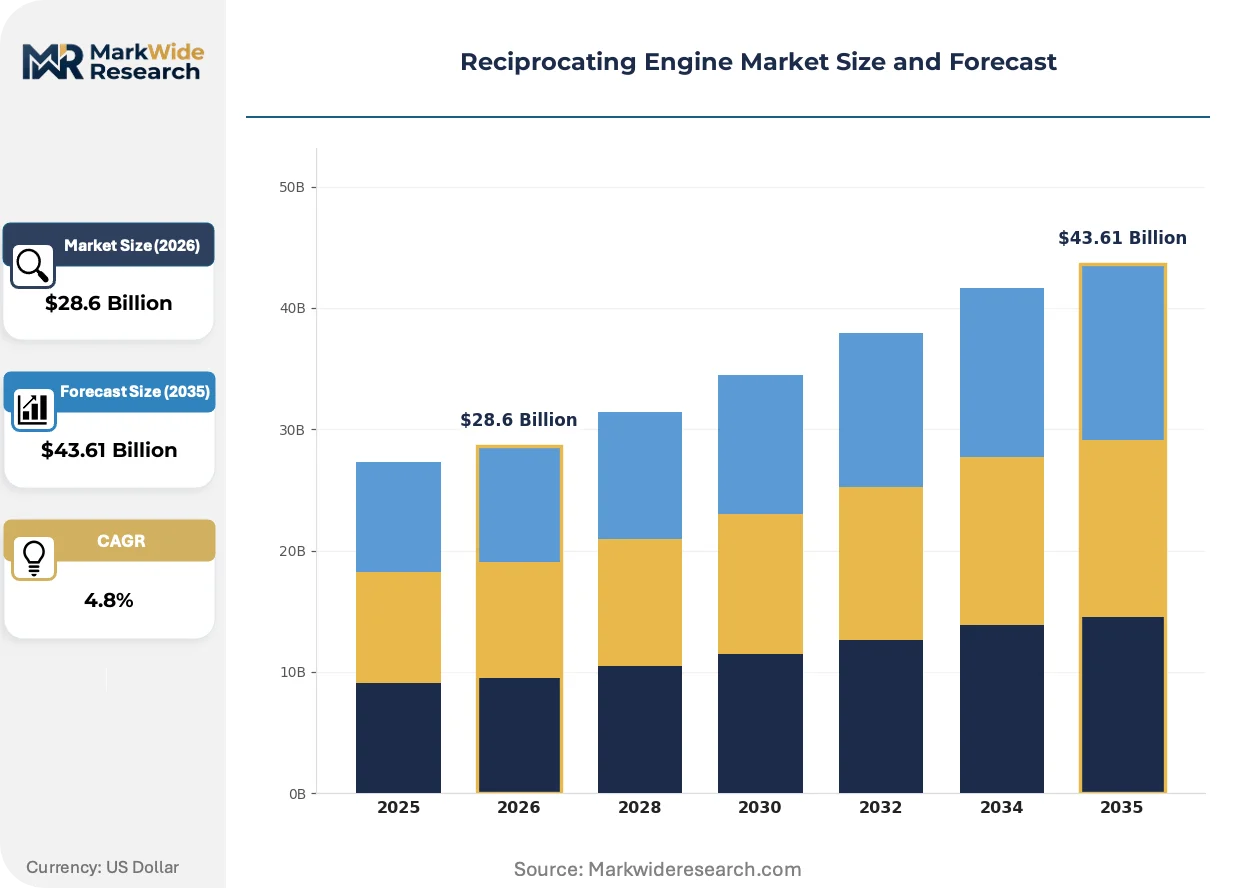
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Engines, Diesel Engines, Dual-Fuel Engines, Natural Gas Engines End User: Transportation, Power Generation, Marine, Industrial Equipment Technology: Single-Cylinder, Multi-Cylinder, Turbocharged, Supercharged Installation: Onshore, Offshore, Stationary, Mobile |
| Companies Covered | MAN Energy Solutions, General Electric Company, Caterpillar Inc., MTU Friedrichshafen GmbH, Mitsubishi Heavy Industries Ltd., Cummins Inc., Rolls-Royce Holdings plc, Yanmar Co., Ltd., Wärtsilä Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reciprocating Engine Market Emerging Trajectories
Engine architecture is fragmenting into modular subsystems that decouple combustion hardware from aftertreatment and control electronics. This decomposition is enabling faster platform iteration and supplier specialization.
Containerized reciprocating gensets are modularizing power plant deployment by integrating engines, radiators, and switchgear into standardized shipping frames. Mining contractors in Western Australia and data center developers in Singapore are specifying these plug-and-play units to compress site construction schedules from years to months. The approach is modularizing the traditional engineer-procure-construct model into repeatable equipment leases.
The EU's F-Gas Regulation is tightening methane slip limits for gas-fired stationary engines, forcing combustion chamber redesigns that sacrifice some thermal efficiency for emission compliance. Manufacturers serving the European market are adopting pre-chamber ignition and Miller-cycle valve timing to meet the new ceilings. This regulatory pressure is diverging product roadmaps between EU-bound and export-only engine variants.
Industrial buyers are unbundling long-term service agreements from initial equipment procurement, preferring competitive tendering for maintenance and parts supply. Power plant operators in India and Southeast Asia are driving this fragmentation, using digital condition monitoring to justify switching service providers mid-contract. The practice is compressing OEM aftermarket margins and accelerating third-party parts certification.
Reciprocating Engine Market Segmentation
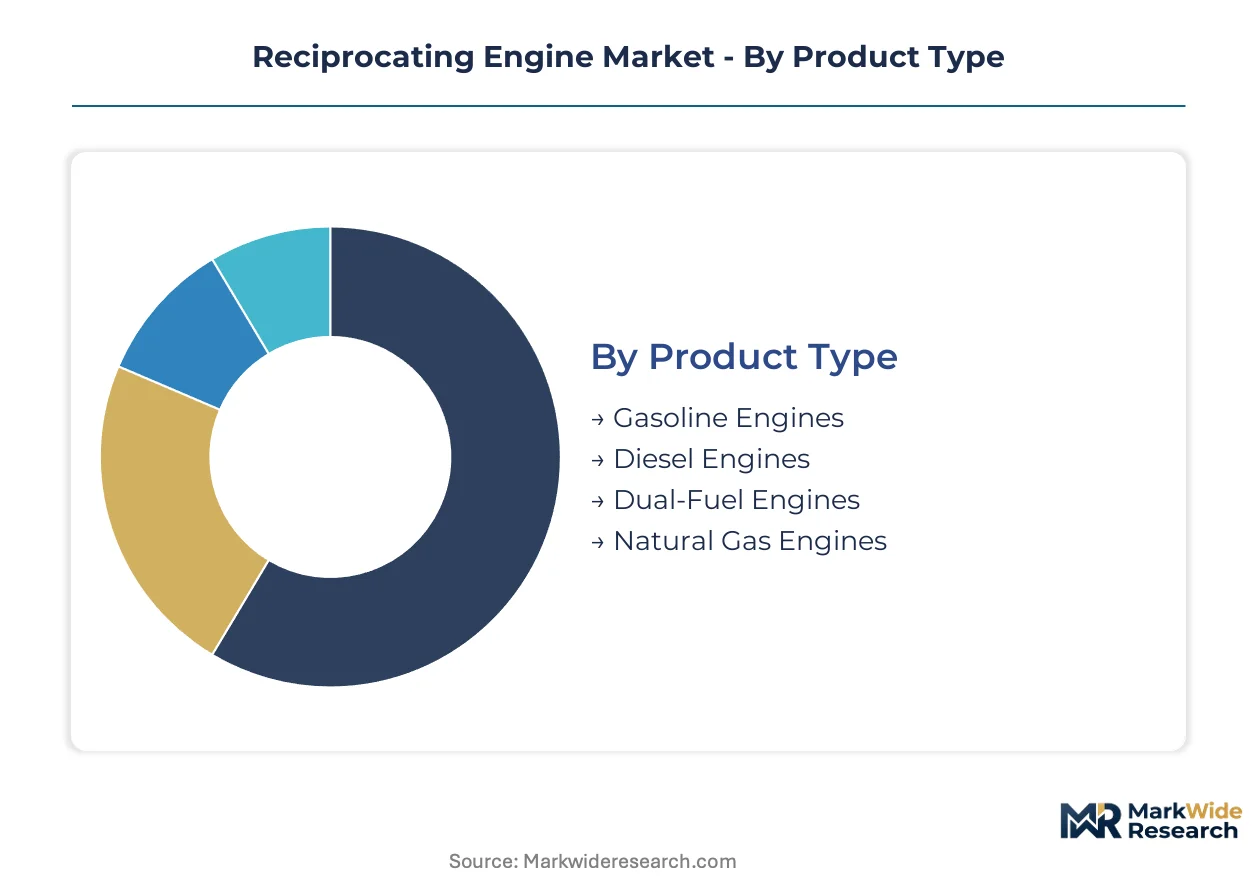
Reciprocating engine procurement patterns diverge sharply across fuel types, end-use applications, and installation contexts. Buyers in data centers, marine shipping, and remote mining prioritize fundamentally different performance attributes, forcing suppliers to maintain parallel product architectures.
Product Type:
Cost tier separates buyers seeking fuel arbitrage flexibility from those prioritizing capital discipline and single-fuel simplicity.
- Diesel Engines:Compression-ignition architectures dominate heavy-duty transportation and remote power generation where fuel logistics favor liquid fuels over pipeline-dependent alternatives. Demand concentrates in mining contractors across Western Australia and Chilean Atacama, driven by torque density requirements and established refueling infrastructure.
- Natural Gas Engines:Spark-ignited designs with stoichiometric or lean-burn combustion chambers represent the fastest-expanding category as methane pipeline density improves in industrial clusters. Installations in Gujarat and Maharashtra are displacing diesel backup systems, propelled by lower fuel costs and tightening particulate emission limits under MEE requirements.
- Dual-Fuel Engines:Pilot-ignited gas combustion with diesel backup enables fuel switching based on price spreads.
- Gasoline Engines:Port-fuel and direct-injection architectures serve light-duty automotive and small stationary applications.
Volume sits with diesel architectures; growth tilts toward natural gas and dual-fuel flexibility.
End User:
Application-specific duty cycles determine engine sizing, fuel choice, and maintenance interval negotiations.
- Power Generation:Continuous-duty and standby gensets for data centers, hospitals, and industrial facilities require rapid-start capability and grid-islanding controls. Hyperscale operators in Northern Virginia and Frankfurt are commissioning gas-fired units to manage grid instability, prioritizing energy security over marginal generation cost.
- Marine:Medium-speed and high-speed propulsion engines for deep-sea vessels and coastal craft face decarbonization mandates from the EU and IMO. Dual-fuel medium-speed architectures are gaining share fastest as shipyards seek compliance with methane slip regulations and future ammonia fuel pathways.
- Transportation:On-highway trucking, rail locomotives, and off-road equipment.
- Industrial Equipment:Construction machinery, agricultural tractors, and material handling systems.
Revenue concentrates in power generation; technology leadership is concentrating in marine propulsion.
Technology:
Maturity gradients separate legacy architectures from advanced forced-induction and electronic control systems.
- Turbocharged:Exhaust-driven compressors boost specific output and compensate for altitude derating across all power classes. Demand clusters in high-speed diesel and gas engines for data center backup and mobile industrial equipment, driven by footprint constraints and emissions compliance requirements.
- Multi-Cylinder:Inline and V-configurations with four to twenty cylinders balance power density with torsional vibration management. Marine and power generation buyers in Europe and Japan specify these for continuous-duty applications, prioritizing thermal efficiency and maintenance accessibility.
- Single-Cylinder:Compact two-stroke and four-stroke designs for small equipment and auxiliary power.
- Supercharged:Mechanically driven compression for transient response in specialized industrial applications.
Installed base tilts toward naturally aspirated designs; engineering investment flows to turbocharged and multi-cylinder platforms.
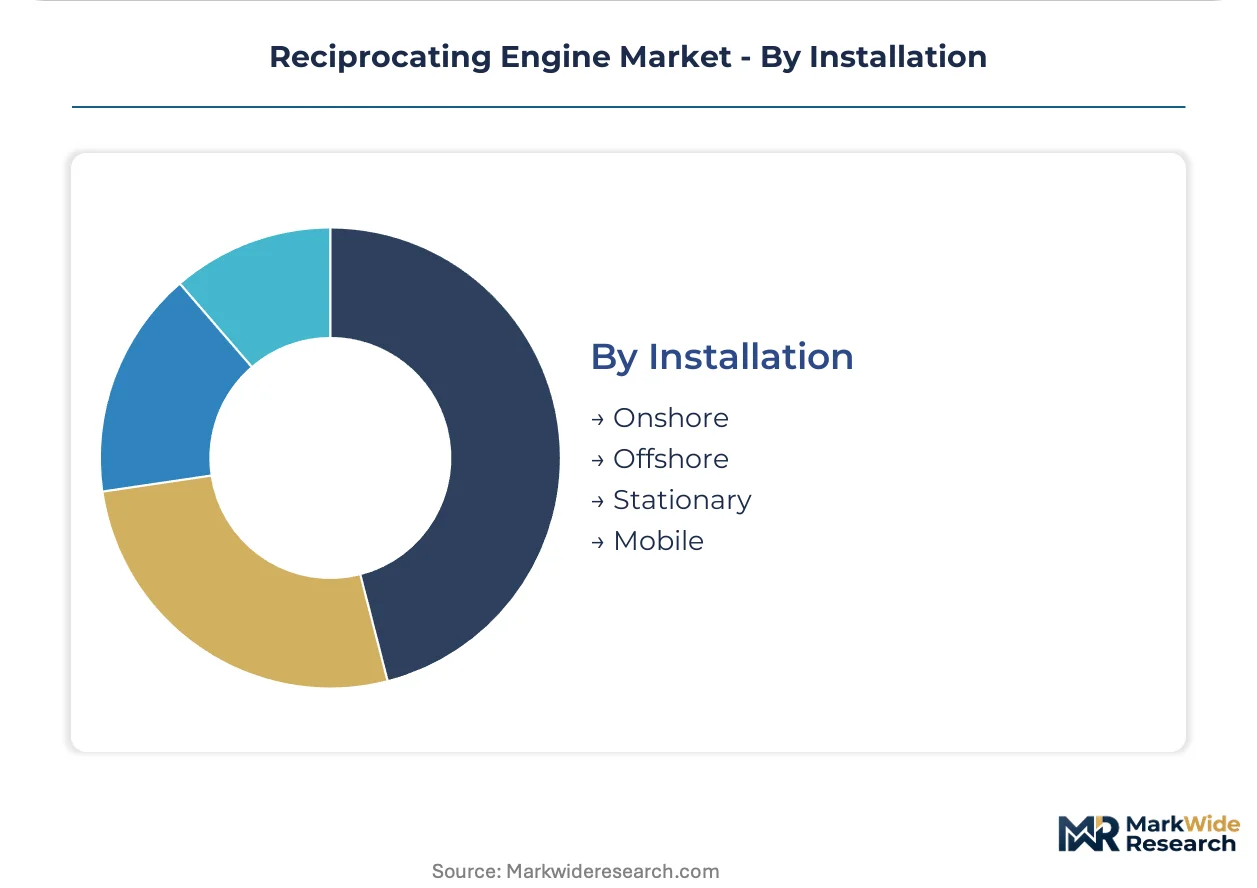
Installation:
Geographic mobility requirements dictate packaging, cooling system design, and regulatory jurisdiction.
- Stationary:Fixed installations with permanent foundations and integrated fuel storage dominate captive power and grid-support applications. Industrial clusters in India and data center campuses in Singapore specify these for long-term operational certainty, accepting higher upfront civil works costs.
- Mobile:Skid-mounted and containerized gensets enable rapid deployment across mining, construction, and emergency response contexts. Contractors in Western Australia favor plug-and-play units to compress site construction schedules from years to months.
- Onshore:Land-based power plants and industrial facilities.
- Offshore:Oil and gas platforms, floating production units, and marine vessels.
Capital commitment favors stationary installations; flexibility premiums accrue to mobile and containerized configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial demand concentrates in India where manufacturing clusters seek fuel-switching flexibility, while data center operators in the United States and Germany drive captive power expansion. Marine decarbonization mandates in Norway and Japan are reshaping engine certification priorities across export markets.
United States
Hyperscale data center operators in Northern Virginia commission gas-fired reciprocating units to isolate critical loads from grid instability. The EPA enforces Tier 4 Final emission standards, forcing selective catalytic reduction integration. Industrial buyers across Texas and Ohio prioritize energy security over marginal generation cost in captive power procurement.
Germany
Marine engine manufacturers in Hamburg and Augsburg navigate the EU's F-Gas Regulation methane slip limits for gas-fired stationary engines. The EU Green Deal tightens hydrofluorocarbon phase-down schedules, incentivizing natural gas engine adoption in commercial refrigeration. Shipyards in Bremen specify dual-fuel medium-speed architectures for decarbonization compliance.
India
Industrial clusters in Gujarat and Maharashtra commission gas-fired reciprocating units as pipeline density improves. The CEA mandates emission monitoring for captive power installations above threshold capacities. Manufacturing facilities in Tamil Nadu switch from diesel backup to continuous-duty natural gas engines for cost arbitrage.
China
MEE requirements tighten methane slip limits for gas-fired engines, reshaping combustion chamber design priorities. The dual carbon goals accelerate ammonia and hydrogen pilot projects in marine applications. Port infrastructure in Shanghai and Shenzhen drives demand for dual-fuel propulsion systems.
Japan
METI supports ammonia combustion pilots for deep-sea shipping through marine classification society certification. Shipyards in Nagoya and Kobe specify medium-speed dual-fuel architectures for future fuel pathways. Industrial facilities in Osaka adopt natural gas engines as pipeline networks expand.
Reciprocating Engine Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular containerization and digital service unbundling. The supplier base concentrates among integrated power system providers with captive financing arms and specialized combustion technology developers. Three archetypes dominate: diversified industrial conglomerates with marine propulsion heritage, pure-play engine manufacturers with high-speed diesel specialization, and energy-technology integrators with dual-fuel expertise. Competitive intensity manifests through strategic partnerships for ammonia fuel certification and geographic expansion into industrial clusters with emerging methane infrastructure.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries Ltd. and General Electric Company exemplify scale-driven positions spanning marine, power generation, and oilfield applications. MAN Energy Solutions anchors the medium-speed propulsion segment through European engineering heritage. Wärtsilä Corporation occupies a distinctive position navigating marine decarbonization mandates with dual-fuel architecture leadership. Caterpillar Inc. and Cummins Inc. represent North American manufacturing depth in high-speed diesel and integrated power systems. Rolls-Royce Holdings plc and MTU Friedrichshafen GmbH sit within the premium-performance tier serving defense and specialized industrial applications.
| Leading Market Players |
|---|
| MAN Energy Solutions |
| General Electric Company |
| Caterpillar Inc. |
| MTU Friedrichshafen GmbH |
| Mitsubishi Heavy Industries Ltd. |
| Cummins Inc. |
| Rolls-Royce Holdings plc |
| Yanmar Co., Ltd. |
| Wärtsilä Corporation |
| Others |
Supply Flow & Price Mechanics
Combustion calibration specialists in Germany and Switzerland command wage premiums that compress margin spreads between Tier 4 Final compliant engines and standard diesel architectures. OEMs offset these labor costs through modular platform standardization that amortizes engineering across EU-bound and export-only variants.
Pricing Analysis
Volume concentrates in diesel architectures while margin pools accrue to dual-fuel and natural gas platforms with fuel-switching flexibility. Price differentiation hinges on EPA Tier 4 Final certification tier and after-sales service bundling duration. Cost compression in the standard diesel tier is intensifying because platinum-group metal volatility in SCR catalysts squeezes supplier margins. Mining contractors in Western Australia exhibit highest price sensitivity, whereas data center operators in Northern Virginia prioritize energy security over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with European suppliers of medium-speed dual-fuel combustion systems for marine propulsion. Manufacturing concentrates in Germany, Finland, and Japan for high-precision fuel injection hardware. The supply chain draws from palladium and rhodium deposits in South Africa and Russia for aftertreatment catalysts, with logistics chokepoints through Rotterdam and Singapore port hubs. Distribution runs through authorized dealer networks for stationary power and direct shipyard contracting for marine applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reciprocating engine market occupies a technology-transition phase as dual-fuel architectures displace pure diesel dominance across industrial captive power and marine propulsion segments.
For Market Incumbents: Hedge fuel-cell substitution risk by accelerating ammonia combustion certification through marine classification societies in Norway and Japan. Deepen backward integration into turbocharger manufacturing to capture margin from forced-induction technology leadership. Prioritize captive financing arms to anchor long-term service contracts against third-party parts certification trends in India and Southeast Asia. For New Entrants and Emerging Players: Launch via containerized genset leasing models targeting remote mining electrification in Western Australia and Chilean Atacama. White-space sits with modular hybrid systems integrating reciprocating engines with battery storage for off-grid mineral extraction. Penetrate through digital condition-monitoring platforms that unbundle maintenance procurement from OEM lock-in. For Investors and Strategic Acquirers: The window for entry favors dual-fuel technology specialists with marine certification pathways. Long-term viability over the coming decade rests on ammonia and hydrogen combustion adaptability rather than methane-only architectures. Watch the pace of solid-oxide fuel cell efficiency gains in stationary microgrids as the critical inflection signal for reciprocating engine displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Combustion Certification | Marine classification societies in Norway validate fuel pathways that sidestep methane slip regulations. |
| Backward Integration into Turbochargers | Caterpillar and Cummins capture margin from altitude-compensation technology in data center backup. |
| Containerized Genset Leasing | Modular deployment compresses site construction schedules from years to months in Western Australia mining. |
| Digital Service Unbundling | Third-party parts certification accelerates as Indian operators leverage condition monitoring for provider switching. |
| Dual-Fuel Architecture Licensing | Wärtsilä and MAN Energy Solutions monetize marine decarbonization compliance across South Korean shipyards. |
Methodological Framework
Multi-period observation of EPA Tier 4 Final adoption rates, methane pipeline density in Gujarat and Maharashtra, and marine fuel-switching patterns anchored the trend analysis, supplemented by interviews with plant engineers at hyperscale data centers, procurement leads at mining contractors, aftermarket service heads at OEM distributors, and fuel supply specialists in LNG infrastructure. Secondary validation drew from EPA certification databases, EU F-Gas Regulation implementation tracking, ISO 8178 test cycle documentation, and customs data on engine component trade flows. Bottom-up installation counts across power generation, marine, and industrial segments were triangulated against top-down OEM revenue disclosures.
Segment-weighting applied fuel type, end-use application, and technology tier as primary dimensions across the projection horizon, with regional regulatory clusters as a cross-cutting modifier. CAGRs were derived from installed base turnover modeling and new-build capital expenditure tracking. Industry-specific forecast inputs included data center power density trends in Northern Virginia and Frankfurt, plus marine orderbook composition from shipyards in South Korea and Japan.
Platinum-group metal price shocks, accelerated fuel-cell efficiency gains, and unilateral methane slip regulation tightening are the dominant revision risks that could compress or extend reciprocating engine demand trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Turbocharger Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Automotive Camless Engine Market
Powertrain
Automotive Oil Sump Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Internal Combustion Engine Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Small Gas Engine Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Automotive PTC Heaters Market
Powertrain
Automotive Counter Shaft Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market