
 South Korea Automotive Engine Oils Market | 2026-2036
South Korea Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive Engine Oils Market Analytics
Aftermarket service revenue is fragmenting between quick-lube chains and authorized dealer networks. SK Lubricants Co., Ltd. leverages captive refinery supply to dominate synthetic product lines. S-OIL CORPORATION anchors its position through backward integration into base oil production. Hyundai Oilbank competes aggressively via service station channel control.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and neutralize combustion acids in internal combustion engines, with viscosity grades such as 0W-20 and 5W-30 specified by SAE J300 standards. Synthetic formulations command premium positioning as OEM fill specifications tighten. Passenger vehicles drive volume across distribution channels while commercial fleets concentrate purchases through direct supply agreements. Online retail captures growing share as fleet managers consolidate procurement.
MFDS oversees chemical substance registration under K-REACH, compelling additive transparency throughout supply chains. Korea Energy Agency efficiency labeling influences consumer selection at retail points. Stakeholders must monitor evolving OEM drain interval specifications and their displacement effect on total lubricant consumption.
Market Dynamics
Extended OEM drain interval specifications are compressing total lubricant consumption volumes across South Korea's automotive fleet while simultaneously elevating synthetic product specifications. This technical displacement forces reformulation investments and channel recalibration throughout the value chain.
Growth Catalysts
- K-REACH additive disclosure mandates:MFDS transparency requirements accelerate premium synthetic adoption as fleet operators demand verified additive packages for extended-drain warranties.
- Passenger vehicle fleet electrification transition:Hybrid powertrains retain internal combustion architectures, sustaining engine oil demand with specialized low-viscosity formulations.
- Seoul metropolitan concentration:Dense vehicle population in Gyeonggi province creates efficient logistics corridors for bulk lubricant distribution and rapid technical service response.
Market Restraints
- Group II/III base oil import dependency:South Korean blenders rely on regional supply chains for high-quality base stock, exposing margin compression during feedstock volatility.
- Extended drain interval displacement:OEM specifications stretching beyond 15,000 kilometers structurally reduce per-vehicle lubricant throughput regardless of fleet expansion.
- Synthetic formulation cost premiums:PAO and ester base stocks command 40-60% raw material premiums over mineral alternatives, constraining price-competitive positioning.
Strategic Opportunities
- Busan-Ulsan industrial corridor penetration:Heavy commercial fleet density in southeastern manufacturing zones remains underserved by premium synthetic distribution networks.
- Korea Energy Agency efficiency labeling leverage:Top-tier viscosity grade certifications enable retail premium positioning and fleet procurement preference anchoring.
- Digital fleet management platform integration:Oil condition monitoring sensors create predictive maintenance revenue streams and captive lubricant supply lock-in.
Industry Challenges
- Additive chemistry talent scarcity:Specialized formulators with K-REACH compliance expertise command premium compensation, constraining R&D scaling.
- Legacy distribution infrastructure retrofitting:Conventional warehouse networks require capital-intensive upgrades for synthetic product segregation and contamination prevention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive Engine Oils Market |
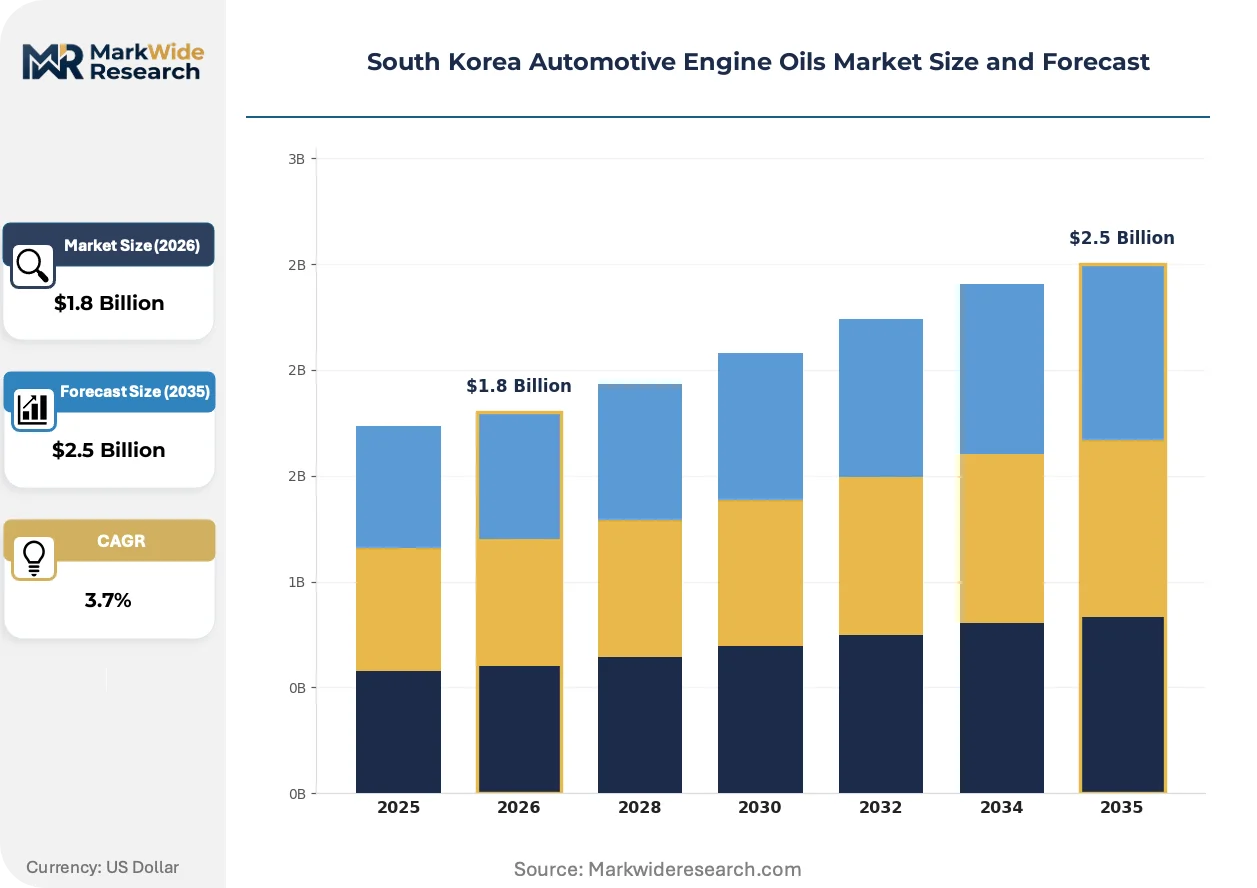
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral, Semi-Synthetic, Bio-Based Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 End User: Passenger Vehicles, Commercial Vehicles, Heavy Trucks, Motorcycles Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Supermarkets |
| Companies Covered | S-OIL CORPORATION, SK Lubricants Co., Ltd., GS Caltex, Chevron Corporation, Idemitsu Kosan Co., Ltd., Hyundai Oilbank, ExxonMobil Corporation, TotalEnergies SE, SK Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive Engine Oils Market Evolving Landscape
Reformulation priorities are converging on friction reduction chemistry and electrified powertrain compatibility. Technical specifications from domestic OEMs are tightening faster than API or ILSAC global benchmarks, creating Korea-specific product development requirements.
Low-viscosity 0W-8 and 0W-12 grades are hybridizing with high-molybdenum friction modifier packages to meet Hyundai-Kia's next-generation thermal efficiency targets. Fleet operators in Seoul's taxi and rideshare segments are adopting these specifications aggressively to maximize fuel economy credits under national efficiency programs. This chemistry trajectory is compressing demand for conventional 5W-30 formulations in urban passenger vehicle segments.
MFDS enforcement of K-REACH substance of very high concern (SVHC) candidate list expansion is forcing additive package reformulations with documented alternative chemistries. Lubricant blenders must resubmit technical dossiers for existing product registrations, creating compliance timeline bottlenecks. Small and mid-sized independent brands face disproportionate documentation burdens compared to integrated refinery-affiliated competitors.
Fleet procurement consolidation through digital platforms is displacing traditional jobber networks in commercial vehicle segments. Large logistics operators in Gyeonggi province are centralizing lubricant purchasing through direct manufacturer agreements with telemetry-linked consumption tracking. This channel compression is most visible in express delivery and cold-chain transport verticals where total cost of ownership modeling dominates supplier selection.
South Korea Automotive Engine Oils Market Segmentation
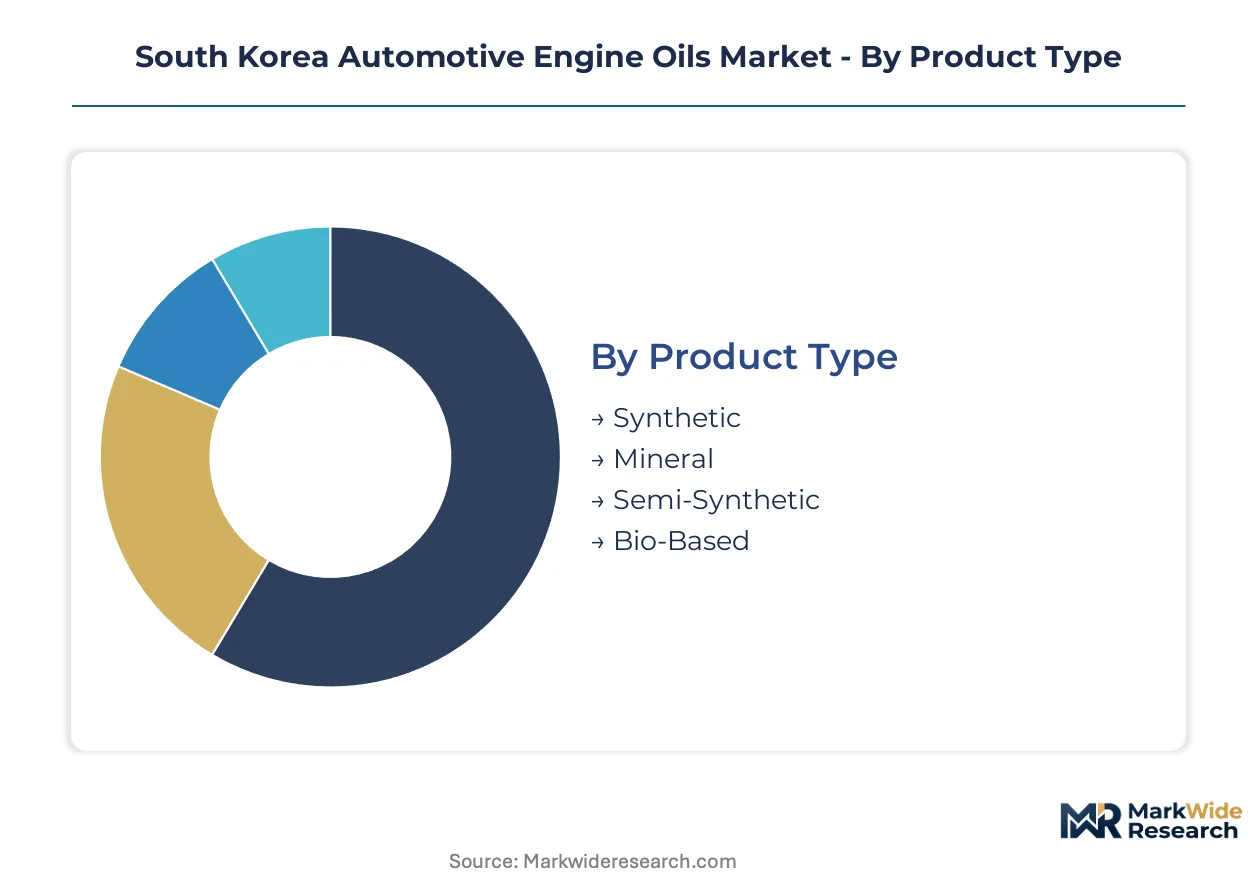
South Korea's automotive engine oils market segments along technical specifications, use-case intensity, and procurement pathways. Each dimension reveals distinct margin structures and regulatory exposure profiles that shape supplier positioning strategies.
Product Type:
Synthetic formulations span premium OEM fill requirements to extended-drain fleet specifications, while mineral products retain cost-sensitive segments. The use-case spectrum ranges from high-performance thermal stability to basic friction reduction in aging vehicle populations.
- Synthetic:PAO and Group III base stocks deliver oxidation resistance for Hyundai-Kia's 15,000-kilometer drain intervals. Seoul taxi and rideshare fleets concentrate purchases here to maximize Korea Energy Agency efficiency credits.
- Mineral:Group I base oils serve legacy vehicle populations and price-constrained independent workshops. Demand concentrates in provincial cities outside the Gyeonggi manufacturing belt where older vehicle fleets predominate.
- Semi-Synthetic:Blended formulations balance cost and performance for mid-market passenger vehicles.
- Bio-Based:Ester and vegetable-derived base stocks address K-REACH SVHC compliance pressures in environmentally sensitive procurement.
Established volume favors Mineral; emerging adoption favors Synthetic.
Viscosity Grade:
Grade selection tracks OEM thermal efficiency mandates and regional climate exposure. Cost tier differentiation separates premium low-viscosity certifications from standard multi-grade offerings.
- 0W-20:Ultra-low viscosity with high-molybdenum friction modifiers meets Hyundai-Kia's next-generation engine architectures. Gyeonggi province hybrid fleets drive fastest adoption for fuel economy optimization.
- 5W-30:Conventional multi-grade specifications dominate independent aftermarket channels. Urban Seoul service stations still stock heavily for older passenger vehicle populations.
- 10W-40:Higher viscosity protects high-mileage engines in commercial applications.
- 15W-50:Heavy-duty grade serves performance motorcycles and aged heavy truck fleets.
Volume leadership sits with 5W-30; specification momentum favors 0W-20.
End User:
Application intensity determines formulation complexity and procurement centralization. Customer type segmentation separates fragmented retail demand from consolidated fleet purchasing.
- Passenger Vehicles:Individual owners and small fleet operators generate fragmented demand across retail channels. Seoul metropolitan density enables efficient quick-lube network coverage.
- Commercial Vehicles:Express delivery and cold-chain operators in Gyeonggi province centralize procurement through direct manufacturer agreements with telemetry tracking.
- Heavy Trucks:Busan-Ulsan industrial corridor fleets require specialized high-detergent formulations for severe duty cycles.
- Motorcycles:Two-stroke and four-stroke segments demand shear-stable viscosity grades for high-RPM operation.
Fleet consolidation favors Commercial Vehicles; retail fragmentation favors Passenger Vehicles.
Distribution Channel:
Channel control determines margin capture and technical service attachment. Supply concentration separates refinery-affiliated networks from independent retail pathways.
- Online Retail:Digital platforms enable fleet procurement consolidation with consumption analytics. Large logistics operators leverage Gyeonggi-based distribution hubs for bulk lubricant scheduling.
- Auto Parts Stores:Independent jobber networks retain do-it-yourself and small workshop segments. Provincial cities depend on these channels for same-day availability.
- Service Stations:Refinery-affiliated networks control synthetic product placement and warranty-linked service bundling.
- Supermarkets:Mass retail captures emergency purchase occasions and price-sensitive consumer segments.
Channel margin favors Service Stations; volume expansion favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area buyers exhibit the lowest price elasticity as fleet operators prioritize Korea Energy Agency efficiency credits, while provincial independent workshops in Honam and Gangwon remain acutely sensitive to mineral-grade cost premiums.
Seoul Capital Area
Gyeonggi province hybrid taxi and rideshare fleets drive synthetic 0W-20 adoption for fuel economy optimization. MFDS K-REACH enforcement tightens additive disclosure for all products entering Seoul metropolitan distribution hubs. Pangyo Techno Valley hosts lubricant blender technical centers developing next-generation friction modifier packages.
Busan-Ulsan Industrial Corridor
Heavy commercial fleets in southeastern manufacturing zones concentrate demand for high-detergent formulations serving severe-duty express delivery cycles. Korea Energy Agency efficiency labeling influences procurement decisions at Busan port logistics terminals. Ulsan petrochemical complexes anchor captive base oil supply for regional blending operations.
Daegu-Gyeongbuk
Textile and electronics manufacturing fleets generate stable demand for mid-tier semi-synthetic specifications. Provincial environmental offices enforce K-REACH SVHC documentation for workshop chemical inventories. Daegu metropolitan quick-lube chains consolidate procurement through Gyeongbuk distribution cooperatives.
Daejeon-Sejong
Government fleet operators anchor demand for certified synthetic products meeting public procurement standards. Korea Energy Agency headquarters influences national efficiency labeling protocols adopted by Sejong administrative city vehicle pools. Daejeon research institutes collaborate with blenders on low-viscosity formulation testing.
Gwangju-Honam
Agricultural machinery and aging passenger vehicle populations sustain mineral-grade consumption despite synthetic transition elsewhere. Regional consumer protection agencies monitor K-REACH compliance at independent auto parts retailers. Gwangju service station networks compete on price positioning for cost-sensitive Honam basin drivers.
South Korea Automotive Engine Oils Market Competitive Landscape
Integrated refinery-affiliated blenders and multinational lubricant specialists split the market along supply-chain control versus formulation-technology axes. Domestic players leverage backward integration into base oil production while international entrants compete through OEM certification portfolios. Two strategic archetypes dominate: captive-refinery operators with channel control advantages, and technology-licensed specialists with premium synthetic positioning. Competitive intensity manifests through service station network expansion and direct fleet supply agreement capture.
Among integrated domestic operators, SK Lubricants Co., Ltd., S-OIL CORPORATION, and Hyundai Oilbank exemplify the captive-refinery archetype. SK Lubricants Co., Ltd. anchors synthetic product lines through refinery-affiliated supply security. S-OIL CORPORATION occupies a position defined by upstream base oil production control. Hyundai Oilbank represents service station channel dominance as a competitive vector. These three entities collectively illustrate how backward integration shapes competitive positioning in South Korea's lubricant value chain.
| Leading Market Players |
|---|
| S-OIL CORPORATION |
| SK Lubricants Co., Ltd. |
| GS Caltex |
| Chevron Corporation |
| Idemitsu Kosan Co., Ltd. |
| Hyundai Oilbank |
| ExxonMobil Corporation |
| TotalEnergies SE |
| SK Inc. |
| Others |
Value Network & Pricing Analysis
Group II/III base oil import dependency determines both pricing tier spreads and supply chain shape across South Korean lubricant blending operations. Feedstock volatility from regional Asian refineries compresses margins on mineral-grade products while elevating synthetic premiums, forcing blenders to anchor pricing power through captive refinery supply or absorb cost swings in competitive segments.
Pricing Analysis
After-sales service bundling drives lifetime value across refinery-affiliated service station networks. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified synthetics from dealer-channel semi-synthetics and independent workshop mineral grades. Cost compression in economy tiers is intensifying because of Group I base oil import exposure and provincial jobber price wars. Fleet operators in Gyeonggi province exhibit the lowest price sensitivity, while Honam basin independent workshops remain acutely reactive to mineral-grade premiums.
Supply Chain Analysis
Export-control scrutiny on advanced lubricant additive packages limits technology flows from select Western specialty chemical suppliers. South Korean blenders draw from Japan, Singapore, and domestic Ulsan petrochemical complexes for Group III base stocks and friction modifier chemistries. Single-source vulnerability concentrates in high-molybdenum additive packages compliant with Hyundai-Kia's next-generation specifications. Distribution runs through refinery-affiliated service station networks for synthetic products, while independent jobber channels handle mineral-grade provincial fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's automotive engine oils market sits in early-cycle expansion as hybrid powertrain proliferation sustains internal combustion lubricant demand alongside electrification transitions. Extended drain interval specifications and K-REACH compliance mandates create dual tailwinds for premium synthetic penetration.
For Market Incumbents: Pre-empt margin erosion in mineral-grade segments by accelerating backward integration into Group III base oil production and locking Gyeonggi fleet operators into telemetry-linked direct supply agreements. SK Lubricants and S-OIL CORPORATION should fortify channel control against digital procurement platforms threatening service station dominance. MFDS additive disclosure timelines present a regulatory chokepoint where integrated players can outspend independent brands on compliance dossiers. For New Entrants and Emerging Players: Pursue white-space capture in Busan-Ulsan heavy commercial corridors where premium synthetic distribution networks remain underdeveloped relative to Seoul-centric logistics. Bio-based ester formulations offer a differentiated entry vector for K-REACH SVHC-conscious procurement in Daejeon-Sejong government fleets. A digital-first fleet management platform with oil condition monitoring sensors provides the most penetrable go-to-market angle against legacy jobber relationships. For Investors and Strategic Acquirers: K-REACH SVHC candidate list expansion reshapes the acquisition landscape by disproportionately burdening small and mid-sized independent brands with documentation costs. Long-term viability centers on blenders with captive refinery supply and additive chemistry R&D capabilities. The signal to watch is MFDS enforcement intensity on existing product registration resubmissions, which would accelerate consolidation toward integrated operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Production | Ulsan petrochemical complexes anchor supply security against regional import volatility. |
| Digital Fleet Management Platform Launch | Predictive maintenance sensors create captive lubricant supply lock-in with Gyeonggi logistics operators. |
| K-REACH Compliance Certification Investment | MFDS additive transparency mandates favor blenders with documented technical dossiers. |
| Busan-Ulsan Distribution Network Expansion | Heavy commercial fleet density in southeastern zones remains underserved by synthetic channels. |
| 0W-8/0W-12 Low-Viscosity Formulation Development | Hyundai-Kia thermal efficiency targets drive specification momentum ahead of global API benchmarks. |
Research Methodology
Operator-level perspectives from lubricant blending plant managers, fleet procurement officers at Gyeonggi logistics operators, aftermarket service station operators, and MFDS regulatory affairs specialists anchored the qualitative base. Primary interview insights combined with secondary validation from Korea Energy Agency efficiency labeling databases, K-REACH registration filings, customs trade data on base oil imports, and SEC disclosures from multinational lubricant parents. Bottom-up volume modeling across viscosity grades and end-use segments triangulated against top-down refinery production capacity assessments.
Scenario-bracketing framed the analytical approach across the projection horizon, with CAGRs derived from elasticity-adjusted consumption models. Segmentation dimensions included product type (synthetic, mineral, semi-synthetic, bio-based), viscosity grade tier, end-user application intensity, and distribution channel concentration. Forecast inputs incorporated OEM drain interval specification trajectories and MFDS enforcement intensity on additive disclosure timelines.
Sensitivities concentrate around Group II/III base oil import price volatility and MFDS K-REACH SVHC list expansion timing. Forecasts reflect documented assumptions on hybrid powertrain penetration rates and fleet procurement consolidation through digital platforms. Material shifts in Hyundai-Kia thermal efficiency specifications or K-REACH enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Chain Tensioners Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Global Automotive Pumps Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Reciprocating Engine Market
Powertrain
High Speed Engine Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Crankshaft Sensor Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
Global Automotive Fuel Delivery and Injection Systems Market
Powertrain
Global Automotive Tappet Market