
 South Africa Automotive Engine Oils Market | 2026-2036
South Africa Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Engine Oils Market Analytics
SABS Mark certification is unwinding competitive access for smaller blenders without accredited laboratory infrastructure. Shell Plc leverages its downstream fuel retail network to anchor engine oil availability at Engen-branded service stations. Sasol sustains captive supply advantages through its Fischer-Tropsch base oil production at Secunda. FUCHS competes on technical service intensity for mining and agricultural OEM fill programs.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines; typical specifications include SAE viscosity grades and API service categories that define high-temperature shear stability and wear protection performance. Synthetic formulations command premium positioning due to extended drain intervals demanded by fleet operators, while mineral oils retain volume dominance in the personal user segment through price-accessible retail channels. Semi-synthetic blends capture growth in workshops seeking compromise formulations for aging passenger vehicle parc.
South Africa's National Regulator for Compulsory Specifications enforces SABS Mark requirements that gate market entry for imported lubricants, while Department of Transport emissions alignment with Euro standards shapes OEM specifications for newer vehicle cohorts. The South African Bureau of Standards periodically revises testing protocols that determine additive package acceptability. Stakeholders must monitor regulatory harmonization pressures between domestic specification autonomy and multinational OEM global oil standards.
Market Dynamics
Fleet operators in Gauteng province are compressing drain intervals while simultaneously demanding extended service life from lubricants, creating a specification tension that favors synthetic formulations with higher additive loading.
Growth Catalysts
- Extended drain interval mandates:Logistics operators serving Johannesburg's freight corridors now require oils rated for 15,000+ kilometer service cycles, pulling demand toward API SP and ILSAC GF-6 formulations.
- Euro 6 emissions alignment:South Africa's Department of Transport adoption of European emission standards for heavy commercial vehicles is forcing OEM fill specifications toward low-SAPS (sulfated ash, phosphorus, sulfur) lubricant chemistries.
- Fischer-Tropsch base oil availability:Domestic synthetic base stock production at Secunda eliminates import dependency for Group III feedstocks, compressing formulation costs for local blenders.
Market Restraints
- SABS Mark certification barriers:The National Regulator for Compulsory Specifications requires accredited laboratory infrastructure for lubricant registration, excluding smaller importers without R&D capex.
- Base oil supply concentration:Over 70 percent of Group II/III feedstock for South African blenders originates from a single domestic Fischer-Tropsch complex, creating single-source vulnerability.
- Mineral oil substitution ceiling:Price-sensitive personal vehicle owners in township retail channels resist synthetic premiums, locking volume in lower-margin categories.
Strategic Opportunities
- Mining OEM technical service contracts:Underground equipment operators in the Platinum Belt require on-site oil analysis and condition monitoring, opening service-revenue streams beyond product sales.
- Agricultural mechanization corridors:Combine harvester and tractor fleets in Free State province lack dedicated lubricant distribution, representing white-space for mobile dispensing services.
- Used oil collection regulation:Draft extended producer responsibility frameworks under the Department of Forestry, Fisheries and Environment will mandate closed-loop recycling infrastructure, favoring blenders with reverse logistics capabilities.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise for high-performance diesel engine oils concentrates among retired SABS laboratory staff, constraining product development velocity for new market entrants.
- Certification timeline compression:SABS protocol revisions for oxidation stability testing extend product approval cycles from 18 to 30 months, delaying revenue recognition for reformulated lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Engine Oils Market |
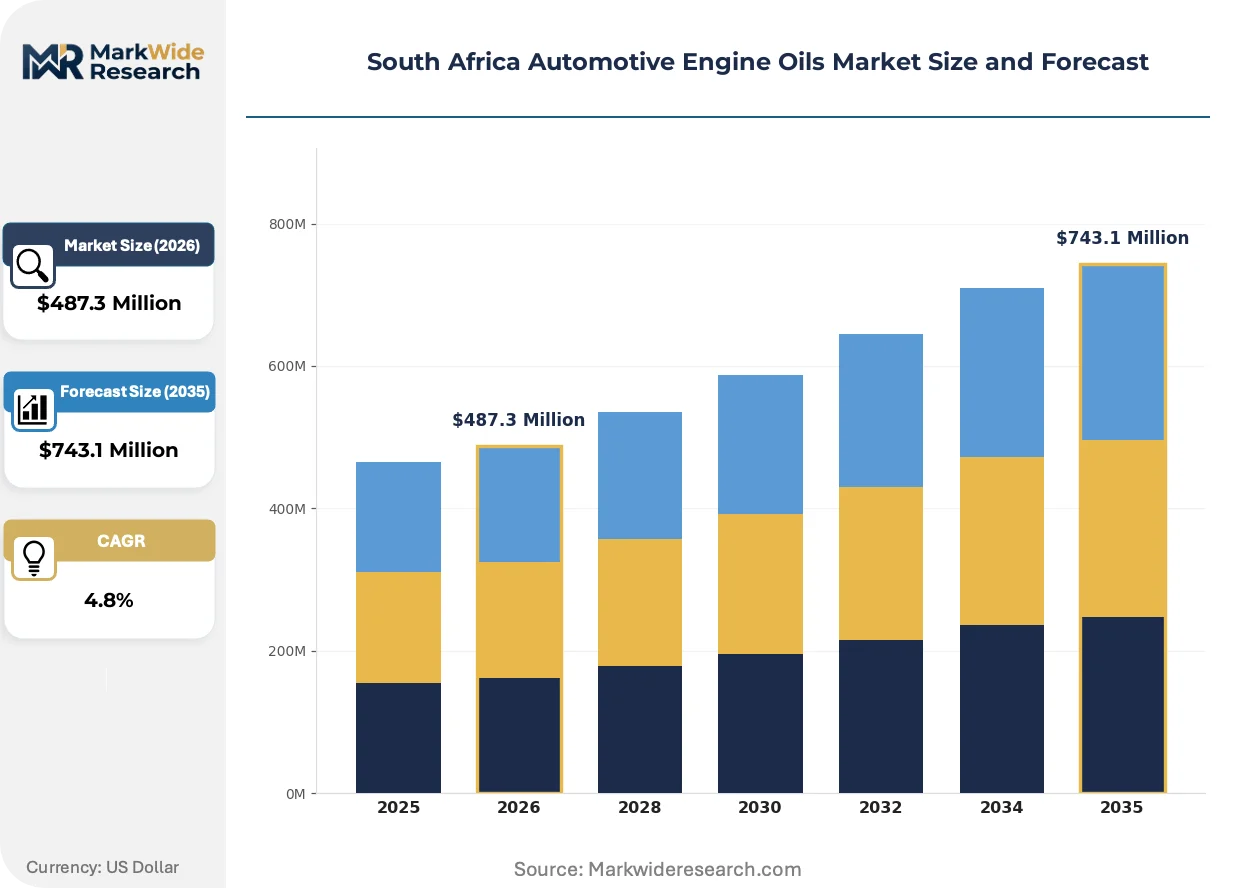
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Bio-Based End User: Passenger Vehicles, Commercial Vehicles, Agricultural Vehicles, Heavy-Duty Vehicles Distribution Channel: Retail Stores, Online Channels, Service Stations, Auto Parts Stores Customer Type: Personal Users, Fleet Operators, Workshops, Distributors |
| Companies Covered | Shell Plc, FUCHS, ExxonMobil Corporation, Sasol, Chevron Corporation, TotalEnergies, Engen Petroleum, Motul, BP p.l.c., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Engine Oils Market Evolving Landscape
Formulation chemistry and procurement models are diverging sharply between fleet operators and personal vehicle owners, with synthetic technology penetration rates splitting by customer type rather than vehicle age or engine displacement.
Polyalphaolefin (PAO) and ester-based synthetic base stocks are displacing Group I mineral oils in heavy-duty diesel formulations for long-haul operators. Fleet managers running Johannesburg-Durban corridors now specify full synthetics for 50,000-kilometer drain intervals. This displacement is compressing the addressable market for mineral-based 15W-40 products in commercial segments.
The South African Bureau of Standards is revising SANS 1099 testing protocols to incorporate high-temperature deposit control requirements aligned with Euro 6 particulate filter compatibility. Local blenders must reformulate calcium detergent systems to reduce ash content. Workshop operators in Gauteng are stockpiling pre-revision inventory to delay compliance costs.
Consolidated procurement through fuel card networks is displacing traditional workshop-based oil purchasing for commercial fleets. Engen, Shell, and TotalEnergies integrate lubricant billing with diesel transactions, capturing fleet spend at point of fueling. This channel shift is most visible among logistics operators with more than 50 vehicles under single ownership.
South Africa Automotive Engine Oils Market Segmentation
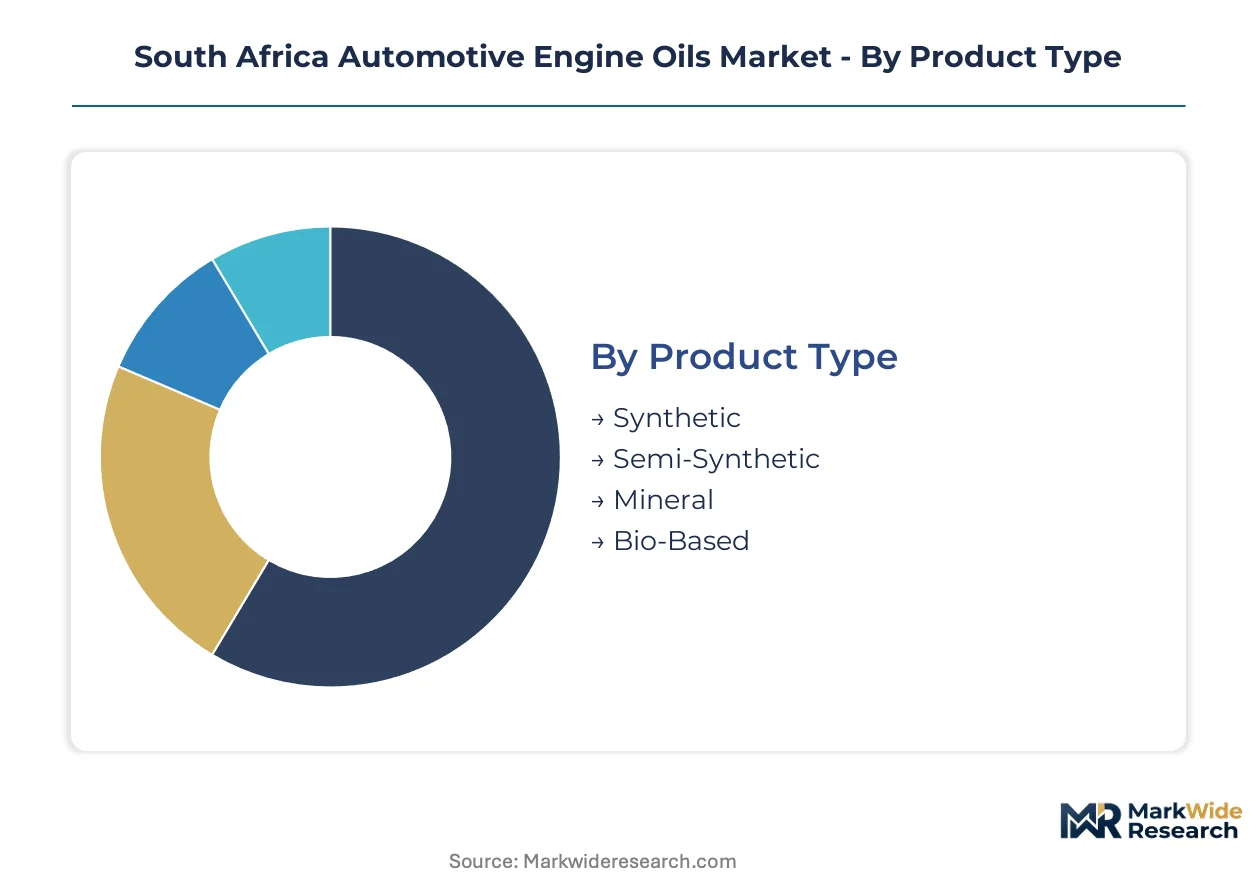
Segmentation in the South Africa automotive engine oils market reveals how substitution pressures and channel consolidation are fragmenting competitive strategy. Fleet procurement centralization and SABS certification barriers are forcing blenders to choose between volume-driven mineral formulations and premium synthetic positioning.
Product Type:
Synthetic formulations face the strongest substitution pressure as Fischer-Tropsch base oil availability at Secunda compresses cost differentials against mineral alternatives.
- Synthetic:Group III and PAO base stocks deliver 50,000-kilometer drain intervals for long-haul operators on the Johannesburg-Durban corridor. Gauteng fleet managers now mandate full synthetics for vehicles under single ownership exceeding 50 units, though SABS Mark certification delays constrain new entrant supply.
- Semi-Synthetic:Blends capture workshop demand for aging passenger vehicle parc where mineral performance proves inadequate but full synthetic pricing encounters resistance. Free State agricultural mechanics favor 10W-40 semi-synthetic for combine harvester fleets operating in dust-intensive conditions.
- Mineral:Group I base oils retain township retail channel dominance through price-accessible 15W-40 and 20W-50 grades.
- Bio-Based:Ester-derived feedstocks from domestic soy and canola oil processing remain nascent, constrained by oxidation stability failures under SANS 1099 high-temperature deposit protocols.
Mineral formulations anchor the volume base while synthetic grades gain share at the steepest rate.
End User:
Cost tier divergence separates specification-intensive commercial operators from price-sensitive personal vehicle owners.
- Passenger Vehicles:Personal owners in Gauteng townships and Cape Town informal settlements drive 15W-40 mineral oil volume through spaza shop retail. Euro 6 pre-buy activity among Johannesburg upper-income households is pulling API SP synthetic demand for newer vehicle cohorts.
- Commercial Vehicles:Logistics operators serving Durban Container Terminal and Richards Bay Coal Terminal specify low-SAPS 5W-30 synthetics to protect diesel particulate filters. Fleet consolidation among Johannesburg-based road freight companies concentrates procurement through fuel card networks.
- Agricultural Vehicles:Tractor and harvester fleets in Free State and North West provinces operate on extended seasonal cycles with limited workshop infrastructure.
- Heavy-Duty Vehicles:Mining haul trucks in the Platinum Belt require 500-hour drain interval oils with extreme pressure additive packages.
Commercial vehicles generate the highest per-liter margins while agricultural applications present the most underdeveloped service infrastructure.
Distribution Channel:
Channel concentration in fuel retail networks is displacing traditional workshop-based purchasing for fleet accounts.
- Retail Stores:Mass merchandisers in Gauteng shopping malls stock 1-liter and 5-liter packs for DIY personal users. Pick n Pay and Shoprite shelf space allocations favor established brands with SABS Mark visibility.
- Online Channels:E-commerce penetration remains limited by lubricant shipping weight economics and counterfeit product risks. Takealot and Loot.co.za list primarily 1-liter consumer formats.
- Service Stations:Engen, Shell, and TotalEnergies forecourt shops integrate lubricant with diesel billing through fleet card systems. This channel captures Johannesburg logistics corridor demand from operators with centralized procurement functions.
- Auto Parts Stores:Midas and Goldwagen franchise networks serve independent workshops with bulk 20-liter drum formats and technical specification support.
Service stations command fleet operator loyalty while auto parts stores retain workshop trade relationships.
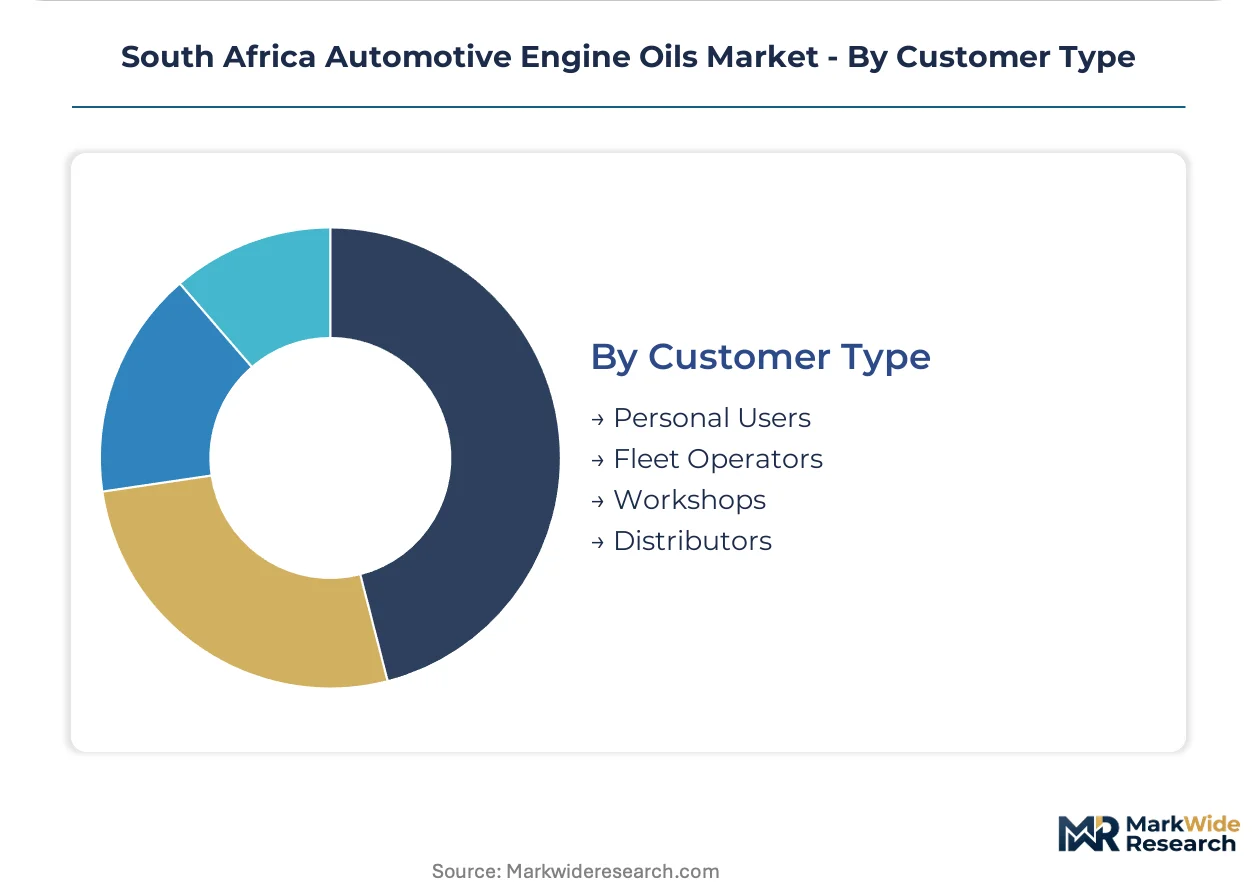
Customer Type:
Procurement authority concentration separates centralized fleet decision-making from fragmented personal user purchasing.
- Personal Users:Individual vehicle owners in Soweto and Tembisa townships purchase single-liter packs based on price visibility at spaza shops and informal retailers. Brand switching costs are negligible.
- Fleet Operators:Logistics companies with 50-plus vehicle fleets centralize lubricant procurement through fuel card networks and negotiate volume rebates directly with blenders. Technical service contracts include used oil analysis and condition monitoring.
- Workshops:Independent mechanics in Gauteng industrial zones stock semi-synthetic blends as compromise formulations for mixed vehicle parc. SABS Mark certification requirements limit supplier switching.
- Distributors:Regional warehousing operations in Durban and Cape Town maintain buffer inventory for downstream retail and workshop channels.
Fleet operators drive synthetic conversion while personal users lock volume in mineral categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Durban-Johannesburg freight corridor anchors South African logistics infrastructure, channeling bulk lubricant consumption through Gauteng's dense distribution networks. Richards Bay Coal Terminal and Durban Container Terminal generate concentrated heavy-duty vehicle traffic that drives synthetic oil demand for extended drain intervals.
Gauteng
Johannesburg's logistics corridors host the densest concentration of fleet operators in the country, with road freight companies running 50-plus vehicle fleets specifying API SP synthetics through fuel card networks. The Department of Transport's Euro 6 alignment mandates shape OEM fill specifications for heavy commercial vehicles registered in this province. The Platinum Belt mining clusters in Rustenburg and Brits require 500-hour drain interval oils with extreme pressure additive packages for underground haul trucks.
KwaZulu-Natal
Durban Container Terminal and Richards Bay Coal Terminal generate sustained demand for low-SAPS 5W-30 synthetics protecting diesel particulate filters in port haulage fleets. The South African Bureau of Standards' SANS 1099 protocol revisions force local blenders to reformulate calcium detergent systems for reduced ash content. Engen Petroleum's coastal refining and distribution infrastructure supports lubricant availability at forecourt shops integrated with fleet diesel billing systems.
Western Cape
Cape Town's informal settlements and township retail channels drive 15W-40 mineral oil volume through spaza shops serving price-sensitive personal vehicle owners. The National Regulator for Compulsory Specifications enforces SABS Mark certification that gates market entry for imported lubricants distributed through this region. Midas and Goldwagen franchise networks in the Cape Flats industrial zones serve independent workshops with bulk 20-liter drum formats.
Free State
Agricultural mechanization corridors around Bloemfontein and Welkom present underdeveloped lubricant distribution infrastructure for combine harvester and tractor fleets operating on extended seasonal cycles. Workshop operators in this province favor 10W-40 semi-synthetic formulations for dust-intensive conditions. The Department of Forestry, Fisheries and Environment's draft extended producer responsibility frameworks will mandate closed-loop recycling infrastructure favoring blenders with reverse logistics capabilities.
Mpumalanga
Sasol's Fischer-Tropsch base oil production at Secunda eliminates import dependency for Group III feedstocks, compressing formulation costs for regional blenders serving mining and agricultural equipment operators. The province's coal transport corridors generate heavy-duty diesel demand requiring extreme pressure additive packages. Local workshops stockpile pre-revision SANS 1099 inventory to delay compliance costs associated with high-temperature deposit control requirements.
South Africa Automotive Engine Oils Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and channel access. Shell Plc, TotalEnergies, and BP p.l.c. leverage downstream fuel retail networks to anchor lubricant availability at forecourt shops, while Sasol sustains captive supply advantages through Fischer-Tropsch base oil production. Three archetypes dominate: integrated energy majors with retail channel control, domestic base oil producers with feedstock security, and technical service specialists targeting mining OEM contracts. Competitive moves concentrate on fuel card network integration for fleet procurement capture and SABS Mark certification timeline acceleration.
Among integrated majors, Shell Plc and TotalEnergies exemplify the fuel-retail-anchored archetype, bundling lubricant billing with diesel transactions at service stations. Sasol occupies a distinct position as the domestic base oil producer with Secunda complex feedstock security. FUCHS represents the technical service specialist tier, competing on oil analysis and condition monitoring intensity for mining and agricultural OEM fill programs. These three patterns illustrate how certification barriers and channel concentration shape competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Shell Plc |
| FUCHS |
| ExxonMobil Corporation |
| Sasol |
| Chevron Corporation |
| TotalEnergies |
| Engen Petroleum |
| Motul |
| BP p.l.c. |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty days of finished lubricant inventory at Johannesburg distribution hubs signals how supply chain concentration in Gauteng logistics corridors translates directly into pricing power for integrated majors with captive storage infrastructure. This inventory band compresses working capital cycles for Shell and TotalEnergies while stranding smaller blenders without regional warehousing, amplifying their cost disadvantage in fleet contract bidding.
Pricing Analysis
Volume-discount tiering structures separate fleet operators purchasing 20,000-liter annual contracts from personal users buying single-liter packs at township spaza shops. Pricing stratifies across premium synthetic, semi-synthetic, and mineral economy tiers, with SABS Mark certification grade and fuel card network access serving as the primary differentiation levers. Cost compression in the mineral tier is intensifying because Sasol's Fischer-Tropsch base oil availability eliminates import premiums for domestic blenders. Personal vehicle owners in Soweto and Tembisa exhibit the highest price sensitivity, while logistics operators with centralized procurement functions show minimal elasticity for API SP formulations.
Supply Chain Analysis
Strategic stockpile preferences dominate among mining and agricultural equipment operators facing seasonal demand spikes, contrasting with just-in-time inventory management at Gauteng workshop networks. Base oil feedstock draws from South Africa's Secunda Fischer-Tropsch complex, with additive packages sourced from Singapore and the United States. Single-source vulnerability concentrates in the Secunda facility supplying over 70 percent of Group II/III feedstock for domestic blenders. Distribution runs through Engen and Shell fuel retail networks for fleet accounts, while independent auto parts stores serve workshop trade with bulk drum formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's automotive engine oils market sits in early-cycle expansion as Euro 6 emissions alignment accelerates synthetic conversion among commercial vehicle fleets. Extended drain interval mandates pull specification-intensive demand toward API SP and ILSAC GF-6 formulations faster than personal user segment substitution.
For Market Incumbents: Shield market position by accelerating SABS Mark certification timeline compression through pre-positioned laboratory infrastructure investments, countering emerging entrant threats from regional African blenders seeking South African market access. Deepen backward integration into used oil collection networks ahead of Department of Forestry, Fisheries and Environment extended producer responsibility mandates. Prioritize fuel card network exclusivity renewals with Engen and Shell to lock fleet procurement channels against TotalEnergies competitive bidding. For New Entrants and Emerging Players: SABS Mark certification fast-track partnerships with retired Bureau of Standards laboratory staff offer the most viable entry path around 30-month approval cycles that constrain product development velocity. Free State agricultural corridors present the most penetrable white-space, where combine harvester fleets lack dedicated lubricant distribution and mobile dispensing services could capture workshop relationships. Target technical service contracts with platinum mining operators as the go-to-market anchor, bundling on-site oil analysis with product supply to differentiate against established fuel-retail channels. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated energy majors seeking to divest non-core lubricant blending assets amid downstream restructuring pressures. Five-to-ten year viability hinges on feedstock security and reverse logistics capabilities rather than brand equity alone. Monitor Sasol Fischer-Tropsch base oil pricing disclosure patterns as the critical inflection signal for domestic blender margin sustainability; compression in Secunda supply costs would accelerate synthetic adoption and reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| SABS Mark Certification Acceleration | Compresses 30-month approval cycles to capture fleet synthetic conversion demand ahead of competitors. |
| Fuel Card Network Integration | Bundles lubricant billing with Engen and Shell diesel transactions to lock centralized procurement functions. |
| Backward Integration into Used Oil Collection | Builds reverse logistics infrastructure ahead of Department of Forestry, Fisheries and Environment mandates. |
| Technical Service Contract Expansion | Captures mining OEM fill programs through on-site oil analysis and condition monitoring intensity. |
| Free State Agricultural Distribution Buildout | Addresses white-space in combine harvester and tractor fleet lubricant access through mobile dispensing. |
Research Methodology
A standing panel of lubricant blending plant managers, fleet procurement officers at Johannesburg logistics operators, SABS certification laboratory directors, and Engen forecourt network managers provided ongoing calibration across the study period. This primary fieldwork combined with secondary validation from South African Bureau of Standards protocol revision notices, Department of Transport emissions alignment documentation, customs import data for additive packages, and Sasol annual reporting disclosures. Bottom-up volume modeling across synthetic, semi-synthetic, mineral, and bio-based product tiers triangulated against top-down macroeconomic elasticity assumptions.
Consistency checks validated volume and value outputs against external benchmarks including vehicle parc registration data, mining equipment fleet counts in the Platinum Belt, and agricultural mechanization statistics from Free State provincial records. The analytical framework modeled segmentation across product type, end user category, distribution channel, and customer procurement authority across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves for synthetic formulations, with fleet operator consolidation rates and SABS certification approval timelines serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained Euro 6 alignment implementation and stable Fischer-Tropsch base oil supply from Secunda; material deviation in either would warrant model refresh. Specific risk factors include abrupt Department of Transport regulatory reversal, Sasol production disruption at Secunda, or accelerated bio-based formulation breakthroughs bypassing SANS 1099 oxidation stability barriers. Revision becomes warranted when synthetic penetration in commercial vehicle segments crosses inflection thresholds that invalidate mineral volume assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Hydraulic Lash Adjuster Market
Powertrain
Transmission Repair Market
Powertrain
Tuning Box Market
Powertrain
Automotive Half Shaft Market
Powertrain
Drive Shaft Market
Powertrain
Brazil Automotive Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Transmission Sales Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Power Assisted Steering Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Automotive Active Purge Pump Market