
 High-Performance IC Engine Vehicle Market | 2026-2036
High-Performance IC Engine Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
High-Performance IC Engine Vehicle Market Foresight
Project finance and performance vehicle leasing is tilting competitive access toward capital-light entrants. Ford Motor Company leverages its modular V8 architecture to sustain manufacturing scale across multiple nameplates. Toyota Motors anchors its position through in-house production of high-compression powertrains. Mercedes-Benz Group AG differentiates via integrated motorsport-to-road technology transfer programs.
High-performance IC engine vehicles are combustion-propelled automobiles engineered for exceptional dynamic capability, typically exceeding 400 horsepower through forced induction, multi-valve cylinder heads, and forged internal components. These machines serve affluent consumers and racing professionals seeking visceral driving engagement that battery-electric platforms have not fully replicated. Turbocharged gasoline configurations occupy the dominant share of current volume, while hybrid-assisted powertrains represent the fastest-expanding technology category as manufacturers balance output with regulatory compliance. Sports cars and supercars command the deepest margin pools, though high-powered SUVs are capturing incremental demand from buyers seeking utility without performance compromise.
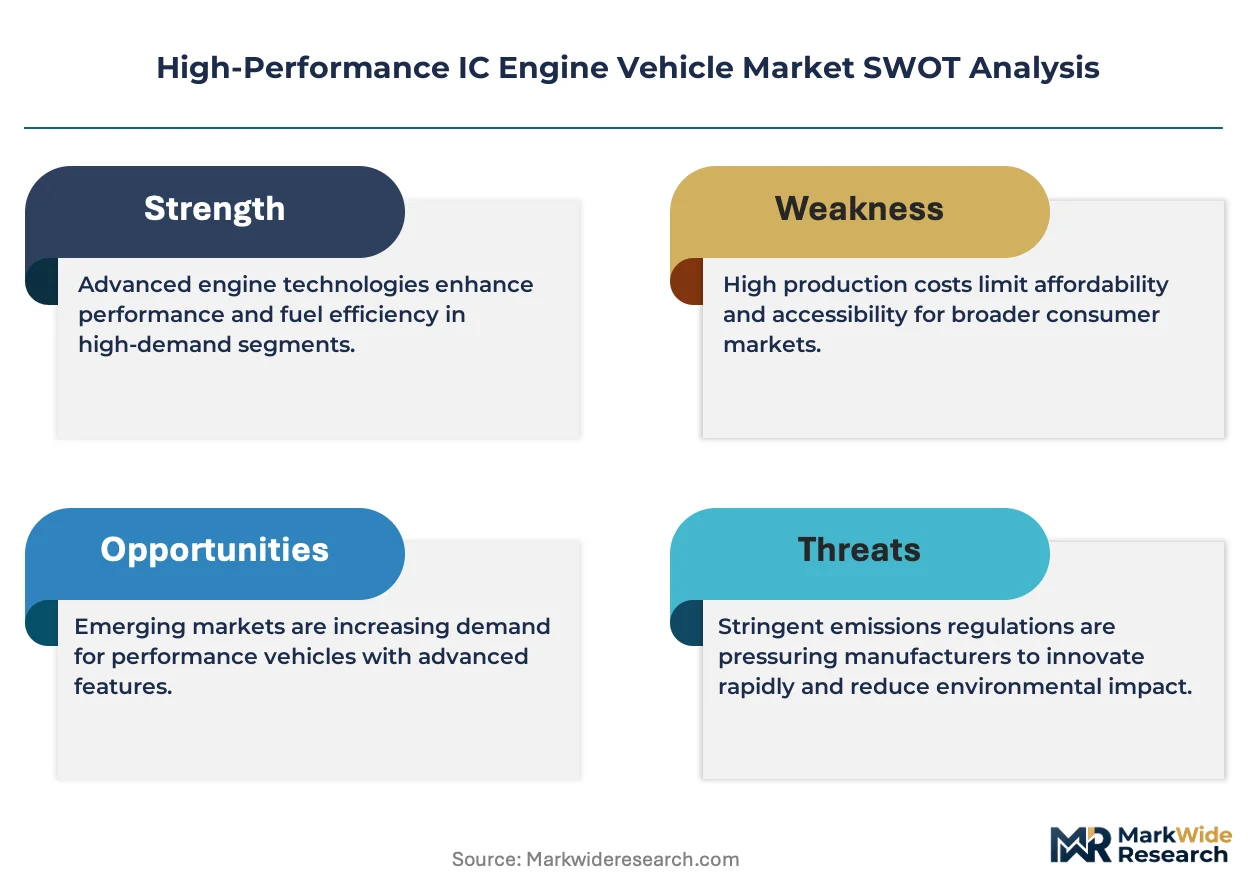
EPA tailpipe standards and Euro 7 emission frameworks are forcing powertrain downsizing and after-treatment complexity that elevates engineering costs. NHTSA fuel economy mandates in the United States further constrain large-displacement architectures, pushing development toward sophisticated thermal management and cylinder deactivation. Stakeholders must monitor how regulatory stringency in key manufacturing jurisdictions affects the economic viability of continued IC engine investment against electrification timelines.
Market Dynamics
Powertrain electrification timelines are compressing investment horizons for combustion-based performance platforms, forcing manufacturers to extract maximum technical lifespan from existing architectures while navigating tightening emission thresholds.
Growth Catalysts
- Motorsport-to-road technology pipelines:Racing series including Formula 1 and World Rally Championship serve as forced-induction development crucibles, with Stuttgart-based engineering teams transferring thermal efficiency breakthroughs to production powertrains.
- Euro 7 compliance engineering:The European emission framework mandates particulate filter integration and real-driving emission monitoring, spurring supplier innovation in gasoline particulate filter substrates and onboard diagnostic calibration.
- Hybrid-assist architectures:Belt-driven starter-generators and 48-volt electrical systems enable torque-fill during turbo lag, preserving throttle response while downsizing displacement.
Market Restraints
- Precious metal cost volatility:Platinum-group metal loading in three-way catalysts faces price pressure from South African mining concentration and automotive sector demand competition.
- Technical displacement ceiling:Thermal efficiency gains in spark-ignition engines approach theoretical limits near 45%, constraining further specific output improvements without hybridization.
- Regulatory friction from EPA tailpipe standards:NHTSA fleet average requirements penalize large-displacement configurations, compressing model-line profitability for naturally aspirated V8 derivatives.
Strategic Opportunities
- Synthetic fuel compatibility:Porsche and Siemens Energy pilot e-fuel production in Chile, creating a carbon-neutral combustion pathway that preserves existing powertrain investments.
- Track-day experience monetization:Manufacturers are bundling circuit access, professional instruction, and telemetry analysis with vehicle purchases, capturing lifetime value beyond initial transaction.
- Heritage powertrain preservation:Collector markets in the United States and Middle East are driving factory-backed restoration and remanufacturing programs for out-of-production high-performance engines.
Industry Challenges
- Calibration engineering scarcity:Combustion optimization and emission control strategy development require specialized expertise that has migrated toward battery-electric and software-defined vehicle programs.
- Homologation timeline compression:Real-driving emission test protocols extend certification cycles, delaying regional market entry and compressing model-year selling periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Performance IC Engine Vehicle Market |
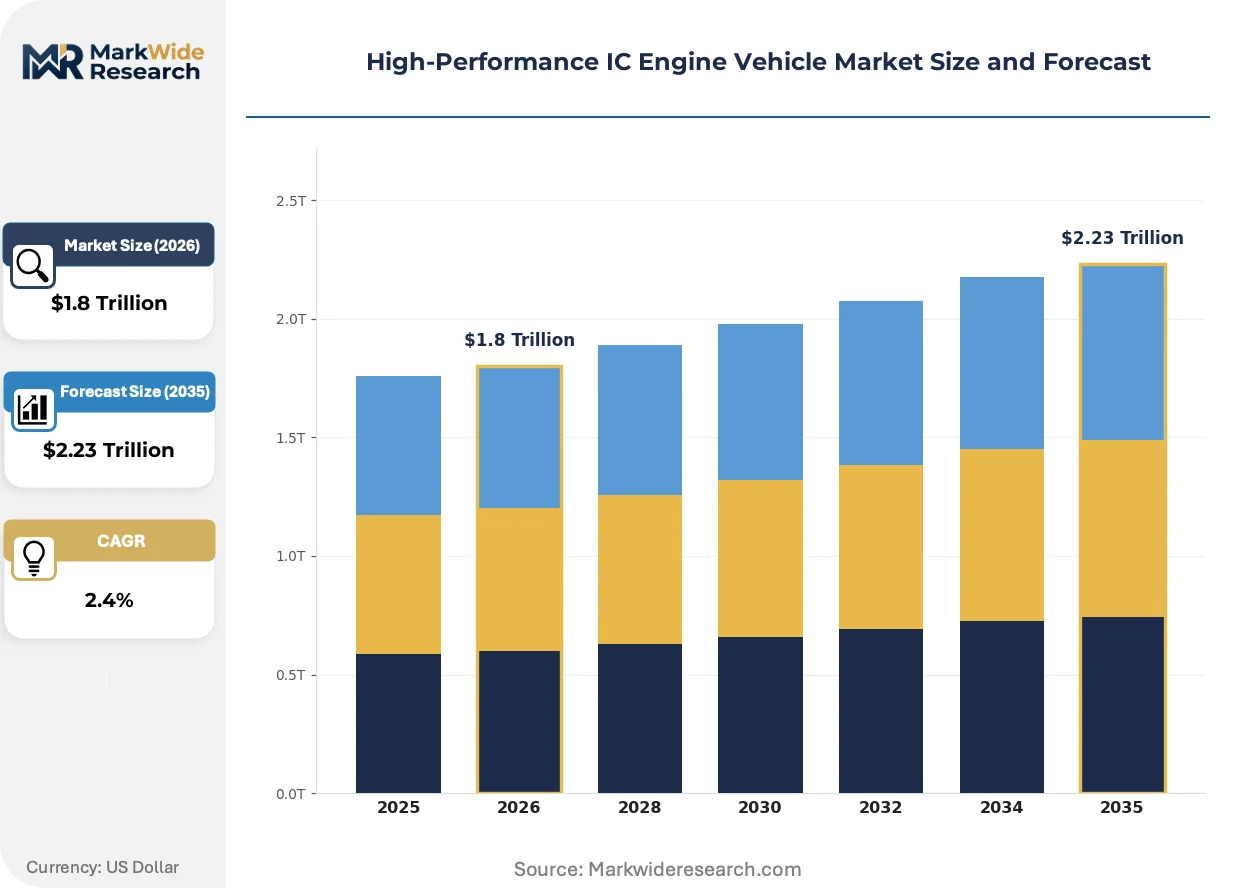
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $2.23 Trillion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sports Car, Luxury Sedan, High-Powered SUV, Supercar Technology: Turbocharged, Hybrid, Diesel, Gasoline Performance Metric: Acceleration, Top Speed, Horsepower, Torque End User: Motorsport Enthusiasts, Affluent Drivers, Racing Teams, Performance Tuners |
| Companies Covered | Hyundai Motors, Ford Motor Company, Honda Motors, Mitsubishi Heavy Industries, Mercedes-Benz Group AG, Volkswagen AG, General Motors, Cummins Inc, Toyota Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Performance IC Engine Vehicle Market Shifts & Advancements
Digital twin technology and connected powertrain telemetry are transforming how high-performance vehicles are developed, validated, and serviced. Engineering teams now simulate entire duty cycles before physical prototyping.
Pre-chamber ignition systems derived from Formula 1 are digitizing combustion control in road-going engines. Mahle and Maserati deploy turbulent jet ignition architectures that enable lean-burn operation without spark plug degradation. Track-day enthusiasts and amateur racers adopt these configurations for their thermal efficiency advantages. The technology is digitizing fuel injection mapping, allowing cloud-based calibration updates that optimize spark timing across octane grades and ambient conditions.
EPA greenhouse gas standards and Euro 7 particulate number limits are forcing gasoline particulate filter adoption across all direct-injection architectures. Engineering teams integrate close-coupled filter substrates that regenerate during highway operation. Sports car manufacturers face packaging constraints that elevate exhaust system complexity and thermal management cost. German premium brands respond with active acoustic tuning that preserves exhaust character despite filtration hardware.
Direct-to-consumer configuration platforms are displacing traditional dealer inventory models for limited-production performance vehicles. Buyers now specify paint-to-sample finishes, interior material combinations, and powertrain calibrations through manufacturer-hosted digital studios. Ferrari and Lamborghini operate invitation-only allocation systems that prioritize established collector relationships. This shift concentrates in North American and Gulf Cooperation Council markets where buyer willingness to wait for bespoke builds exceeds European expectations.
High-Performance IC Engine Vehicle Market Segmentation
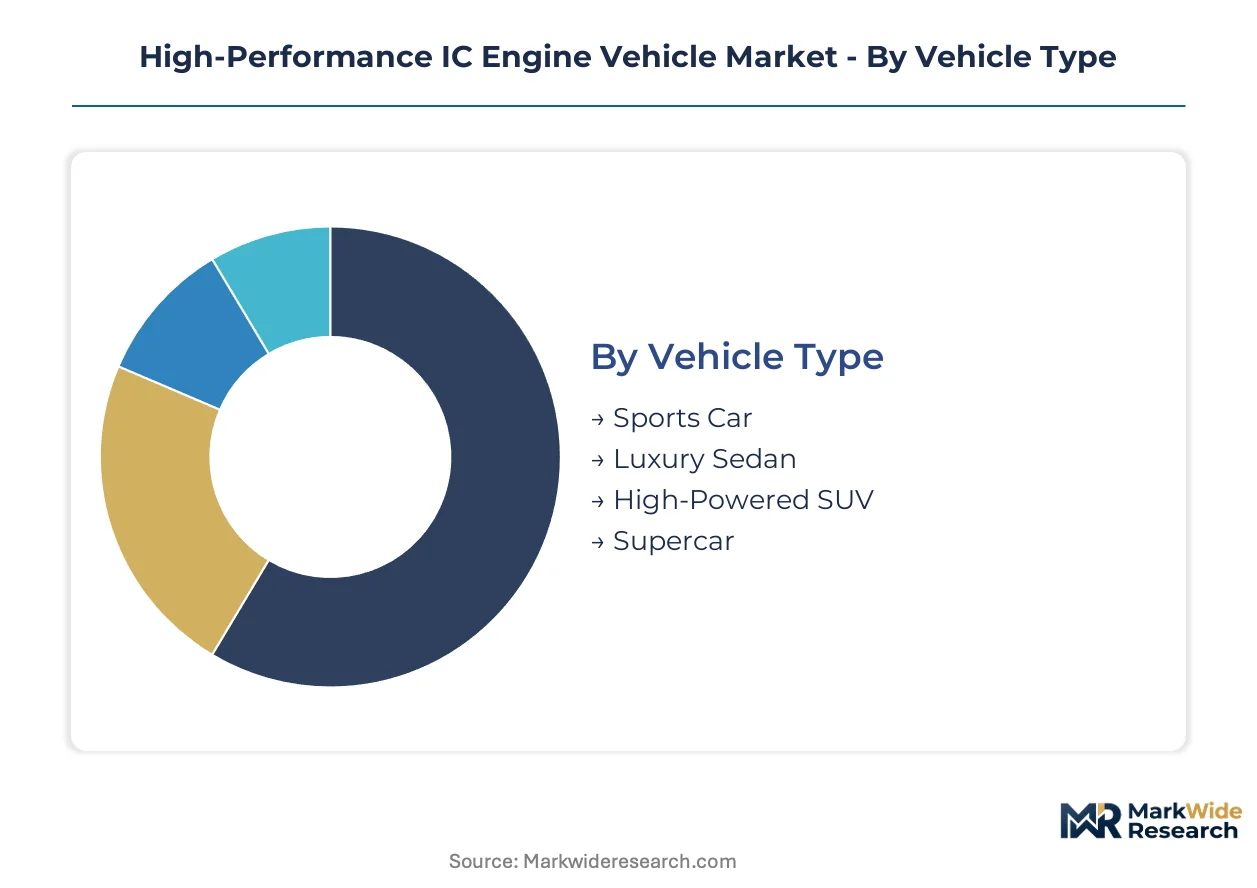
Segmentation reveals how engineering investment and buyer behavior fragment across distinct performance tiers. Each dimension exposes different margin structures, replacement cycles, and regulatory exposure that shape manufacturer portfolio strategy.
Vehicle Type:
Product lifecycles stretch from eighteen months for limited-run supercars to seven years for high-powered SUVs, creating divergent capital recovery timelines across the portfolio.
- Sports Car:Two-door configurations with sub-3,000 pound curb weights and mid-engine or front-engine rear-drive layouts. Stuttgart engineering teams concentrate development here, transferring aerodynamic packages from World Endurance Championship programs to road-legal variants.
- Luxury Sedan:Four-door architectures accommodating forced-induction V8 and V12 powertrains with adaptive chassis systems. Affluent drivers in Germany's premium corridor favor these for daily usability without performance compromise, though sedan volumes face compression from SUV demand shifts.
- Supercar:Carbon-fiber monocoque construction with active aerodynamics and 700+ horsepower outputs. Ferrari and Lamborghini allocation systems prioritize established collectors, creating artificial scarcity that sustains residual value.
- High-Powered SUV:Performance-tuned all-wheel-drive platforms combining utility with sub-4-second acceleration. This segment is expanding most quickly as Middle Eastern and North American buyers reject performance-utility tradeoffs.
Sports cars dominate installed base. High-powered SUVs are where expansion concentrates.
Technology:
Cost tiers separate established naturally aspirated architectures from emerging electrified configurations requiring supplier ecosystem rebuilds.
- Turbocharged:Forced-induction gasoline systems using twin-scroll or variable-geometry turbochargers to extract specific outputs exceeding 150 horsepower per liter. Stuttgart and Munich engineering centers lead thermal efficiency optimization for Euro 7 compliance.
- Hybrid:48-volt belt-driven starter-generators and P2 motor integrations enabling torque-fill and energy recovery. Porsche and Mercedes-Benz deploy these architectures to preserve throttle response while downsizing displacement for EPA fleet average requirements.
- Gasoline:Naturally aspirated and direct-injection spark-ignition engines, predominantly large-displacement V8 and V12 configurations. Collector markets in the United States sustain demand despite regulatory pressure on fleet emissions.
- Diesel:Compression-ignition high-performance variants, primarily European-market torque-focused configurations. BMW and Audi have phased out these powertrains for passenger applications following emission certification challenges.
Turbocharged systems dominate installed base. Hybrid architectures are climbing the fastest.
Performance Metric:
Buyer prioritization splits between measurable track performance and subjective driving engagement, with implications for instrumentation and telemetry investment.
- Acceleration:Zero-to-100 kilometer per hour times, with sub-3.0 second thresholds now achievable through launch control and all-wheel-drive traction. Drag racing enthusiasts and Middle Eastern buyers prioritize this metric above absolute velocity.
- Horsepower:Peak power output, the traditional comparative benchmark for performance marketing. Stuttgart manufacturers have pushed production vehicles beyond 800 horsepower through hybrid augmentation.
- Top Speed:Maximum velocity capability, relevant for Autobahn-legal configurations and collector bragging rights. Bugatti and Koenigsegg compete for production vehicle records exceeding 400 kilometers per hour.
- Torque:Low-RPM twisting force enabling tractable daily driving and towing capacity in high-powered SUVs. Diesel and electric-assisted configurations excel here, though diesel faces regulatory phaseout.
Horsepower dominates installed base. Acceleration is where expansion concentrates.
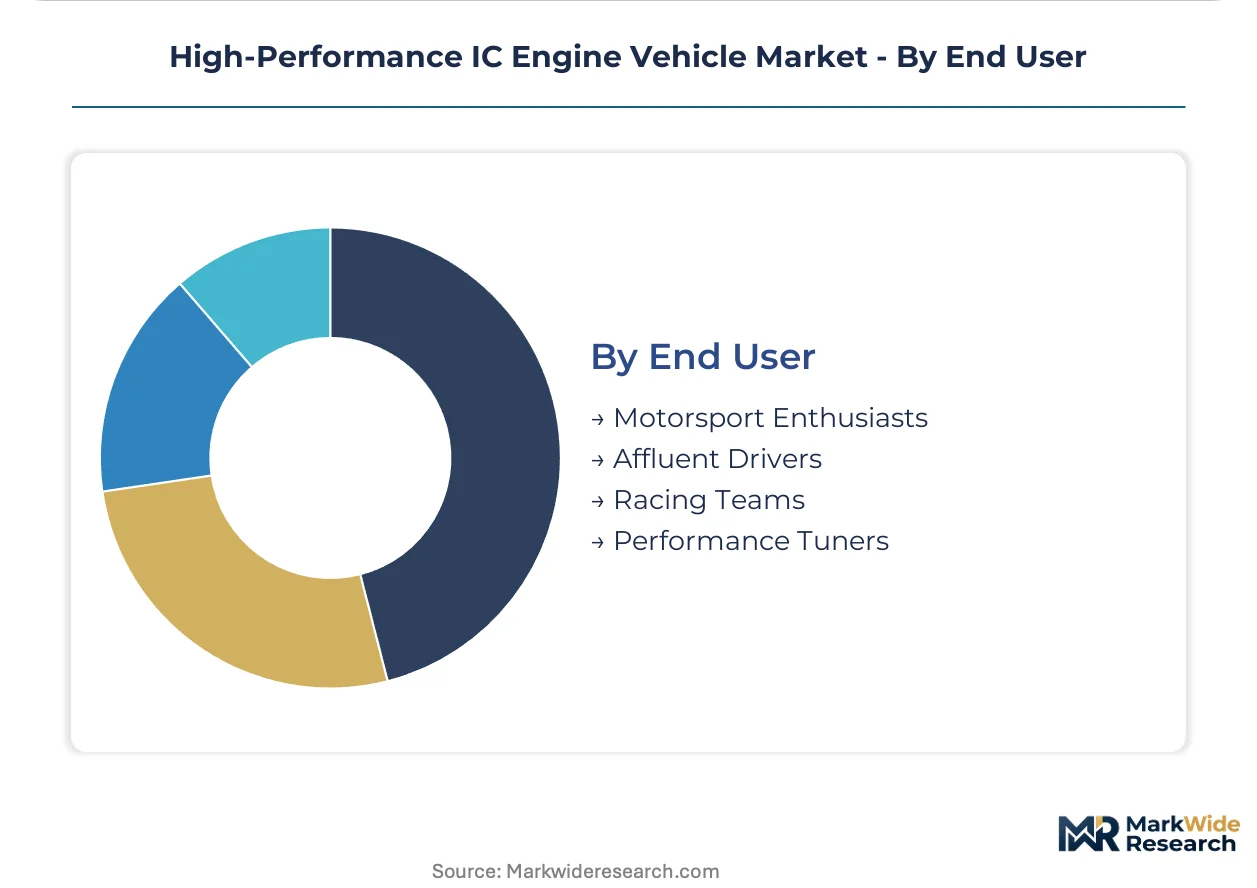
End User:
Customer type determines service attachment rates, warranty exposure, and aftermarket parts monetization potential across the ownership lifecycle.
- Affluent Drivers:High-net-worth individuals purchasing performance vehicles for daily transportation and status signaling. These buyers generate the highest service revenue per unit through factory maintenance programs and concierge delivery.
- Motorsport Enthusiasts:Amateur racers and track-day participants demanding telemetry integration and circuit-ready durability. Porsche and BMW operate driving experience centers that convert this segment to repeat purchasers through coaching relationships.
- Racing Teams:Professional motorsport competitors acquiring homologation specials and GT-category vehicles. Ferrari Challenge and Lamborghini Super Trofeo series create captive demand for race-prepared variants.
- Performance Tuners:Aftermarket modification specialists and their customers seeking powertrain calibration and hardware upgrades. EPA enforcement against defeat devices has compressed this segment's legal operating envelope in the United States.
Affluent drivers dominate installed base. Motorsport enthusiasts are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Affluent collectors and motorsport enthusiasts cluster disproportionately in mature automotive economies with established racing heritage and discretionary wealth concentration. Regulatory divergence between emission jurisdictions is fragmenting product availability and homologation timelines across markets.
United States
Drag racing culture and collector auction networks sustain demand for large-displacement naturally aspirated configurations. EPA tailpipe standards and NHTSA fleet average requirements penalize manufacturers offering high-output V8 derivatives outside hybrid-assisted architectures. Detroit-based engineering teams balance performance calibration with federal compliance through cylinder deactivation and thermal management systems.
Germany
Autobahn-legal velocity capability and premium manufacturing heritage anchor Stuttgart and Munich as global development centers for forced-induction powertrains. KBA homologation protocols and Euro 7 emission frameworks mandate gasoline particulate filter integration and real-driving emission monitoring. Stuttgart engineering corridors transfer World Endurance Championship aerodynamic packages to road-legal variants.
Japan
Kei car regulations and dense urban infrastructure have compressed domestic demand for high-displacement performance vehicles, shifting output toward export markets. METI industrial policy supports hybrid-assist architecture development through supplier ecosystem coordination. Toyota City and Nagoya manufacturing clusters specialize in high-compression powertrain production for North American and Middle Eastern buyers.
United Kingdom
Motorsport Valley concentration around Silverstone and Oxfordshire sustains Formula 1 technology transfer pipelines to production vehicle programs. DVSA emission certification and post-Brexit regulatory divergence from EU type-approval create parallel homologation burdens. McLaren Technology Centre and surrounding engineering consultancies supply calibration expertise to premium European manufacturers.
United Arab Emirates
Zero personal income taxation and subsidized fuel pricing concentrate regional demand for high-output SUVs and supercars among expatriate wealth holders. MOHAP vehicle import regulations and GCC standardization requirements govern regional specification compliance. Dubai and Abu Dhabi dealer networks operate invitation-only allocation systems for limited-production variants.
High-Performance IC Engine Vehicle Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered access structures. The market exhibits consolidated premium-tier concentration alongside fragmented volume-tier supply. Three archetypes dominate: vertically integrated premium manufacturers with motorsport heritage, scale-driven mass-market players with modular performance architectures, and hybrid-focused engineering houses balancing output with regulatory compliance. Dominant competitive moves include technology licensing partnerships for emission control systems and geographic portfolio diversification through regional specification variants.
Within the premium-tier archetype, Mercedes-Benz Group AG and Ford Motor Company occupy positions representing divergent strategic approaches to powertrain preservation. Stuttgart-based Mercedes-Benz exemplifies integrated motorsport-to-road technology transfer, while Dearborn-headquartered Ford anchors manufacturing scale through modular V8 architecture deployment across multiple nameplates. Toyota Motors sits within the hybrid-assist specialization tier, exemplifying in-house production strategies for high-compression configurations. These three manufacturers represent distinct responses to electrification timeline compression.
| Leading Market Players |
|---|
| Hyundai Motors |
| Ford Motor Company |
| Honda Motors |
| Mitsubishi Heavy Industries |
| Mercedes-Benz Group AG |
| Volkswagen AG |
| General Motors |
| Cummins Inc |
| Toyota Motors |
| Others |
Supply & Pricing Matrix
Platinum-group metal volatility in catalytic converter substrates dictates both margin compression across powertrain tiers and supplier consolidation toward captive foundry arrangements. Stuttgart and Munich engineering corridors anchor premium pricing power through vertical integration, while volume-tier manufacturers absorb PGM cost swings via long-term offtake contracts indexed to London Metal Exchange spot rates.
Pricing Analysis
Cost-plus contracts with London Metal Exchange platinum-group metal indexation dominate procurement between OEMs and catalyst suppliers. Pricing stratifies across homologation complexity tiers, with Euro 7-certified powertrains commanding substantial premiums over pre-compliant architectures. Cost compression in naturally aspirated V8 derivatives is intensifying because NHTSA fleet average penalties erode model-line profitability. Affluent collectors exhibit lowest price sensitivity, while fleet procurement managers at rental and leasing companies drive hardest bargain negotiations.
Supply Chain Analysis
Contract manufacturing capacity for gasoline particulate filter substrates concentrates at Corning and NGK Insulators foundries in Germany, Japan, and the United States. Powertrain assembly draws from forged crankshaft suppliers in China, precision camshaft grinding in Germany, and superalloy turbine casting in the United Kingdom. Single-source vulnerability in platinum-group metal refining from South African concentrators threatens catalyst cost stability. Distribution runs through captive OEM logistics networks for finished vehicles, with aftermarket parts flowing via authorized dealer channels and specialized motorsport distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where Euro 7 homologation timelines and emission calibration expertise create insurmountable barriers for unproven entrants. Incumbents leverage motorsport-to-road technology pipelines as structural switching costs that lock in collector relationships across vehicle generations.
For Market Incumbents:Entrench position through backward integration into gasoline particulate filter substrate production, eliminating single-source dependency on Corning and NGK. Acquire specialized calibration engineering boutiques in Stuttgart and Oxfordshire before talent migrates entirely to battery-electric programs. Lock in long-term PGM supply contracts before South African mining concentration triggers further price spikes.
For New Entrants and Emerging Players:Pursue heritage powertrain remanufacturing as the most penetrable white space, targeting United States and Middle East collector markets with factory-backed restoration programs. Target track-day experience monetization bundles where capital-light business models bypass heavy manufacturing infrastructure requirements. Enter through direct-to-consumer configuration platforms that displace dealer inventory models for limited-production allocations.
For Investors and Strategic Acquirers:The market sits at a late-cycle consolidation phase that favors hybrid-assist engineering specialists with proven Euro 7 compliance track records. Five-to-ten year viability hinges on synthetic fuel compatibility validation preserving combustion powertrain residual values. Monitor Porsche and Siemens Energy e-fuel pilot production milestones in Chile as the critical inflection signal for carbon-neutral combustion pathway economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Assist Architecture Investment | Porsche and Mercedes-Benz deploy 48-volt systems to preserve throttle response while downsizing displacement for EPA compliance. |
| Synthetic Fuel Compatibility Program | Porsche and Siemens Energy pilot e-fuel production in Chile, creating carbon-neutral combustion pathway for existing powertrains. |
| Gasoline Particulate Filter Integration | German premium brands adopt close-coupled filter substrates with active acoustic tuning to preserve exhaust character despite Euro 7 mandates. |
| Track-Day Experience Monetization | Manufacturers bundle circuit access and telemetry analysis with vehicle purchases, capturing lifetime value beyond initial transaction. |
| Heritage Powertrain Remanufacturing | Ferrari and Lamborghini operate factory-backed restoration programs for out-of-production engines serving United States and Middle East collectors. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement data anchors the qualitative findings. Primary interviews with powertrain calibration specialists, gasoline particulate filter substrate engineers, motorsport program directors, and collector market auction houses combined with secondary validation from KBA homologation filings, EPA certification databases, IHS Markit vehicle registration data, and London Metal Exchange PGM price records. Bottom-up segment sizing and top-down macroeconomic reconciliation triangulate volume estimates.
Calibration against historical powertrain production volumes and segment shift patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, performance tier, homologation standard, and regional production cluster. CAGRs were derived from regression analysis of installed base replacement cycles and regulatory compliance timeline impacts. Industry-specific forecast inputs incorporate Euro 7 implementation phasing and synthetic fuel infrastructure development trajectories.
Macroeconomic conditions sit as an overlay; deviation in discretionary wealth concentration, PGM mining output, and carbon credit pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stringency maintenance and collector market liquidity. Quarterly review of homologation timeline announcements, PGM spot price volatility, and e-fuel pilot production milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Car Oil Filter Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Global Automotive Clutch Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Automotive Turbocharger Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Clutch Friction Plate Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Engine Tuner Market
Powertrain
Turbocharger Actuators Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
LNG Engine Market
Powertrain
Fuel Cell Powertrain Market