
 Global Automotive Pumps Market | 2026-2036
Global Automotive Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Pumps Market Analysis
Electrification of thermal management architectures is reshaping automotive pump engineering, forcing suppliers to redesign for battery cooling loops, e-motor lubrication, and inverter heat rejection. Robert Bosch GmbH leverages its systems integration depth to bundle electric coolant pumps with thermal management modules. Denso Corporation sustains leadership in electric oil pumps for hybrid transmissions through dedicated motor-inverter manufacturing. Aisin Corporation anchors its position in mechanical water pumps for ICE platforms while scaling electric pump capacity for EV contracts.
Automotive pumps are precision fluid-handling devices, typically operating at pressures from 1 to 6 bar and temperatures spanning minus 40 to 150 degrees Celsius, engineered to circulate coolant, lubricant, fuel, or vacuum across powertrain and chassis systems. Fuel pumps retain the largest value share as direct-injection pressures climb, though electric coolant pumps for battery thermal management represent the fastest-expanding margin pool. Water pumps split between belt-driven mechanical units for conventional engines and brushless electric designs for hybrid and battery-electric vehicles, with the latter commanding premium pricing due to integrated motor control electronics.
The EPA enforces evaporative emission standards that constrain fuel pump sealing specifications in the United States, while the EU Green Deal and Euro 7 framework from the European Commission mandate tighter particulate and thermal efficiency thresholds that elevate pump precision requirements. China's MIIT enforces NEV credit quotas that expand electric pump volumes through domestic OEM procurement mandates. Stakeholders must monitor how battery-electric platform consolidation affects pump specification standardization versus customization across OEM thermal strategies.
Market Dynamics
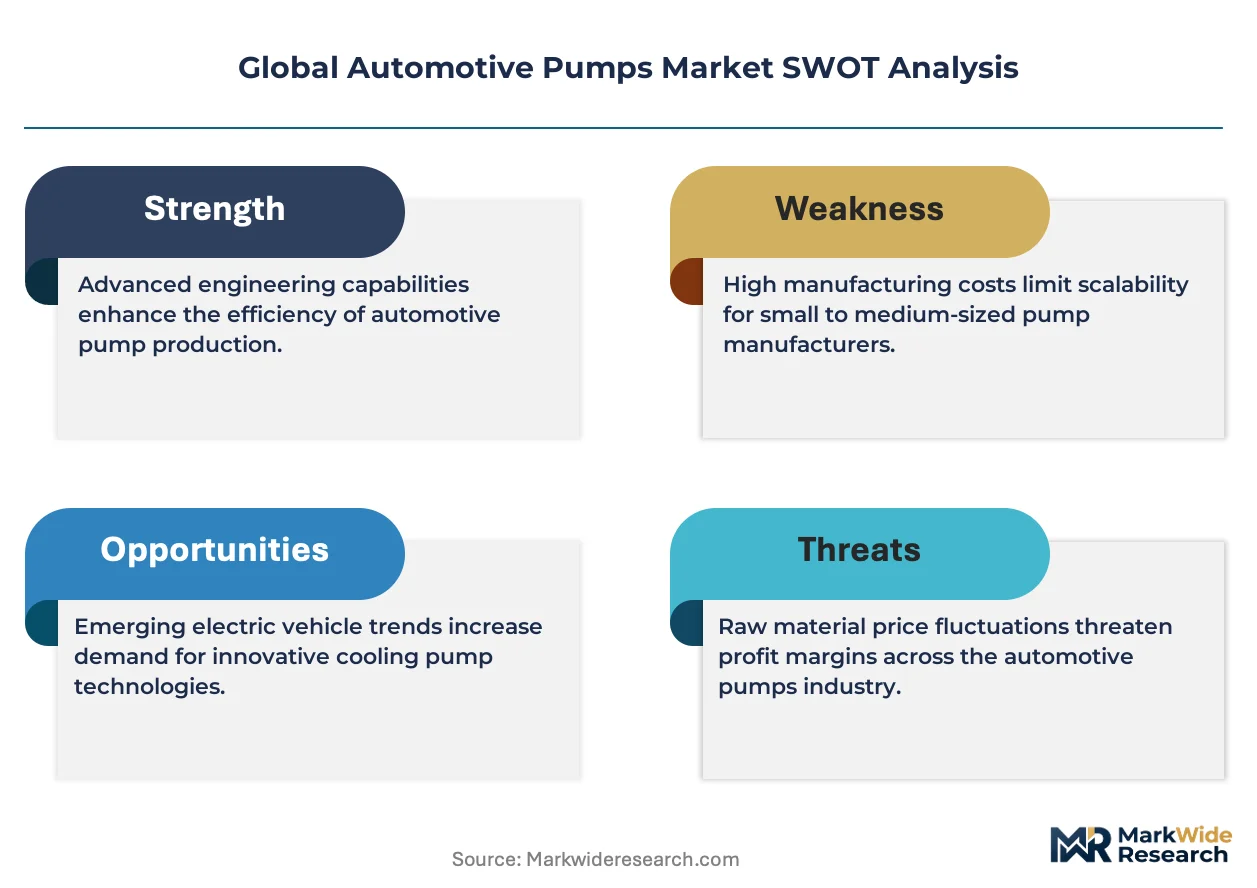
The automotive pumps sector faces a fundamental architecture split as battery-electric platforms eliminate mechanical belt-driven pumps while multiplying electric coolant pump counts per vehicle for thermal management.
Growth Catalysts
- China's NEV credit quotas:MIIT procurement mandates force domestic OEMs to source electric pumps locally, expanding brushless motor pump volumes for battery cooling loops.
- Euro 7 emissions framework:Tighter thermal efficiency thresholds from the European Commission elevate precision requirements for fuel and coolant circulation systems across hybrid and ICE platforms.
- Direct-injection pressure escalation:Gasoline engines now operate at 350+ bar fuel pressures, mandating upgraded high-pressure pump architectures with enhanced sealing specifications.
Market Restraints
- Rare earth magnet cost volatility:Neodymium price swings for brushless pump motors compress margins on electric coolant pumps just as volumes scale.
- Supplier concentration in precision machining:Germany and Japan dominate high-tolerance pump housing manufacturing, creating geographic supply risk for second-tier OEMs.
- Technical limitation in extreme-temperature sealing:Minus 40 to 150 degree Celsius operating ranges strain elastomer compatibility across coolant chemistries.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives attract pump suppliers to establish localized electric pump capacity for domestic NEV manufacturing.
- Solid-state battery thermal management:Next-generation cell chemistries require novel dielectric fluid pumps, opening white space beyond conventional glycol loops.
- Vehicle-to-grid integration:Bidirectional charging architectures demand auxiliary coolant pumps for battery conditioning during stationary power discharge cycles.
Industry Challenges
- Embedded software certification timelines:ISO 26262 functional safety validation for brushless motor control electronics extends pump development cycles by 12-18 months.
- Integration complexity with legacy thermal architectures:Hybrid platforms must synchronize electric and mechanical pumps across powertrain modes without thermal shock.
- Power electronics skill scarcity:Motor-inverter design expertise concentrates at tier-one suppliers, limiting second-tier pump manufacturers' in-house electrification capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Pumps Market |
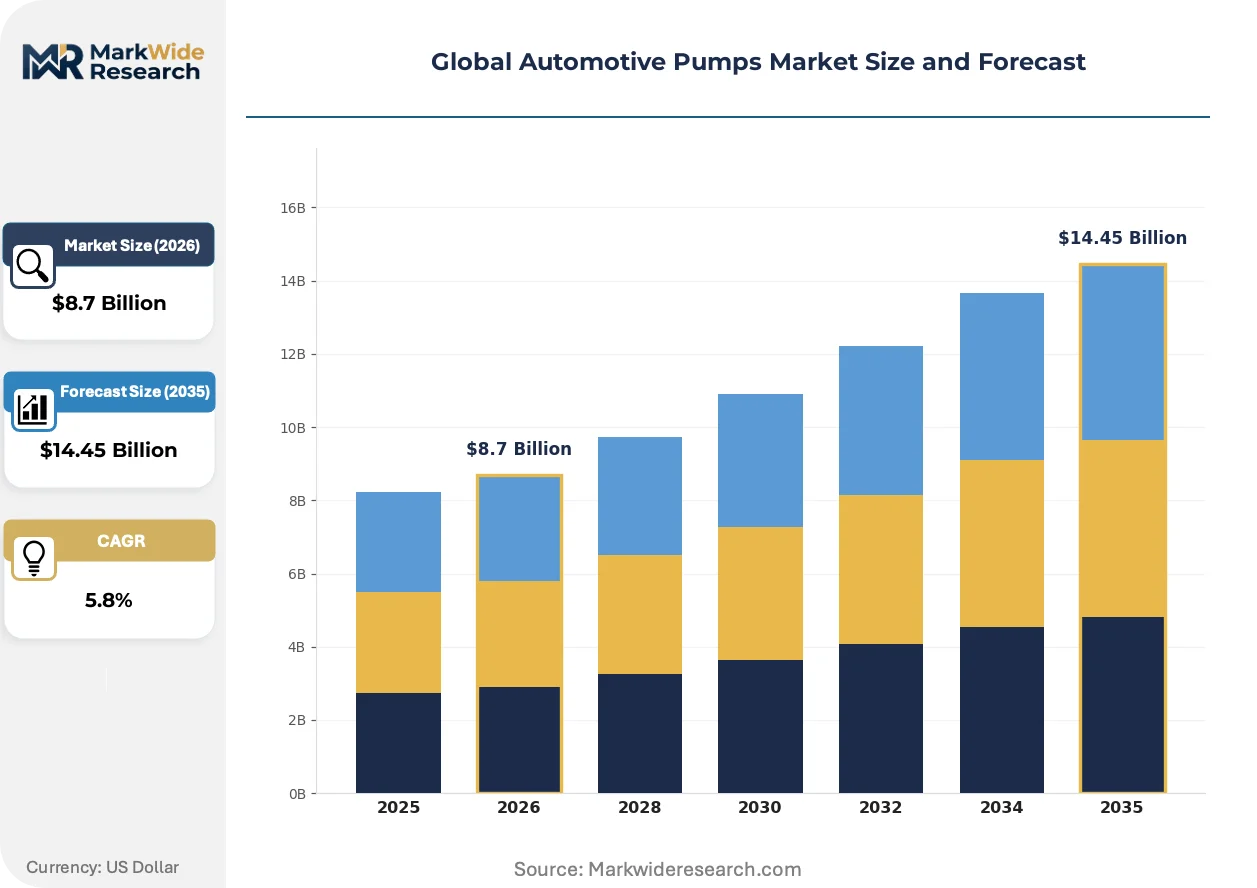
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Pumps, Water Pumps, Oil Pumps, Vacuum Pumps End User: OEMs, Aftermarket Providers, Repair Shops, Vehicle Assemblers Technology: Mechanical, Electric, Hydraulic, Pneumatic Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Aisin Corporation, Continental AG, Magna International Inc., Delphi Technologies, Johnson Electric Holdings Limited, Valeo SA, SHW AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Pumps Market Emerging Trajectories
Electrification is collapsing the traditional pump category boundaries as thermal management subsystems merge with power electronics cooling, demanding integrated mechatronic designs rather than discrete fluid-handling components.
Brushless DC electric coolant pumps with integrated motor control electronics are collapsing the historical separation between engine cooling and battery thermal management. OEMs now specify unified pump families across hybrid and battery-electric platforms to reduce part proliferation. This consolidation is collapsing supplier margins on mechanical water pumps while compressing development timelines for electric architectures.
The EU Green Deal's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in automotive climate systems, forcing pump redesigns for alternative working fluids with different viscosity and lubricity profiles. Heat pump-based thermal systems now dominate European EV platforms, elevating refrigerant pump specifications. Suppliers are responding with variable-displacement designs that modulate flow across heating and cooling modes.
Platform-level pump specification consolidation is compressing supplier counts as OEM engineering centers in Germany, Japan, and the United States mandate common thermal architectures across vehicle lines. Single-source contracts for integrated pump modules are displacing multi-vendor component sourcing. This concentration is most visible in battery-electric platforms where thermal performance directly impacts warranty exposure and range certification.
Global Automotive Pumps Market Segmentation
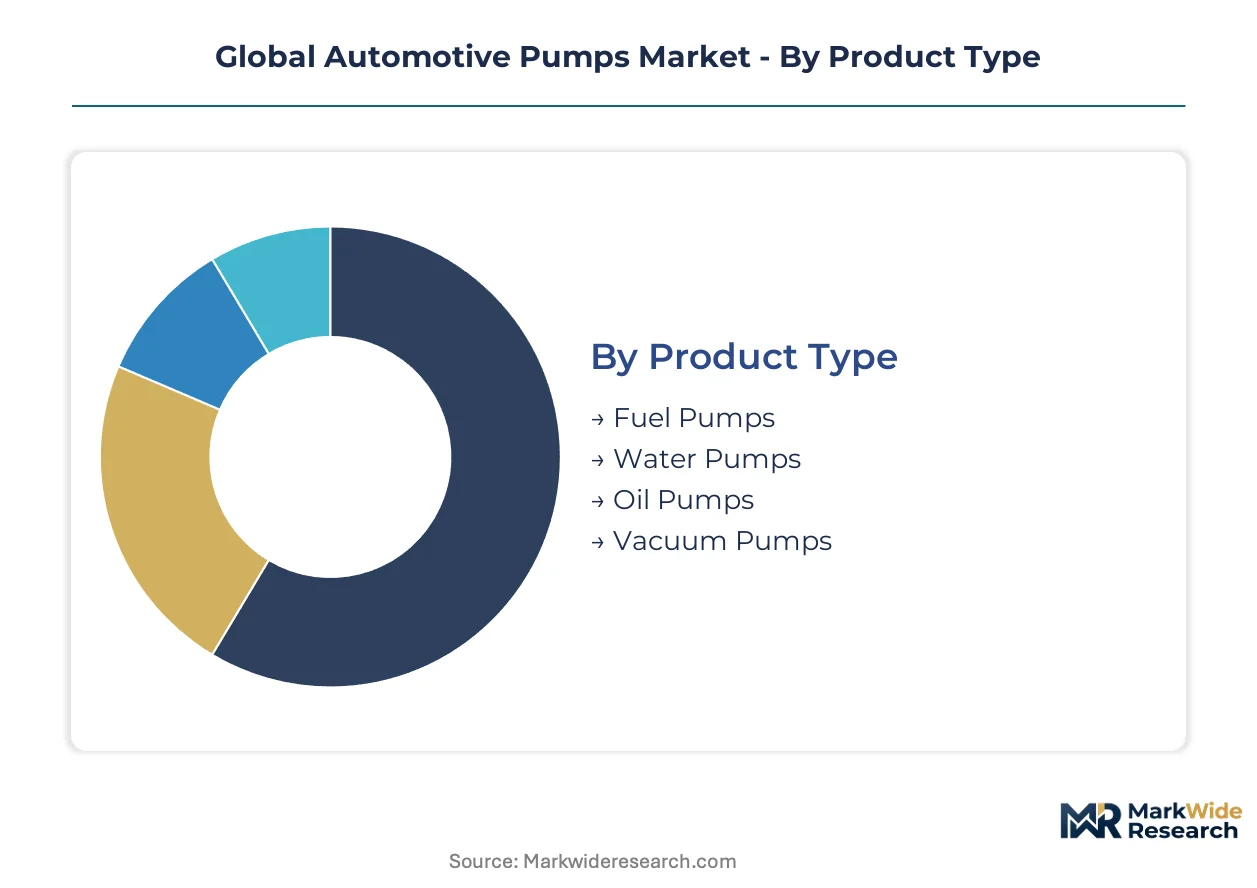
Automotive pump suppliers navigate divergent engineering requirements across powertrain architectures, customer procurement patterns, and thermal system specifications. Segmentation reveals where electric coolant technologies displace mechanical designs and which customer channels concentrate specification authority.
Product Type:
Mature mechanical pump categories face displacement pressure from emerging electric architectures as thermal management subsystems electrify.
- Fuel Pumps:High-pressure direct-injection systems operate at 350+ bar, mandating precision-machined plungers and enhanced sealing specifications. Demand concentrates in Germany and the United States where OEM engineering centers specify gasoline direct-injection platforms. EPA evaporative emission standards constrain sealing material selection.
- Water Pumps:Belt-driven mechanical units dominate conventional ICE platforms while brushless electric designs command premium pricing for battery cooling loops. China's MIIT NEV procurement mandates expand electric pump volumes through domestic OEM sourcing requirements.
- Oil Pumps:Variable-displacement vane pumps optimize lubrication pressure across hybrid powertrain operating modes. Japan's METI efficiency standards drive precision requirements for e-motor lubrication circuits.
- Vacuum Pumps:Electric vacuum pumps replace engine-driven units as brake boost systems decouple from ICE operation. European OEMs lead specification shifts for battery-electric platforms.
Fuel pumps retain volume leadership; electric water pumps hold the steepest expansion curve.
End User:
Customer concentration patterns split between specification-setting OEMs and fragmented service channels with divergent procurement economics.
- OEMs:Platform-level thermal architecture decisions concentrate at engineering centers in Germany, Japan, and the United States. Single-source contracts for integrated pump modules displace multi-vendor component sourcing as battery-electric platforms standardize.
- Aftermarket Providers:Replacement demand concentrates for mechanical water pumps and fuel pump assemblies in aging ICE vehicle populations. Distribution networks in the United States and Europe carry broad SKU portfolios for legacy platforms.
- Repair Shops:Service bay pump replacement follows vehicle age demographics and regional fleet composition. China's expanding NEV fleet creates emerging demand for electric coolant pump service protocols.
- Vehicle Assemblers:Contract manufacturing arrangements for regional production facilities source pump modules through tier-one supplier integration. India's PLI scheme attracts localized electric pump capacity for domestic NEV manufacturing.
OEMs anchor specification authority; vehicle assemblers are expanding most quickly through regional production mandates.
Technology:
Technology trajectories diverge between declining mechanical architectures and expanding electric pump platforms with embedded motor control.
- Mechanical:Belt-driven and cam-driven designs retain cost advantages for conventional ICE cooling and lubrication. Euro 7 thermal efficiency thresholds from the European Commission elevate precision machining requirements.
- Electric:Brushless DC motors with integrated control electronics enable variable-speed operation for battery thermal management. Rare earth magnet cost volatility compresses margins as volumes scale.
- Hydraulic:Power steering and transmission systems utilize hydraulic pressure generation with fixed-displacement pump architectures. Commercial vehicle applications in heavy-duty segments sustain demand.
- Pneumatic:Compressed air systems serve auxiliary functions in commercial vehicle braking and suspension. Limited passenger vehicle adoption restricts growth trajectory.
Mechanical technology retains installed base dominance; electric systems gain share fastest through powertrain electrification.
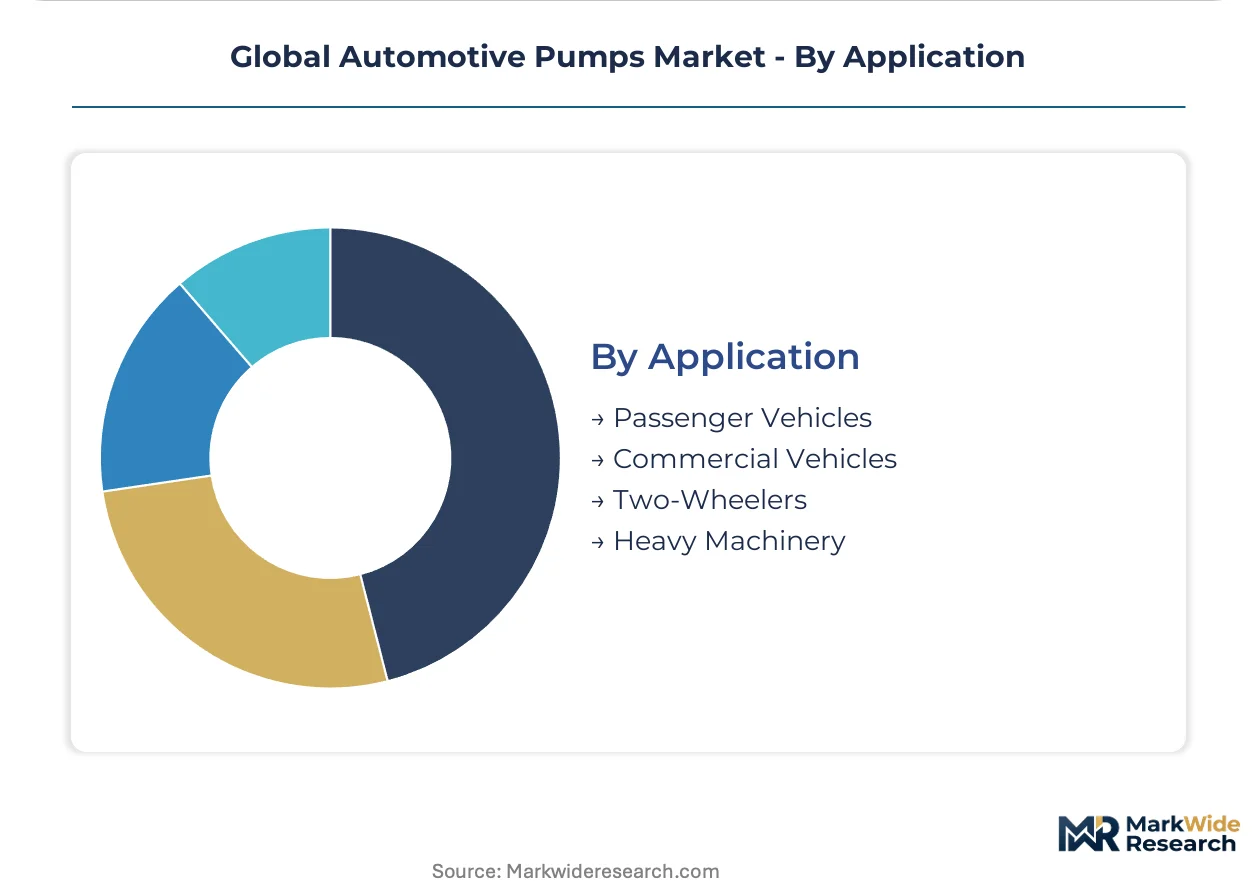
Application:
Application demand splits between passenger vehicle platform consolidation and commercial vehicle durability requirements.
- Passenger Vehicles:Battery-electric platforms multiply electric coolant pump counts per vehicle for cell, inverter, and e-motor thermal management. Unified pump families across hybrid and BEV platforms reduce part proliferation.
- Commercial Vehicles:Heavy-duty diesel applications sustain mechanical fuel and oil pump demand with extended service interval requirements. EPA and Euro 7 emission frameworks tighten fluid-handling specifications.
- Two-Wheelers:Small-displacement engines utilize compact mechanical pumps with cost-optimized material specifications. India's domestic market drives volume concentration for entry-level thermal components.
- Heavy Machinery:Construction and agricultural equipment demand high-pressure hydraulic pumps with contamination-resistant sealing. Operating temperature extremes strain elastomer compatibility across coolant chemistries.
Passenger vehicles anchor volume concentration; commercial vehicles maintain the most stable procurement trajectory through regulatory compliance cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pump suppliers export integrated thermal modules to OEM engineering centers in the United States and Japan, establishing the primary trade-flow corridor for precision fluid-handling components.
United States
EPA evaporative emission standards constrain fuel pump sealing specifications for gasoline direct-injection platforms. The Inflation Reduction Act's domestic content provisions incentivize localized electric pump manufacturing for battery-electric vehicle assembly. Detroit-area engineering centers specify platform-level thermal architectures that cascade through North American supply chains.
Germany
OEM engineering centers in Stuttgart and Munich mandate unified pump families across hybrid and battery-electric platforms to reduce part proliferation. The KBA enforces Euro 7 pre-certification timelines that compress supplier development cycles. Baden-Württemberg's precision machining clusters dominate high-tolerance pump housing production for European OEM procurement.
China
MIIT NEV credit quotas force domestic OEMs to source electric coolant pumps locally for battery thermal management systems. Dual carbon goals accelerate the phase-out of mechanical belt-driven pumps in favor of brushless DC architectures. Yangtze River Delta manufacturing hubs scale electric pump capacity to meet domestic NEV production mandates.
Japan
METI efficiency standards drive precision requirements for e-motor lubrication circuits in hybrid powertrains. Toyota City and Nagoya-area engineering centers anchor specification authority for variable-displacement oil pump designs. Domestic suppliers maintain captive manufacturing for motor-inverter integration in electric pump modules.
India
The PLI scheme for auto components attracts pump suppliers to establish localized electric pump capacity for domestic NEV manufacturing. BIS certification requirements align with global thermal management standards for export-bound vehicle production. Tamil Nadu and Gujarat automotive clusters concentrate contract manufacturing for regional OEM assembly operations.
Global Automotive Pumps Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The market structure consolidates around OEM engineering centers that mandate single-source contracts for integrated pump modules. Three archetypes dominate: diversified automotive suppliers with systems integration depth, dedicated pump manufacturers with precision machining heritage, and electric motor specialists pivoting into thermal management. Competitive moves center on M&A for motor-inverter capabilities and capacity expansion in NEV manufacturing hubs.
Within the diversified systems tier, Robert Bosch GmbH and Denso Corporation exemplify channel-controlling positions through bundled thermal module offerings. Aisin Corporation occupies a position bridging mechanical pump heritage with electric architecture scaling. Continental AG and Valeo SA sit within the European precision-engineering cluster. Johnson Electric Holdings Limited anchors the motor-specialist pivot into automotive thermal systems.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Aisin Corporation |
| Continental AG |
| Magna International Inc. |
| Delphi Technologies |
| Johnson Electric Holdings Limited |
| Valeo SA |
| SHW AG |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta electric pump manufacturing clusters compresses supplier margins while forcing tier-two producers toward aggressive pricing postures to maintain utilization rates. This utilization-driven pricing pressure cascades through procurement negotiations with domestic OEMs seeking cost absorption for battery-electric platform launches.
Pricing Analysis
Cost-plus contracts with neodymium rare-earth magnet indexation dominate electric coolant pump procurement between tier-one suppliers and OEM thermal management divisions. Price differentiation separates ISO 26262-certified brushless motor modules from standard-grade mechanical pumps, with certification tier commanding 15-25% premiums. Cost compression in standard mechanical water pumps intensifies as Chinese domestic suppliers expand capacity under MIIT procurement mandates. Aftermarket distributors exhibit highest price sensitivity due to fragmented SKU portfolios and inventory carrying costs, while OEM engineering centers prioritize thermal performance over unit cost in battery-electric platform sourcing.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for precision-machined pump housings and high-pressure fuel pump assemblies. Manufacturing concentrates in Germany's Baden-Württemberg precision machining clusters, China's Yangtze River Delta electric motor hubs, and Japan's Aichi Prefecture component corridors. Rare earth magnet supply draws from Chinese processing facilities, German permanent magnet specialists, and Japanese sintering operations. Single-source vulnerability persists in brushless DC motor controller ASICs. Distribution runs through tier-one supplier integration contracts directly to OEM assembly plants, with aftermarket channels serving legacy ICE replacement demand through regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motor-inverter design expertise concentrates at a shrinking pool of tier-one suppliers, creating a structural bottleneck that determines competitive viability across electric pump architectures. This capability scarcity rewards early movers who secure embedded software certification and thermal systems integration depth.
For Market Incumbents: Harden defensive positions by acquiring brushless motor controller design capabilities before ISO 26262 validation timelines extend further. Deepen backward integration into rare earth magnet supply through offtake agreements with Chinese processors. Prioritize certification investment for functional safety validation to maintain single-source contract eligibility with German and Japanese OEM engineering centers. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized electric pump manufacturing for domestic NEV assembly. Target solid-state battery dielectric fluid pump development as white space beyond incumbent glycol-loop expertise. Pursue joint development agreements with regional vehicle assemblers seeking localized thermal module sourcing to meet domestic content thresholds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with integrated thermal module contracts spanning hybrid and battery-electric platform generations. Long-term viability over the projection horizon rests on software-defined thermal management capability rather than discrete component manufacturing. Monitor MIIT NEV credit quota adjustments as the primary inflection signal for Chinese electric pump demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Unified pump families across hybrid and BEV architectures reduce part proliferation for German OEM engineering centers. |
| Battery Supply Agreement | Cell manufacturer partnerships secure thermal management specification input for next-generation cooling loop designs. |
| Software-Defined Vehicle Investment | Embedded motor control algorithms enable predictive pump operation across variable battery thermal loads. |
| Geographic Manufacturing Footprint | Localized capacity in India's Tamil Nadu and Gujarat clusters satisfies PLI domestic content requirements. |
| Charging Infrastructure Partnership | Vehicle-to-grid integration protocols demand auxiliary coolant pumps for stationary power discharge cycles. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of MIIT production filings, EPA emission certification databases, and EU Green Deal regulatory disclosures. Primary interviews engaged OEM platform engineers, tier-one supplier procurement directors, aftermarket distribution channel managers, and thermal systems R&D leads. Secondary validation drew from vehicle production databases, customs trade statistics for pump component flows, and IHS Markit registration data. Bottom-up segment sizing triangulates against top-down market value estimates across product type, technology, and application dimensions.
Forecast inputs incorporate powertrain electrification trajectories, regulatory compliance timelines, and platform consolidation patterns across the analysis window. Segmentation modeling spans propulsion architecture, vehicle class, content per vehicle, OEM tier positioning, and regional production cluster. CAGRs derive from unit volume projections mapped against average selling price evolution for mechanical versus electric pump technologies. Battery-electric platform ramp schedules and thermal management subsystem specifications anchor the demand-side framework.
Sensitivities concentrate around MIIT NEV quota adjustments, Euro 7 pre-certification timeline shifts, and rare earth magnet price volatility. Forecasts reflect assumptions regarding OEM single-source contract concentration and brushless motor cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
North America Torque Vectoring Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Spark Plugs Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Drive Shaft Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Automotive Transmission Repair Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Automotive Turbocharger Market
Powertrain
Tuning Box Market
Powertrain
Automotive Carburetor Market