
 Continuously Variable Transmission (CVT) Market | 2026-2036
Continuously Variable Transmission (CVT) Market Size, Share, and Industry Trends Forecast 2026-2036
Continuously Variable Transmission (CVT) Market Outlook
Steel is recalibrating CVT economics as advanced high-strength alloys replace conventional stamped components in pulley assemblies, reducing weight while maintaining clamping force tolerance. Toyota Motor Corporation leverages its captive manufacturing scale to sustain integrated CVT-hybrid powertrain output across multiple vehicle lines. Bosch differentiates through its position as a dominant force in the push-belt segment, supplying both European and Asian OEMs. JATCO anchors the global market with specialized chain-CVT architectures for front-wheel-drive applications.
A continuously variable transmission employs a system of variable-diameter pulleys and a flexible belt or chain to provide an infinite number of effective gear ratios between fixed limits, typically managing engine speed between 1,500 and 6,000 RPM for optimal thermal efficiency. The primary commercial purpose is to eliminate discrete gear steps, improving fuel economy and drivability in applications where operating cost sensitivity outweighs performance priority. Chain-type CVTs command the largest installed base among passenger vehicles due to their torque capacity advantage over rubber-belt alternatives, while toroidal designs retain niche positioning in industrial equipment where high-torque density justifies premium cost. Electronic control technology is displacing hydraulic actuation in new platforms, enabling faster ratio changes and predictive shift logic tied to navigation data.
Japan's Ministry of Economy, Trade and Industry (METI) enforces fuel efficiency benchmarks that directly incentivize CVT adoption in domestic vehicle segments, while China's Ministry of Industry and Information Technology (MIIT) imposes GB standards on transmission efficiency that shape product certification for local assembly. The U.S. National Highway Traffic Safety Administration (NHTSA) maintains corporate average fuel economy rules that push domestic automakers toward ratioless architectures in compact car portfolios. Stakeholders must monitor how electrification timelines in major automotive markets redefine the competitive window for mechanical CVT platforms against multi-speed dedicated hybrid transmissions.
Market Dynamics
Electrification timelines in major automotive markets are compressing the competitive window for mechanical CVT platforms, forcing suppliers to defend installed base against multi-speed dedicated hybrid transmissions while hybrid-integrated CVT architectures extend relevance in transitional powertrain portfolios.
Growth Catalysts
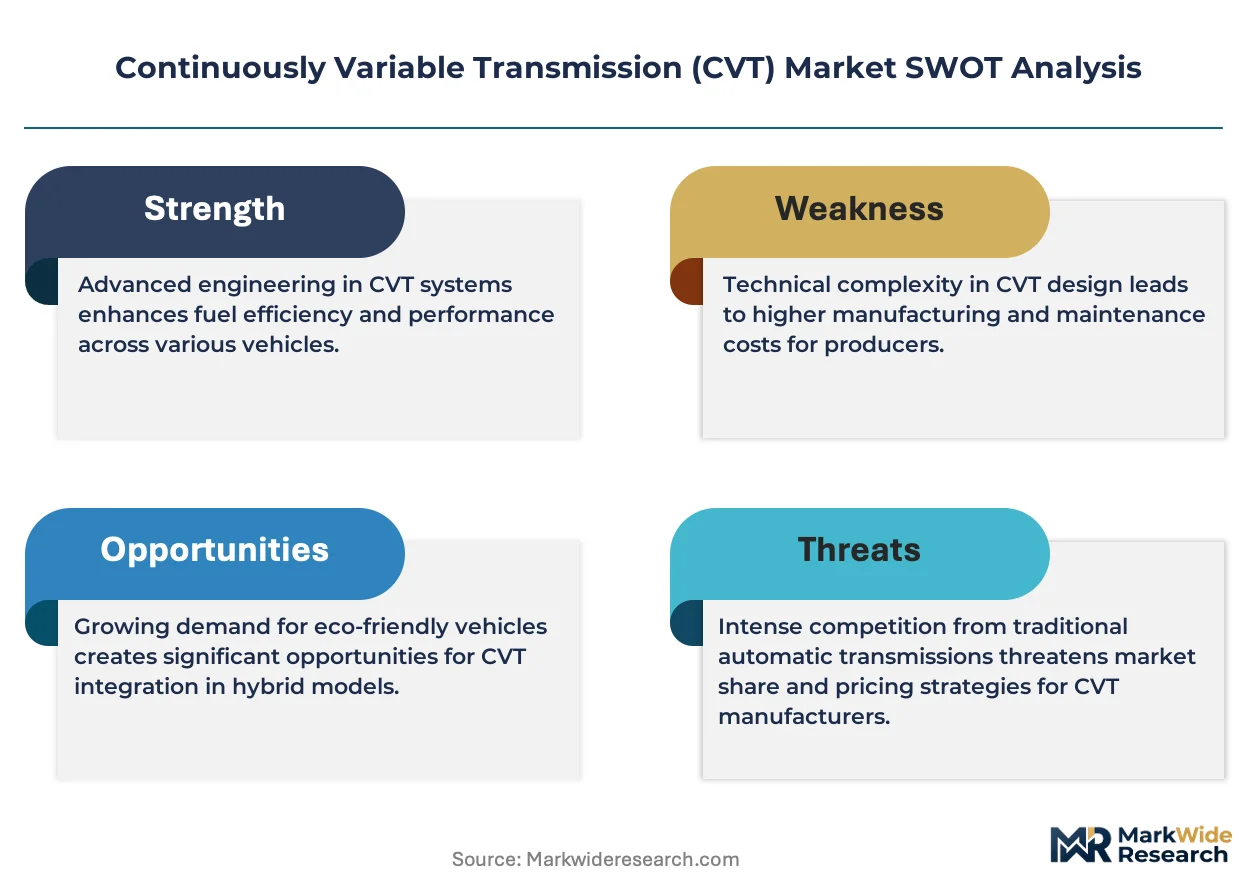
- Corporate Average Fuel Economy Standards:NHTSA mandates in the United States push domestic automakers toward ratioless architectures in compact car portfolios, sustaining CVT procurement volumes.
- Chain-CVT Production Scaling:Domestic suppliers in China expand manufacturing capacity for local OEM programs, concentrating demand within the world's largest vehicle assembly base.
- Advanced High-Strength Steel Alloys:Pulley assembly weight reduction through metallurgical innovation maintains clamping force tolerance while improving power-to-weight ratios in front-wheel-drive applications.
Market Restraints
- Input Cost Volatility:Specialty steel and precision bearing supply chains face price pressure from energy-intensive smelting operations, squeezing component margins.
- Substitution Threat:Multi-speed dedicated hybrid transmissions capture share in electrifying segments where CVT efficiency advantages diminish against torque-split hybrid architectures.
- Technical Limitation:Torque capacity ceilings in rubber-belt CVT designs restrict deployment to sub-2.0 liter engine applications, excluding performance vehicle segments.
Strategic Opportunities
- Hybrid Powertrain Integration:CVT-electric motor coupling architectures create white space in transitional vehicle segments where full electrification remains uneconomical.
- Industrial Equipment Expansion:Toroidal CVT designs penetrate high-torque density applications in agricultural and construction machinery where premium cost acceptance justifies performance gains.
- Navigation-Linked Predictive Shifting:Electronic control systems leveraging route topography data optimize ratio selection before grade changes, differentiating supplier value propositions.
Industry Challenges
- Control Software Talent Scarcity:Embedded systems engineering for real-time ratio management competes with broader automotive software recruitment, lengthening development timelines.
- Legacy Hydraulic System Integration:Electronic actuation retrofits into existing vehicle platforms require recalibration of transmission control modules, complicating model-year transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuously Variable Transmission (CVT) Market |
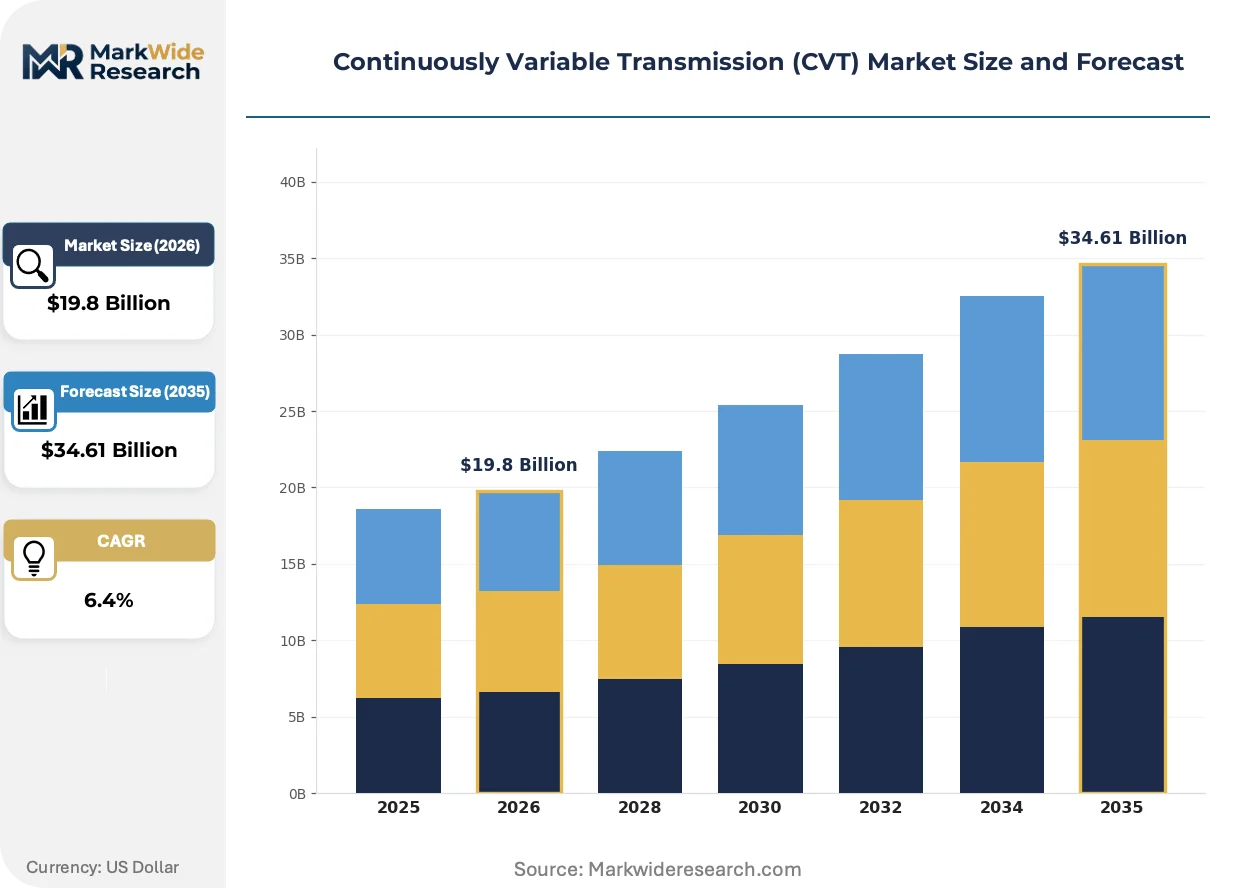
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
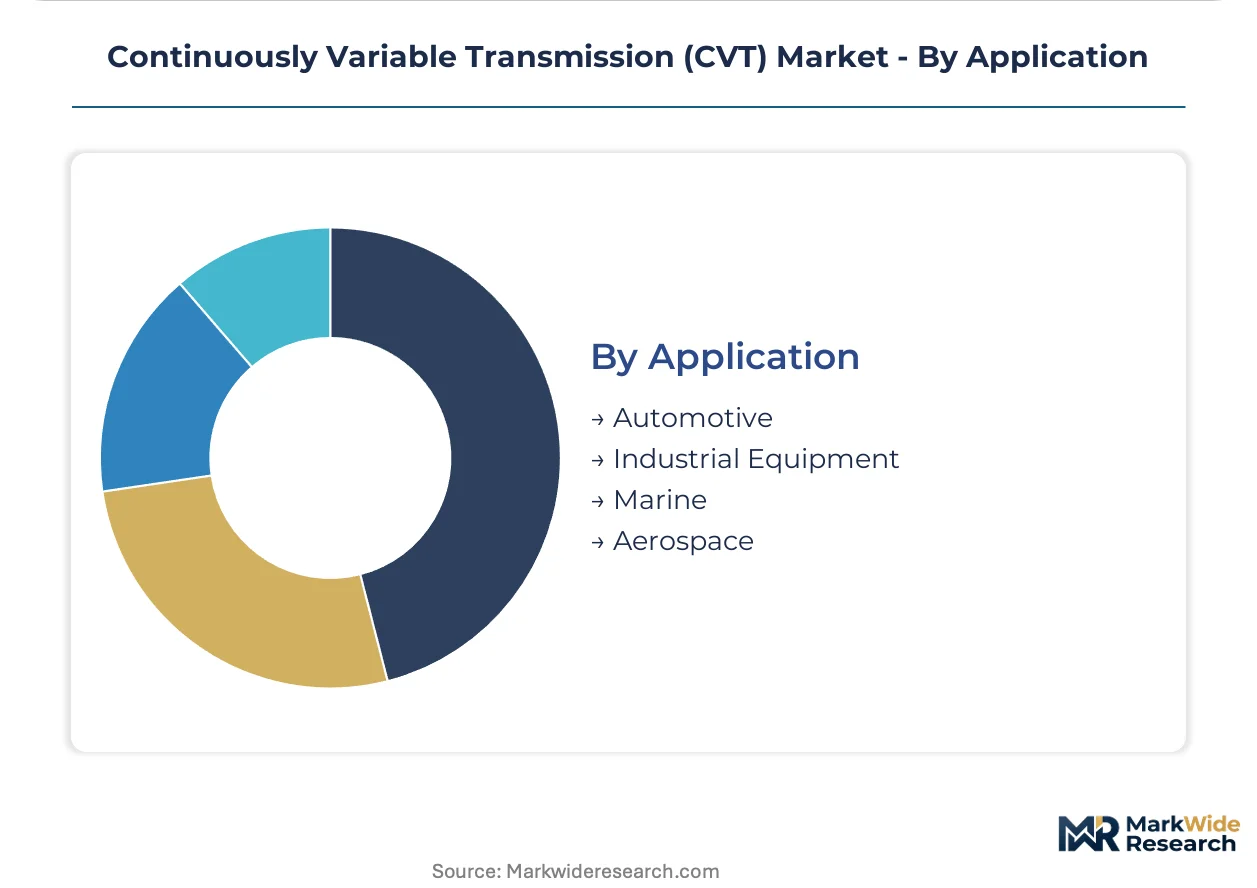
| Segmentation | Type: Rubber Belt, Chain, Toroidal, Electrical End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, ATVs Technology: Hydraulic, Mechanical, Electronic, Hybrid Application: Automotive, Industrial Equipment, Marine, Aerospace |
| Companies Covered | Punch Powertrain, Honda Motor Co., Ltd., JATCO, Nissan Motor Co., Ltd., Toyota Motor Corporation, Aisin AW, ZF Friedrichshafen AG, Wanliyang, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuously Variable Transmission (CVT) Market Strategic Shifts
Electronic control architectures are supplanting hydraulic actuation across new vehicle platforms, enabling predictive ratio management and tightening integration with powertrain software stacks.
Push-belt CVT designs are overtaking rubber-belt alternatives in mid-size passenger vehicle segments. These steel-element belts transmit higher torque loads without slippage. Japanese and Korean OEMs have standardized push-belt architectures across 1.5-2.5 liter engine lines. The technology is overtaking chain-CVT cost structures in applications where torque density requirements sit below 400 Nm, compressing supplier differentiation to electronic control sophistication.
China's MIIT GB standards on transmission efficiency reshape product certification requirements for local assembly operations. The regulations mandate minimum mechanical efficiency thresholds that disqualify first-generation hydraulic CVT designs. Tier-1 suppliers accelerate electronic control module localization to maintain program eligibility. Southeast Asian export markets adopting Chinese regulatory baselines extend compliance pressure beyond domestic assembly.
Fleet procurement contracts now specify total cost of ownership metrics rather than unit transmission pricing, unbundling hardware from calibration service agreements. Rental and ride-hail operators in urban China negotiate predictive maintenance packages tied to telematics data streams. Component suppliers reposition around software-enabled service revenue, with hardware margins compressing toward commodity levels in high-volume segments.
Continuously Variable Transmission (CVT) Market Segmentation
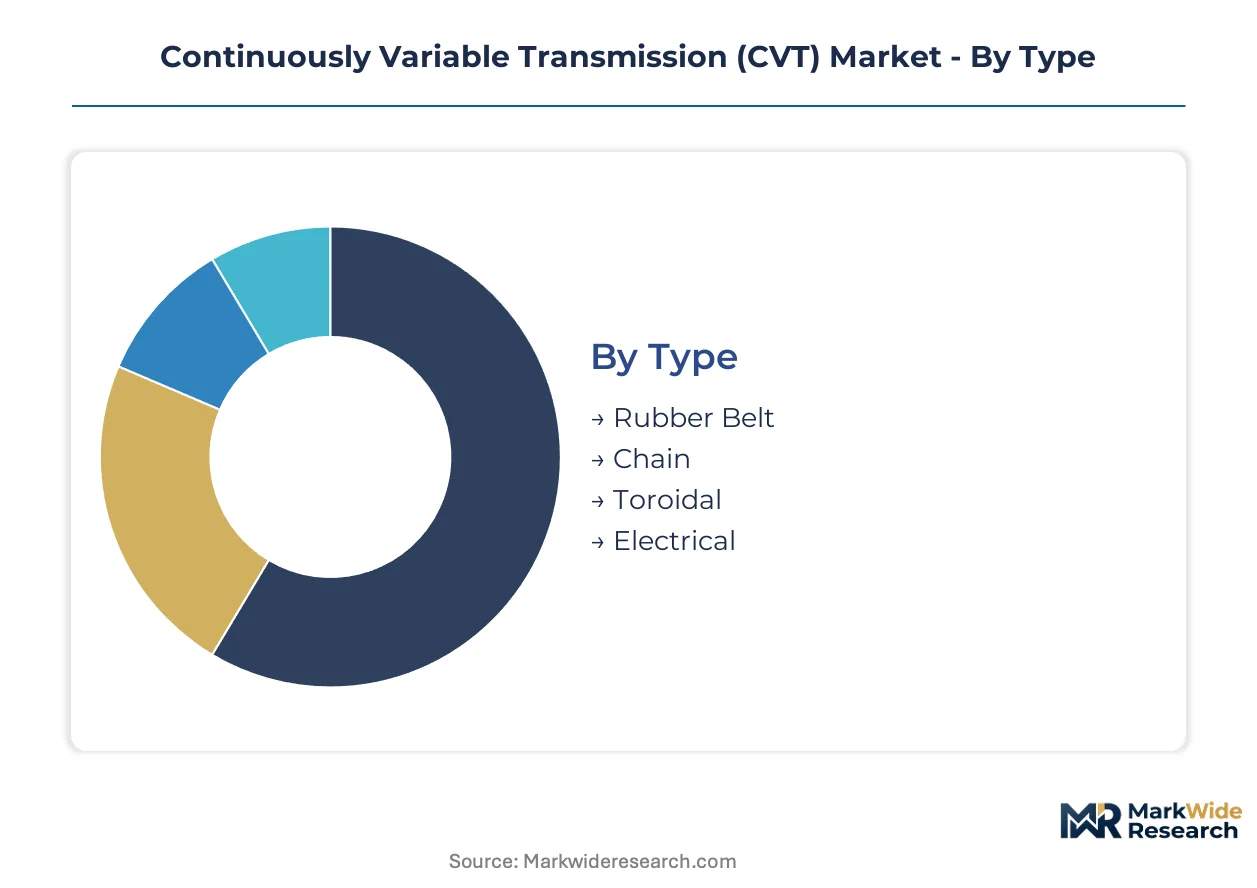
CVT architectures diverge sharply in their integration depth. Some segments function as standalone mechanical systems, while others embed into hybrid powertrains or industrial drivetrains. Understanding this layering reveals where suppliers can defend margin against commoditization.
Type:
Standalone mechanical CVTs dominate front-wheel-drive automotive applications, while hybrid-integrated variants command premium positioning in transitional powertrain portfolios.
- Rubber Belt:Constructed from reinforced elastomer compounds with steel tensile cords, rubber-belt CVTs operate efficiently below 250 Nm torque thresholds. Demand concentrates in Southeast Asian compact car segments where cost sensitivity outweighs durability requirements. China's MIIT efficiency standards are disqualifying first-generation hydraulic designs, accelerating replacement demand.
- Chain:Link-plate chains manufactured from advanced high-strength steel alloys transmit torque loads exceeding 400 Nm without slippage. Japanese and Korean OEMs have standardized chain-CVT architectures across 1.5-2.5 liter engine lines. METI fuel efficiency benchmarks in Japan directly incentivize chain-CVT procurement over stepped-gear alternatives.
- Toroidal:Roller-based traction drives using high-viscosity traction fluid achieve torque density superior to belt or chain alternatives. Niche adoption persists in industrial equipment where premium cost acceptance justifies performance gains.
- Electrical:Motor-generator integrated architectures eliminate mechanical ratio elements entirely. Emerging deployment in range-extender hybrid systems where packaging constraints favor electrical solution.
Chain leads volumes today; electrical is gaining share fastest.
End User:
Volume concentration varies dramatically by customer type, with fleet procurement patterns diverging from retail consumer preferences on total cost metrics.
- Passenger Vehicles:Front-wheel-drive compacts and mid-size sedans represent the dominant installation base. Japanese OEMs maintain CVT standardization across 60% of domestic production volumes. NHTSA corporate average fuel economy mandates sustain procurement in US compact portfolios.
- Commercial Vehicles:Light commercial vans adopt CVT for urban delivery duty cycles where stop-start efficiency dominates operating economics. European last-mile logistics operators specify predictive maintenance packages tied to telematics data.
- Motorcycles:Scooter segments in India and Southeast Asia deploy rubber-belt CVT for automatic transmission convenience. High-volume production amortizes tooling costs across platforms.
- ATVs:Recreational off-highway vehicles utilize CVT for torque multiplication across variable terrain. North American powersports manufacturers source from specialized transmission suppliers.
Passenger vehicles anchor revenue; commercial vehicles show steepest expansion trajectory.
Technology:
Actuation methodology determines control precision, with electronic architectures displacing legacy hydraulic systems across new platform introductions.
- Hydraulic:Pump-and-valve systems using automatic transmission fluid generate clamping force through pressure modulation. Legacy installed base in existing vehicle platforms complicates model-year transitions.
- Mechanical:Centrifugal and spring-loaded mechanisms provide ratio control without external power. Limited to small-displacement applications where cost minimization dominates.
- Electronic:Stepper motor and solenoid actuation enables millisecond-ratio changes with navigation-linked predictive logic. Tier-1 suppliers accelerate control module localization to satisfy China's MIIT GB certification requirements.
- Hybrid:Integrated motor-generator coupling with CVT ratio management optimizes engine operating points in electrified powertrains. Toyota's captive manufacturing scale sustains integrated CVT-hybrid output across multiple vehicle lines.
Electronic leads new platform adoption; hybrid commands premium positioning.
Application:
End-use diversification creates buffer against automotive cyclicality, with industrial and marine segments offering counter-cyclical revenue streams.
- Automotive:Light-duty passenger and commercial vehicles constitute the primary revenue concentration. China's domestic suppliers scale chain-CVT production for local OEM programs.
- Industrial Equipment:Agricultural tractors and construction machinery deploy toroidal CVT for high-torque density requirements. Premium pricing acceptance in this segment exceeds automotive benchmarks.
- Marine:Pleasure craft and small commercial vessels utilize CVT for propeller speed optimization across varying load conditions. Saltwater corrosion resistance dictates specialized material specifications.
- Aerospace:Auxiliary power unit and ground support equipment applications exploit CVT speed matching capabilities. Certification requirements limit supplier qualification to established aerospace transmission specialists.
Automotive dominates absolute volumes; industrial equipment delivers superior margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Aichi-Nagoya industrial corridor anchors CVT manufacturing concentration, with Toyota City and surrounding prefectures hosting integrated powertrain assembly. Japanese OEMs export chain-CVT architectures throughout Southeast Asia. China's Yangtze River Delta and Pearl River Delta regions scale domestic supplier capacity for local vehicle programs.
Japan
Compact car demand from Toyota, Honda, and Nissan sustains chain-CVT standardization across 60% of domestic production. METI fuel efficiency benchmarks directly incentivize ratioless transmission procurement over stepped-gear alternatives. The Aichi-Nagoya corridor integrates captive CVT manufacturing with hybrid powertrain assembly, concentrating engineering talent and precision steel component supply.
China
Domestic OEM programs from Geely, BYD, and Great Wall Motor drive chain-CVT procurement volumes for 1.5-2.0 liter engine lines. MIIT GB standards on transmission efficiency disqualify first-generation hydraulic designs, accelerating electronic control module localization. The Yangtze River Delta region hosts Wanliyang and emerging suppliers scaling manufacturing for export-oriented assembly plants.
United States
NHTSA corporate average fuel economy mandates push domestic automakers toward ratioless architectures in compact car portfolios. Ford and General Motors sustain CVT procurement for front-wheel-drive platforms where operating cost sensitivity dominates consumer preference. The Midwest manufacturing belt integrates transmission assembly with powertrain engineering centers in Michigan and Ohio.
Germany
ZF Friedrichshafen AG supplies push-belt CVT architectures to European OEMs seeking efficiency gains in mid-size passenger segments. The country's national automotive regulator enforces CO2 fleet targets that favor ratioless transmission adoption in urban duty cycles. The Baden-Württemberg region concentrates precision steel component manufacturing and transmission control software development.
South Korea
Hyundai and Kia Motor standardize push-belt CVT across 1.5-2.5 liter engine lines, displacing traditional automatic transmissions in domestic and export markets. The national ministry of trade, industry and energy enforces fuel efficiency standards that accelerate electronic control adoption. The Busan-Ulsan industrial complex integrates CVT assembly with engine manufacturing for ASEAN export programs.
Continuously Variable Transmission (CVT) Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers defend installed base against electrification timelines. The vendor base concentrates around three strategic tiers: Japanese captive manufacturers with integrated hybrid powertrain output, European push-belt specialists serving premium OEM segments, and Chinese domestic suppliers scaling chain-CVT production for local programs. Two competitive moves define positioning: electronic control module localization to satisfy Chinese regulatory requirements, and hybrid powertrain integration to extend CVT relevance in transitional vehicle segments.
Within the captive manufacturing tier, Toyota Motor Corporation and JATCO exemplify vertical integration strategies that couple CVT ratio management with hybrid electric motor control. Among European-based suppliers, ZF Friedrichshafen AG occupies a position representing precision steel push-belt specialization for mid-torque passenger vehicle applications. Bosch anchors the independent supplier segment, with its position reflecting scale advantages in electronic control module development across multiple OEM programs.
| Leading Market Players |
|---|
| Punch Powertrain |
| Honda Motor Co., Ltd. |
| JATCO |
| Nissan Motor Co., Ltd. |
| Toyota Motor Corporation |
| Aisin AW |
| ZF Friedrichshafen AG |
| Wanliyang |
| Bosch |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing integration across Japan's Aichi-Nagoya corridor anchors both supply security and pricing power for integrated CVT-hybrid powertrain producers. Toyota Motor Corporation's in-house production of chain-CVT architectures insulates procurement costs from specialty steel volatility while compressing supplier margins for independent push-belt manufacturers competing on electronic control sophistication.
Pricing Analysis
Specialty steel and precision bearing cost pass-through from energy-intensive smelting operations compresses component margins across the supplier base. Three-tier pricing structure across premium, standard, and economy levels separates hybrid-integrated CVT systems from standalone chain-CVT architectures and rubber-belt alternatives for Southeast Asian compact cars. Price differentiation hinges on electronic control module certification grade and after-sales calibration service bundling. Fleet procurement contracts in urban China intensify pricing pressure through total cost of ownership metrics that unbundle hardware from predictive maintenance packages. Ride-hail operators exhibit highest price sensitivity; industrial equipment buyers accept premium positioning for toroidal torque density advantages.
Supply Chain Analysis
Regional distribution centers in Japan, China, and Germany coordinate hub-and-spoke patterns for precision steel pulley components and electronic control modules. Manufacturing concentration in Japan, China, and South Korea feeds from advanced high-strength steel alloy suppliers and traction fluid formulators. Supply chain risk centers on single-source vulnerability for specialized bearing assemblies used in chain-CVT link plates. Distribution runs through OEM captive assembly plants for integrated powertrain output and Tier-1 supplier networks serving aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MIIT GB efficiency standards impose stricter certification burdens than Southeast Asian regulatory baselines, creating cost-arbitrage opportunities for electronic control module localization in Yangtze River Delta manufacturing clusters.
For Market Incumbents: Hedge against electrification timeline compression by accelerating hybrid powertrain integration investments and securing captive supply of advanced high-strength steel alloys for pulley assemblies. Multi-speed dedicated hybrid transmissions threaten installed base in electrifying segments where CVT efficiency advantages diminish. Backward integration into electronic control software development extends differentiation beyond commodity hardware margins. For New Entrants and Emerging Players: MIIT GB standards in China open a window for electronic control module localization partnerships with domestic OEM programs seeking certification compliance. Target industrial equipment applications in agricultural and construction machinery where toroidal CVT premium pricing acceptance exceeds automotive benchmarks. Pursue white-label manufacturing agreements with emerging Chinese suppliers scaling chain-CVT capacity for export-oriented assembly plants. For Investors and Strategic Acquirers: Roll-up economics work for electronic control specialists because software-enabled service revenue streams decouple from hardware margin compression in high-volume passenger vehicle segments. Long-term viability hinges on five-to-ten year electrification transition windows in major automotive markets. Monitor hybrid powertrain penetration rates as inflection indicator for mechanical CVT platform relevance against dedicated hybrid transmission architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Control Module Localization | MIIT GB certification compliance secures program eligibility in China's domestic OEM procurement. |
| Hybrid Powertrain Integration | Toyota's captive manufacturing scale demonstrates integrated CVT-electric motor coupling viability. |
| Advanced High-Strength Steel Sourcing | Specialty alloy procurement anchors pulley assembly weight reduction and clamping force tolerance. |
| Predictive Maintenance Service Bundling | Telematics-linked calibration agreements capture recurring revenue from fleet operators in urban China. |
| Industrial Equipment Segment Expansion | Toroidal traction drive penetration in agricultural machinery justifies premium pricing beyond automotive benchmarks. |
Study Parameters
Coverage spans Japan, China, the United States, Germany, and South Korea, with primary inputs from each market's regulatory and manufacturing clusters. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, transmission control software developers, and aftermarket distributors combined with secondary validation from vehicle production databases, MIIT GB standard filings, METI efficiency benchmark reports, and NHTSA corporate average fuel economy rulemakings. Bottom-up segment modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Granularity-level modeling deployed vehicle class, propulsion architecture, CVT type, and actuation technology as core segmentation dimensions across the projection horizon. CAGRs derived from segment-level growth rate synthesis applied to base-year market sizing. Industry-specific forecast inputs included OEM powertrain platform standardization timelines and electrification penetration assumptions by regional regulatory cluster.
Revisions become necessary when electrification timelines accelerate beyond modeled assumptions or when specialty steel supply disruptions alter component cost structures. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and hybrid powertrain adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Yaw Damper Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Electric Powertrain Systems Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Turbocharger Actuators Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Gear Oil Market
Powertrain
Engines Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
Automotive Hydrostatic Fan Drive System Market