
 Automotive Fuel Cock Market | 2026-2036
Automotive Fuel Cock Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Cock Market Analysis
Aftermarket providers are rotating toward premium replacement fuel cocks as vehicle age profiles lengthen across emerging economies. Pricol Ltd. dominates Indian two-wheeler supply chains through captive manufacturing scale and backward integration into die-casting operations. Mikuni Corporation leverages its carburetor heritage to anchor vacuum fuel cock demand among Japanese motorcycle OEMs. Yamaha Motor Co., Ltd. sustains in-house production for captive powertrain assemblies, limiting external procurement exposure.
An automotive fuel cock is a precision flow-control valve that regulates fuel delivery between the tank and the engine, typically machined from brass or aluminum with Viton seals rated for aromatic hydrocarbon exposure and operating pressures up to 15 psi. Its primary purpose is to enable safe fuel shutoff during transport, maintenance, or emergency conditions while preventing vapor lock and leakage. Electric fuel cock variants are displacing manual units in fuel-injected platforms, concentrating margin pools at suppliers with sensor-integrated valve architectures. By material, brass sustains cost-sensitive aftermarket volumes while stainless steel penetrates marine and commercial vehicle segments where corrosion resistance commands price premiums. Plastic housings are accelerating in lightweight motorcycle applications where gram-scale mass reduction drives OEM specification.
EPA certification requirements for evaporative emissions under Title 40 CFR Part 1060 are forcing tighter seal tolerances and permeation-resistant material substitutions across US-bound production. NHTSA FMVSS 302 flammability standards shape fuel cock housing compositions, particularly for plastic variants in passenger vehicle applications. India's BIS IS 15547 specifications for two-wheeler fuel system components create compliance barriers for unqualified imports. Stakeholders must monitor divergence between regional emissions test protocols, as harmonization gaps between EPA, Euro 5, and Bharat Stage VI certification pathways multiply validation costs for multi-market suppliers.
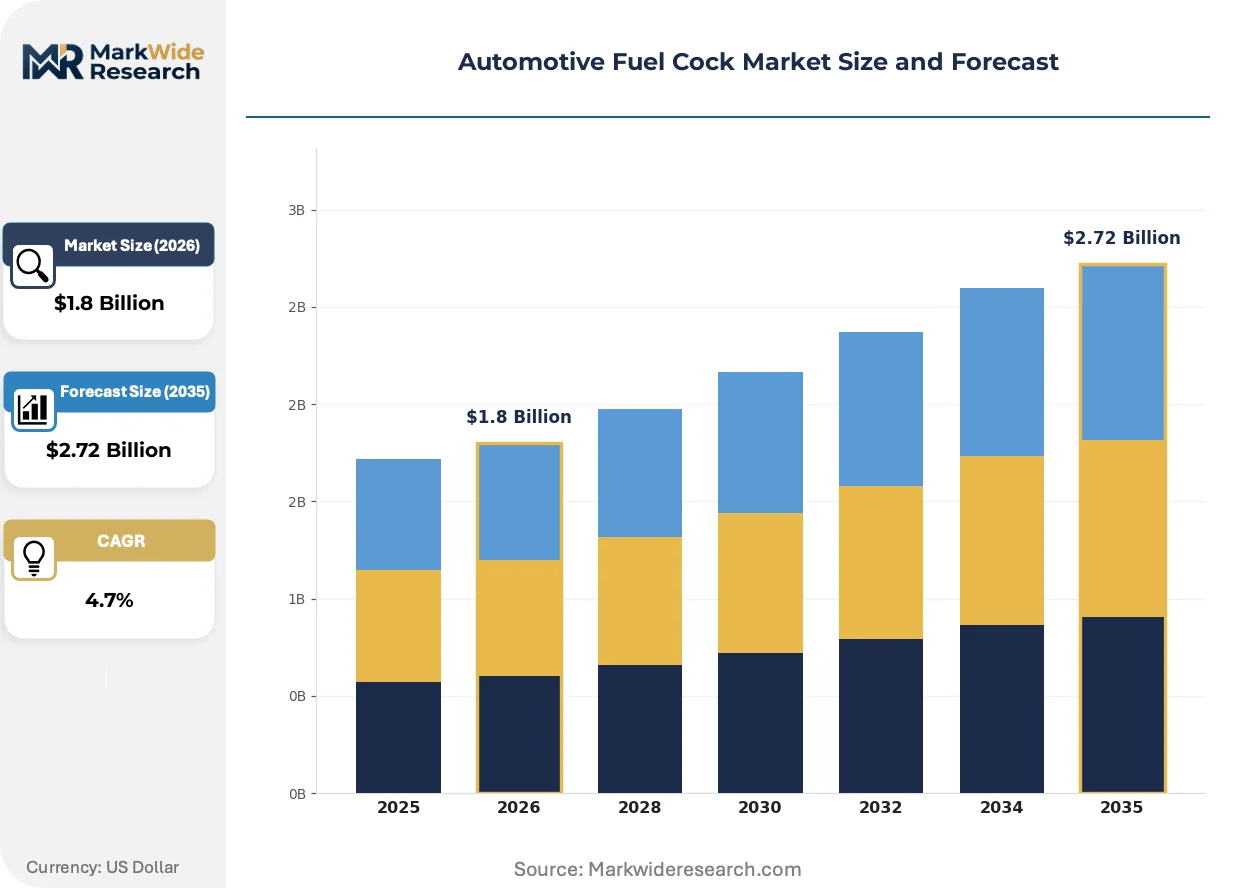
Market Dynamics
Fuel injection penetration across motorcycle OEM platforms is systematically displacing manual vacuum fuel cocks, concentrating procurement power at suppliers capable of integrating solenoid actuators with engine management system signaling protocols.
Growth Catalysts
- EPA Title 40 CFR Part 1060:Evaporative emissions mandates are forcing permeation-resistant material upgrades across US-bound production, expanding specification scope for fluoropolymer seal suppliers.
- Two-wheeler production clustering:India’s component localization incentives under the PLI scheme are accelerating captive sourcing investments by multinational OEMs seeking tariff arbitrage.
- Electric fuel cock architectures:Sensor-integrated valve designs with PWM control interfaces are capturing specification share as fuel-injected motorcycle platforms multiply in Southeast Asian export manufacturing.
Market Restraints
- Brass alloy price volatility:Copper and zinc input cost swings compress margin stability for die-cast housing producers serving cost-sensitive aftermarket channels.
- Indian supply concentration:Tier-2 component clusters around Chennai and Pune create single-geography disruption exposure for global OEM procurement networks.
- Carburetor platform attrition:Vacuum fuel cock demand tied to legacy powertrain architectures faces structural volume compression as Bharat Stage VI and Euro 5 compliance deadlines accelerate fuel injection adoption.
Strategic Opportunities
- Marine outboard applications:Stainless steel fuel cock specifications for saltwater corrosion resistance command price premiums in recreational boating segments underserved by motorcycle-focused suppliers.
- Aftermarket premiumization:Extended vehicle age profiles in Indonesia and Vietnam create service-interval replacement demand for brass-bodied units with enhanced Viton seal durability ratings.
- Plastic housing penetration:PA66 and PPS material substitution in lightweight motorcycle platforms enables gram-scale mass reduction valued by performance-oriented OEM engineering teams.
Industry Challenges
- Multi-protocol certification burden:Divergent EPA, Euro 5, and Bharat Stage VI test procedures multiply validation timelines and tooling amortization costs for multi-market suppliers.
- Legacy system integration:Electric fuel cock retrofit compatibility with existing tank flange geometries and fuel line routing constraints complicates platform upgrade engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Cock Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Fuel Cock, Electric Fuel Cock, Vacuum Fuel Cock, Automatic Fuel Cock End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Material: Aluminium, Stainless Steel, Plastic, Brass Installation Type: On-vehicle, Off-vehicle, Surface Mount, In-line |
| Companies Covered | Pricol Ltd., Fuel Star, Inc., Golan Products, Pacco Industrial Corporation, Advik Hi-tech Pvt. Ltd., J&P Cycles, Mikuni Corporation, Yamaha Motor Co., Ltd., Hitachi Astemo, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Cock Market Emerging Trajectories
Actuator technology and seal material science are converging to redefine fuel cock performance benchmarks, while regulatory test protocol divergence is fragmenting supplier certification strategies across export markets.
Solenoid-actuated electric fuel cocks with integrated position feedback sensors are bifurcating the product landscape into premium sensor-integrated tiers and basic on-off variants. Japanese and Indian motorcycle OEMs specify the former for fuel-injected platforms above 150cc displacement, while Southeast Asian commuter bike producers retain manual vacuum units for cost containment. This technical schism is compressing mid-tier supplier margins as specification polarization accelerates.
REACH Annex XVII restrictions on nickel release rates are compelling European-market suppliers to migrate from nickel-plated brass toward stainless steel or coated aluminum housing compositions. The industrial consequence is elevated tooling investment for stamping and machining operations. Marine and commercial vehicle segments bound for EU ports are most affected, with producers accelerating material qualification programs to maintain market access.
Buyer consolidation among Indian two-wheeler OEMs is compressing supplier negotiation cycles and unbundling aftermarket service contracts from original equipment procurement agreements. Tier-1 component distributors are displacing traditional multi-tier supply networks in spare parts fulfillment. This channel restructuring is most visible in Maharashtra and Tamil Nadu manufacturing corridors, where captive logistics investments by Pricol and comparable domestic suppliers are reshaping competitive access.
Automotive Fuel Cock Market Segmentation
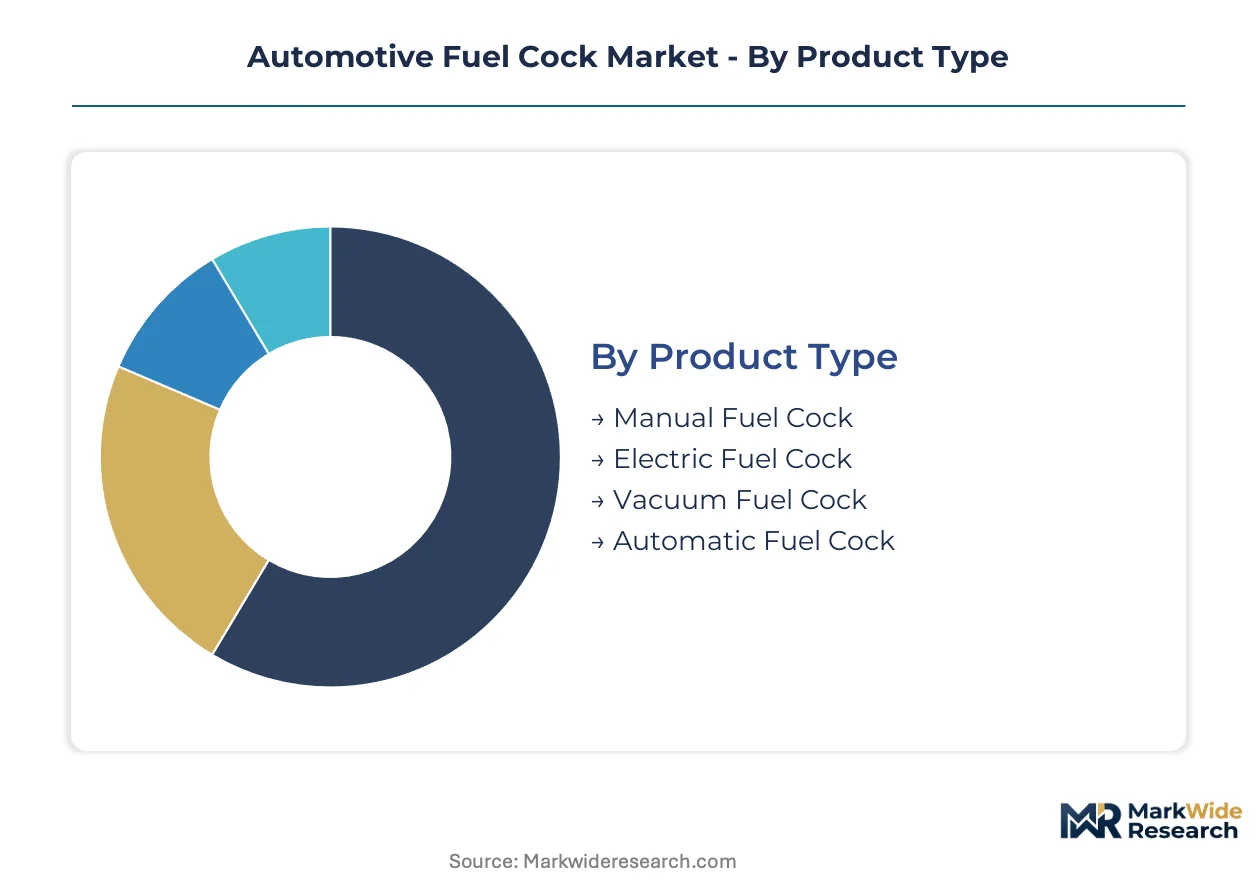
Segmentation in the automotive fuel cock market reveals how specification divergence between fuel-injected and carbureted platforms is fragmenting procurement patterns. Material choices and installation geometries now determine supplier qualification pathways more than historical volume relationships.
Product Type:
Margin pools concentrate at the intersection of sensor integration and engine management system compatibility, where electric variants command specification premiums from fuel-injected motorcycle OEMs.
- Manual Fuel Cock:Simple mechanical shutoff valves machined from brass or aluminum with basic Viton seals. Demand concentrates in Indian and Southeast Asian commuter motorcycle segments where carburetor retention persists for cost containment against Bharat Stage VI compliance deadlines.
- Electric Fuel Cock:Solenoid-actuated units with PWM control interfaces and position feedback sensors. Japanese and Indian OEMs above 150cc displacement specify these for fuel-injected platforms, concentrating procurement power at suppliers with engine management system integration capabilities.
- Vacuum Fuel Cock:Diaphragm-operated valves responding to engine vacuum signals. Legacy carburetor architectures in Indonesian and Vietnamese aftermarket channels sustain residual demand despite structural volume compression from emission compliance acceleration.
- Automatic Fuel Cock:Electronically controlled variants with integrated pressure sensing and fail-safe shutoff logic. Marine outboard and commercial vehicle applications in saltwater environments specify these for corrosion-resistant stainless steel configurations.
Manual fuel cocks hold installed capacity across emerging economy aftermarket channels. Electric fuel cocks are rotating up the share rankings as fuel injection penetration deepens in Southeast Asian export manufacturing.
End User:
Volume concentration sits with captive procurement networks, while margin expansion follows unbundled aftermarket service contracts as vehicle age profiles lengthen.
- OEMs:Motorcycle and powersports manufacturers with captive fuel system engineering teams. Indian two-wheeler OEMs in Maharashtra and Tamil Nadu corridors leverage PLI scheme localization incentives to consolidate supplier relationships around Pricol and comparable domestic producers.
- Aftermarket Providers:Distributors and retailers serving replacement demand from aging vehicle parc. Extended service intervals in Indonesia and Vietnam create demand for brass-bodied units with enhanced seal durability ratings.
- Vehicle Assemblers:Contract manufacturers and kit assembly operations. Cost-sensitive procurement in African and Latin American markets favors manual vacuum units from Chinese supply bases.
- Repair Shops:Independent service facilities performing maintenance and collision repair. Channel restructuring by Tier-1 distributors is displacing traditional multi-tier supply networks in spare parts fulfillment.
OEMs dominate volume absorption for new platform specifications. Aftermarket providers are climbing fastest in margin contribution as unbundled service contracts proliferate.
Material:
Cost tier stratification separates commodity die-cast volumes from corrosion-resistant premium specifications.
- Aluminium:Die-cast and machined housings balancing weight reduction with thermal conductivity. Lightweight motorcycle platforms specify these for gram-scale mass reduction valued by performance-oriented engineering teams.
- Stainless Steel:Marine-grade 316L and comparable alloys for saltwater corrosion resistance. Recreational boating segments command price premiums underserved by motorcycle-focused suppliers.
- Plastic:PA66 and PPS housings in injection-molded configurations. REACH Annex XVII nickel release restrictions are accelerating European-market substitution away from plated brass alternatives.
- Brass:Copper-zinc alloys with nickel plating for cost-sensitive aftermarket volumes. Copper and zinc input cost swings compress margin stability for die-cast housing producers serving price-sensitive replacement channels.
Brass maintains volume leadership in cost-driven aftermarket segments. Plastic is expanding most quickly as emission-driven material substitution accelerates in EU-bound production.
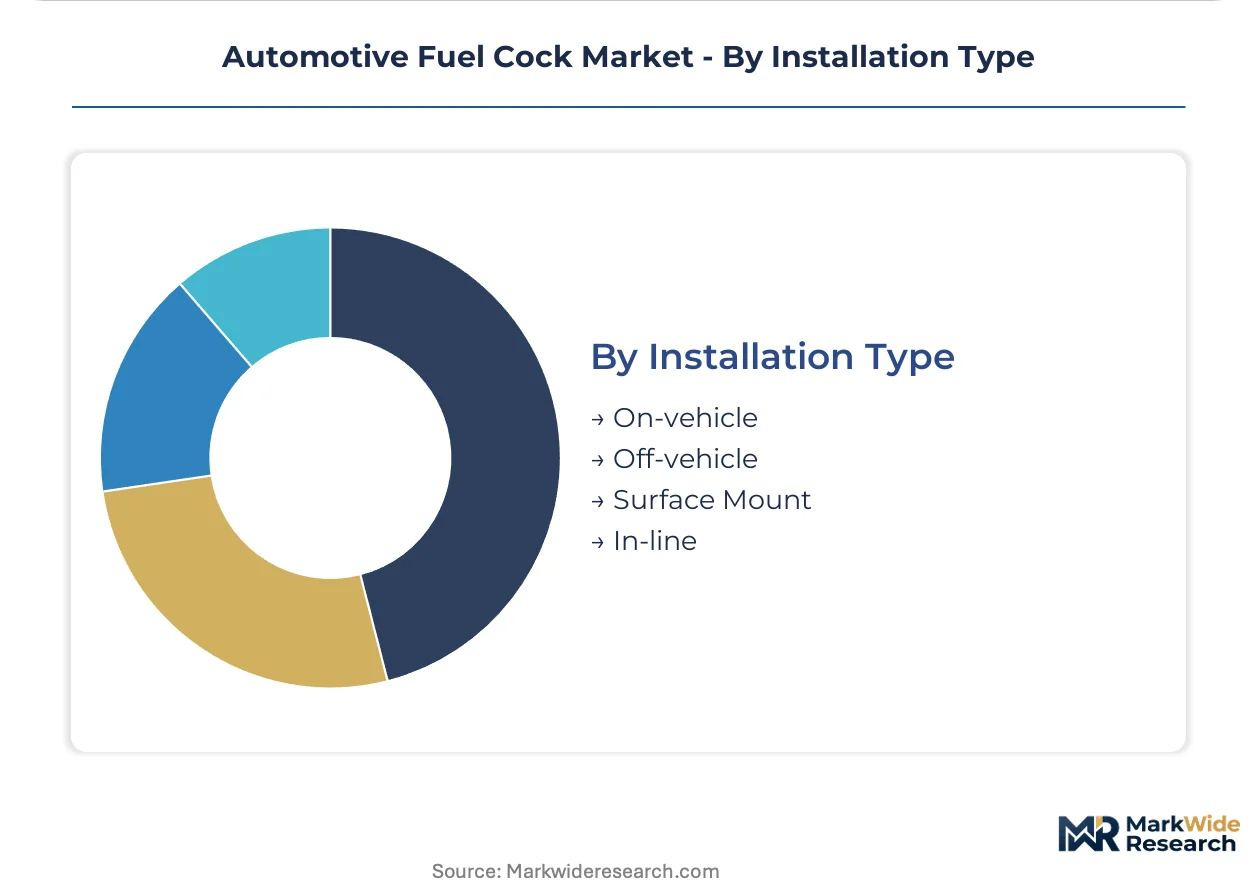
Installation Type:
Geography of final assembly dictates flange geometry standardization, with surface mount configurations dominating high-volume motorcycle production.
- On-vehicle:Tank-integrated fuel cocks with flange-mounted sealing interfaces. OEM motorcycle assembly lines in India and Thailand specify these for production efficiency and leak-test integration.
- Off-vehicle:Portable fuel system components for auxiliary tanks and transfer applications. Commercial vehicle and agricultural equipment segments in North America utilize these for modular fuel system architectures.
- Surface Mount:Externally attached valves with gasket-sealed interfaces. Dominates two-wheeler production where tank geometry standardization enables automated assembly.
- In-line:Hose-barb or quick-connect fittings for flexible routing. Custom motorcycle builders and retrofit applications favor these for fuel line routing adaptability.
Surface mount configurations hold installed capacity in high-volume motorcycle manufacturing. In-line installations are rotating up the share rankings as retrofit and custom build segments expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors Indian two-wheeler component export flows, while the Port of Shanghai channels Chinese die-cast housing volumes into Southeast Asian assembly networks.
United States
EPA Title 40 CFR Part 1060 evaporative emissions mandates tighten seal tolerance requirements for US-bound motorcycle fuel systems. NHTSA FMVSS 302 flammability standards shape plastic housing specifications for passenger vehicle applications. Detroit-area Tier-1 distributors are consolidating aftermarket procurement networks around automated inventory management systems.
India
Two-wheeler production volumes exceeding eight million units annually concentrate fuel cock demand in Maharashtra and Tamil Nadu manufacturing corridors. BIS IS 15547 specifications for fuel system components create compliance barriers for unqualified imports. The PLI scheme localization incentives are accelerating captive sourcing investments by multinational OEMs in Pune and Chennai industrial clusters.
Japan
Japanese motorcycle OEMs above 150cc displacement specify sensor-integrated electric fuel cocks for fuel-injected platforms. METI industrial standards govern precision valve performance benchmarks for domestic powertrain engineering teams. Nagoya-area suppliers leverage carburetor heritage relationships to anchor vacuum fuel cock specifications among legacy platform producers.
Germany
REACH Annex XVII nickel release restrictions compel European-market suppliers to migrate from nickel-plated brass toward stainless steel or coated aluminum housing compositions. KBA type-approval procedures validate fuel system component durability for EU-bound commercial vehicle applications. Stuttgart engineering consultancies are qualifying alternative material compositions to maintain marine outboard market access.
Vietnam
Extended vehicle age profiles in Indonesian and Vietnamese aftermarket channels create replacement demand for brass-bodied units with enhanced seal durability ratings. ASEAN harmonized technical regulations fragment certification pathways for multi-market suppliers. Ho Chi Minh City logistics hubs are restructuring spare parts distribution networks around Tier-1 component distributors.
Automotive Fuel Cock Market Vendor Landscape
Listed leaders compete with private specialists across capital access and engineering agility dimensions. The vendor base segments into three tiers: multinational OEMs with captive production, domestic scale specialists with backward integration into die-casting, and regional fabricators serving cost-sensitive aftermarket channels. Strategic archetypes include sensor-integrated system integrators, brass die-casting scale operators, and marine corrosion-resistant specialists. Dominant competitive moves center on geographic expansion into Indian PLI corridors and portfolio diversification toward electric actuator architectures.
Within the domestic Indian tier, Pricol Ltd. and Advik Hi-tech Pvt. Ltd. occupy positions exemplifying scale-driven supply chain consolidation. Among Japanese precision engineering specialists, Mikuni Corporation anchors carburetor-heritage supplier relationships. Yamaha Motor Co., Ltd. represents captive in-house production strategies that limit external procurement exposure for powertrain assemblies.
| Leading Market Players |
|---|
| Pricol Ltd. |
| Fuel Star, Inc. |
| Golan Products |
| Pacco Industrial Corporation |
| Advik Hi-tech Pvt. Ltd. |
| J&P Cycles |
| Mikuni Corporation |
| Yamaha Motor Co., Ltd. |
| Hitachi Astemo, Ltd. |
| Others |
Supply Flow & Price Mechanics
Fluoropolymer seal substitution for conventional Viton compounds simultaneously shifts specification authority toward Japanese and German chemical suppliers while compressing margin pools for die-cast housing producers locked into brass-centric cost structures. This material migration redraws procurement geography as REACH-compliant European producers capture premium-tier pricing power from legacy Asian suppliers.
Pricing Analysis
Volume-discount tiering structures separate sensor-integrated electric fuel cocks from basic manual variants, with Japanese OEM procurement above 150cc displacement commanding 40-60% unit premiums over Southeast Asian commuter bike specifications. Certification grade under EPA Title 40 CFR Part 1060 and BIS IS 15547 creates price stratification, as dual-certified suppliers capture margin from single-market competitors. Cost compression in brass aftermarket channels is intensifying because copper-zinc alloy volatility transfers input risk to die-casters without forward-contract hedging. Vehicle assemblers in African and Latin American markets exhibit highest price sensitivity, while marine outboard OEMs demonstrate lowest sensitivity due to corrosion-resistance specifications.
Supply Chain Analysis
India and China anchor fuel cock manufacturing, with Maharashtra and Tamil Nadu die-casting clusters feeding Indian two-wheeler OEMs while Shanghai-area stamping operations serve Southeast Asian export assembly. Raw material draws from Chilean copper mines, Indonesian nickel smelters, and German fluoropolymer compounders. Single-geography concentration around Chennai and Pune creates disruption exposure from monsoon logistics or regional regulatory shifts. Distribution runs through Tier-1 component distributors displacing traditional multi-tier networks in Indonesia and Vietnam aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Unbundled aftermarket service contracts represent a faster-expanding recurring-revenue layer than hardware sales, as extended vehicle age profiles in emerging economies lengthen replacement intervals and attach diagnostic and logistics services to physical component delivery.
For Market Incumbents: Fortify backward integration into die-casting operations to buffer brass alloy price volatility, while accelerating sensor-integrated electric fuel cock certification for fuel-injected platform procurement. Captive manufacturing scale in Indian PLI corridors limits exposure to emerging Chinese entrants in Southeast Asian manual vacuum segments. For New Entrants and Emerging Players: Differentiate on marine-grade stainless steel specifications for saltwater corrosion resistance, a segment underserved by motorcycle-focused incumbents. White-space targets include recreational boating OEMs in EU and North American markets requiring REACH Annex XVII compliance. Go-to-market leverage rests on qualifying 316L alloy compositions through KBA and EPA dual-certification pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian component specialists possessing PLI scheme accreditation and captive logistics networks. Long-term viability hinges on electric actuator architecture transition completion and fuel injection penetration saturation across Southeast Asian export manufacturing. The signal to watch is Bharat Stage VI enforcement acceleration compressing vacuum fuel cock residual demand timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Electric Fuel Cock Development | Captures specification share from Japanese and Indian OEMs above 150cc displacement fuel-injected platforms. |
| Backward Integration into Die-Casting Operations | Pricol and comparable domestic suppliers secure margin stability against copper-zinc input cost volatility. |
| Dual-Certification for EPA and BIS Compliance | Unlocks procurement access to US-bound motorcycle production and Indian PLI scheme incentives simultaneously. |
| Marine-Grade Stainless Steel Qualification | Commands price premiums in recreational boating segments requiring REACH Annex XVII nickel release compliance. |
| Tier-1 Distributor Channel Restructuring | Displaces multi-tier supply networks in Indonesian and Vietnamese aftermarket spare parts fulfillment. |
Methodological Framework
A standing panel of Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and BIS certification specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA Title 40 CFR Part 1060 filings, BIS IS 15547 specification documents, vehicle production databases, and customs trade records for copper-zinc alloy imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including IHS Markit motorcycle registration data and ASEAN automotive production indices. The analytical framework modeled product type, material composition, end-user category, and installation geometry dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectory blending and cross-referenced with fuel injection penetration curves and emission compliance deadline impacts.
The analysis sits within stated boundaries; outcomes outside EPA, Euro 5, and Bharat Stage VI harmonization trajectories would require recalibration. Forecasts reflect assumptions on fuel injection substitution rates, brass alloy price stability, and PLI scheme continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Torque Converter Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Automotive Driveline Market
Powertrain
Automatic Transmission Market
Powertrain
North America Torque Vectoring Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Global Driveline Market
Powertrain
Global Automotive Engine and Engine Mounts Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Power Steering Filter Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Global Powertrain Market
Powertrain
Diesel Particulate Filter (DPF) Market