
 Russia Electro Hydraulic Power Steering Market | 2026-2036
Russia Electro Hydraulic Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Electro Hydraulic Power Steering Market Analytics
Software-defined calibration services for steering feel and torque mapping is pivoting how EHPS suppliers monetize their installed base. Robert Bosch GmbH leverages its embedded control firmware to sustain recurring revenue from automakers seeking over-the-air steering parameter updates. ZF Friedrichshafen AG anchors its competitive stance through captive hydraulic pump production, while JTEKT Corporation specializes in compact column-assist architectures for Russia's light-vehicle segment.
Electro hydraulic power steering combines an electric motor-driven hydraulic pump with electronic control modules to deliver variable assist force based on vehicle speed and driver input, typically operating at fluid pressures between 80 and 120 bar. The system reduces parasitic engine load versus conventional hydraulic steering, cutting fuel consumption by disabling pump flow during straight-line cruising. Rack assist configurations command the dominant share of value given their integration complexity and suitability for mid-size passenger cars, while integrated systems represent the fastest-growing product type as OEMs pursue module consolidation. Active steering technology captures premium positioning through its lane-keeping and automated parking compatibility, whereas hydraulic boosting remains the volume foundation across Russia's price-sensitive vehicle tiers.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) enforces GOST-R certification and UNECE harmonized standards that dictate EHPS electromagnetic compatibility and functional safety thresholds for market entry. The Ministry of Industry and Trade coordinates import-substitution policies that steer procurement toward locally manufactured steering components, reshaping supplier qualification criteria. Stakeholders must monitor how evolving vehicle-type approval protocols and localization thresholds alter the cost structure of imported versus domestically assembled EHPS units.
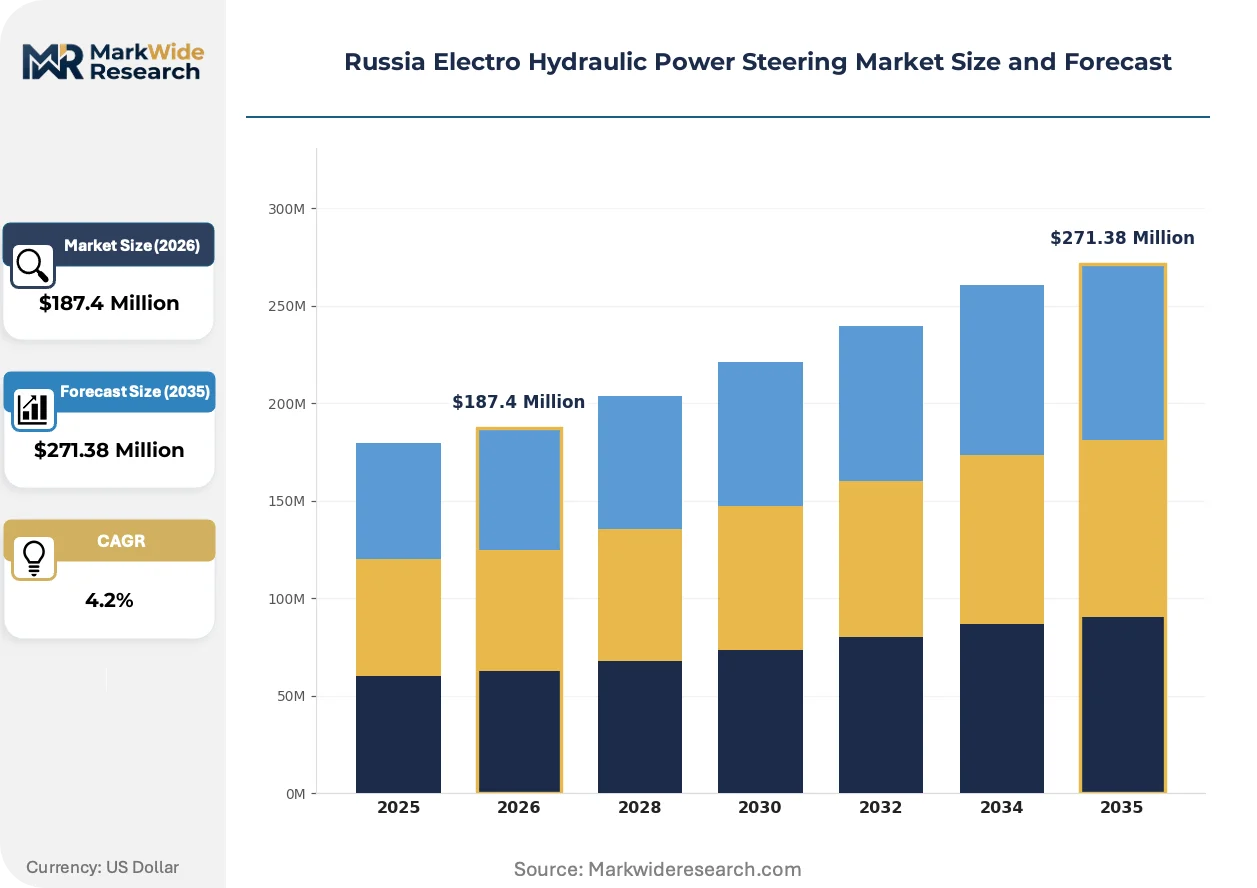
Market Dynamics
Software-defined calibration is compressing hardware differentiation margins across Russia's EHPS supply base, forcing suppliers to monetize firmware updates and steering parameter libraries as recurring revenue streams rather than one-time component sales.
Growth Catalysts
- Rosstandart fuel-efficiency mandates:Tightening GOST-R certification thresholds for parasitic engine load reduction compel domestic OEMs to replace conventional hydraulic steering with variable-displacement EHPS architectures.
- Moscow-Saint Petersburg assembly corridor:Deepening supplier-OEM co-location within these automotive clusters cuts logistics costs and accelerates just-in-sequence steering system delivery.
- Active steering compatibility:Lane-keeping and automated parking functionality requirements from premium vehicle buyers pull EHPS demand toward electronically modulated rack-assist configurations.
Market Restraints
- Import-substitution procurement rules:Ministry of Industry and Trade localization thresholds disqualify fully-imported hydraulic pump and control module assemblies from state-backed fleet tenders.
- Specialized mechatronics talent scarcity:Shortage of firmware engineers capable of torque mapping and electromagnetic compatibility validation extends supplier qualification timelines.
- Electro-mechanical steering substitution:Full-electric EPS architectures gain share in A-segment vehicles where hydraulic infrastructure weight penalties outweigh cost advantages.
Strategic Opportunities
- Over-the-air update services:Embedded control firmware enables suppliers to sell subscription-based steering feel recalibration to fleet operators managing driver preference diversity.
- Volga Federal District production expansion:Underpenetrated assembly capacity in Tatarstan and Samara regions offers greenfield EHPS integration sites beyond saturated Moscow-Saint Petersburg corridor.
- UNECE harmonized standard alignment:Functional safety protocol convergence with European vehicle-type approval frameworks opens export pathways for Russia-certified EHPS modules.
Industry Challenges
- GOST-R electromagnetic compatibility certification:Extended testing protocols for electronic control modules delay product launch schedules and inflate validation budgets.
- Legacy hydraulic system integration:Retrofitting EHPS architectures into existing vehicle platforms without full electrical harness redesign creates engineering complexity and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Electro Hydraulic Power Steering Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Integrated System, Conventional System End User: OEMs, Aftermarket Providers, Commercial Vehicles, Passenger Cars Distribution Channel: Direct Sales, Distributors, Online Retail, Hybrid Distribution Technology: Active Steering, Passive Steering, Electronic Control, Hydraulic Boosting |
| Companies Covered | Robert Bosch GmbH, JTEKT Corporation, ZF Friedrichshafen AG, NSK Ltd, Nexteer Automotive Corporation, Hyundai Mobis Co Ltd, Denso Corporation, GKN PLC, Mitsubishi Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Electro Hydraulic Power Steering Market Evolving Landscape
Digitalization of steering system architecture is dissolving the boundary between mechanical component supply and software service delivery, with firmware-defined functionality now determining competitive positioning more than hydraulic hardware specifications.
Brushless DC motor-driven hydraulic pumps are integrating variable-speed control algorithms that modulate fluid pressure between 80 and 120 bar based on real-time vehicle speed and steering angle inputs. Mid-size passenger car assemblers in the Moscow region are adopting these architectures fastest, drawn by measurable fuel consumption reductions during straight-line cruising. This integration is compressing the addressable market for fixed-displacement pump suppliers unable to deliver electronic control module compatibility.
Rosstandart enforcement of UNECE harmonized functional safety standards is mandating fail-operational steering system behavior for vehicles above 3.5 tonnes gross vehicle weight. Commercial vehicle manufacturers must now source EHPS units with redundant sensor arrays and dual-channel electronic control architectures. Heavy-duty truck assemblers operating in the Ural Federal District are responding by consolidating supplier qualification lists around vendors with proven electromagnetic immunity test records.
Fleet operators are unbundling steering system maintenance from traditional dealership service contracts, instead negotiating direct aftermarket support agreements with component manufacturers. This channel shift disintermediates tier-one system integrators and exposes hydraulic pump suppliers to end-user price pressure. Agricultural and construction vehicle fleets in Siberian Federal District oilfield operations are driving this behavior most aggressively, motivated by remote location service access constraints.
Russia Electro Hydraulic Power Steering Market Segmentation
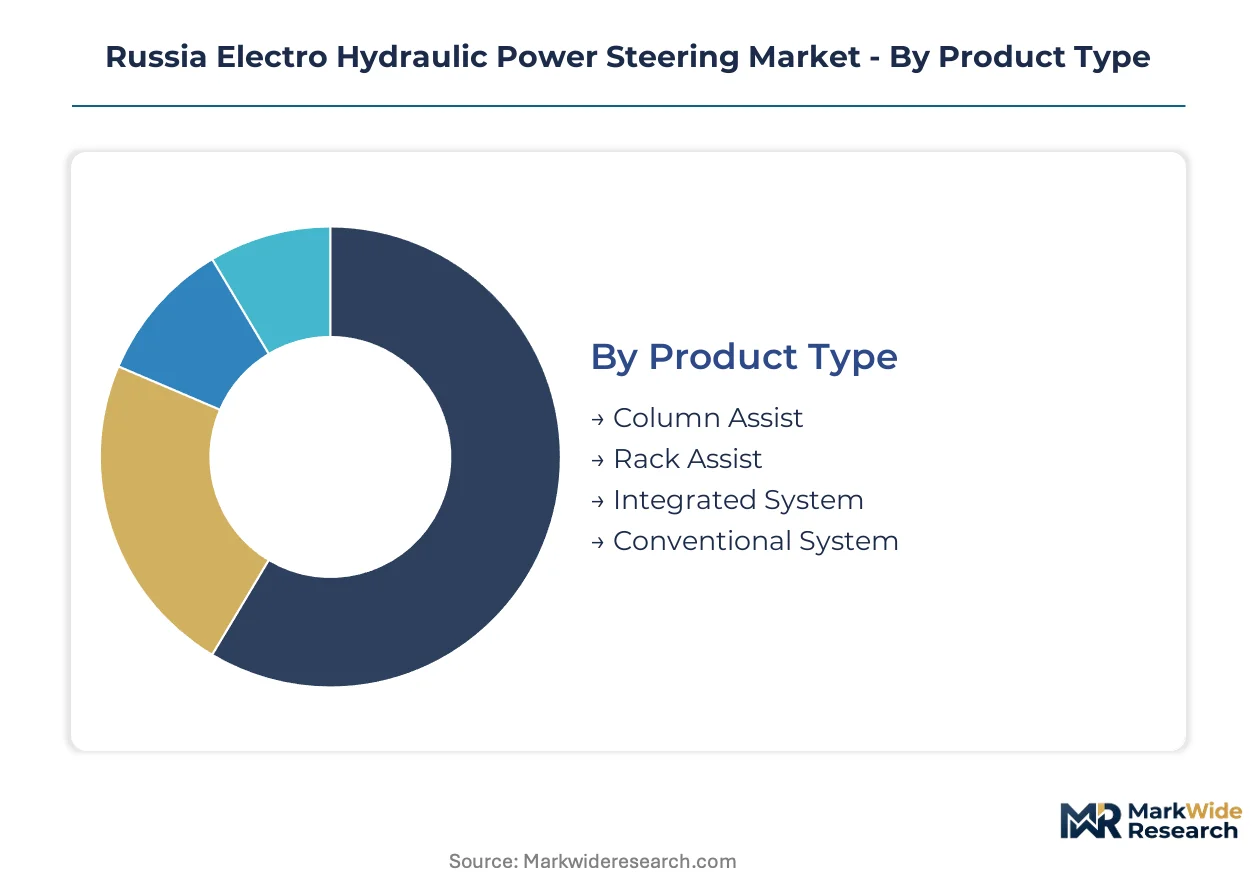
Segmentation reveals how Russia's EHPS market fragments across hardware architectures, customer procurement patterns, and technology maturity levels. Understanding these divides exposes where localization pressures, software monetization potential, and regulatory compliance burdens concentrate differentially.
Product Type:
Rack assist configurations integrate variable-displacement hydraulic pumps with electronic control modules mounted directly to the steering rack, enabling precise torque modulation across vehicle speed ranges. Moscow-region assemblers of mid-size passenger cars source these units most intensively, drawn by measurable fuel efficiency gains during highway cruising that satisfy tightening Rosstandart certification thresholds. Column assist architectures position the electric motor and pump assembly atop the steering column, delivering compact packaging suited to light-vehicle segments where engine bay space constraints dominate design trade-offs. Saint Petersburg-based OEMs favor this format for A-segment and B-segment vehicles, balancing cost against the parasitic load reduction mandates now embedded in GOST-R technical regulations.
- Column Assist:Compact motor-pump integration atop the steering column serves space-constrained light-vehicle platforms. Saint Petersburg passenger car assemblers specify this format for entry-tier models where cost minimization overrides absolute efficiency optimization.
- Rack Assist:Variable-displacement pump and control module integration at the steering rack delivers superior torque precision. Moscow-region mid-size vehicle manufacturers specify this architecture to meet Rosstandart fuel efficiency certification requirements.
- Integrated System:Module consolidation combining pump, reservoir, and controller into single housing. Emerging procurement preference among OEMs pursuing assembly line simplification and reduced part count logistics.
- Conventional System:Fixed-displacement hydraulic pump without electronic speed control. Retained primarily in heavy commercial vehicle segments where proven durability outweighs efficiency gains.
Mature deployment sits with rack assist configurations. Newer deployment is concentrated in integrated systems.
End User:
Procurement patterns diverge sharply between state-coordinated vehicle programs and private fleet operators, reshaping supplier qualification pathways.
- OEMs:Original equipment manufacturers dominate volume procurement through just-in-sequence supply contracts tied to Moscow-Saint Petersburg assembly corridors. Ministry of Industry and Trade localization thresholds now disqualify fully-imported assemblies from state-backed fleet tenders.
- Aftermarket Providers:Independent service networks and component distributors serve aging vehicle parc outside warranty coverage. Siberian Federal District agricultural and construction fleets negotiate direct manufacturer support agreements, bypassing traditional tier-one integrators.
- Commercial Vehicles:Heavy-duty truck and bus assemblers operating in the Ural Federal District source fail-operational EHPS units with redundant sensor arrays. Rosstandart enforcement of UNECE functional safety standards for vehicles above 3.5 tonnes gross vehicle weight drives specification intensity.
- Passenger Cars:Light-vehicle manufacturers balance steering feel calibration against cost constraints across premium and volume tiers. Active steering compatibility requirements from premium buyers pull demand toward electronically modulated rack-assist configurations.
Volume concentration rests with OEM direct procurement. Margin expansion is concentrated in aftermarket direct-to-fleet arrangements.
Distribution Channel:
Channel structure reflects the tension between just-in-sequence manufacturing integration and remote territory service access requirements.
- Direct Sales:Supplier-OEM contractual relationships governing sequenced delivery to assembly plants. Moscow and Saint Petersburg automotive clusters anchor this channel, with deepening co-location reducing logistics friction.
- Distributors:Regional warehousing networks serving independent repair facilities and smaller fleet operators. Volga Federal District expansion into Tatarstan and Samara regions relies on distributor infrastructure for aftermarket penetration.
- Online Retail:Digital procurement platforms for replacement components and diagnostic equipment. Limited penetration in EHPS given calibration complexity and warranty validation requirements.
- Hybrid Distribution:Blended models combining direct OEM supply with authorized service network support. Agricultural and construction vehicle fleets in remote Siberian oilfield operations drive adoption of this channel structure.
Established infrastructure sits with direct sales to OEMs. Channel experimentation is concentrated in hybrid distribution models.
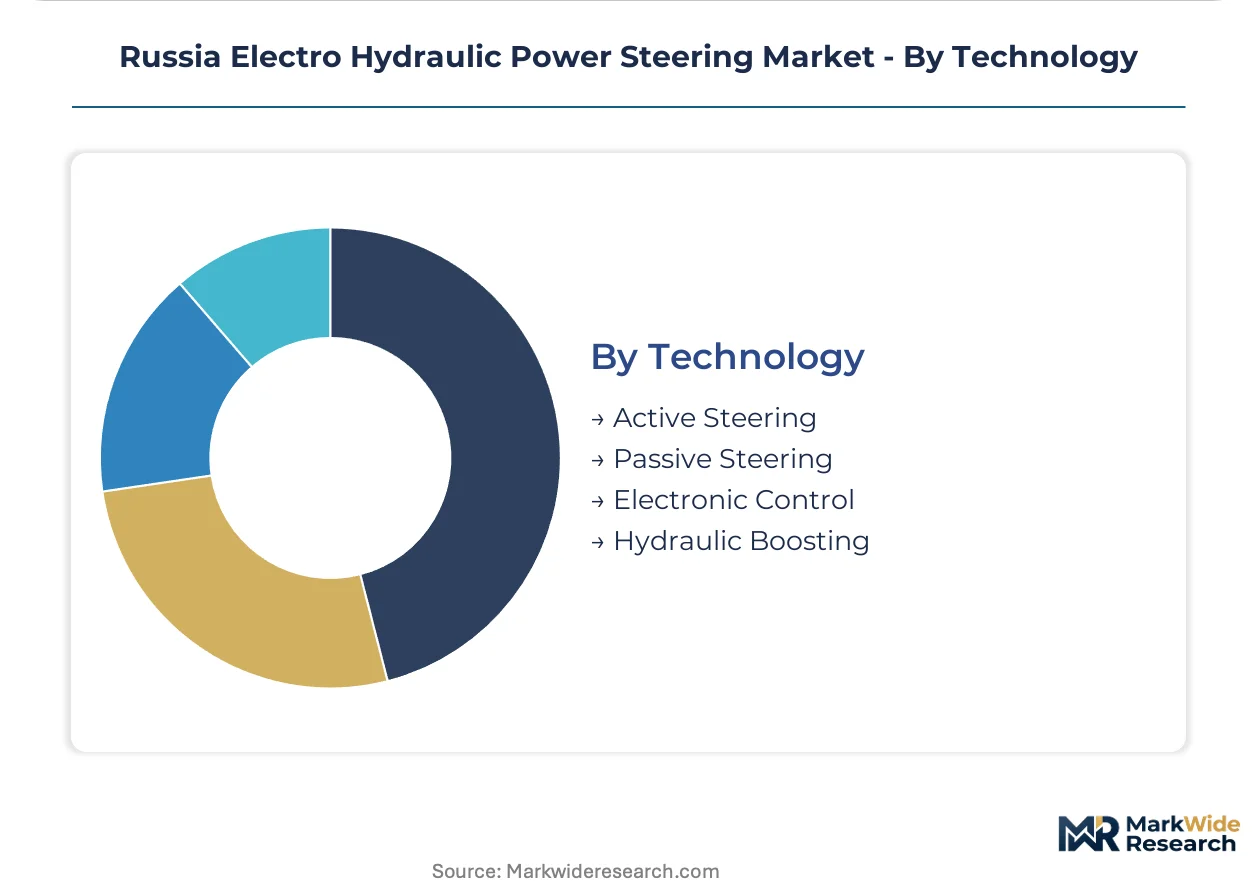
Technology:
Technology segmentation captures the transition from hydraulic hardware dominance toward firmware-defined functionality and automated driving compatibility.
- Active Steering:Electronically modulated gear ratios enabling lane-keeping assistance and automated parking maneuvers. Premium vehicle assemblers specify this technology to differentiate against import competition.
- Passive Steering:Conventional hydraulic assist without electronic intervention or variable ratio capability. Retained in price-sensitive vehicle tiers where regulatory compliance rather than feature differentiation drives specification.
- Electronic Control:Embedded firmware governing pump speed, pressure modulation, and torque mapping. Software-defined calibration services now generate recurring revenue streams for suppliers with embedded control expertise.
- Hydraulic Boosting:Fundamental hydraulic pressure multiplication without electronic speed control. Volume foundation across Russia's commercial vehicle segments where proven field durability outweighs efficiency optimization.
Installed base concentration sits with hydraulic boosting. Capability investment is concentrated in electronic control firmware development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's EHPS production concentrates in the western federal districts while consumption spreads across dispersed industrial zones, creating logistical complexity for steering system suppliers balancing just-in-sequence delivery against remote territory service requirements.
Central Federal District
Moscow-region automotive clusters anchor domestic EHPS demand through AvtoVAZ and GAZ assembly operations. Rosstandart enforces GOST-R certification thresholds that compel variable-displacement pump adoption. Kaluga and Tula oblasts host expanding supplier parks where tier-one integrators co-locate steering component warehousing.
Northwestern Federal District
Saint Petersburg light-vehicle manufacturers specify column-assist architectures for A-segment and B-segment platforms. Ministry of Industry and Trade localization rules disqualify fully-imported assemblies from state procurement. Pskov and Novgorod regions develop distributor infrastructure serving aftermarket channels.
Volga Federal District
Tatarstan and Samara regions offer underpenetrated greenfield capacity beyond saturated western corridors. Regional governments negotiate investment incentives for steering system component manufacturing. Naberezhnye Chelny truck assembly operations source fail-operational EHPS units for commercial vehicle platforms.
Ural Federal District
Heavy-duty truck manufacturers in Chelyabinsk and Sverdlovsk oblasts consolidate supplier lists around vendors with proven electromagnetic immunity records. UNECE functional safety standards for vehicles above 3.5 tonnes gross vehicle weight reshape procurement criteria. Yekaterinburg anchors aftermarket distribution for Siberian-bound commercial fleets.
Siberian Federal District
Agricultural and construction vehicle fleets in Krasnoyarsk and Irkutsk oblasts negotiate direct manufacturer support agreements bypassing tier-one integrators. Remote location service access constraints accelerate hybrid distribution model adoption. Omsk and Novosibirsk develop authorized service networks for hydraulic pump calibration.
Russia Electro Hydraulic Power Steering Market Competitive Landscape
Top-tier vendors anchor firmware-defined steering calibration services, while mid-tier suppliers compete on captive hydraulic pump production and regional assembly proximity. The market exhibits tiered concentration around embedded control expertise and electromagnetic compatibility certification capabilities. Strategic archetypes include software-centric system integrators, hydraulic hardware specialists, and regionally-integrated component fabricators. Dominant competitive moves encompass backward integration into pump manufacturing and strategic partnerships for GOST-R certification acceleration.
Within the embedded control tier, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify vendors leveraging firmware monetization through over-the-air update services. JTEKT Corporation occupies a position among compact column-assist specialists serving space-constrained light-vehicle platforms. These three entities represent distinct competitive archetypes: the German GmbH-structured conglomerates anchor software-defined revenue streams, while the Japanese corporation exemplifies hardware-optimized architectures for entry-tier segments.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| NSK Ltd |
| Nexteer Automotive Corporation |
| Hyundai Mobis Co Ltd |
| Denso Corporation |
| GKN PLC |
| Mitsubishi Electric Corporation |
| Others |
Value Network & Pricing Analysis
Brushless DC motor-driven hydraulic pump adoption simultaneously compresses fixed-displacement supplier margins and concentrates procurement leverage among firmware-capable tier-one integrators across Moscow and Saint Petersburg automotive clusters. Rosstandart fuel-efficiency mandates force OEMs to absorb upfront electronic control module costs while extracting lifecycle value through over-the-air calibration services, reshaping how steering system economics distribute between hardware and software layers.
Pricing Analysis
Cost compression in rack-assist configurations reflects embedded control firmware premiums that suppliers now monetize separately from hydraulic hardware. Three-tier pricing structure across active steering, electronic control, and hydraulic boosting segments separates premium lane-keeping compatibility from standard variable-displacement architectures and economy fixed-pump systems. Ministry of Industry and Trade localization thresholds intensify pricing pressure on fully-imported assemblies, disqualifying them from state fleet tenders. Commercial vehicle manufacturers in the Ural Federal District exhibit lowest price sensitivity given fail-operational safety mandates, while A-segment passenger car assemblers in Saint Petersburg drive hardest cost-down negotiations.
Supply Chain Analysis
Workforce availability constraints in Tatarstan and Samara regions limit greenfield pump manufacturing expansion beyond established Moscow-Saint Petersburg corridors. Russia's EHPS supply chain draws from Germany, Japan, and China for precision-machined valve bodies, rare-earth permanent magnets, and automotive-grade microcontrollers respectively. Single-source vulnerability concentrates in brushless DC motor controller chipsets subject to export control alignment risks. Distribution runs through just-in-sequence direct delivery to OEM assembly plants, with hybrid models emerging for Siberian aftermarket fleet support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around firmware-defined service revenue, squeezing pure-play hydraulic hardware vendors unable to bridge embedded control competency gaps. Rosstandart certification acceleration timelines favor incumbents with established electromagnetic compatibility test records.
For Market Incumbents: Anticipate electro-mechanical steering substitution in A-segment vehicles by accelerating backward integration into brushless DC motor controller production. Secure captive supply of rare-earth magnet alloys through offtake agreements with processors in China or domestic recycling ventures. Lock in GOST-R certification pipeline advantages to extend lead times for challenger qualification. For New Entrants and Emerging Players: Enter via underpenetrated Volga Federal District assembly capacity where tier-one integrators seek secondary pump sourcing to diversify geographic risk. Target commercial vehicle fail-operational segments where incumbent supplier lists remain narrow and electromagnetic immunity test records transfer across UNECE-aligned regulatory frameworks. Lead with direct fleet aftermarket support agreements that disintermediate traditional tier-one channel control in remote Siberian territories. For Investors and Strategic Acquirers: Exit pathways concentrate in firmware-capable tier-one acquisitions by multinational steering conglomerates seeking GOST-R certification shortcuts and Moscow-region co-location assets. Five-to-ten year viability hinges on successful pivot from hardware transactional revenue to recurring calibration service income. Monitor Rosstandart enforcement intensity for UNECE functional safety standards as the inflection signal determining whether heavy commercial vehicle demand sustains premium EHPS architectures or collapses toward electro-mechanical substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Controller Production | Captures margin erosion from semiconductor supply constraints affecting ZF Friedrichshafen AG and Robert Bosch GmbH. |
| GOST-R Certification Acceleration Program | Compresses competitor entry timelines for electromagnetic compatibility validation at Rosstandart testing facilities. |
| Direct Fleet Aftermarket Support Agreements | Disintermediates tier-one integrators serving remote Siberian oilfield and agricultural vehicle operators. |
| Volga Federal District Manufacturing Footprint | Exploits underpenetrated Tatarstan and Samara capacity beyond saturated western automotive corridors. |
| Software-Defined Calibration Service Launch | Transforms one-time hardware sales into recurring revenue from over-the-air steering parameter updates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with EHPS supplier procurement directors, OEM platform engineers, Rosstandart certification specialists, and aftermarket fleet maintenance managers. Bottom-up vehicle production forecasts from IHS Markit registration databases combined with top-down steering system content-per-vehicle estimates derived from tier-one supplier SEC disclosures. Triangulation across these streams validated market sizing and growth trajectory assumptions.
Reconciliation of production volume data, component bill-of-materials cost structures, and regional pricing surveys generated consistent value estimates across the projection horizon. Segmentation modeling incorporated vehicle class, propulsion architecture, steering assist type, and regional production cluster dimensions. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory mandate implementation schedules and technology substitution elasticities. Forecast inputs included Rosstandart certification timeline projections and Ministry of Industry and Trade localization threshold evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation affecting microcontroller supply or sudden electro-mechanical steering cost parity achievement in commercial vehicle segments. Assumptions reflect current regulatory enforcement intensity and technology cost curves. Material deviation in GOST-R electromagnetic compatibility protocol timelines or UNECE functional safety harmonization pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Japan Electrically Powered Hydraulic Steering Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Global Industrial Engine Market
Powertrain
Car Oil Filter Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Crate Engines Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Positive Crankcase Ventilation Valve Market