
 Global Driveline Market | 2026-2036
Global Driveline Market Size, Share, and Industry Trends Forecast 2026-2036
Global Driveline Market Analysis
Aftermarket distribution for driveline components is tilting toward direct OEM-Tier-1 digital procurement platforms. Dana Incorporated leverages vertical integration across casting, forging, and assembly operations to sustain margin control on heavy-duty axle programs. GKN Automotive anchors European supply through its eDrive systems division, while ZF Friedrichshafen AG competes by extending its hybrid transmission portfolio across multiple vehicle architectures.
A driveline comprises the mechanical and electromechanical subsystems that transmit torque from a power source to the driving wheels, encompassing drive shafts, differentials, transmissions, and axles engineered to withstand torsional loads exceeding 15,000 Nm in commercial applications. Its primary purpose is to modulate speed, torque, and directional power flow while accommodating suspension articulation and wheel speed differentials. The electric vehicle application segment leads value creation as OEMs integrate motor, inverter, and reduction gear into single e-axle modules, while torque vectoring technology captures premium positioning through enhanced vehicle dynamics and energy recuperation. Transmissions retain volume dominance in internal combustion platforms but face margin compression as multi-speed architectures simplify.
The EPA, EU Green Deal framework, and China's MIIT dual carbon goals collectively mandate CO2 reduction trajectories that reshape driveline product planning across all major automotive production regions. REACH substance restrictions and NHTSA safety standards further constrain material selection and validation protocols for lightweight driveshaft alloys. Stakeholders must monitor the pace of platform consolidation as OEMs reduce unique driveline variants and demand modular architectures spanning hybrid and full-electric propulsion systems.
Market Dynamics
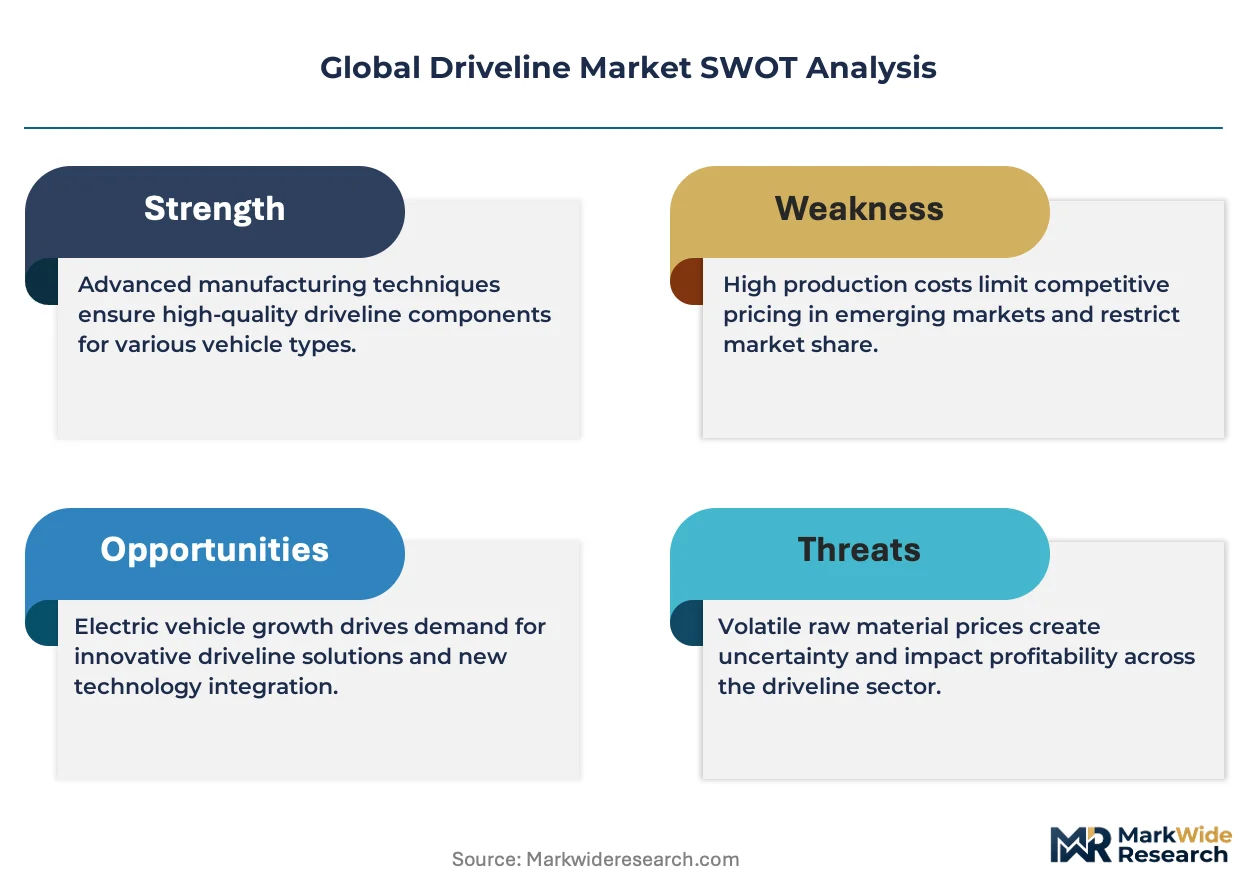
Electrified torque-vectoring architectures are compressing mechanical all-wheel-drive volumes as OEMs redesign platforms around battery-integrated driveline modules. The shift from multi-speed transmissions to single-speed reduction gears in electric vehicles is collapsing supplier margins while concentrating procurement power among integrated e-axle specialists.
Growth Catalysts
- EU Green Deal CO2 mandates:Fleet emission targets below 95 g/km are forcing European OEMs to electrify drivelines ahead of mechanical phase-out schedules.
- China's MIIT dual carbon goals:Domestic joint ventures are localizing hybrid transmission production to capture subsidies and avoid import tariffs on electrified powertrains.
- E-axle integration:Motor-inverter-gearbox modules reduce packaging space and assembly cost, accelerating adoption across compact and mid-size electric vehicle platforms.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing clusters in China create geopolitical exposure for permanent-magnet motor production.
- Legacy transmission asset stranding:Internal combustion-focused suppliers face write-downs on multi-speed gearbox tooling as electrification accelerates beyond depreciation schedules.
- REACH substance restrictions:ECHA limitations on hexavalent chromium coatings and certain alloys constrain corrosion-resistant driveshaft material selection.
Strategic Opportunities
- India's PLI scheme for automotive:Tier-1 suppliers can access production-linked incentives by establishing electric drive unit assembly within designated manufacturing zones.
- Software-defined torque vectoring:Convergence of vehicle dynamics control algorithms with electric drivelines enables subscription-based performance upgrades.
- Direct OEM-Tier-1 digital platforms:Blockchain-tracked component provenance and automated procurement are compressing distributor margins while rewarding vertically integrated suppliers.
Industry Challenges
- Power electronics talent scarcity:Inverter design and thermal management expertise resides in semiconductor and aerospace sectors, forcing driveline suppliers into cross-industry compensation competition.
- Functional safety certification timelines:ISO 26262 ASIL-D validation for electric axle systems extends development cycles by 12-18 months versus mechanical equivalents.
- Legacy platform integration friction:Retrofitting electrified drivelines into existing vehicle architectures requires chassis redesign, limiting speed-to-market for hybrid conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Driveline Market |
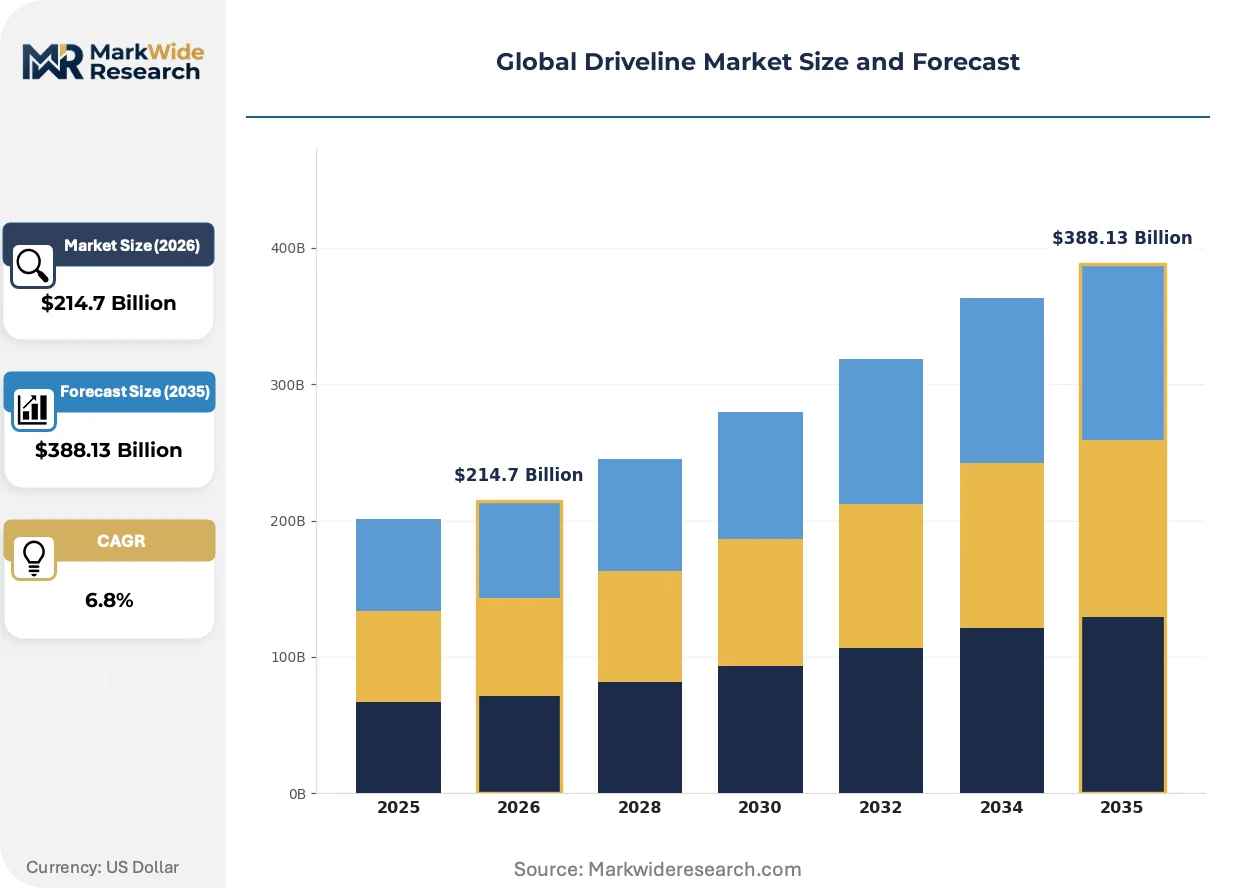
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drive Shafts, Differentials, Transmissions, Axles Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Electric Vehicles End User: OEMs, Aftermarket, Tier-1 Suppliers, Fleet Operators Technology: Torque Vectoring, All-Wheel Drive, Two-Wheel Drive, Hybrid Systems |
| Companies Covered | Dana Incorporated, American Axle & Manufacturing, Inc., GKN Automotive, JTEKT Corporation, Aisin Seiki Co., Ltd., ZF Friedrichshafen AG, Schaeffler AG, Continental AG, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Driveline Market Emerging Trajectories
Silicon carbide semiconductors and additive manufacturing are rewriting thermal and structural limits for driveline components. The competitive frontier has shifted from mechanical durability to software-calibrated power delivery and energy recuperation efficiency.
Silicon carbide MOSFETs in inverter modules are hybridizing power electronics thermal management with driveline packaging, enabling sustained peak torque output without liquid cooling loops. Heavy-duty truck and performance electric vehicle platforms are adopting these devices first. The technology is hybridizing supplier capabilities, forcing mechanical driveline specialists to acquire power semiconductor competencies or cede margin to integrated electronics vendors.
EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates are compressing development timelines for electrified driveline architectures. Manufacturers must certify powertrain variants across multiple regulatory thresholds simultaneously. Commercial vehicle segments in North America face the steepest compliance gradients, accelerating partnerships between traditional axle suppliers and battery-electric powertrain specialists.
Fleet operators and mobility service providers are consolidating procurement around total cost of ownership metrics rather than component-level pricing. Long-term service agreements covering predictive maintenance and residual value guarantees are displacing transactional parts purchasing. This recalibration is most visible in European commercial vehicle markets where CO2-based tolling and urban access restrictions amplify lifecycle cost sensitivity.
Global Driveline Market Segmentation
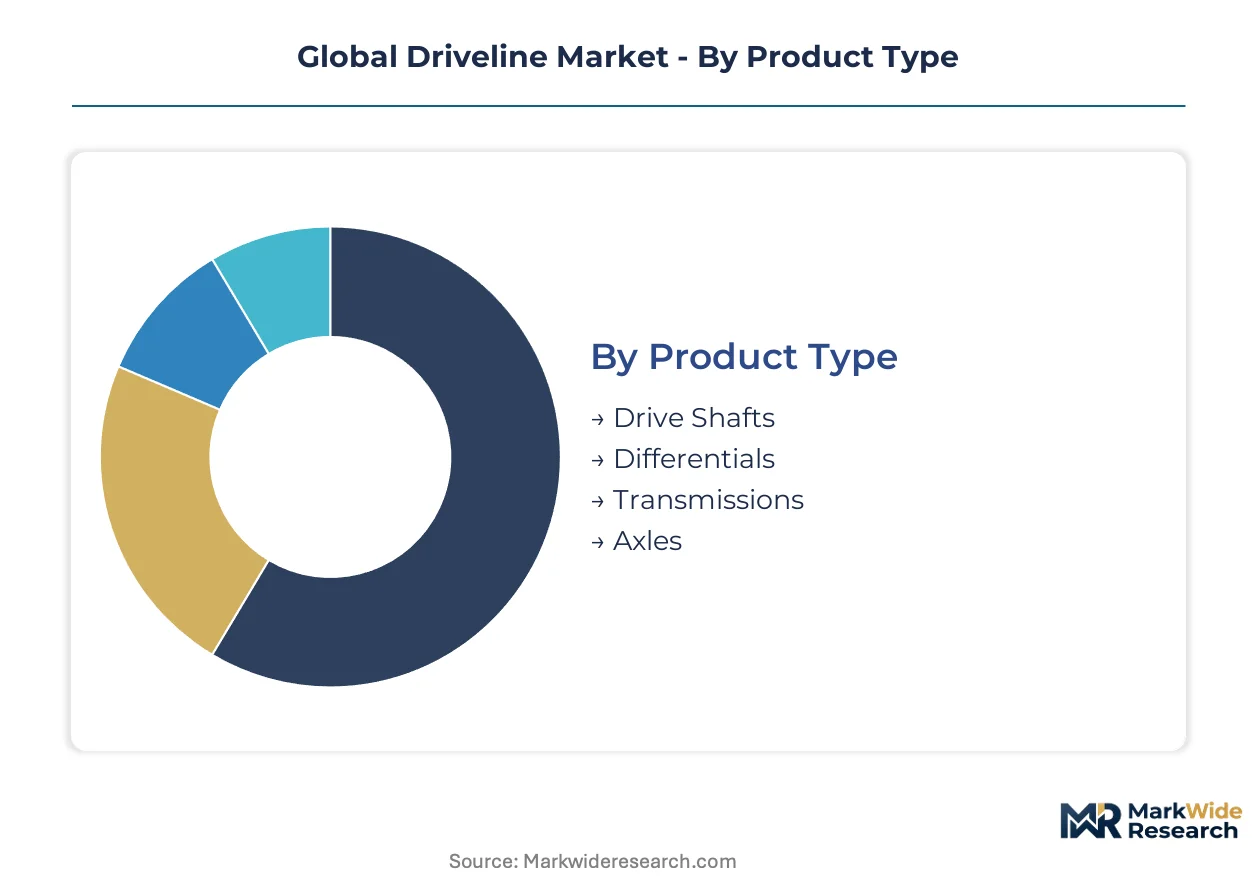
Driveline procurement patterns diverge sharply across vehicle architectures and supply chain tiers. Technology integration and electrification timelines reshape how suppliers allocate R&D resources across product categories.
Product Type:
Cost tier differentiation separates commodity mechanical components from integrated electromechanical modules commanding premium positioning.
- Transmissions:Multi-speed architectures for internal combustion engines retain volume dominance but face margin erosion as single-speed reduction gears displace complex planetary gearsets in electric platforms. Fleet operators in Germany and China are accelerating procurement of automated manual transmissions for commercial vehicles ahead of full electrification transitions.
- Axles:E-axle modules integrating motor, inverter, and reduction gear into single housings represent the highest-value product category. Dana and GKN anchor supply for heavy-duty electric truck programs in the US and UK, where EPA and EU Green Deal mandates compress development cycles.
- Drive Shafts:Hollow aluminum and carbon fiber composite shafts reduce unsprung mass in performance applications.
- Differentials:Limited-slip and torque-vectoring variants serve off-road and premium passenger segments.
Transmissions command the established base. The steepest expansion runs through axles.
Application:
Electrification maturity varies dramatically by vehicle class, with battery platform architecture dictating driveline specification requirements.
- Electric Vehicles:Dedicated battery-electric platforms from Tesla, BYD, and Volkswagen Group mandate compact, high-torque e-axle systems with integrated thermal management. China's MIIT dual carbon goals and California's ZEV mandates are converging procurement specifications across the US, China, and Germany.
- Commercial Vehicles:Heavy-duty trucks and buses face the steepest regulatory compliance gradients, with EPA greenhouse gas standards and EU CO2 performance standards forcing rapid electrification of axle and transmission architectures.
- Passenger Vehicles:Hybrid transmissions bridge internal combustion and full-electric platforms during transition periods.
- Off-Road Vehicles:Mining and construction equipment demand extreme-duty axles exceeding 15,000 Nm torsional capacity.
Passenger vehicles anchor current volume. Commercial vehicles are climbing the fastest as regulatory deadlines tighten.
End User:
Procurement authority is concentrating as OEMs reduce supplier counts and consolidate around integrated module providers.
- OEMs:Volkswagen, Stellantis, and Geely are internalizing e-axle design while outsourcing manufacturing to captive Tier-1 partners. Direct digital procurement platforms are displacing traditional distributor networks for high-volume programs in Germany and China.
- Tier-1 Suppliers:ZF, Dana, and GKN function as system integrators, procuring sub-components from specialized forging and casting operations while retaining final assembly and calibration.
- Fleet Operators:Total cost of ownership contracts now cover predictive maintenance and residual value guarantees.
- Aftermarket:Independent repair networks face margin compression as software-locked components restrict service access.
OEMs command the established base. Tier-1 suppliers are gaining share fastest through vertical integration of power electronics.
Technology:
Mechanical architectures are yielding to software-calibrated electromechanical systems with embedded intelligence.
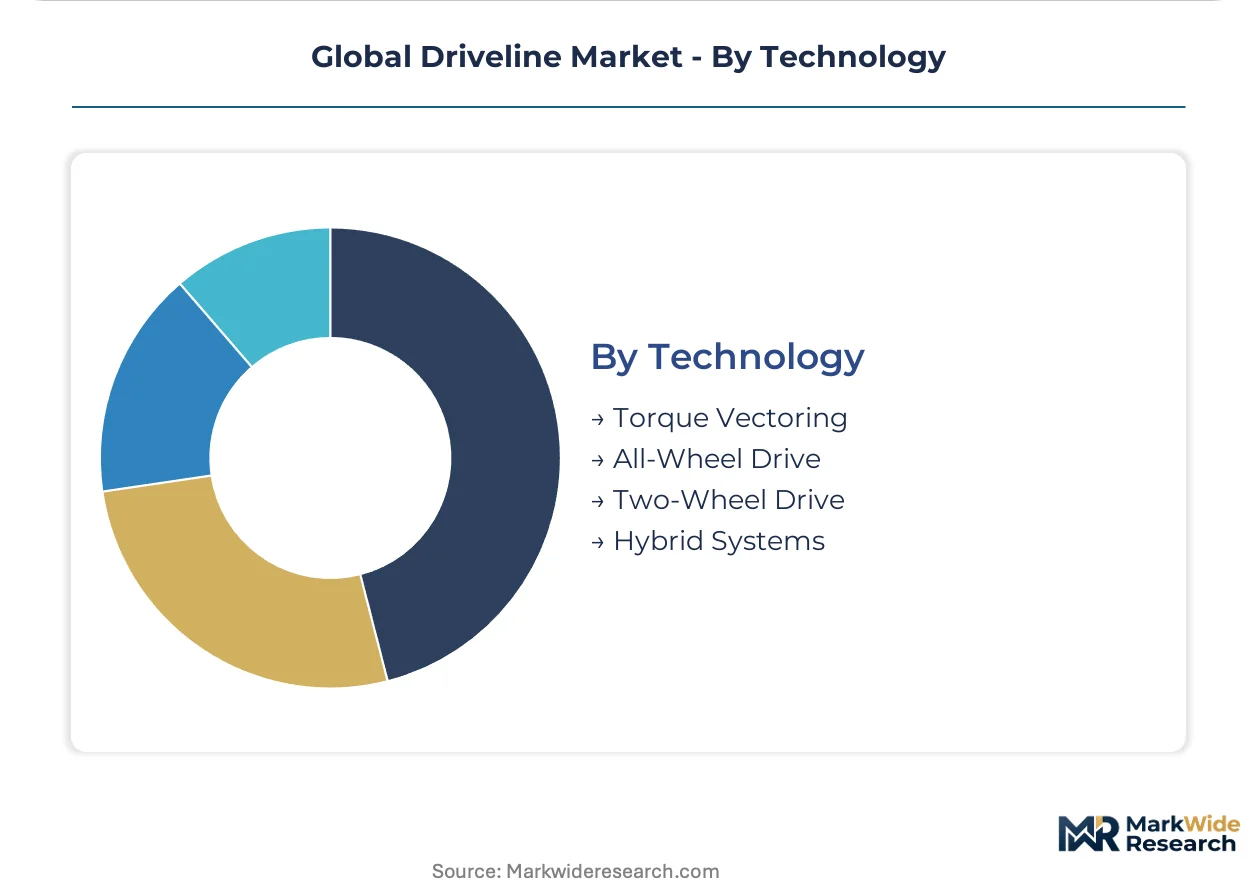
- Torque Vectoring:Electronically controlled differentials and dual-motor e-axles enable precise wheel-level torque distribution, improving vehicle dynamics and enabling energy recuperation during cornering. Premium electric SUVs from BMW, Mercedes-Benz, and NIO are standardizing this technology across Germany, China, and the US.
- Hybrid Systems:P2 and P3 hybrid transmissions integrate electric motors with conventional multi-speed gearboxes, serving as bridge technology for markets with charging infrastructure gaps.
- All-Wheel Drive:Mechanical AWD systems are contracting as electrified torque vectoring displaces center differentials.
- Two-Wheel Drive:Front-wheel-drive architectures dominate compact and economy segments in India and Southeast Asia.
Two-wheel drive commands the established base. Torque vectoring is expanding most quickly as premium electric platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific automotive logistics, channeling rare earth magnet feedstock and finished e-axle modules across Pacific trade lanes. This maritime throughput underwrites China's dominance in electric driveline component exports and establishes pricing benchmarks for global procurement.
United States
Detroit's automotive engineering corridor drives heavy-duty e-axle development for commercial truck electrification. EPA greenhouse gas standards for medium- and heavy-duty vehicles compress supplier development timelines by mandating CO2 reductions through 2032. Michigan and Ohio manufacturing clusters host pilot production lines for integrated electric drive units serving North American OEMs.
Germany
Stuttgart's powertrain engineering ecosystem concentrates torque-vectoring R&D for premium electric SUVs. EU Green Deal fleet emission targets below 95 g/km force mechanical driveline phase-outs ahead of original schedules. Bavaria and Baden-Württemberg supplier parks specialize in silicon carbide inverter integration for high-performance e-axle systems.
China
Shenzhen and Shanghai battery-electric platforms demand compact, high-torque driveline architectures from domestic joint ventures. MIIT dual carbon goals accelerate localization of hybrid transmission production to capture subsidies and avoid import tariffs. Yangtze River Delta manufacturing zones scale electric drive unit output for BYD, NIO, and Volkswagen Group joint ventures.
Japan
Nagoya's automotive belt refines hybrid transmission architectures bridging internal combustion and full-electric platforms. METI carbon neutrality roadmaps mandate supply chain decarbonization for automotive components exported to European markets. Toyota City and surrounding Aichi Prefecture facilities concentrate precision forging capacity for lightweight driveshaft alloys.
India
Chennai and Pune automotive corridors attract electric drive unit assembly under PLI scheme production-linked incentives. Central government automotive sector PLI allocations require domestic value-add thresholds for electrified component eligibility. Tamil Nadu and Maharashtra manufacturing zones host ZF and Dana assembly operations serving Maruti Suzuki and Tata Motors programs.
Global Driveline Market Vendor Landscape
On the supply side, the industry is consolidating around integrated e-axle specialists capable of merging power electronics with mechanical systems. Three archetypes dominate: diversified automotive suppliers with transmission heritage, axle-focused manufacturers extending into electrification, and power electronics entrants from semiconductor sectors. Competitive moves concentrate on strategic partnerships for silicon carbide sourcing and geographic expansion into subsidized manufacturing zones.
Among German-based diversified suppliers, ZF Friedrichshafen AG and Schaeffler AG occupy positions spanning mechanical transmission heritage and electromechanical integration. Dana Incorporated represents the axle-specialist archetype extending into e-axle modules through North American commercial vehicle programs. These three entities exemplify how supplier identity shapes strategic options as electrification collapses traditional component boundaries.
| Leading Market Players |
|---|
| Dana Incorporated |
| American Axle & Manufacturing, Inc. |
| GKN Automotive |
| JTEKT Corporation |
| Aisin Seiki Co., Ltd. |
| ZF Friedrichshafen AG |
| Schaeffler AG |
| Continental AG |
| BorgWarner Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in legacy multi-speed transmission manufacturing across Germany and Japan is forcing suppliers to absorb fixed costs across shrinking volumes, compressing margins and accelerating price concessions for mechanical driveline components while electrified e-axle modules command premium positioning through silicon carbide integration and software-defined torque calibration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated e-axle systems with silicon carbide inverters from aluminum-intensive mechanical axles and commodity cast-iron differentials. Certification tiering under ISO 26262 ASIL-D functional safety standards adds cost premiums for electric axle suppliers serving European and North American OEMs. Price erosion runs through mechanical transmission tiers as platform consolidation eliminates unique gearbox variants. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while premium electric SUV OEMs prioritize performance calibration over unit cost.
Supply Chain Analysis
Rare earth magnet supply concentration in China creates geopolitical exposure for permanent-motor production across Japanese and European e-axle assembly operations. Neodymium and dysprosium processing clusters in Inner Mongolia and Jiangxi province feed motor manufacturing in South Korea and Germany. REACH substance restrictions on hexavalent chromium coatings constrain corrosion-resistant driveshaft material selection for European-bound exports. Distribution runs through direct OEM-Tier-1 digital procurement platforms that displace traditional aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as EU Green Deal and EPA tailpipe mandates create certification moats that mechanical specialists cannot cross without 12-18 month ASIL-D validation cycles.
For Market Incumbents: Build switching-cost moats through embedded software calibration and long-term service agreements covering predictive maintenance. Dana and GKN should deepen backward integration into silicon carbide sourcing to defend margin position against semiconductor entrants. ZF must accelerate hybrid transmission simplification to avoid asset stranding as single-speed reduction gears displace multi-speed architectures.
For New Entrants and Emerging Players: India's PLI scheme manufacturing zones represent the most penetrable entry point for electric drive unit assembly serving Maruti Suzuki and Tata Motors programs. Mid-market commercial vehicle electrification in North America offers white-space as EPA greenhouse gas standards compress development timelines faster than incumbent capacity expansion. Target software-defined torque vectoring as the go-to-market angle, enabling subscription-based performance upgrades that bypass capital-intensive hardware manufacturing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon carbide inverter integration and thermal management subsystems. Long-term viability favors suppliers with captive power electronics competencies or exclusive semiconductor partnerships. Watch rare earth magnet supply diversification initiatives as the inflection signal for geopolitical risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| E-Axle Platform Standardization | Reduces unique variants for Volkswagen Group and Stellantis, compressing supplier qualification costs. |
| Silicon Carbide Supply Agreement | Locks in thermal performance advantage for heavy-duty electric truck programs under EPA mandates. |
| Software-Defined Vehicle Investment | Enables subscription torque-vectoring upgrades across BMW and NIO premium electric SUV platforms. |
| Geographic Manufacturing Footprint | Captures India's PLI scheme incentives for ZF and Dana assembly operations in Tamil Nadu. |
| Charging Infrastructure Partnership | Accelerates commercial vehicle electrification adoption through fleet operator total cost of ownership contracts. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, and SEC supplier filings preceded structured interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads. Primary fieldwork captured procurement platform migration patterns and silicon carbide adoption timelines. Secondary validation drew from EPA regulatory dockets, EU Green Deal implementation documents, and China MIIT policy circulars. Bottom-up unit economics triangulated against top-down market sizing across propulsion architecture segments.
Assumptions held fixed include EU fleet emission targets below 95 g/km and EPA greenhouse gas standards for medium- and heavy-duty vehicles through the projection horizon. Variable assumptions encompass rare earth magnet supply diversification pace and silicon carbide cost curves. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from production volume trajectories and average selling price evolution across electrification transition scenarios. Forecast inputs incorporated battery platform standardization rates and hybrid transmission bridge technology persistence.
Practitioners should monitor MIIT dual carbon goal acceleration and REACH substance restriction expansion for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
North America Precision Gearbox Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Engine Rocker Arm Market
Powertrain
LNG Engine Market
Powertrain
India Automotive Engine Oils Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Diesel Engine Management System Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Sway Bar Bushing Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Automotive Thrust Washer Market