
 Automotive Fuel Injector Market | 2026-2036
Automotive Fuel Injector Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Injector Market Analysis
Electromechanical engineering talent scarcity in precision fuel systems is reorganizing supplier hierarchies across the automotive fuel injector value chain. Robert Bosch GmbH leverages its in-house semiconductor capabilities to control piezoelectric actuator sourcing. Denso Corporation anchors Asian OEM supply relationships through manufacturing scale in Thailand and Japan. Continental AG competes on hybrid electromagnetic-piezoelectric architectures for next-generation powertrains.
An automotive fuel injector is a precision solenoid or piezoelectric valve that meters pressurized fuel at 100-350 bar into engine combustion chambers, with nozzle orifice diameters typically below 0.2 millimeters for gasoline direct injection. Its primary function is optimizing air-fuel mixture atomization to maximize thermal efficiency while minimizing particulate and NOx emissions across varying load conditions. Gasoline direct injectors command the dominant value share as turbocharged downsized engines proliferate, though diesel injectors retain structural importance in commercial vehicle segments. Electromagnetic technology occupies the volume leadership position due to cost scalability, while piezoelectric systems capture premium positioning through sub-millisecond response times enabling multiple injection events per cycle.
The US EPA tailpipe standards and California Air Resources Board mandates compel injector manufacturers to achieve finer fuel droplet size distributions, while China's MIIT corporate average fuel consumption regulations drive domestic OEMs toward higher-pressure direct injection platforms. Euro 7 preparatory work at EMA and national type-approval authorities is forcing redesign cycles for cold-start particulate control. Stakeholders must monitor how battery-electric vehicle penetration rates reshape internal combustion engine component procurement timelines and aftermarket service revenue durability.
Market Dynamics
Precision direct injection system procurement by passenger vehicle OEMs is accelerating as tailpipe standards tighten across major automotive manufacturing jurisdictions. The shift from port injection to high-pressure direct injection architectures is reorganizing supplier technical requirements and certification timelines.
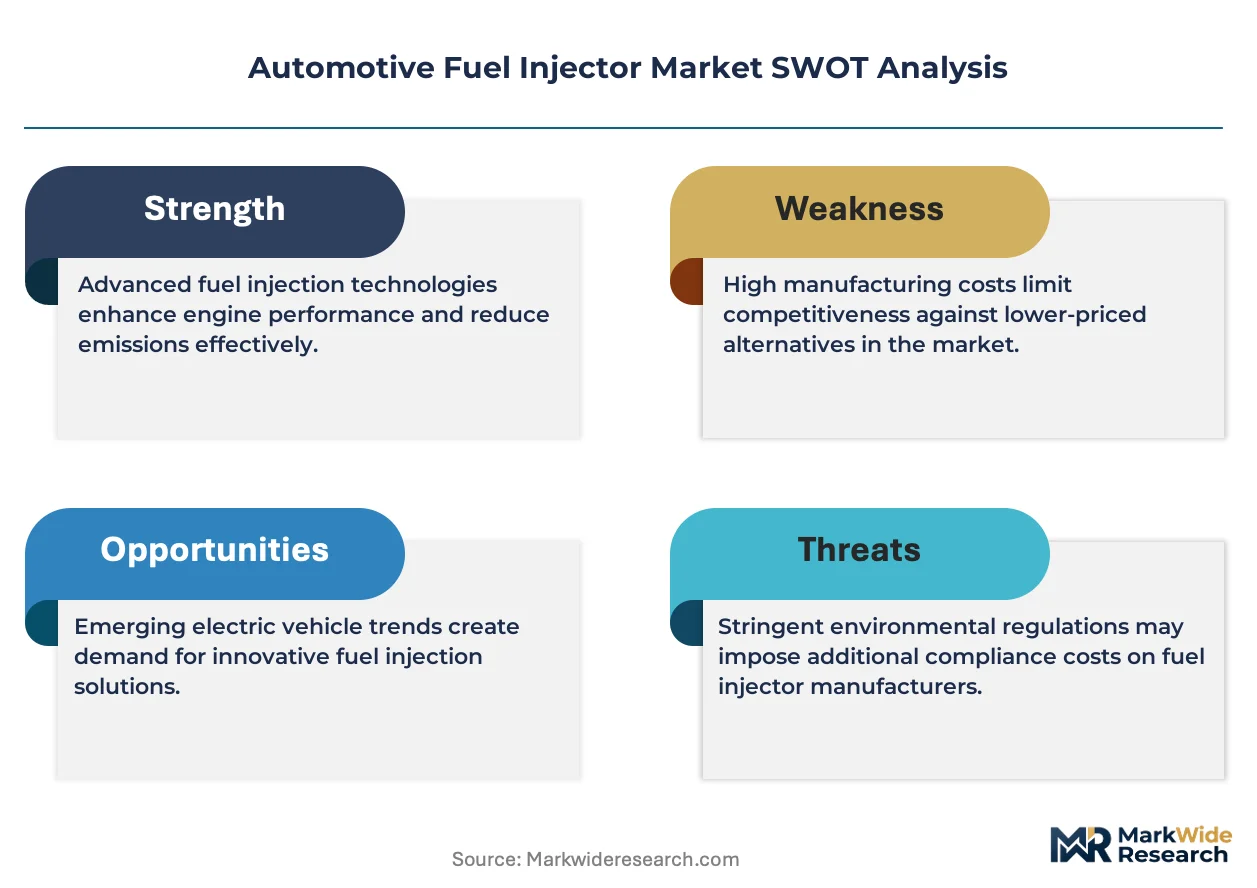
Growth Catalysts
- Euro 7 Framework:The European Commission's preparatory work on cold-start particulate limits is forcing injector redesign cycles for gasoline direct injection platforms across EU member states.
- MIIT Fuel Consumption Mandates:China's Ministry of Industry and Information Technology corporate average fuel consumption regulations compel domestic OEMs toward higher-pressure direct injection systems.
- Turbocharged Downsizing:Engine displacement reduction strategies in passenger vehicles are concentrating demand for piezoelectric actuators capable of multiple injection events per combustion cycle.
Market Restraints
- Piezoelectric Material Concentration:Specialized ceramic actuator sourcing depends on concentrated rare earth processing capabilities in limited geographic corridors.
- Battery-Electric Substitution:BEV powertrain penetration is compressing long-term internal combustion engine component procurement timelines and aftermarket service revenue durability.
- Orifice Machining Costs:Sub-0.2 millimeter nozzle diameter specifications for gasoline direct injection require specialized electrical discharge machining equipment with extended depreciation schedules.
Strategic Opportunities
- Commercial Vehicle Electrification Gap:Heavy-duty diesel injector demand persists in long-haul trucking segments where battery energy density limitations delay full electrification timelines.
- Hybrid Powertrain Convergence:Electromagnetic-piezoelectric hybrid architectures enable optimized injection strategies across variable load conditions in plug-in hybrid electric vehicles.
- Aftermarket Service Digitization:Connected diagnostic platforms for injector performance monitoring create recurring revenue streams independent of original equipment manufacturing cycles.
Industry Challenges
- Piezoelectric Actuator Talent Scarcity:Electromechanical engineering expertise for precision fuel systems is concentrating among a limited supplier base with in-house semiconductor fabrication capabilities.
- Multi-Jurisdiction Certification Compression:Simultaneous EPA, CARB, and MIIT type-approval timelines strain engineering resource allocation across divergent testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Injector Market |
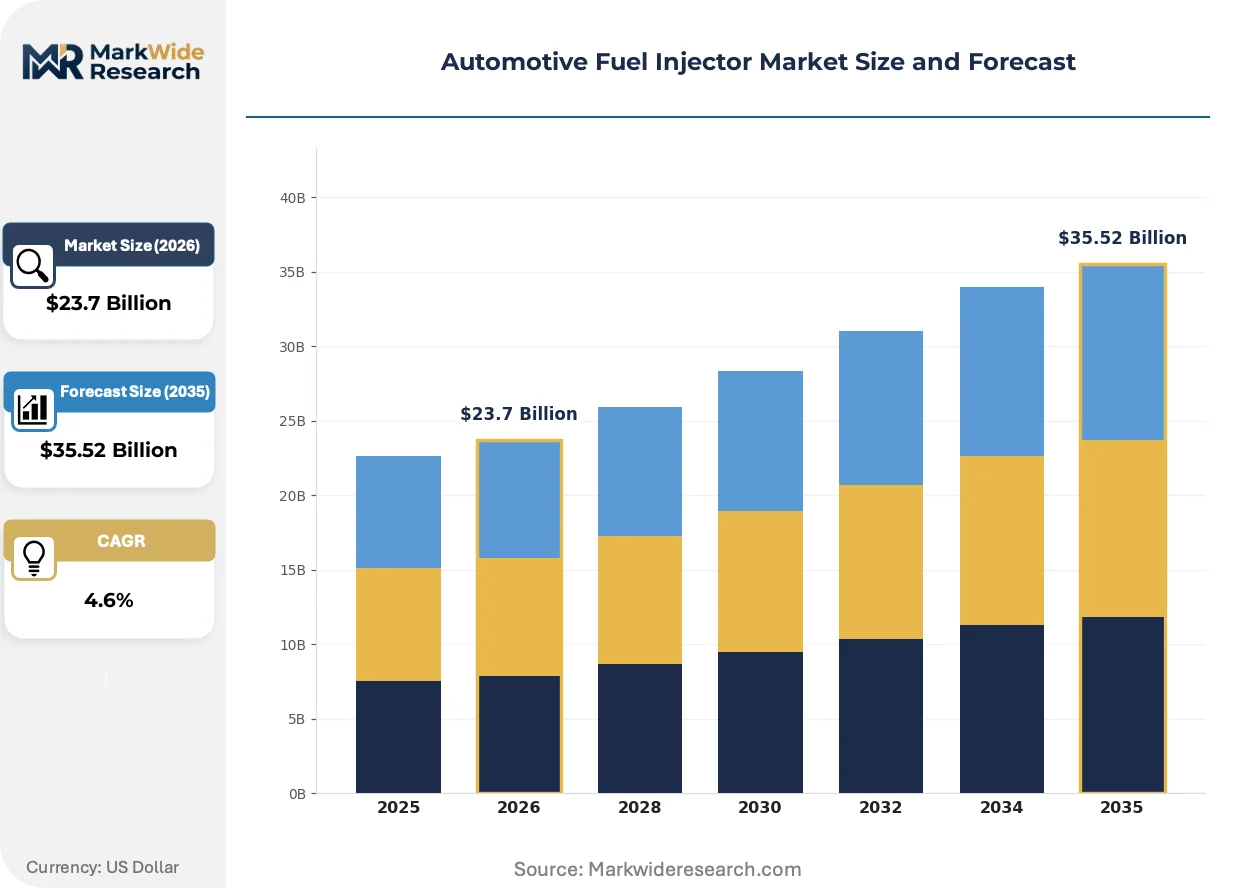
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $35.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Injectors, Diesel Injectors, Direct Injectors, Port Injectors Technology: Electromagnetic, Piezoelectric, Hybrid, Mechanical End User: Original Equipment Manufacturers, Aftermarket Providers, Automotive Repair Shops, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Heavy-duty Trucks, Motorcycles |
| Companies Covered | BorgWarner Inc., Hitachi Astemo Ltd., Robert Bosch GmbH, Stanadyne LLC, Aisan Industry Co. Ltd., Denso Corporation, Marelli Holdings Co. Ltd., Hyundai KEFICO Corporation, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Injector Market Emerging Trajectories
Injector technology trajectories are diverging between cost-optimized electromagnetic architectures and performance-driven piezoelectric systems. Regulatory pressure on particulate emissions is compressing development cycles for cold-start optimization.
Gasoline direct injection nozzle technology is bifurcating between single-hole designs for cost-sensitive applications and multi-hole configurations for premium segment atomization requirements. European luxury OEMs are adopting multi-hole piezoelectric systems at accelerated procurement rates. This technical divergence is compressing supplier R&D allocation between volume and premium tier development tracks.
EPA tailpipe standards and California Air Resources Board mandates are tightening fuel droplet size distribution requirements for particulate matter control. The industrial consequence is expanded electrical discharge machining capacity for orifice precision. Gasoline direct injection platforms face the most acute certification pressure, with OEMs accelerating pre-production validation cycles.
Aftermarket procurement patterns are fragmenting as fleet operators unbundle injector replacement from dealership service contracts. Independent repair networks in Germany's automotive engineering corridor are capturing maintenance volume through specialized diagnostic tooling. This channel shift is most visible in commercial vehicle segments with extended duty cycles and higher injector replacement frequencies.
Automotive Fuel Injector Market Segmentation
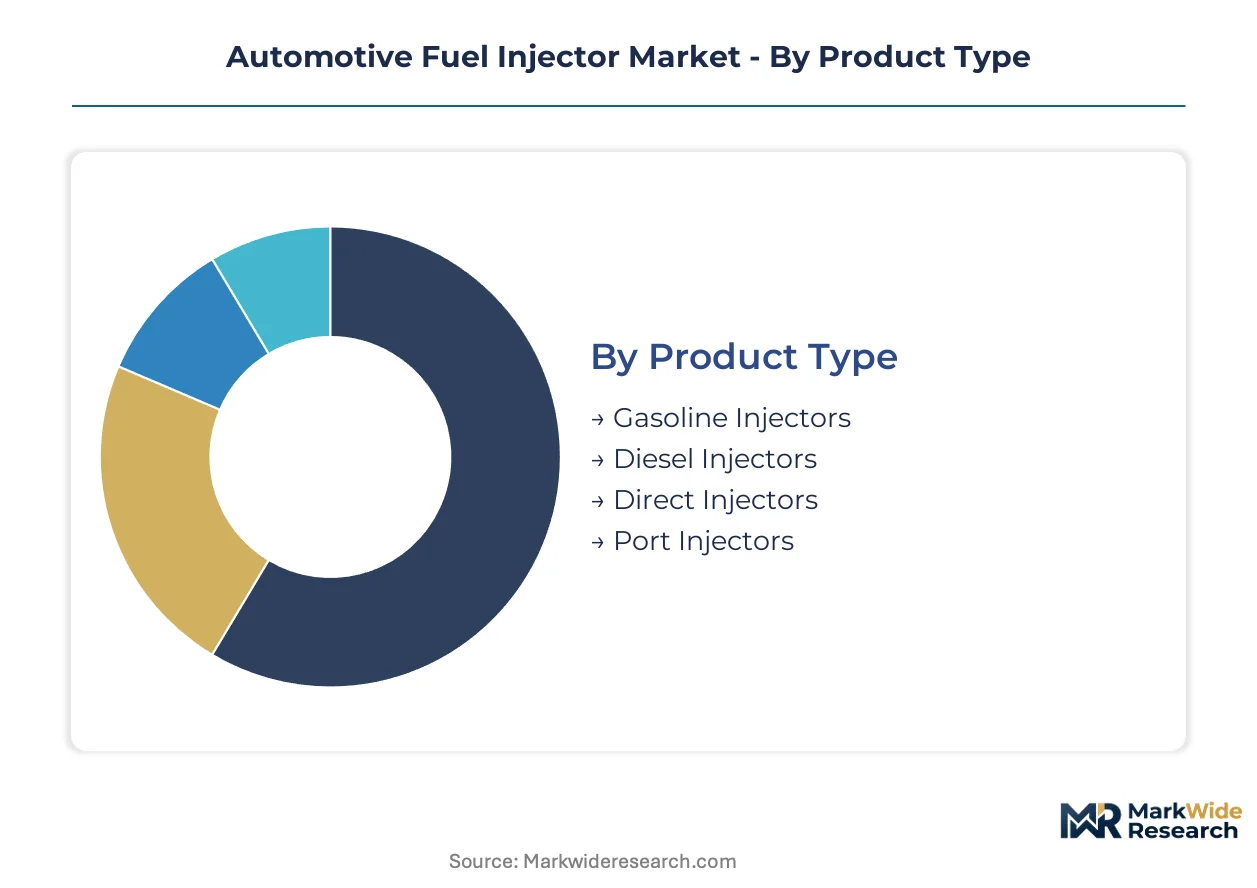
Injector procurement patterns diverge sharply across product architectures and customer channels. OEM specifications for direct injection platforms are tightening faster than aftermarket replacement cycles, creating asynchronous demand rhythms across segment boundaries.
Product Type:
Gasoline direct injectors dominate export flows to European and Chinese assembly plants, while diesel variants concentrate in domestic commercial vehicle supply chains.
- Gasoline Injectors:These solenoid or piezoelectric valves meter fuel at 100-350 bar into combustion chambers with sub-0.2 millimeter orifice precision. Demand clusters in Germany's automotive engineering corridor where turbocharged downsizing strategies require multiple injection events per cycle to satisfy Euro 7 preparatory work on cold-start particulate limits.
- Diesel Injectors:High-pressure common-rail systems operate at 1,800-2,500 bar for commercial vehicle applications, with nozzle designs optimized for soot-NOx tradeoffs. Procurement concentrates in China's Yangtze River Delta manufacturing cluster where heavy-duty trucking electrification timelines remain extended due to battery energy density constraints.
- Direct Injectors:In-cylinder placement enables stratified charge operation and lean-burn thermal efficiency gains.
- Port Injectors:Lower-pressure manifold mounting persists in cost-optimized powertrain configurations and emerging market vehicle platforms.
Gasoline injectors hold installed capacity. Direct injectors are rotating up the share rankings.
Technology:
Actuator selection stratifies by cost-performance tradeoffs, with electromagnetic architectures anchoring volume production and piezoelectric systems capturing premium positioning.
- Electromagnetic:Solenoid-actuated valves achieve 1-2 millisecond response times through copper coil magnetic field generation, enabling cost scalability across high-volume passenger vehicle programs. China's MIIT fuel consumption mandates are accelerating domestic OEM procurement of electromagnetic direct injection platforms for corporate average fuel efficiency compliance.
- Piezoelectric:Ceramic actuator stacks deliver sub-millisecond response enabling five or more injection events per combustion cycle, with precision critical for Euro 7 cold-start particulate control. Sourcing concentrates among suppliers with in-house semiconductor fabrication capabilities due to electromechanical engineering talent scarcity in precision fuel systems.
- Hybrid:Combined electromagnetic-piezoelectric architectures optimize across variable load conditions in plug-in hybrid electric vehicles.
- Mechanical:Legacy spring-loaded designs persist in specialized industrial and marine applications with limited electronic control requirements.
Electromagnetic technology anchors volume leadership. Hybrid architectures are climbing the fastest as PHEV production scales.
End User:
Customer channel concentration varies by vehicle lifecycle position, with OEM procurement driving technology refresh cycles and aftermarket capturing extended service revenue.
- Original Equipment Manufacturers:Passenger vehicle OEMs specify injector performance requirements through powertrain co-development contracts, with procurement timelines compressing under simultaneous EPA, CARB, and MIIT type-approval pressures. European luxury marques are accelerating multi-hole piezoelectric system adoption rates.
- Aftermarket Providers:Independent distributors capture replacement volume as fleet operators unbundle injector service from dealership contracts, particularly visible in Germany where specialized diagnostic tooling enables repair network expansion.
- Automotive Repair Shops:Service bay capacity constraints limit high-pressure direct injector replacement throughput.
- Vehicle Assemblers:Contract manufacturing arrangements concentrate procurement decisions at the platform engineering level.
OEMs hold specification authority. Aftermarket providers are gaining channel share through diagnostic platform digitization.
Application:
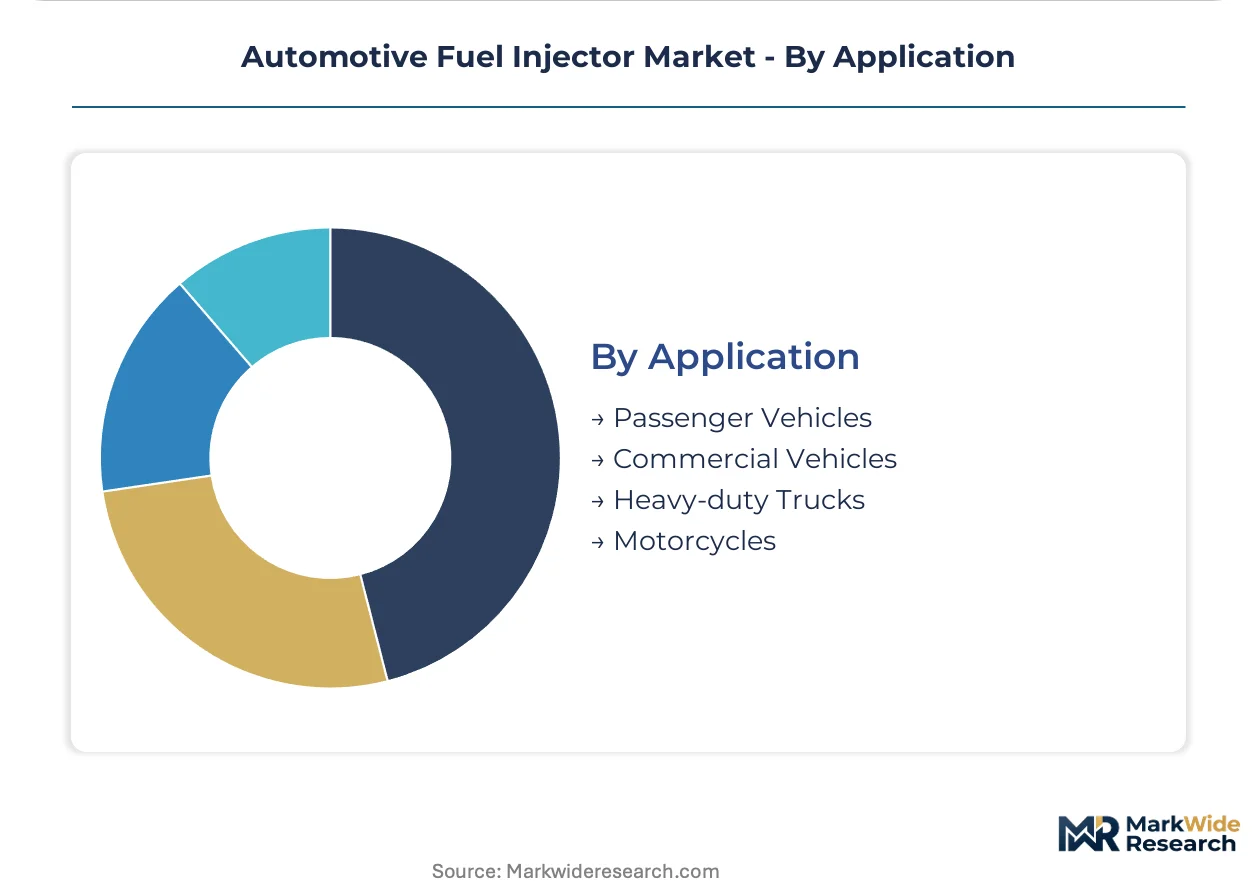
Vehicle category demand splits between passenger car precision requirements and commercial vehicle durability specifications.
- Passenger Vehicles:Turbocharged downsizing strategies concentrate injector procurement in direct injection architectures, with EPA tailpipe standards and California Air Resources Board mandates tightening fuel droplet size distribution requirements for particulate matter control. US and Chinese OEMs are accelerating pre-production validation cycles.
- Commercial Vehicles:Heavy-duty diesel injector demand persists in long-haul trucking segments where full electrification timelines face battery energy density limitations, with replacement frequencies higher than passenger applications due to extended duty cycles.
- Heavy-duty Trucks:Class 8 vehicle specifications emphasize thermal management and extended injector service intervals.
- Motorcycles:Small-displacement gasoline direct injection adoption lags due to cost constraints and packaging limitations.
Passenger vehicles command value concentration. Commercial vehicles are expanding fastest on electrification gap persistence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's precision engineering corridor while Chinese manufacturers compete on volume scale across the Yangtze River Delta. This asymmetry shapes procurement negotiations between European OEMs and Asian suppliers. Regional regulatory divergence accelerates technology fragmentation.
United States
Passenger vehicle OEMs accelerate direct injection platform validation under EPA tailpipe standards and California Air Resources Board mandates. The regulatory pressure tightens fuel droplet size distribution requirements for particulate matter control. Detroit's automotive engineering cluster concentrates pre-production testing capacity for gasoline direct injection systems.
Germany
European luxury marques drive multi-hole piezoelectric injector procurement at premium pricing tiers. Euro 7 preparatory work at EMA forces redesign cycles for cold-start particulate limits. Stuttgart and Munich anchor supplier R&D allocation between volume and premium development tracks.
China
Domestic OEMs expand higher-pressure direct injection procurement to satisfy MIIT corporate average fuel consumption regulations. The ministry's fuel efficiency mandates compress technology refresh timelines. Shanghai and Suzhou in the Yangtze River Delta manufacturing cluster concentrate electromagnetic actuator production scale.
Japan
Piezoelectric actuator expertise concentrates among suppliers with in-house semiconductor fabrication capabilities. METI industrial policy supports precision component manufacturing competitiveness. Toyota City and Nagoya anchor hybrid powertrain injector development for plug-in electric vehicle convergence.
South Korea
Domestic OEMs balance electromagnetic cost scalability with piezoelectric performance requirements for turbocharged downsizing strategies. National type-approval authorities align testing protocols with EPA and Euro 7 frameworks. Ulsan and Hwaseong manufacturing complexes concentrate high-volume injector assembly capacity.
Automotive Fuel Injector Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the automotive fuel injector value chain. The supplier base organizes into three tiers: integrated system houses with captive semiconductor capabilities, scale-focused electromagnetic specialists, and regional fabrication champions serving domestic OEMs. Consolidation pressures intensify as multi-jurisdiction certification timelines strain engineering resources. Dominant competitive moves include backward integration into piezoelectric ceramic processing and strategic partnerships for hybrid actuator architectures.
Among German-integrated system houses, Robert Bosch GmbH and Continental AG exemplify the technology leadership archetype through in-house precision manufacturing capabilities. Denso Corporation anchors Asian supply relationships through manufacturing scale concentration in Japan and Thailand. These three companies represent the primary competitive anchors against which regional specialists and emerging challengers position their alternative cost-performance profiles.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Hitachi Astemo Ltd. |
| Robert Bosch GmbH |
| Stanadyne LLC |
| Aisan Industry Co. Ltd. |
| Denso Corporation |
| Marelli Holdings Co. Ltd. |
| Hyundai KEFICO Corporation |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
EPA tailpipe standards and California Air Resources Board mandates gate both supplier qualification and price differentiation simultaneously, as certification-grade electromagnetic and piezoelectric architectures command distinct procurement premiums while excluding uncertified fabrication capacity from OEM consideration. The interaction between multi-jurisdiction type-approval compression and specialized electrical discharge machining requirements concentrates pricing power among integrated system houses with captive semiconductor capabilities.
Pricing Analysis
The customization-premium spread separates configured-to-order multi-hole piezoelectric systems for European luxury OEMs from standard electromagnetic platforms serving high-volume passenger vehicle programs. Price differentiation hinges on certification tier under Euro 7 preparatory work and MIIT fuel consumption mandates, alongside volume scale economies in China's Yangtze River Delta manufacturing cluster. Cost compression in standard electromagnetic tiers intensifies as domestic Chinese suppliers expand capacity. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while European luxury marques demonstrate lowest sensitivity due to performance-critical cold-start particulate requirements.
Supply Chain Analysis
Extended lead times for specialized electrical discharge machining equipment and piezoelectric ceramic actuator stacks compress inventory flexibility across the value chain. Supply concentrates in Germany's precision engineering corridor, China's Yangtze River Delta manufacturing cluster, and Japan's semiconductor fabrication hubs. Raw material dependencies draw from rare earth processing corridors for ceramic actuators, high-purity copper for electromagnetic coils, and specialized tungsten alloys for nozzle orifices. Single-source vulnerability in piezoelectric material sourcing constitutes the dominant structural risk. Distribution runs through Tier 1 supplier direct contracts with OEM platform engineering teams, with aftermarket channels fragmenting toward independent diagnostic-equipped repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive fuel injector market sits at a platform-economics inflection as powertrain electrification convergence forces interoperability decisions between electromagnetic-piezoelectric hybrid architectures and pure-play technology commitments. The shift toward software-defined injection control and connected diagnostic platforms restructures competitive moats around data ecosystems rather than component manufacturing scale alone.
For Market Incumbents: Compound defensive positioning through backward integration into piezoelectric ceramic processing and captive semiconductor fabrication capacity, addressing electromechanical engineering talent scarcity that threatens supplier hierarchy stability. Accelerate certification investment for simultaneous EPA, CARB, and MIIT type-approval to compress competitor entry timelines. Prioritize channel control through proprietary diagnostic platform deployment that locks aftermarket service revenue independent of OEM procurement cycles.
For New Entrants and Emerging Players: Anchor in commercial vehicle electrification gaps where heavy-duty diesel injector demand persists against extended battery energy density limitations, particularly in China's Yangtze River Delta logistics corridors. Target aftermarket digitization white space through connected injector performance monitoring platforms serving fleet operators unbundling from dealership service contracts. Pursue go-to-market partnerships with independent repair networks in Germany's automotive engineering corridor leveraging specialized diagnostic tooling requirements.
For Investors and Strategic Acquirers: Euro 7 cold-start particulate limits reshape the acquisition landscape toward suppliers with proven multi-hole piezoelectric system validation and in-house semiconductor capabilities. Frame long-term viability around hybrid powertrain convergence persistence rather than pure internal combustion engine component durability. Monitor battery-electric vehicle penetration rates in passenger vehicle segments as the critical signal for portfolio rebalancing between electrification-gap plays and legacy aftermarket service exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Piezoelectric Ceramic Backward Integration | Captive actuator sourcing insulates against rare earth processing concentration risk. |
| Multi-Jurisdiction Certification Pre-Positioning | Simultaneous EPA, CARB, and MIIT approval compresses competitor platform access. |
| Hybrid Actuator Architecture Development | Electromagnetic-piezoelectric convergence captures plug-in hybrid electric vehicle procurement. |
| Connected Diagnostic Platform Deployment | Recurring aftermarket revenue streams decouple from OEM manufacturing cycles. |
| Electrical Discharge Machining Capacity Expansion | Sub-0.2 millimeter orifice precision enables Euro 7 cold-start particulate compliance. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and piezoelectric actuator R&D directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, IHS Markit registration data, EPA certification filings, and MIIT corporate fuel consumption disclosure records. Bottom-up triangulation across component-level procurement volumes and top-down reconciliation against powertrain production forecasts anchored the quantitative framework.
Segmentation dimensions modeled span vehicle class, propulsion architecture, actuator technology type, and regional production cluster across the projection horizon. CAGRs were derived from weighted regression across historical procurement trajectories and regulatory-mandated technology refresh timelines. Industry-specific forecast inputs incorporated turbocharged downsizing penetration rates and battery-electric vehicle substitution elasticity by vehicle segment.
Decision-makers should treat outputs as directional under assumptions of sustained internal combustion engine production through the analysis window and stable multi-jurisdiction regulatory divergence; material deviation in electrification pace or regulatory harmonization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Internal Combustion Engine Market
Powertrain
Automotive PTC Heaters Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Automotive Hydraulic Lash Adjuster Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Clutch Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Automotive Hydrostatic Fan Drive System Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Diesel Engine Management System Market
Powertrain
Torque Limiter Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Car Drive System Market