
 Transmission Components Market | 2026-2036
Transmission Components Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Components Market Outlook
The divergence between premium precision components and commodity-grade transmission parts is hardening as electric powertrains demand tighter tolerances and lighter materials. SKF AB leverages its bearing and precision engineering heritage to anchor the premium tier across European automotive supply chains. Dana Incorporated competes in the North American commercial vehicle segment with integrated electromechanical systems that reduce drivetrain complexity. Schaeffler AG specializes in hybrid transmission modules that bridge mechanical and electric architectures for OEM customers.
Transmission components encompass the mechanical, hydraulic, and electromechanical elements—gears, shafts, couplings, and actuators—that transfer rotational power between engine and driven load, typically manufactured through precision forging, CNC hobbing, and heat treatment to achieve surface hardness ratings exceeding 60 HRC. The automotive application segment leads volume demand as OEMs and Tier-1 Suppliers retool for electrified platforms, while the hydraulics product category sustains margin pools in industrial and marine end uses where load capacity and shock resistance command specification premiums. The electric technology segment is displacing pneumatic and pure mechanical alternatives in aerospace and automotive contexts where energy efficiency and regenerative capability determine platform selection.
The EPA and NHTSA in the United States, alongside the EU Green Deal and REACH frameworks in Europe, are tightening emissions and material disclosure standards that force component suppliers to certify supply chain transparency and recyclability. China's MIIT enforces GB standards for energy consumption in vehicle transmissions, creating market access barriers for uncertified imports. Stakeholders must monitor how dual carbon goals in Asia and the EU AI Act's emerging manufacturing compliance requirements reshape sourcing and certification priorities across their supplier networks.
Market Dynamics
The transition from multi-speed mechanical transmissions to fixed-gear electric powertrains is compressing component counts while elevating precision requirements for remaining gears and shafts. This structural shift forces suppliers to retool forging and heat-treatment capacity toward tighter tolerances or exit volume automotive supply chains entirely.
Growth Catalysts
- Dual Carbon Goals:China's MIIT enforcement of GB standards for vehicle transmission efficiency accelerates demand for lightweight alloy components that reduce energy consumption in electrified platforms.
- REACH Compliance:The EU's material disclosure and recyclability mandates force component suppliers to certify supply chain transparency, creating specification premiums for certified precision manufacturers.
- EV Production Hubs:Concentrated battery and vehicle assembly in Germany, China, and the United States pulls localized sourcing of precision-engineered gears and shafts to reduce logistics exposure.
Market Restraints
- Aluminum and Rare Earth Volatility:Lightweight alloy feedstock costs fluctuate with energy prices and mining export controls, compressing margins for forged component producers locked into annual OEM pricing agreements.
- Supplier Concentration in East Asia:Carbon composite preform manufacturing and precision CNC equipment production cluster in China and Japan, creating single-source vulnerability for Western tier suppliers.
- Fixed-Gear Architecture Limits:Electric powertrains eliminate multi-speed gearbox complexity, reducing addressable component volume per vehicle by 60-70 percent versus conventional automatic transmissions.
Strategic Opportunities
- Commercial Vehicle Electrification:Heavy-duty truck and bus platforms in North America and Europe retain multi-speed requirements for torque multiplication, preserving demand for high-load gears and integrated electromechanical actuators.
- EU AI Act Manufacturing Compliance:Emerging requirements for automated quality assurance and predictive maintenance in component production create first-mover advantage for suppliers deploying machine-vision inspection systems.
- Aftermarket Remanufacturing:Extended vehicle lifecycles and sustainability mandates open channel expansion into certified rebuilt transmission modules, bypassing price-competitive new-component markets.
Industry Challenges
- CNC Hobbing and Grinding Talent Scarcity:Precision gear manufacturing requires specialized machinist skills that retire faster than vocational programs replenish, constraining capacity expansion at independent forges.
- Heat Treatment Certification Timelines:Surface hardness validation to 60+ HRC specifications demands extended testing protocols that delay new product qualification with risk-averse OEM quality departments.
- Legacy System Integration:Electromechanical actuators and sensor-embedded components must interface with existing vehicle communication architectures, multiplying validation complexity for hybrid transmission modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Components Market |
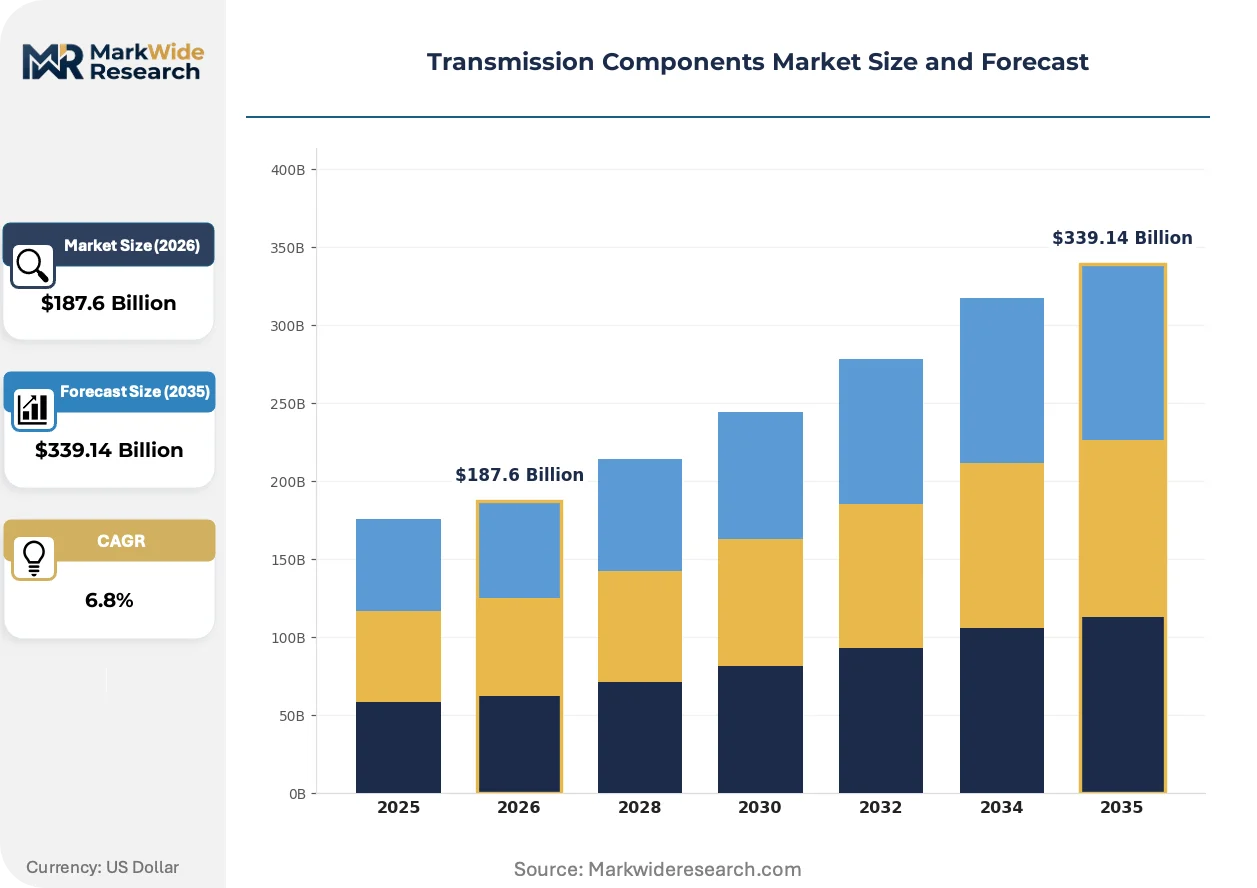
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gears, Shafts, Hydraulics, Couplings Technology: Electric, Pneumatic, Mechanical, Hybrid Application: Automotive, Industrial, Marine, Aerospace End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Maintenance Services |
| Companies Covered | NSK Ltd., Rexnord Corporation, Continental AG, SKF AB, Schaeffler AG, Dana Incorporated, NTN Corporation, The Timken Company, JTEKT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Components Market Strategic Shifts
Additive manufacturing of near-net-shape gear blanks is reshaping forging economics by reducing material waste and enabling topology-optimized designs impossible with conventional die forging. This technology convergence accelerates prototype-to-production cycles for low-volume precision applications.
Integrated electromechanical transmission modules is modularizing powertrain architecture by combining motor, gearbox, and inverter into single housings. Tier-1 suppliers in the commercial vehicle segment adopt this approach fastest, compressing supplier tiers from three to two while elevating system-level accountability. The shift forces component specialists to certify as module integrators or retreat to commodity shaft and bearing supply.
REACH and the EU Green Deal are tightening material disclosure requirements that extend to conflict minerals and carbon intensity certification. Component suppliers must document smelter sources and recyclability rates to maintain specification status with European OEMs. The hydraulics product category faces the steepest compliance burden due to legacy use of chrome plating and phosphate coatings now restricted under emerging substance bans.
Buyer concentration among electrified platform OEMs is consolidating procurement authority into fewer sourcing decisions with larger volume commitments. Tier-1 transmission integrators in Germany and China now specify component suppliers directly, disintermediating traditional tier-2 relationships. This pattern concentrates revenue risk for precision forges while rewarding scale investments that secure sole-source positions on high-volume EV programs.
Transmission Components Market Segmentation
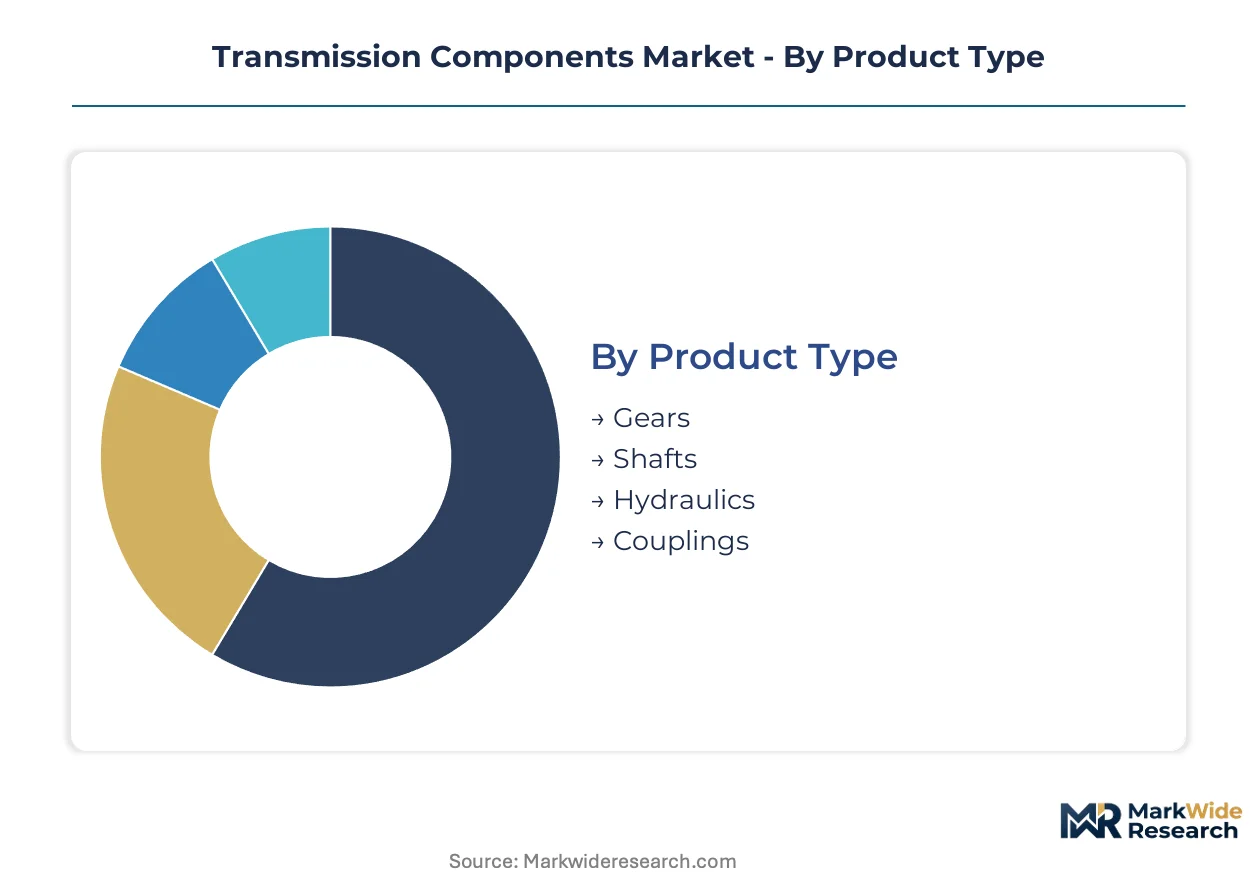
Transmission component procurement patterns diverge sharply across product categories and end-use specifications. OEMs prioritize precision tolerances and certification traceability, while aftermarket channels emphasize interchangeability and remanufacturing compatibility.
Product Type:
Cost tier separates commodity forging buyers from precision specification customers requiring surface hardness validation above 60 HRC.
- Gears:Precision-forged or CNC-hobbed components with case-hardened surfaces deliver torque transmission in multi-speed and fixed-gear architectures. Demand concentrates in Germany and China where EV powertrain assembly clusters pull localized sourcing of spiral bevel and helical gear sets for torque density optimization.
- Shafts:Hollow and solid forged shafts undergo induction hardening and finish grinding to achieve sub-10 micron runout tolerances. Automotive OEMs in the United States specify these for integrated electromechanical modules where weight reduction and NVH performance determine platform selection.
- Hydraulics:Valve bodies, pumps, and actuators serve industrial and marine load-handling applications.
- Couplings:Flexible and rigid designs accommodate misalignment compensation in drivetrain assemblies.
Volume sits with Gears; growth tilts toward Shafts.
Technology:
Application requirements dictate whether energy efficiency, regenerative capability, or shock resistance dominates specification priorities.
- Electric:Integrated motor-gearbox-inverter modules eliminate mechanical complexity while demanding precision-machined gears for single-speed reduction ratios. Aerospace and automotive platforms in China and Germany adopt these fastest where regenerative braking and energy recovery determine total cost of ownership calculations.
- Hybrid:Electromechanical architectures bridge internal combustion and electric power sources through clutch-integrated gear sets. Commercial vehicle OEMs in North America specify these for torque multiplication in heavy-duty truck applications where battery weight limits pure electric range.
- Mechanical:Pure gear-and-shaft systems persist in cost-sensitive industrial equipment.
- Pneumatic:Compressed air actuation retains niche use in explosive-environment machinery.
Mechanical systems retain installed base dominance; Hybrid configurations are expanding most quickly in commercial vehicle electrification.
Application:
Volume scale versus margin structure separates high-unit automotive programs from specification-premium industrial and marine contracts.
- Automotive:Light-duty passenger and commercial vehicle platforms drive the largest unit demand for transmission components. Retooling for electrified architectures in Germany, China, and the United States compresses multi-speed gearbox content while elevating precision requirements for remaining fixed-gear elements.
- Industrial:Material handling, construction, and agricultural equipment sustain demand for hydraulics and mechanical power transmission. Load capacity ratings and shock resistance specifications command margin premiums in this segment where equipment lifecycle cost outweighs initial procurement price.
- Marine:Propulsion and auxiliary systems require corrosion-resistant alloys and sealed bearing assemblies.
- Aerospace:Weight-critical applications specify titanium and composite shafting for auxiliary power units.
Automotive commands unit volume; Industrial and Marine together generate superior margin per kilogram.
End User:
Procurement authority concentration determines whether component suppliers negotiate directly with platform integrators or through tiered supply chain intermediaries.
- OEMs:Vehicle and equipment manufacturers specify component grades directly for new platform development. Electrified powertrain programs in China and Germany consolidate sourcing decisions into fewer supplier relationships with larger volume commitments and stringent certification timelines.
- Tier-1 Suppliers:Transmission system integrators procure gears, shafts, and actuators for module assembly. These intermediaries in Germany and the United States now disintermediate traditional tier-2 relationships by specifying component sources directly.
- Aftermarket Providers:Independent distributors and remanufacturers serve replacement demand.
- Maintenance Services:Fleet operators and repair facilities procure components for in-service equipment refurbishment.
Procurement volume aggregates with OEMs and Tier-1 Suppliers; channel expansion tilts toward Aftermarket Providers as extended vehicle lifecycles elevate remanufacturing economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European transmission component demand through its concentration of OEM powertrain engineering centers and Tier-1 module assembly plants serving electrified vehicle platforms.
China
MIIT enforcement of GB standards for transmission energy efficiency accelerates lightweight alloy adoption in Yangtze River Delta manufacturing clusters. Dual carbon goals compress supplier certification timelines for carbon intensity disclosure. Shenzhen and Shanghai house the dominant electromechanical module integrators pulling precision gear sourcing locally.
Germany
REACH material disclosure mandates and the EU Green Deal force component suppliers to document smelter sources and recyclability rates. The EU AI Act's emerging manufacturing compliance requirements reshape automated quality assurance investments. Baden-Württemberg and Bavaria concentrate precision forging capacity for hybrid transmission modules.
United States
EPA and NHTSA emissions standards tighten specifications for commercial vehicle powertrain efficiency. The Inflation Reduction Act's domestic content provisions incentivize localized sourcing of precision-machined shafts. Michigan and Ohio retain forged component capacity serving Detroit-based OEM electrification programs.
Japan
METI industrial policy supports carbon-neutral manufacturing transitions for precision gear producers. JIS standards for surface hardness validation maintain specification barriers for imported components. Nagoya and Tokyo metropolitan areas concentrate CNC hobbing equipment production and technical talent development.
South Korea
MFDS-equivalent industrial standards and national carbon neutrality targets accelerate heat-treatment facility upgrades. Seoul Capital Area and Busan-Ulsan corridor host integrated motor-gearbox assembly operations for domestic EV platforms. Government battery production subsidies pull localized component sourcing from Chinese and Japanese suppliers.
Transmission Components Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade and precision-tolerance dimensions. The vendor base stratifies into three tiers: integrated module suppliers capturing system-level value, precision forging specialists defending specification premiums, and commodity shaft producers competing on volume scale. Consolidation pressures concentrate procurement authority into fewer Tier-1 relationships with larger volume commitments. Dominant competitive moves include strategic partnerships for electromechanical integration and capacity expansion in heat-treatment and CNC grinding capabilities.
Within the integrated module tier, Schaeffler AG and Dana Incorporated exemplify suppliers bridging mechanical and electric architectures through hybrid transmission systems. SKF AB anchors the precision engineering segment with heritage positioning in bearing and gear applications. These three entities occupy positions that reflect the market's bifurcation between system integrators and component specialists.
| Leading Market Players |
|---|
| NSK Ltd. |
| Rexnord Corporation |
| Continental AG |
| SKF AB |
| Schaeffler AG |
| Dana Incorporated |
| NTN Corporation |
| The Timken Company |
| JTEKT Corporation |
| Others |
Value Chain & Pricing Dynamics
CNC hobbing machinist concentration in Baden-Württemberg and Bavaria feeds labor-cost differentials that widen pricing-tier spreads between premium-certified precision forges and commodity-grade shaft producers. These regional skill premiums compound with energy-intensive heat-treatment costs to stratify supplier economics across European and North American automotive supply chains.
Pricing Analysis
Yield-based pricing anchors component valuations to validated surface hardness outcomes and fatigue-life performance rather than input weight alone. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified precision manufacturers from aftermarket interchangeability suppliers. Cost compression in commodity-grade forged shafts intensifies because aluminum alloy feedstock volatility squeezes margin pools locked into annual OEM pricing agreements. Tier-1 transmission integrators exhibit lowest price sensitivity due to sole-source qualification timelines, while independent aftermarket distributors face acute pressure from remanufacturing alternatives.
Supply Chain Analysis
Precision CNC equipment supply rests on Japanese and German machine tool producers, with carbon composite preform manufacturing clustering in China and Japan. Lightweight alloy feedstock draws from Chinese rare earth processors and German specialty steel mills, while induction hardening equipment sources from Italian and American thermal systems specialists. Single-source vulnerability concentrates in East Asian carbon fiber preform capacity, exposing Western tier suppliers to export control disruptions. Distribution runs through OEM-directed Tier-1 module integrators that disintermediate traditional tier-2 component relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed-gear electric powertrains are displacing multi-speed mechanical architectures, compressing component counts while elevating precision requirements for remaining gears and shafts in automotive and commercial vehicle platforms.
For Market Incumbents: Anchor premium positioning through captive heat-treatment capacity additions in Germany and the United States that secure OEM qualification timelines against emerging Asian competitors. Deepen backward integration into lightweight alloy forging feedstocks to buffer margin pressure from rare earth export controls. Certification investment in REACH-compliant material traceability systems defends specification status against regulatory tightening in European automotive procurement. For New Entrants and Emerging Players: Additive manufacturing of near-net-shape gear blanks offers a technology-first wedge into low-volume precision applications where prototyping speed commands specification premiums. Target commercial vehicle electrification segments in North America where heavy-duty torque multiplication requirements preserve multi-speed gearbox demand. Pursue direct qualification with battery-electric bus OEMs bypassing entrenched Tier-1 transmission integrator relationships. For Investors and Strategic Acquirers: Re-rating potential sits with precision forging specialists possessing certified 60+ HRC heat-treatment capabilities given accelerating OEM consolidation of supplier relationships into fewer volume commitments. Long-term viability favors mid-cap entities with demonstrated module integration competence bridging mechanical and electromechanical architectures. Monitor MIIT enforcement intensity on GB standards compliance as inflection indicator for Chinese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Treatment Capacity Expansion | Captures OEM qualification premiums through validated 60+ HRC surface hardness certification. |
| Electromechanical Module Integration | Elevates supplier tier from component forge to system-level accountability with German OEMs. |
| Lightweight Alloy Backward Integration | Secures feedstock cost control against Chinese rare earth export volatility. |
| Machine-Vision Quality Assurance | Positions first-mover advantage under emerging EU AI Act manufacturing compliance requirements. |
| Aftermarket Remanufacturing Channel | Bypasses price-competitive new-component markets through certified rebuilt transmission modules. |
Study Parameters
Multi-period observation of OEM platform retooling timelines and Tier-1 supplier consolidation patterns anchored the trend analysis, supplemented by interviews with transmission procurement directors, heat-treatment facility managers, CNC equipment specialists, and aftermarket distribution executives. Secondary validation drew from EPA and NHTSA regulatory filings, MIIT GB standard enforcement records, EU ECHA substance restriction updates, and automotive production registration databases. Bottom-up component demand modeling triangulated against top-down powertrain architecture forecasts across the analysis window.
Segment-weighting applied product-type splits across gears, shafts, hydraulics, and couplings, crossed with technology categories spanning electric, hybrid, mechanical, and pneumatic architectures, further disaggregated by automotive, industrial, marine, and aerospace end-use applications. CAGRs derived from fitted growth curves applied to electrification penetration scenarios and commercial vehicle torque-density requirements throughout the forecast period. Industry-specific inputs included MIIT dual carbon goal enforcement trajectories and REACH material disclosure timeline assumptions.
Several conditions sit outside the modeled scope, including unannounced OEM platform cancellations, abrupt rare earth export embargoes, and disruptive solid-state battery commercialization that could eliminate remaining gearbox content. Forecasts reflect stated policy implementation and announced capacity investment commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Engine Air Filter Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
Aluminum Alloy Wheel Market
Vehicle Components
Headlight Market
Vehicle Components
Steering Gear Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Rear Axle Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Throttle Cable Market