
 North America Smart Transformers Market | 2026-2036
North America Smart Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Transformers Market Analytics
Utility procurement is consolidating around smart transformer platforms capable of bidirectional power flow and real-time grid communication. General Electric leverages its digital energy software stack to anchor utility-scale deployments across the United States. Siemens competes through integrated substation automation systems that extend its transformer offerings into full grid-edge solutions. Hitachi Energy Ltd dominates high-voltage direct current tie-ins where smart transformer coordination enables interstate renewable transmission.
Smart transformers are intelligent power conversion devices equipped with embedded sensors, microprocessor-based controls, and communication protocols that enable autonomous voltage regulation and load balancing across distribution networks. These units typically operate at 10 kV to 765 kV classes with efficiency ratings exceeding 99% under partial load conditions, serving primarily to stabilize grid frequency and integrate variable renewable generation. Step-down transformers lead product type revenue as distribution utilities replace aging infrastructure with digitally monitored units that reduce outage duration. IoT connectivity represents the fastest-expanding technology segment, though advanced control systems capture the deepest margin pools due to firmware customization requirements and long-term service contracts.
FERC Order 2222 and state-level public utility commission mandates in California, Texas, and New York shape demand by requiring distributed energy resource interoperability at the distribution transformer level. IEEE 1547-2018 standards and NERC CIP cybersecurity frameworks constrain product design, creating compliance barriers for equipment lacking certified communication architectures. Stakeholders must monitor evolving state implementation timelines for FERC's interconnection rules and position procurement strategies around utilities with approved grid modernization rate cases.
Market Dynamics
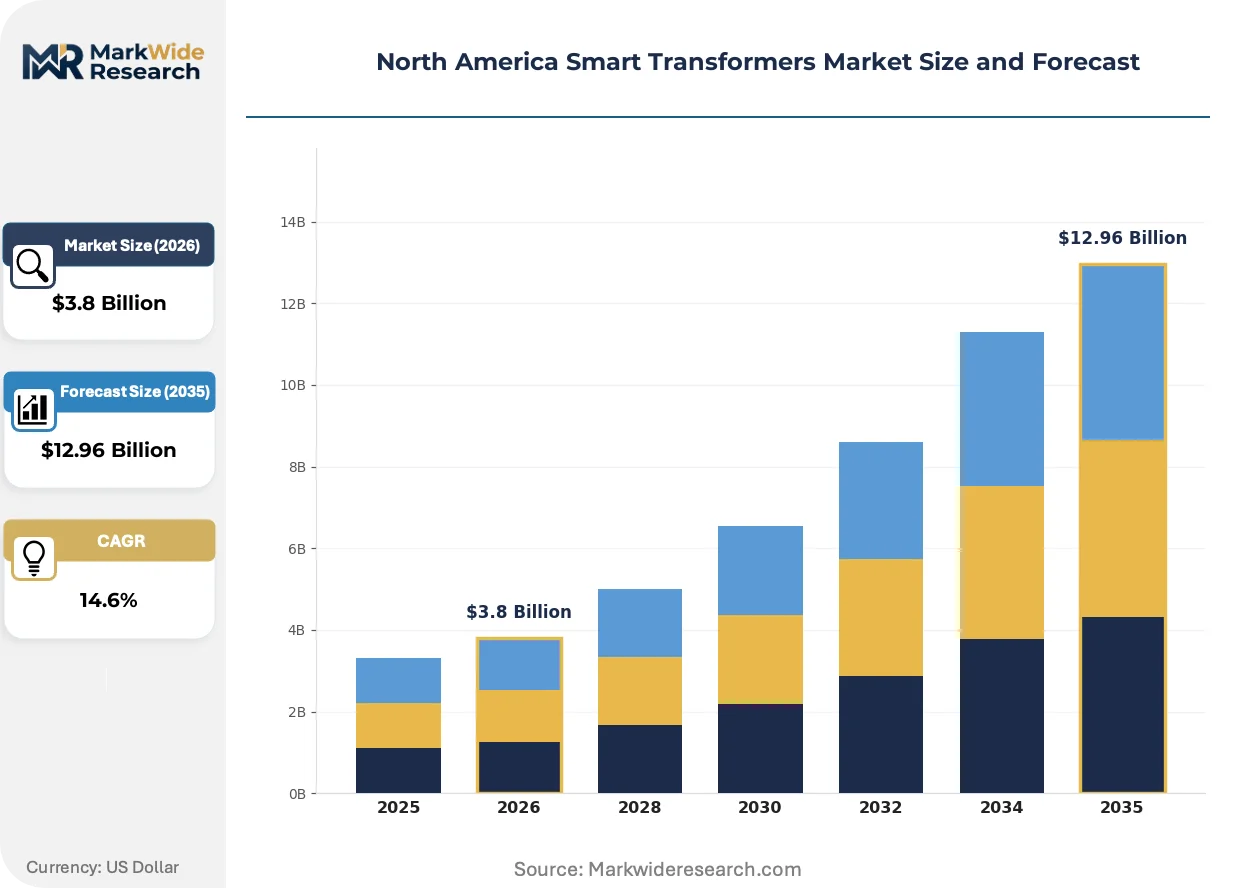
Utility-scale grid modernization across the United States and Canada is consolidating procurement around intelligent voltage management platforms capable of bidirectional power flow, forcing equipment suppliers to embed real-time communication protocols and autonomous control firmware as standard features rather than premium add-ons.
Growth Catalysts
- FERC Order 2222:This federal mandate requires distributed energy resource interoperability at the distribution transformer level, compelling utilities in Texas and California to accelerate replacement cycles of aging infrastructure with smart monitoring capabilities.
- Silicon carbide power electronics:These wide-bandgap semiconductors enable higher switching frequencies and thermal efficiency in solid-state transformer designs, reducing cooling system footprint for urban substation upgrades.
- Texas ERCOT grid instability events:Repeated winter storm failures and summer peak demand crises have triggered state-level capital allocation toward resilient transformer fleets with predictive load balancing algorithms.
Market Restraints
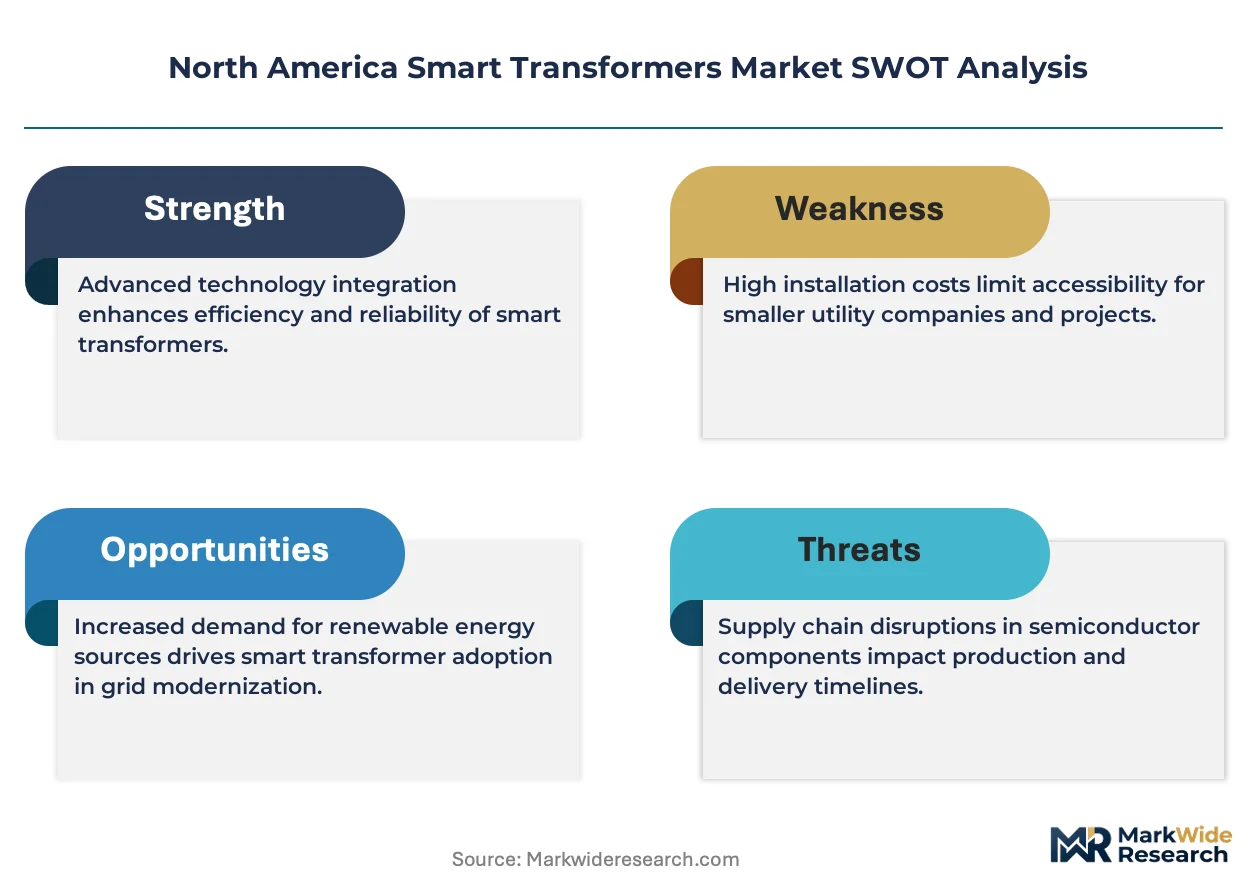
- Copper and grain-oriented electrical steel price volatility:These core raw materials constitute over 40% of manufacturing input costs, with supply concentrated among a limited number of North American and European metallurgical suppliers.
- IEEE 1547-2018 compliance complexity:The interconnection standard's cybersecurity and communication protocol requirements create certification barriers for equipment lacking pre-certified embedded architectures.
- Solid-state transformer thermal management:Current silicon carbide and gallium nitride devices face operational temperature constraints that limit deployment in high-ambient environments without auxiliary cooling systems.
Strategic Opportunities
- Ontario's net-zero electricity grid commitment:Canada's most populous province is deploying distributed energy resource integration at scale, creating demand for smart transformer coordination with provincial intertie capacity.
- Vehicle-to-grid integration:Bidirectional charging infrastructure requires distribution-level voltage regulation that conventional transformers cannot provide, opening replacement demand in California and New York metropolitan corridors.
- NERC CIP-013 supply chain security standards:These cybersecurity procurement guidelines favor domestic manufacturing and firmware transparency, creating competitive positioning advantages for North American-assembled equipment.
Industry Challenges
- Power systems engineering talent scarcity:Utilities and OEMs face acute shortages of professionals skilled in both traditional transformer design and embedded systems firmware development.
- Legacy SCADA integration complexity:Brownfield substations require protocol translation layers and hardware retrofits that extend deployment timelines and increase commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Transformers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-Up Transformers, Step-Down Transformers, Isolation Transformers, Autotransformers End User: Utilities, Industries, Renewable Energy, Commercial Enterprises Installation Type: Indoor, Outdoor, Mobile, Fixed Technology: Digital Monitoring, Communication Interfaces, IoT Connectivity, Advanced Control Systems |
| Companies Covered | General Electric, Siemens, ABB Ltd, Schneider Electric, Eaton, Hitachi Energy Ltd, Siemens Energy, Howard Industries, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Transformers Market Evolving Landscape
Digital twin modeling and edge computing architectures are fundamentally altering how utilities monitor, predict, and intervene in transformer performance, compressing maintenance cycles from scheduled intervals to condition-based triggers.
Silicon carbide-based solid-state transformers are consolidating competitive positioning in urban distribution networks where space constraints and power quality requirements favor compact, high-frequency designs. Municipal utilities in California and New York are piloting these units for data center and electric bus depot feeds. The technology is consolidating procurement criteria around thermal performance metrics and harmonic distortion specifications rather than traditional efficiency ratings alone.
FERC Order 2222 implementation timelines across individual state public utility commissions are creating fragmented compliance schedules that favor suppliers with modular firmware architectures capable of rapid reconfiguration. Texas and California have approved grid modernization rate cases that accelerate capital deployment, while New York's implementation remains pending. Equipment vendors must maintain parallel certification tracks to address this regulatory asynchrony.
Performance-based service contracting is displacing traditional equipment purchase models among large investor-owned utilities seeking to transfer operational risk to OEMs. Duke Energy and Southern California Edison have structured ten-year availability agreements that bundle hardware, software, and maintenance into single-line expenditures. This shift is most visible in renewable-rich jurisdictions where transformer loading profiles are variable and failure costs exceed capital amortization schedules.
North America Smart Transformers Market Segmentation
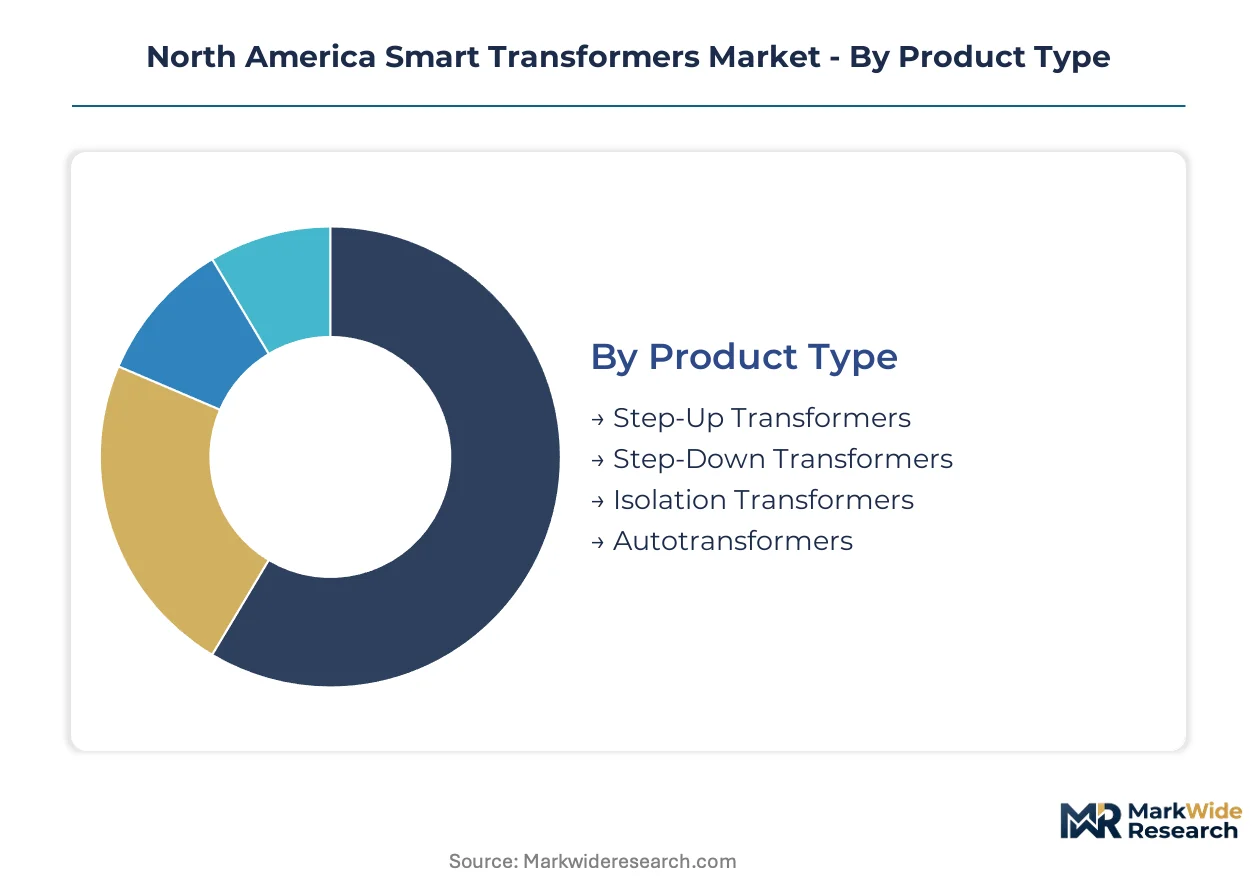
Smart transformer procurement patterns diverge sharply across voltage classes, operational environments, and control architectures. Segment-specific requirements for bidirectional power flow, cybersecurity certification, and thermal management reshape supplier R&D priorities and utility capital allocation frameworks.
Product Type:
Voltage transformation directionality determines physical construction, winding ratios, and embedded sensor placement.
- Step-Up Transformers:These units increase voltage from generator terminals to transmission levels, typically 10 kV to 765 kV classes. Renewable integration in Texas and California concentrates procurement around units with silicon carbide power electronics for variable wind and solar output smoothing.
- Step-Down Transformers:Distribution utilities deploy these to reduce transmission voltages to service levels. Aging infrastructure replacement across Ontario and New York metropolitan corridors drives demand for digitally monitored units that compress outage duration through autonomous load balancing.
- Isolation Transformers:Galvanic separation protects sensitive loads from grid transients. Data center operators in Northern Virginia and Phoenix specify these for power quality assurance.
- Autotransformers:Shared winding construction reduces copper mass and footprint. ERCOT intertie stations deploy these for voltage matching between asynchronous grid zones.
Mature deployment sits with Step-Down Transformers. Newer deployment is concentrated in Step-Up Transformers.
End User:
Customer sophistication around real-time monitoring and predictive maintenance capability varies by sector risk tolerance and regulatory exposure.
- Utilities:Investor-owned and municipal operators anchor procurement volume. FERC Order 2222 compliance timelines in Texas and California force accelerated replacement of electromechanical units with firmware-enabled voltage regulation platforms.
- Industries:Manufacturing facilities and process plants demand power quality assurance. Petrochemical complexes along the US Gulf Coast specify smart transformers with harmonic filtering to protect precision motor drives.
- Renewable Energy:Solar farms and wind parks require bidirectional-capable units. Ontario's net-zero grid commitment drives distributed energy resource integration at the distribution transformer level.
- Commercial Enterprises:Large retail and office complexes seek demand charge optimization. California commercial building codes now require transformer-level monitoring for energy disclosure compliance.
Volume leadership belongs to Utilities. Margin expansion concentrates in Renewable Energy.
Installation Type:
Environmental exposure and mobility requirements dictate enclosure ratings, cooling system design, and communication antenna placement.
- Indoor:Vault and substation-housed units prioritize fire suppression integration and reduced noise signatures. Urban utilities in New York and Chicago specify these for dense commercial districts.
- Outdoor:Pole-mounted and pad-mounted configurations dominate rural and suburban distribution. Texas utilities deploy these with hardened enclosures for extreme weather resilience following winter storm failures.
- Mobile:Trailer-mounted substations enable rapid deployment for emergency restoration and construction power. California wildfire response protocols pre-position these units in high-risk corridors.
- Fixed:Permanent installations anchor grid infrastructure planning. ERCOT's transmission expansion plans rely on these for interstate renewable capacity tie-ins.
Fixed installations carry the deepest installed base. Mobile units are climbing the fastest as climate resilience budgets expand.
Technology:
Intelligence depth—from passive monitoring to autonomous control—separates premium positioning from commodity substitution risk.
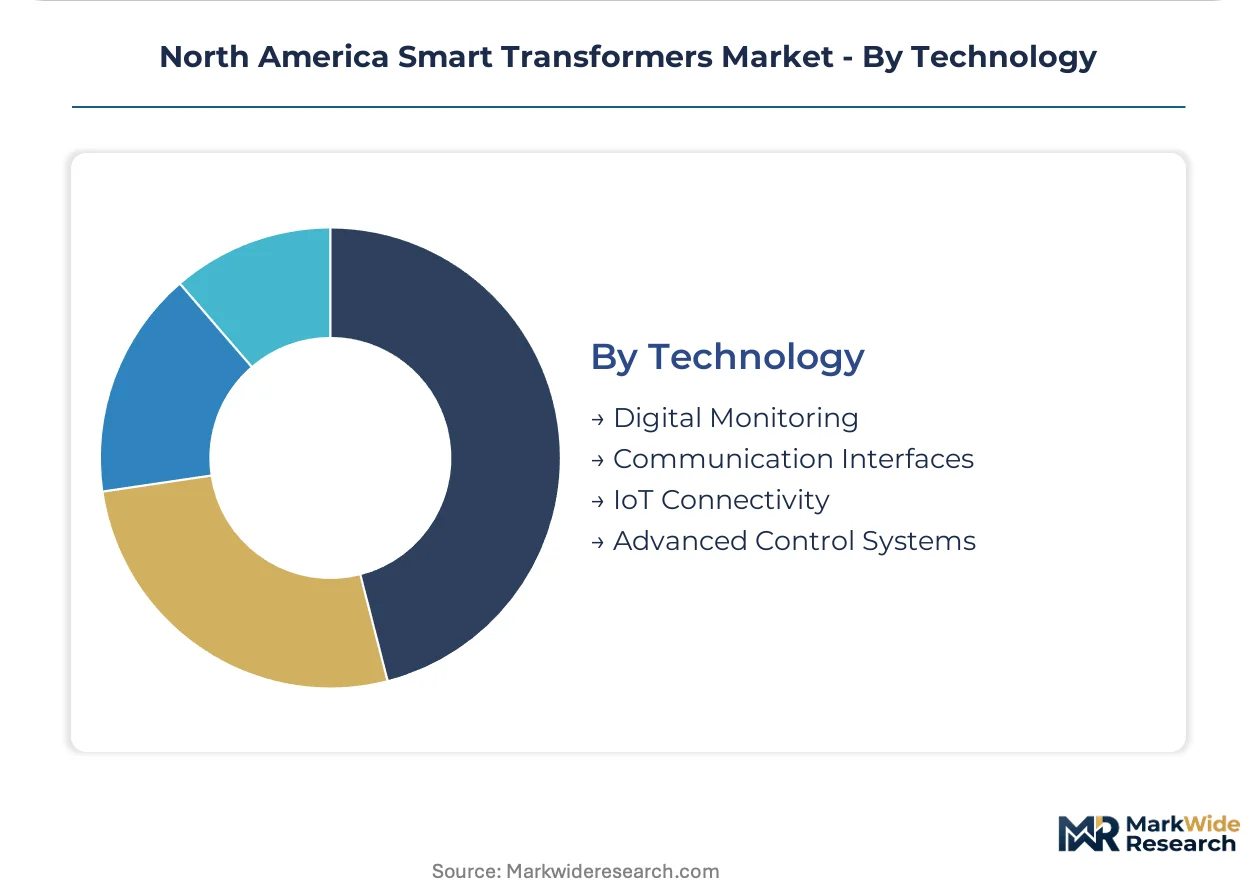
- Digital Monitoring:Embedded sensors track temperature, load current, and dissolved gas analysis. IEEE 1547-2018 mandates drive baseline adoption across all utility-scale deployments.
- Communication Interfaces:Protocol gateways enable SCADA integration and remote firmware updates. NERC CIP cybersecurity frameworks constrain product design to certified architectures.
- IoT Connectivity:Cloud-linked telemetry enables fleet-wide analytics and predictive maintenance. California investor-owned utilities pilot these for transformer health scoring across thousands of units.
- Advanced Control Systems:Autonomous voltage regulation and load balancing firmware capture the deepest margin pools. Long-term service contracts and customization requirements lock in supplier relationships.
Digital Monitoring represents baseline capability. Advanced Control Systems command premium positioning through firmware differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Opportunity Zones and California Clean Energy Zones concentrate smart transformer deployment through accelerated depreciation and interconnection queue fast-tracking. Federal IRA manufacturing credits anchor domestic production decisions. State-level grid modernization rate cases in Ontario and New York reshape procurement timelines.
United States
Texas ERCOT instability events and California wildfire resilience mandates drive replacement demand. FERC Order 2222 implementation varies by state public utility commission. Houston-Galveston and Los Angeles-Long Beach anchor manufacturing and deployment clusters for utility-scale projects.
Canada
Ontario's net-zero electricity commitment requires distributed energy resource integration at scale. The province's independent electricity system operator mandates smart inverter functionality. Toronto-Ottawa corridor utilities deploy coordinated voltage regulation platforms for provincial intertie capacity.
Mexico
Industrial corridor electrification in Nuevo León and Baja California drives demand for power quality assurance. Comisión Federal de Electricidad transmission expansion plans incorporate digital monitoring specifications. Monterrey manufacturing clusters specify smart transformers for precision motor drive protection.
North America Smart Transformers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy conglomerates anchoring utility-scale procurement and regional fabricators capturing industrial retrofit opportunities. The market structure tilts toward consolidated procurement at the transmission level and fragmented competition in distribution equipment. Three archetypes dominate: full-grid solution providers, component-specialist OEMs, and digital-native control system vendors. Strategic moves concentrate on firmware differentiation through long-term service contracting and silicon carbide supply chain partnerships for solid-state transformer thermal management.
Among diversified industrial conglomerates, General Electric and Siemens exemplify full-grid solution positioning through integrated software-hardware bundles. Hitachi Energy Ltd occupies a specialized tier in high-voltage direct current applications where transformer coordination enables interstate renewable transmission. These three companies anchor competitive dynamics through divergent R&D emphases—digital energy platforms, substation automation systems, and HVDC tie-in architectures respectively.
| Leading Market Players |
|---|
| General Electric |
| Siemens |
| ABB Ltd |
| Schneider Electric |
| Eaton |
| Hitachi Energy Ltd |
| Siemens Energy |
| Howard Industries |
| GE Vernova |
| Others |
Value Network & Pricing Analysis
Copper and grain-oriented electrical steel price volatility cascades through transformer manufacturing tiers, compressing margins on standard-efficiency units while silicon carbide-enabled solid-state designs command premium positioning through thermal performance differentiation.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency replacement orders from planned procurement cycles, with utilities paying substantial premiums for units deliverable within compressed windows versus standard-schedule deployments. Three-tier pricing structure across premium solid-state, standard intelligent monitoring, and economy electromechanical levels reflects certification grade and firmware customization depth. Pricing pressure stems from raw material cost compression in the standard tier, where Asian component sourcing competes with domestic assembly. Investor-owned utilities exhibit lowest price sensitivity due to rate-case recovery mechanisms, while municipal operators face acute budget constraints.
Supply Chain Analysis
Dual-sourcing qualification requirements mandated by NERC CIP-013 standards compel utilities to validate alternative suppliers for critical components, fragmenting procurement across qualified vendors. Manufacturing concentrates in the United States, Mexico, and Germany for final assembly, with core winding materials drawing from Japan and Sweden. Silicon carbide substrates, copper windings, and embedded sensor modules constitute critical input dependencies. Single-source vulnerability in wide-bandgap semiconductor supply creates exposure to allocation constraints. Distribution runs through utility-direct contracting and EPC channel partnerships for large-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart transformer procurement consolidation favors integrated platform providers, with IEEE 1547-2018 compliance complexity forcing smaller electromechanical specialists toward exit or acquisition.
For Market Incumbents: Hedge against silicon carbide supply disruption through long-term offtake agreements with substrate manufacturers or backward integration into power module packaging. Capture recurring revenue through ten-year availability contracts that bundle firmware updates and predictive maintenance, transferring operational risk from utilities while locking out component-only competitors. Reinforce positioning by embedding NERC CIP-certified communication architectures as standard rather than optional features. For New Entrants and Emerging Players: Launch via mobile substation rental models targeting California wildfire resilience budgets and Texas emergency response protocols, where asset-light deployment bypasses utility capital approval cycles. Target industrial microgrid segments in Mexico's Nuevo León manufacturing corridor, where power quality requirements outstrip local supplier capabilities. Pursue white-label firmware development partnerships with established transformer fabricators lacking embedded systems competency. For Investors and Strategic Acquirers: FERC Order 2222 state implementation timeline acceleration is the leading indicator that procurement volume will concentrate among vendors with pre-certified modular architectures. Over the medium-term horizon, acquisition targets should feature dual competency in traditional transformer winding and edge computing firmware development, with installed base relationships at municipal utilities. Monitor California Public Utilities Commission rate case approvals as the signal for capital deployment velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Transformer Scale-Up | Silicon carbide thermal management advances enable compact urban substation deployments in California and New York corridors. |
| Long-Term Service Contracting | Duke Energy and Southern California Edison availability agreements transfer operational risk to OEMs through bundled hardware-software-maintenance structures. |
| Domestic Manufacturing Footprint | IRA production credits and NERC CIP-013 supply chain security standards favor North American assembly for utility-scale procurement. |
| Firmware Modularization | Rapid reconfiguration capabilities address fragmented FERC Order 2222 implementation timelines across state public utility commissions. |
| Digital Twin Platform Integration | Edge computing architectures compress maintenance cycles from scheduled intervals to condition-based triggers for predictive intervention. |
Research Methodology
Multi-period observation of utility capital expenditure cycles, grid modernization rate case approvals, and distributed energy resource interconnection queues anchored the trend analysis, supplemented by interviews with utility planning officers, transformer OEM product managers, EPC contractors, and grid operators. Secondary validation drew from FERC filings, EIA electricity infrastructure data, state public utility commission dockets, and IEEE standards documentation. Bottom-up unit deployment modeling triangulated against top-down market sizing across voltage class and technology segments.
Input-output matrices mapped silicon carbide substrate supply constraints, copper price trajectories, and utility procurement lead times against deployment forecasts across the projection horizon. Segmentation dimensions modeled include voltage transformation directionality, end-user sophistication tier, installation environment exposure, and control system intelligence depth. CAGRs were derived from regression analysis of historical replacement cycles overlaid with regulatory mandate acceleration effects. Forecast inputs incorporated ERCOT grid instability event frequency and California wildfire resilience budget allocations.
The model assumes a particular technology adoption path for silicon carbide power electronics; alternative pathways for gallium nitride or hybrid electromechanical designs would alter the outlook for solid-state transformer penetration rates. Forecasts reflect documented assumptions regarding FERC Order 2222 implementation velocity and raw material price stabilization. Deviation in state public utility commission approval timelines or wide-bandgap semiconductor supply allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Green Transformer Market
Transformers
Traction Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
United States Distribution Transformer Market
Transformers
Middle East and Africa Transformer Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Green Power Transformers Market
Transformers
Middle East Distribution Transformer Market
Transformers
Europe Telecom Transformers Market
Transformers
North America Power Transformer Market
Transformers
Power Transformer Market
Transformers
Transformer Oil Market
Transformers
Locomotive Traction Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Transformer Core Market
Transformers
Three Phase Transformer Market