
 Base Oil Market | 2026-2036
Base Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Base Oil Market Intelligence
The transition toward higher-purity Group II and Group III base oils is reorganizing the competitive landscape. This fundamental shift favors large-scale refiners with advanced hydrocracking and isomerization capabilities. Shell Global leverages its extensive global refining infrastructure to produce these higher-grade oils. Meanwhile, PetroChina and SINOPEC dominate supply within Asia, controlling significant domestic production capacity.
Base oil is the refined petroleum or synthetic fluid constituting the majority volume of a finished lubricant. These oils are categorized by the American Petroleum Institute (API) into groups based on sulfur content, saturates, and viscosity index. While Group I oils serve less demanding applications, Group II and Group III products command the engine oils segment due to superior thermal stability. Hydraulic fluids and gear oils also specify higher-grade base stocks to meet extended drain intervals.
Regulatory frameworks directly influence base oil specifications and market access. The US Environmental Protection Agency (EPA) mandates for lower vehicle emissions push lubricant formulators toward cleaner base stocks. In parallel, Europe's REACH regulation and China's GB standards for fuel economy impact formulation choices. Refiners must balance investment in higher-group capacity against the long-term viability of internal combustion engine technologies.

Market Dynamics
The fundamental reorganization of the base oil market stems from the industry-wide migration from Group I to higher-purity Group II and Group III stocks. This technological schism creates a divided market, favoring refiners with advanced hydroprocessing capacity.
Growth Catalysts
- Automotive Emission Standards:Regulations like the US EPA's Tier 3 standards and Europe's Euro norms compel the use of higher-grade base oils in engine lubricants to improve fuel economy and reduce tailpipe emissions.
- Industrial Machinery Demand:The machinery manufacturing sector, especially in industrial hubs across China and India, requires higher-performance lubricants to support equipment efficiency and extend service intervals, driving demand for Group II and III oils.
- Refining Technology Proliferation:Advancements in hydrocracking and catalytic isomerization processes are making the production of high-viscosity-index Group II and III base oils more economically viable for a broader set of refiners.
Market Restraints
- Capital Expenditure Intensity:The construction of new or conversion of existing refineries to produce Group II and Group III base oils requires substantial capital investment, creating a high barrier to entry for smaller players.
- Crude Oil Price Volatility:As the primary feedstock, fluctuations in global crude oil prices directly impact the production costs and margin stability for base oil refiners, creating significant financial risk.
- Electric Vehicle Adoption:The long-term global transition to electric vehicles directly threatens demand for engine oils, which constitute a primary end-market for higher-grade base oils, particularly in passenger cars.
Strategic Opportunities
- Bio-based Lubricants:The development and commercialization of bio-based and ester-based lubricant feedstocks present an opportunity to serve niche markets focused on sustainability and biodegradability, especially in environmentally sensitive applications.
- Re-Refined Base Oils:Growing regulatory and corporate focus on circular economy principles creates a market for high-quality re-refined base oils, particularly where government procurement mandates or sustainability targets exist.
- Emerging Industrial Markets:Untapped demand in rapidly industrializing economies in Southeast Asia and Latin America provides growth opportunities as these regions upgrade their lubricant quality and performance standards.
Industry Challenges
- Specification Divergence:Refiners face complexity in meeting a fragmented landscape of regional specifications, such as Europe's REACH framework and China's distinct GB standards, which can require tailored production runs.
- Supply Chain Logistics:Managing the segregated storage and transportation required to maintain the purity of different base oil groups adds significant logistical complexity and cost compared to handling a single-grade product.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Base Oil Market |
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $48.26 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Group I, Group II, Group III, Synthetic Application: Engine Oils, Gear Oils, Hydraulic Fluids, Metal Working Fluids End User Industry: Machinery Manufacturing, Marine Equipment, Construction Equipment, Agricultural Equipment Packaging Type: Drums, Totes, Bulk Tankers, Intermediate Bulk Containers |
| Companies Covered | PetroChina, ConocoPhillips, Chevron Corporation, TotalEnergies, Shell Global, Exxon Mobil Corporation, Saudi Arabian Oil Company (Saudi Aramco), BP, China Petrochemical Corporation (SINOPEC), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Base Oil Market Strategic Shifts & Innovations
Product innovation is driven by the twin objectives of meeting stringent emissions regulations and satisfying industrial demands for longer-lasting, more efficient lubricants. This pushes development toward synthetic and severely hydrotreated base stocks with superior performance characteristics.
Gas-to-liquids (GTL) technology enables the production of exceptionally pure synthetic base oils with a high viscosity index and near-zero sulfur. Premium automotive and specialized industrial lubricant formulators are the primary adopters, seeking ultimate performance. The superior quality of GTL base oil is decomposing the traditional price-performance hierarchy, establishing a new ultra-premium tier above conventional Group III products.
Regulatory frameworks like Europe's REACH are forcing a re-evaluation of lubricant formulations. The regulation's strict requirements for chemical substance registration increase compliance costs and development timelines for new additive packages. The engine oil segment is most affected, leading to a preference for base stocks that are inherently cleaner and require less complex additive chemistry to meet performance and environmental mandates.
End-user procurement behavior is evolving from simple transactional purchases toward total fluid management programs. This shift disrupts the traditional role of distributors, favoring suppliers capable of providing integrated services like oil analysis, condition monitoring, and end-of-life recycling. This service-centric model is gaining significant traction within the power generation and heavy manufacturing sectors across North America and Europe.
Base Oil Market Segmentation
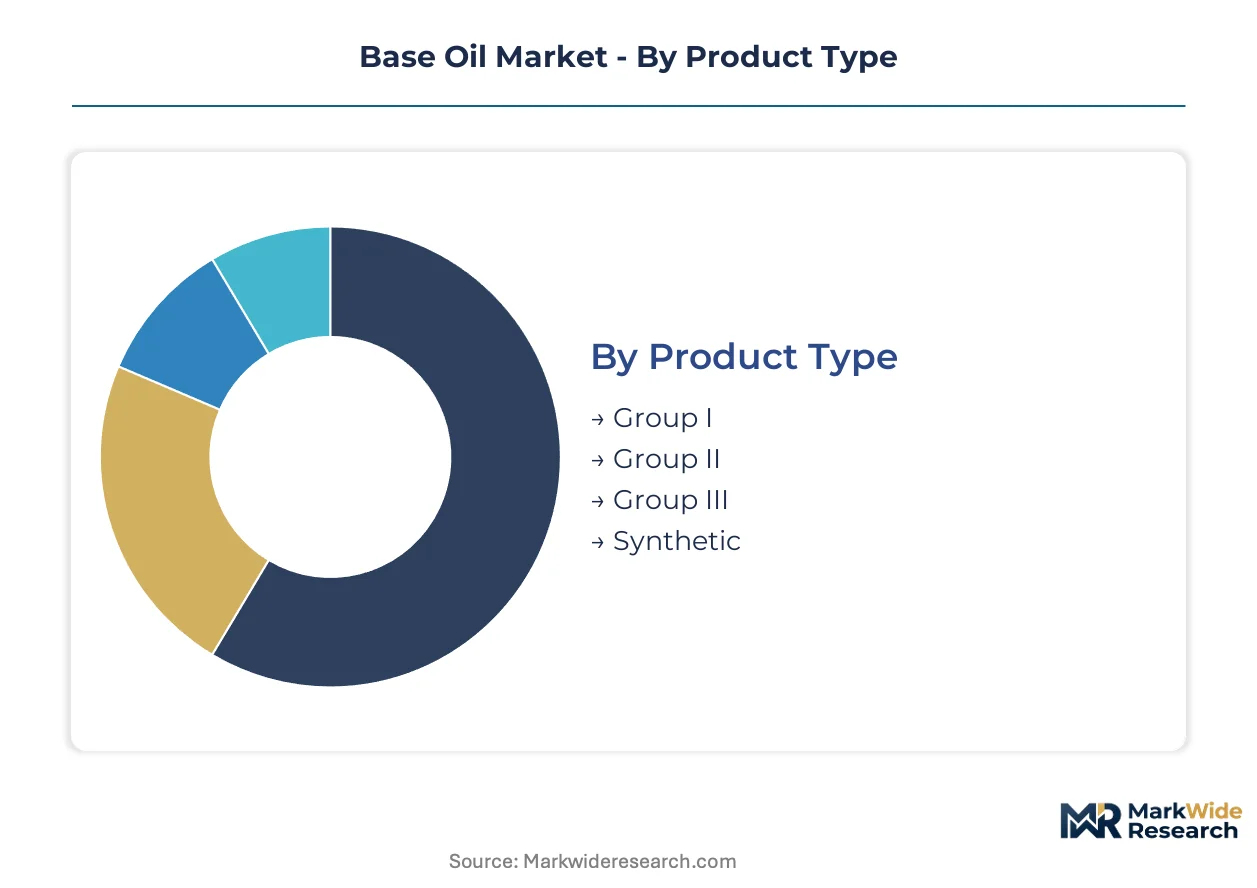
The base oil market segmentation is crucial for understanding the diverse applications and performance requirements that drive product development and distribution strategies. Analyzing these segments helps refiners align production capabilities with specific market demands, ensuring optimal product purity and logistical efficiency for various end-use sectors.
Product Type:
The base oil market channels distinct product types through specialized supply chains, reflecting their varying performance characteristics and end-user requirements.
- Group II:These severely hydrotreated base oils feature low sulfur content and high saturate levels, providing superior oxidation stability and thermal performance. Demand concentrates in the engine oils and industrial machinery sectors across China and India, driven by stringent emission standards and requirements for extended drain intervals.
- Synthetic:Chemically synthesized base oils offer exceptional purity, a very high viscosity index, and near-zero sulfur, enabling superior performance under extreme operating conditions. Premium automotive lubricants and specialized industrial applications are the primary demand centers, leveraging GTL technology for ultimate performance.
- Group I:Solvent-refined base oils contain higher sulfur and aromatic content, making them suitable for less demanding applications where cost-effectiveness is a primary concern.
- Group III:Severely hydrocracked and isomerized base oils provide a very high viscosity index and low volatility, essential for premium engine oils and high-performance hydraulic fluids.
By volume, Group I base oils still lead the market, while Synthetic products are ahead in terms of growth pace due to their performance advantages.
Application:
Base oil applications are defined by their functional roles within mechanical systems, dictating specific formulation needs and performance characteristics.
- Engine Oils:These lubricants reduce friction and wear in internal combustion engines, also providing cooling and cleaning functions. Demand is significant across the global automotive sector, including passenger cars and commercial vehicles, driven by tightening US EPA and Europe's Euro emission regulations and fuel economy mandates.
- Hydraulic Fluids:Used to transmit power in hydraulic systems, these fluids also provide lubrication, heat transfer, and contamination control. Construction equipment and heavy industrial machinery represent major demand segments, requiring higher-grade base stocks for extended drain intervals and equipment efficiency.
- Gear Oils:Formulated to lubricate gears, bearings, and other components in transmissions and gearboxes, protecting against wear, corrosion, and pitting.
- Metal Working Fluids:These fluids cool and lubricate during machining operations like cutting, grinding, and forming, preventing tool wear and ensuring surface finish.
Engine Oils command the largest share of base oil consumption, while Hydraulic Fluids exhibit strong expansion driven by industrial modernization.
End User Industry:
Demand concentration within end-user industries reflects the specific operational environments and performance requirements for lubricants.
- Machinery Manufacturing:This sector produces a wide array of industrial and consumer machinery, requiring high-performance lubricants for assembly and operational longevity. Demand is particularly strong in major industrial centers across China and India, driven by the need for higher-efficiency lubricants for complex equipment.
- Construction Equipment:Heavy machinery like excavators, loaders, and cranes used in infrastructure projects and mining operations demand robust lubricants. These applications require base oils capable of performing under harsh operating conditions and supporting extended maintenance cycles.
- Marine Equipment:This segment encompasses engines, gearboxes, and hydraulic systems found on commercial vessels, offshore platforms, and recreational boats.
- Agricultural Equipment:Tractors, harvesvesters, and other farm machinery rely on specialized lubricants to operate efficiently in diverse environmental conditions.
Machinery Manufacturing represents a foundational demand segment for base oils, with Construction Equipment showing consistent growth due to global infrastructure development.
Packaging Type:
Packaging types for base oils are determined by volume requirements, logistical considerations, and the scale of the end-user or blending operation.
- Bulk Tankers:Large-volume transportation of base oils in specialized road or rail tankers, facilitating direct supply from refineries to large industrial lubricant blenders. This method offers significant cost efficiencies for high-volume transfers between major facilities.
- Drums:Standard 200-liter containers used for distributing base oils to smaller industrial users, regional distributors, and lubricant blenders requiring manageable unit sizes. Drums offer flexibility and ease of handling for diverse customer bases.
- Totes:Intermediate-sized containers, typically ranging from 1,000 to 1,250 liters, providing a balance between bulk efficiency and individual handling convenience.
- Intermediate Bulk Containers:Reusable, multi-trip containers, often 1,000 liters, designed for the efficient storage and transport of liquids and bulk materials.
Bulk Tankers facilitate large-scale industrial supply, while Drums serve a broader range of smaller-volume customers and regional distribution networks.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global base oil market exhibits varied export-import dynamics, with major producing regions balancing domestic demand against international supply opportunities. Countries with significant refining capacity often become net exporters, influencing global pricing and availability. Conversely, regions lacking sufficient production capacity rely on imports to meet their industrial and automotive lubricant needs.
United States
Stringent US EPA Tier 3 emission standards drive demand for higher-grade base oils in automotive lubricants. The Inflation Reduction Act (IRA) also incentivizes domestic production and cleaner industrial processes. Manufacturing hubs in Texas and Louisiana concentrate significant refining capacity for Group II and Group III base oils.
China
Industrial machinery demand in China's Yangtze River Delta region fuels substantial consumption of Group II and Group III base oils. China's GB standards for fuel economy increasingly mandate cleaner lubricant formulations. Major industrial cities like Shanghai and Guangzhou are key centers for lubricant blending and consumption.
India
Rapid industrialization across India's Gujarat and Maharashtra states creates strong demand for high-performance lubricants in manufacturing. The Indian government's PLI scheme encourages domestic production of advanced materials, including base oils. Automotive and industrial clusters around Pune and Chennai are significant consumers.
Germany
Europe's Euro emission norms compel the use of advanced base oils in engine lubricants across Germany's automotive sector. REACH regulation influences the formulation choices for all lubricant manufacturers. The Rhine-Ruhr area remains a core industrial region for lubricant production and application.
Japan
Japan's automotive industry requires high-quality base oils to meet stringent domestic fuel efficiency standards. METI policies support the development of advanced chemical processes, including those for synthetic base oil production. The Kanto region, including Tokyo, serves as a major hub for lubricant research and manufacturing.
Base Oil Market Key Industry Players
Concentration sits with vertically integrated major oil and gas companies possessing extensive refining capabilities. The base oil market exhibits a tiered structure, with a few global giants dominating high-grade production and numerous smaller blenders serving regional demands. Strategic archetypes include large-scale refiners, specialized synthetic producers, and regional blenders. Capacity expansion and strategic partnerships are dominant competitive moves among the larger players.
At the scale-driven end, companies like Shell Global and Exxon Mobil Corporation exemplify integrated major oil companies that leverage their global refining infrastructure. These multinational energy giants maintain substantial market presence through their extensive production capacities and global distribution networks. PetroChina and SINOPEC, both state-owned enterprises, represent the significant domestic production capacity concentrated within Asia, particularly China. These entities anchor the supply of both conventional and higher-grade base oils, often controlling vast portions of their respective national markets.
| Leading Market Players |
|---|
| PetroChina |
| ConocoPhillips |
| Chevron Corporation |
| TotalEnergies |
| Shell Global |
| Exxon Mobil Corporation |
| Saudi Arabian Oil Company (Saudi Aramco) |
| BP |
| China Petrochemical Corporation (SINOPEC) |
| Others |
Cost & Logistics Intelligence
Weeks of inventory for Group I base oils often dictate spot market pricing power, while the complex supply chain for higher-grade Group II and Group III products commands premium pricing due to specialized refining capabilities.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for high-performance base oils. Price differentiation stems from the specific API quality grade and the inclusion of after-sales technical service. Cost compression in less demanding Group I applications stems from regional oversupply. Buyers of Group I base oils exhibit the highest price sensitivity, while formulators requiring synthetic base oils show the least.
Supply Chain Analysis
China and India anchor significant domestic production of Group II and Group III base oils, alongside refining hubs in the United States. The supply chain relies heavily on crude oil as the primary feedstock, with natural gas also critical for Gas-to-Liquids (GTL) synthetic production. Crude oil price volatility represents a significant structural supply chain risk. Distribution runs through bulk tankers for large industrial lubricant blenders.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The base oil market presents a fragmentation opportunity, as evolving regulatory frameworks create distinct niches for specialized lubricant formulations.
For Market Incumbents:Secure advanced hydrocracking and isomerization capacity to maintain leadership in Group II and Group III base oil production. Diversify product portfolios with bio-based lubricant feedstocks to mitigate the long-term threat of electric vehicle adoption. Invest in R&D for next-generation synthetic base oils that require less complex additive chemistry. Expand global distribution networks to support emerging industrial markets.
For New Entrants and Emerging Players:Lead with specialized bio-based lubricant offerings targeting environmentally sensitive industrial applications. The most penetrable segment remains niche industrial sectors in rapidly industrializing economies like Southeast Asia. Focus on developing ester-based alternatives that meet stringent biodegradability and toxicity requirements. A strong go-to-market angle involves sustainability certifications and performance guarantees.
For Investors and Strategic Acquirers:Long-term, this sits as a technology-driven consolidation play because high capital expenditure favors large, integrated refiners with advanced processing capabilities. Target mid-sized refiners with underutilized Group II/III capacity or specialized synthetic base oil producers with proprietary GTL technology. The pace of electric vehicle adoption in commercial fleets serves as a critical signal to watch for long-term demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion (Group II/III) | Increased production meets demand from automotive and industrial sectors in Asia. |
| Bio-based Lubricant R&D | Develops sustainable alternatives for environmentally sensitive applications and regulatory compliance. |
| Digitalization of Logistics | Enhances supply chain efficiency and purity maintenance for diverse base oil groups. |
| Strategic Partnerships with OEMs | Facilitates co-development of specialized lubricants for advanced machinery and engines. |
| Circular Economy Investment | Develops re-refining technologies to create high-quality base oils from used lubricants. |
Research Approach
Initial hypotheses were tested against primary input from refinery operations managers, lubricant blenders, and automotive OEM engineers, then refined through iterative discussions. Secondary validation utilized API specifications, US EPA reports, China GB standards, and company annual reports. This approach ensured robust bottom-up market sizing and top-down validation.
Variance decomposition across the modeling period informed the analytical framework, disaggregating growth drivers by product type, application, end-user industry, and regional regulatory impact. Compound annual growth rates were derived from historical data trend analysis and projected demand shifts. Forecast inputs included crude oil price projections and global vehicle production forecasts.
Forecasts assume regulatory continuity in US EPA and Europe's REACH frameworks; material policy shifts would require re-modeling market dynamics. Geopolitical instability impacting crude oil supply or accelerated EV adoption represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
India White Oil Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Oil Shale Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Uganda Petroleum Products Market