
 United States Large Power Transformer Market | 2026-2036
United States Large Power Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Large Power Transformer Market Analytics
Single-source dependency on foreign core steel is decoupling from utility procurement protocols as domestic supply chain resilience becomes a priority. Hitachi Energy leverages its U.S. manufacturing footprint to anchor utility relationships. Siemens Energy competes through specialized high-voltage direct current capabilities. General Electric Company sustains market presence with integrated transformer and grid automation portfolios.
Large power transformers are electromagnetic devices rated above 100 MVA that transfer electrical energy between circuits through magnetic induction, typically operating at voltages from 69 kV to 765 kV for bulk power transmission and grid interconnection. Core construction uses grain-oriented electrical steel laminated to reduce eddy current losses, while windings employ copper or aluminum conductors insulated with oil-impregnated paper. Three-phase designs dominate utility-scale deployment due to superior power density and footprint efficiency compared to single-phase alternatives. Smart grid technology segments attract premium positioning as utilities deploy monitoring-enabled transformers for real-time thermal and load diagnostics. Liquid-filled units occupy the mainstream commercial channel given proven cooling performance and service infrastructure maturity.
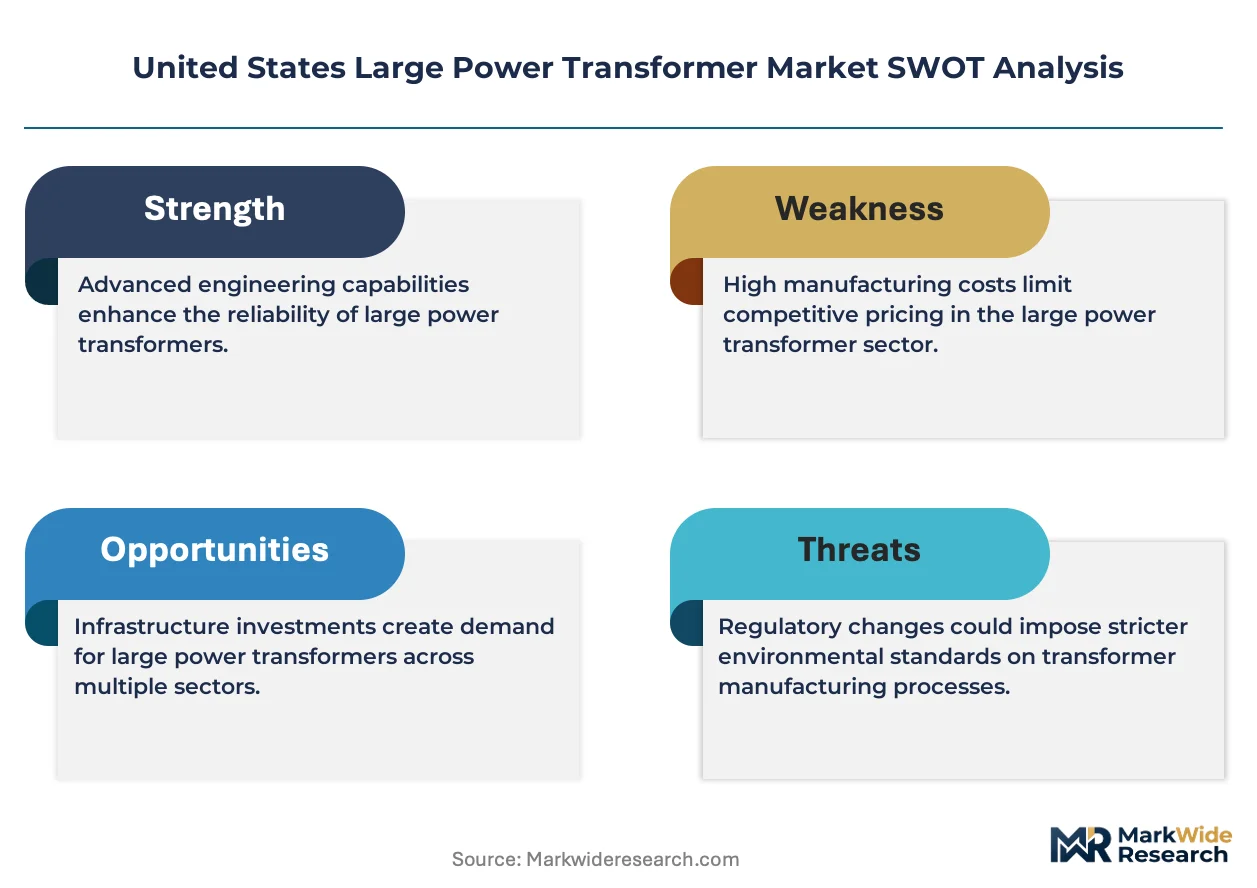
FERC Order 2023 and NERC reliability standards shape grid interconnection timelines and transformer specification requirements, while EPA regulations on PCB contamination drive replacement cycles in aging installations. Domestic content provisions under federal procurement rules restrict foreign-sourced components in federally funded projects. Stakeholders must monitor evolving Buy America thresholds and transformer lead time dynamics to align capital planning with supply availability.
Market Dynamics
The Infrastructure Investment and Jobs Act is redirecting federal capital toward domestic transformer manufacturing capacity, creating a structural pull on utility procurement protocols while grain-oriented electrical steel supply chains remain concentrated outside U.S. borders.
Growth Catalysts
- Grid Modernization Mandates:FERC Order 2023 accelerates interconnection queue processing for renewable projects, forcing utilities to procure higher-capacity units for transmission upgrades.
- Domestic Content Incentives:Buy America provisions in federally funded infrastructure projects restrict foreign-sourced core components, redirecting procurement toward U.S.-based manufacturing.
- Texas and California Load Centers:Renewable energy concentration in these states strains existing transformer infrastructure, driving replacement and expansion cycles.
Market Restraints
- Grain-Oriented Electrical Steel Concentration:Core lamination material remains dependent on limited foreign suppliers, exposing lead times to geopolitical disruption.
- EPA PCB Regulations:Contamination remediation requirements for aging installations compress replacement budgets without expanding total market volume.
- Specialized Winding Labor Scarcity:Copper and aluminum conductor insulation expertise resides in a shrinking workforce pool, constraining production scaling.
Strategic Opportunities
- PJM Interconnection Region:Queue congestion in this mid-Atlantic transmission territory creates demand for higher-voltage intertie transformers.
- Smart Grid Sensor Integration:Real-time thermal monitoring and load diagnostics represent attach-rate expansion for transformer OEMs.
- High-Voltage Direct Current Retrofit:Existing AC corridors offer conversion potential for long-distance renewable transmission from remote generation sites.
Industry Challenges
- Transformer Testing Certification:NERC reliability standards impose extended validation timelines that mismatch utility emergency procurement needs.
- Legacy Oil-Filled Unit Integration:New monitoring-enabled designs must interface with decades-old substation control systems without full infrastructure replacement.
- Domestic Foundry Capacity:Tank and radiator fabrication requires steel casting investment that lags transformer assembly demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Large Power Transformer Market |
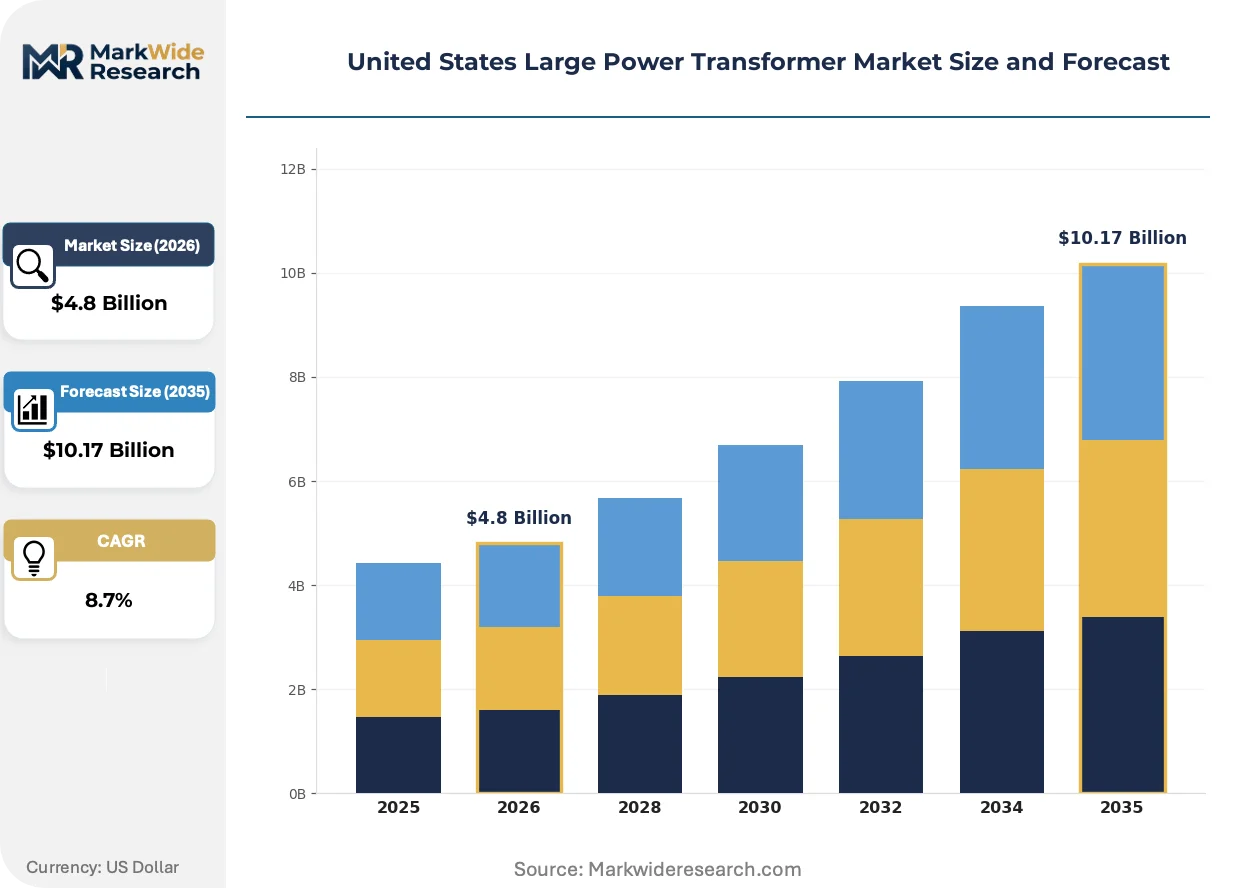
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Autotransformer, Instrument Transformer End User: Utility Companies, Industrial Sector, Renewable Energy, Commercial Sector Installation Type: Onshore, Offshore, Stationary, Mobile Technology: Conventional, Smart Grid, High-Efficiency, Liquid-Filled |
| Companies Covered | ABB Ltd, Schneider Electric, Hitachi Energy, SPX Transformer Solutions, HD Hyundai Electric, General Electric Company, Mitsubishi Electric Corporation, Toshiba Energy Systems & Solutions Corporation, Siemens Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Large Power Transformer Market Evolving Landscape
Digital instrumentation is penetrating transformer enclosures, converting passive electromagnetic hardware into grid-edge sensor platforms that feed real-time operational data to utility control centers.
Amorphous metal core technology is expanding into distribution-class transformer segments where loss reduction justifies material cost premiums. Rural electric cooperatives in the Midwest are piloting these units for peak-load efficiency gains. The technology is expanding into utility-scale procurement specifications as grain-oriented steel price volatility makes alternative core materials economically viable.
The EPA's updated PCB handling regulations now require comprehensive contamination assessment before any transformer removal or retrofit. Utilities must budget remediation costs alongside replacement capital, compressing project timelines. PJM member companies are responding by accelerating pre-emptive replacement schedules for pre-1979 installations.
Long-term service agreements are displacing transactional maintenance contracts as utilities seek to transfer asset-performance risk to OEMs. This model transfers diagnostic responsibility and spare inventory holding to manufacturers. Texas municipal utilities are leading this shift, bundling transformer supply with fifteen-year thermal monitoring and emergency replacement guarantees.
United States Large Power Transformer Market Segmentation
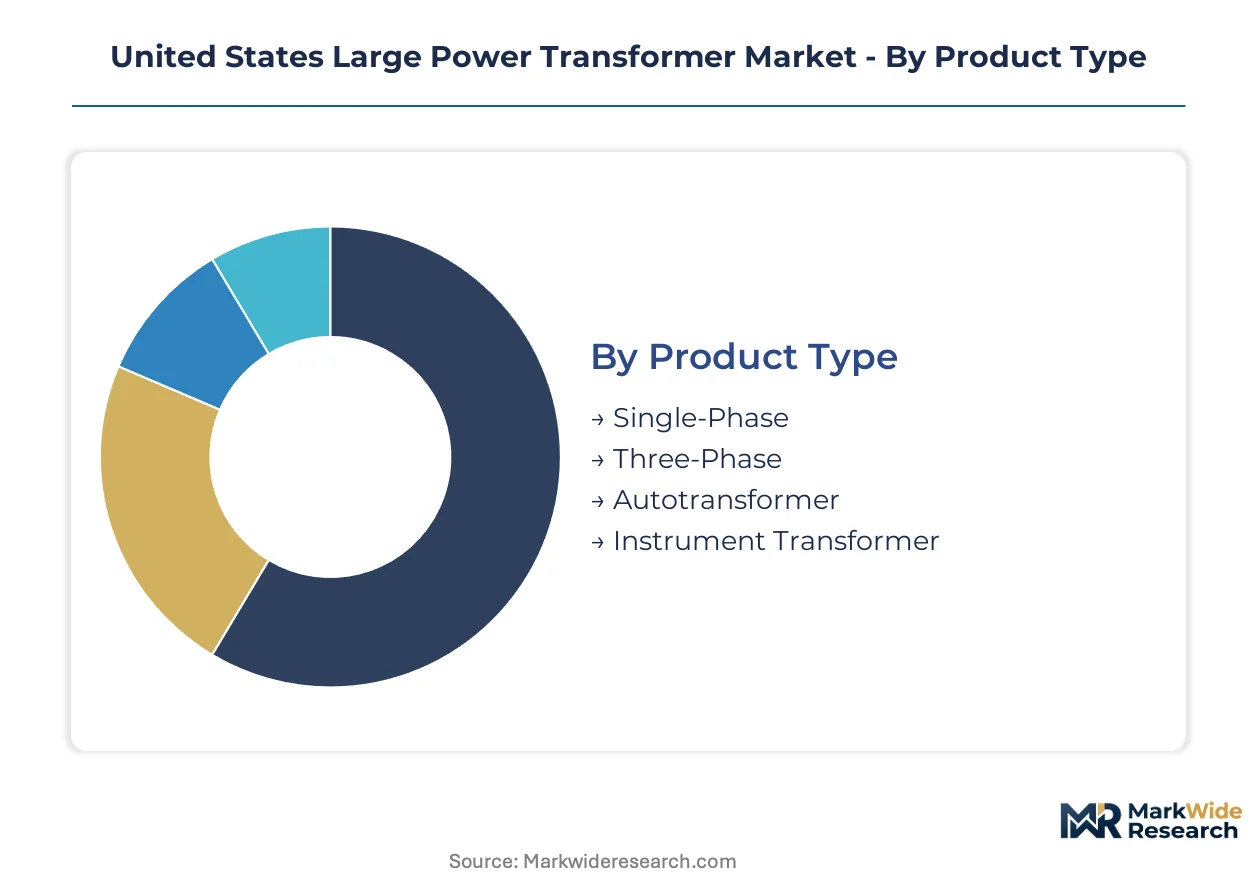
Large power transformer procurement patterns diverge sharply across installation environments and operational technologies, with FERC interconnection standards and NERC reliability certifications creating tiered compliance burdens that reshape supplier qualification requirements.
Product Type:
NERC CIP-014 physical security standards and IEEE C57 test protocols impose differentiated certification timelines across core construction formats, with three-phase designs facing accelerated validation due to their dominance in bulk transmission infrastructure.
- Three-Phase:Core-and-coil assemblies transfer bulk power across three energized conductors simultaneously, achieving superior power density per unit footprint. Utility procurement concentrates in Texas ERCOT territory and California ISO balancing areas where renewable interconnection queues strain 345 kV and 500 kV corridors.
- Single-Phase:Individual winding sets handle one-third of total system capacity, enabling modular replacement strategies and simplified transportation logistics for remote substations. Demand clusters in rural Midwest cooperative networks where spare-unit pooling agreements reduce inventory carrying costs.
- Autotransformer:Common winding sections reduce copper mass and core steel requirements for voltage step-up applications.
- Instrument Transformer:Voltage and current sensing units provide metering and protection inputs for grid control systems.
Three-Phase sits at the top of the volume ranking, with Autotransformer climbing the fastest.
End User:
Capital allocation cycles and regulatory exposure create distinct margin profiles across customer categories, with federally funded utility projects triggering Buy America compliance costs that industrial buyers largely avoid.
- Utility Companies:Investor-owned and municipal electric systems procure units rated 100 MVA and above for transmission grid backbone infrastructure. PJM Interconnection member utilities drive replacement demand as pre-1979 PCB-contaminated installations face EPA-mandated retirement deadlines.
- Renewable Energy:Wind and solar developers require step-up transformers for generator interconnection at collector substations. Texas CREZ transmission buildout and California renewable portfolio standards concentrate procurement in high-capacity, low-loss specifications for remote generation sites.
- Industrial Sector:Petrochemical, mining, and steel operations purchase dedicated substation equipment for facility-scale voltage transformation.
- Commercial Sector:Data center campuses and large institutional loads specify compact, high-impedance designs for urban substation deployment.
Utility Companies commands the largest installed base, while Renewable Energy expands most rapidly.
Installation Type:
Transportation constraints and site preparation requirements segment total cost of ownership, with mobile configurations commanding premium positioning for emergency restoration scenarios.
- Stationary:Permanent concrete-pad installations with fixed oil containment systems constitute standard utility procurement. Gulf Coast utilities specify elevated foundation designs for hurricane resilience, while California operators prioritize seismic anchorage per CPUC requirements.
- Onshore:Land-based deployment covers conventional transmission substations and generation interconnection points across the continental grid.
- Mobile:Trailer-mounted units with quick-connection bushings enable rapid deployment for storm recovery and planned maintenance bypass. Texas municipal utilities maintain emergency fleets for tornado corridor response, transferring outage risk through OEM-operated spare pooling agreements.
- Offshore:Platform-mounted transformers serve coastal wind installations and subsea cable landing points.
Stationary dominates capital expenditure flows, with Mobile gaining share fastest in storm-prone territories.
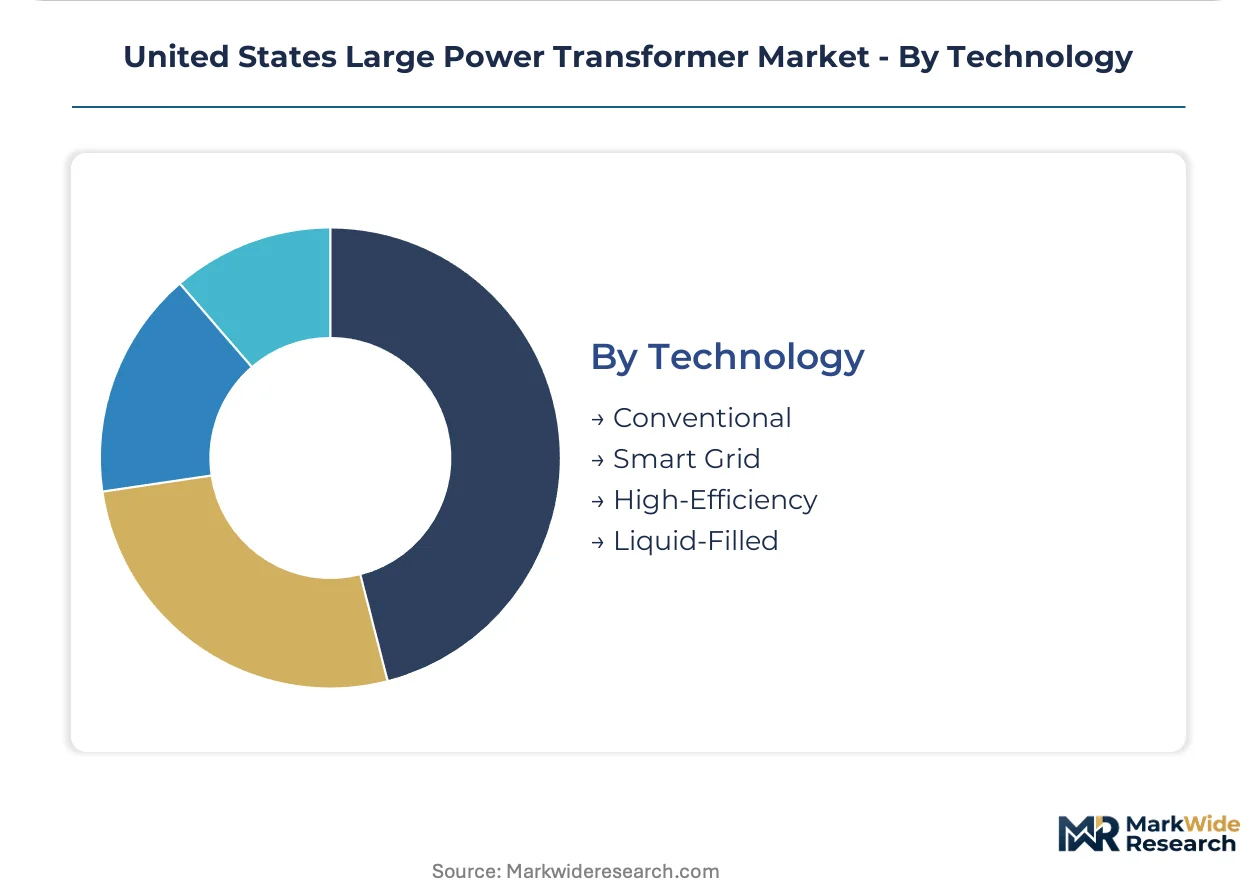
Technology:
Digital instrumentation penetration and efficiency standards create diverging product lifecycles, with smart grid-enabled units requiring cybersecurity certification under NERC CIP-005 that conventional designs bypass.
- Liquid-Filled:Mineral oil or ester-based dielectric coolants enable proven thermal management for high-loading scenarios. Established service infrastructure and dissolved gas analysis protocols support decades-long operational lifespans across Midwest and Southeast utility territories.
- Smart Grid:Embedded temperature, partial discharge, and load tap changer monitoring feed real-time diagnostics to utility control centers. PJM and CAISO member companies specify these units for congestion-managed corridors where thermal loading approaches nameplate limits.
- Conventional:Passive electromagnetic designs without integrated instrumentation serve cost-sensitive replacement cycles.
- High-Efficiency:Reduced no-load and load-loss specifications meet DOE conservation standards and utility energy efficiency program incentives.
Liquid-Filled maintains the deepest installed base, with Smart Grid posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The PJM Interconnection region anchors transformer procurement intensity, with transmission congestion forcing multi-billion-dollar infrastructure commitments across state jurisdictions.
Texas
ERCOT's renewable buildout strains 345 kV corridors connecting West Texas wind zones to Houston load centers. The state's Public Utility Commission fast-tracks transmission investment under CREZ expansion mandates. ERCOT member utilities in the Panhandle and Permian Basin prioritize mobile transformer fleets for storm resilience.
California
CPUC-mandated renewable portfolio standards drive step-up transformer demand at remote solar and battery storage sites. The California ISO's interconnection queue backlog forces transmission upgrades through the Tehachapi corridor. Municipal utilities in the Central Valley accelerate PCB replacement schedules ahead of EPA deadlines.
PJM Interconnection Territory
Queue congestion across Pennsylvania, Ohio, and Virginia creates demand for higher-voltage intertie transformers at 500 kV and 765 kV ratings. FERC Order 2023 compliance deadlines compress procurement timelines for member utilities. Baltimore-Washington corridor substations face the most acute thermal loading constraints.
Southeast
Hurricane exposure drives elevated mobile transformer inventory requirements across Florida and Georgia utility territories. FERC reliability standards impose NERC CIP-014 physical security upgrades at coastal substations. Duke Energy's Carolinas modernization program concentrates procurement in the Charlotte-Greensboro corridor.
Midwest
Rural electric cooperatives in Illinois and Indiana pool spare-unit agreements to reduce inventory carrying costs. MISO interconnection standards harmonize transformer specifications across state boundaries. Chicago-area transmission owners prioritize smart grid-enabled units for congestion-managed corridors.
United States Large Power Transformer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital instrumentation and service-contract bundling. The vendor base concentrates around integrated electrical equipment conglomerates with captive U.S. manufacturing footprints. Three archetypes dominate: domestic-anchored OEMs with federal procurement relationships, Asian-headquartered suppliers competing on cost-engineered specifications, and European-based specialists in high-voltage direct current applications. Capacity expansion and long-term service agreement structures represent the dominant competitive moves reshaping utility procurement protocols.
Among the named participants, Hitachi Energy and General Electric Company exemplify domestic-anchored OEMs with integrated transformer and grid automation portfolios. Siemens Energy occupies a position within the European specialist tier. ABB Ltd and Schneider Electric represent diversified electrical equipment conglomerates with broad infrastructure exposure. Mitsubishi Electric Corporation and Toshiba Energy Systems & Solutions Corporation anchor the Asia-Pacific supplier segment. SPX Transformer Solutions and HD Hyundai Electric exemplify scale-driven competitors with manufacturing presence in U.S. utility procurement channels.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric |
| Hitachi Energy |
| SPX Transformer Solutions |
| HD Hyundai Electric |
| General Electric Company |
| Mitsubishi Electric Corporation |
| Toshiba Energy Systems & Solutions Corporation |
| Siemens Energy |
| Others |
Value Network & Pricing Analysis
Specialized transformer winding technicians concentrated in the Great Lakes manufacturing corridor create labor-cost differentials that widen pricing-tier spreads between premium OEM service bundles and standard transactional procurement. Utilities facing NERC CIP-014 compliance deadlines absorb these premiums for expedited delivery, while municipal cooperatives in the Midwest prioritize cost-engineered specifications from tier-two suppliers.
Pricing Analysis
Input-cost pass-through from grain-oriented electrical steel volatility dominates transformer pricing dynamics, with OEMs indexing contracts to commodity benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates integrated smart-grid units with fifteen-year service guarantees from basic liquid-filled replacements. Cost compression in the economy tier intensifies because Asian-headquartered suppliers compete on scale-manufactured specifications. Renewable energy developers exhibit highest price sensitivity due to project finance constraints, while investor-owned utilities in Texas and California demonstrate lowest sensitivity given rate-base recovery mechanisms.
Supply Chain Analysis
Freight costs for oversized transformer transport from domestic assembly plants to remote substation sites add fifteen-to-twenty percent to landed equipment costs, compressing margins on rural cooperative contracts. Core lamination steel concentrates in Japan, South Korea, and Germany, while copper winding conductors draw from Chilean and Peruvian mining operations. Single-source vulnerability in grain-oriented electrical steel exposes lead times to geopolitical disruption. Distribution runs through utility-direct procurement channels and EPC contractor intermediaries for generation interconnection projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as utilities shift procurement specifications toward smart-grid-enabled transformers with embedded thermal monitoring and predictive maintenance capabilities.
For Market Incumbents: Deepen backward integration into domestic grain-oriented electrical steel sourcing to insulate margin structures from tariff exposure and supply disruption. Anchor utility relationships through captive U.S. manufacturing footprints that satisfy Buy America thresholds for federally funded infrastructure projects. Long-term service agreement bundling transfers asset-performance risk from utilities to OEMs, creating recurring revenue streams that offset cyclical equipment replacement demand. For New Entrants and Emerging Players: Capture mobile transformer fleet opportunities in storm-prone Southeast and Texas territories where emergency restoration capabilities command premium positioning. Rural electric cooperative networks in the Midwest present the most penetrable segment given spare-unit pooling agreements that reduce incumbent inventory advantages. Target digital instrumentation retrofit kits for legacy oil-filled installations as a go-to-market angle that bypasses capital-intensive core manufacturing. For Investors and Strategic Acquirers: Electrical equipment conglomerates with integrated grid automation portfolios are the most active acquirer in this space, seeking transformer manufacturing capacity to complement existing utility relationships. Mid-tier OEMs with established FERC and NERC certification track records represent the optimal acquisition target archetype. Monitor EPA PCB replacement deadline acceleration as the signal to watch for inflection in pre-emptive utility procurement activity.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Capacity Expansion | U.S.-based tank and radiator fabrication reduces lead time exposure to foreign steel supply disruption. |
| Smart Grid Sensor Integration | Embedded thermal monitoring transforms passive hardware into grid-edge data platforms for PJM and CAISO operators. |
| Long-Term Service Agreement Structuring | Fifteen-year performance guarantees transfer diagnostic responsibility and spare inventory holding to manufacturers. |
| Amorphous Metal Core Technology Licensing | Alternative core materials reduce dependency on volatile grain-oriented electrical steel pricing. |
| Mobile Transformer Fleet Partnership | Emergency deployment capabilities capture premium positioning in tornado and hurricane corridor territories. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down transformer manufacturing capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, EPC contractors, OEM sales directors, and grid operators combine with secondary validation from FERC interconnection queue databases, EIA generation capacity reports, and EPA PCB remediation filings. Trade data from the Department of Commerce and utility capital expenditure disclosures triangulate volume estimates across the analysis window.
Historical trendline analysis of transformer procurement cycles, renewable interconnection timelines, and replacement demand patterns informs the projection framework. Segmentation dimensions span product type, end user category, installation configuration, and technology tier, with regional regulatory clusters modeled separately for ERCOT, PJM, CAISO, and MISO territories. CAGRs derive from unit shipment trajectories and average selling price movements across the modeling period, incorporating FERC Order 2023 compliance deadlines and Infrastructure Investment and Jobs Act funding disbursement schedules as demand catalysts.
Geopolitical disruption in core steel supply, EPA regulatory acceleration on PCB remediation, and renewable project cancellation rates are the dominant revision risks that could compress or extend forecast trajectories. Stakeholders should weight assumptions against their own operating context and capital planning horizons.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Transformer Steel Market
Transformers
Transformer Core Market
Transformers
Distribution Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
South America Transformer Market
Transformers
High Frequency Transformer Market
Transformers
Transformer Bobbin Market
Transformers
North America Dry Type Transformer Market
Transformers
Global Transformer Market
Transformers
Global Large Power Transformers Market
Transformers
Saudi Arabia Transformer Market
Transformers
Green Power Transformers Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Rail Traction Transformers Market
Transformers
Current Transformer Market
Transformers
Single Phase Power Transformer Market