
 Transformer Steel Market | 2026-2036
Transformer Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Transformer Steel Market Analytics
EU Green Deal efficiency mandates are restructuring the cost-of-entry calculus for transformer core suppliers across Europe. Nippon Steel Corporation leverages its ultra-thin grain-oriented silicon steel portfolio to dominate premium power transformer segments in Japan and export markets. POSCO sustains vertical integration from hot metal to finished electrical steel, anchoring cost competitiveness in Asian utility procurement cycles. ArcelorMittal competes through European mill proximity to EMA-regulated grid operators seeking localized supply security.
Transformer steel comprises grain-oriented electrical steel with silicon content between 2.5% and 3.5%, manufactured through precise cold rolling and annealing to achieve magnetic permeability below 1.0 W/kg core loss at 1.5 Tesla. Its primary purpose centers on channeling magnetic flux with minimal energy dissipation in power and distribution transformer cores. Silicon steel occupies the mature volume base where margin pools have compressed amid Chinese capacity expansion, while amorphous steel represents the fastest-growing material type as utilities prioritize no-load loss reduction in distribution transformer fleets. Power transformers command premium pricing due to thickness precision requirements and extended qualification cycles with national grid operators.
EPA efficiency standards in the United States and China's GB standards under SAMR jurisdiction collectively shape product specifications and market access thresholds for transformer steel producers. REACH compliance in Europe and India's BIS certification requirements further fragment qualification protocols, forcing manufacturers to maintain parallel metallurgical process controls. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost structure of imported electrical steel relative to domestic melt capacity.
Market Dynamics
Renewable energy integration is forcing power utilities to rebuild transformer fleets with ultra-low-loss core materials, compressing qualification timelines and rewiring procurement priorities across transmission and distribution networks.
Growth Catalysts
- EU Green Deal efficiency mandates:Distribution network operators must replace conventional silicon steel cores with amorphous alternatives to meet no-load loss targets by 2030.
- China's State Grid procurement corridors:Centralized bulk tenders for ultra-high-voltage transformers are consolidating demand for premium grain-oriented electrical steel specifications.
- Amorphous steel ribbon technology:Thin-gauge amorphous alloys now enable distribution transformers to achieve 70-80% lower core losses than conventional silicon steel equivalents.
Market Restraints
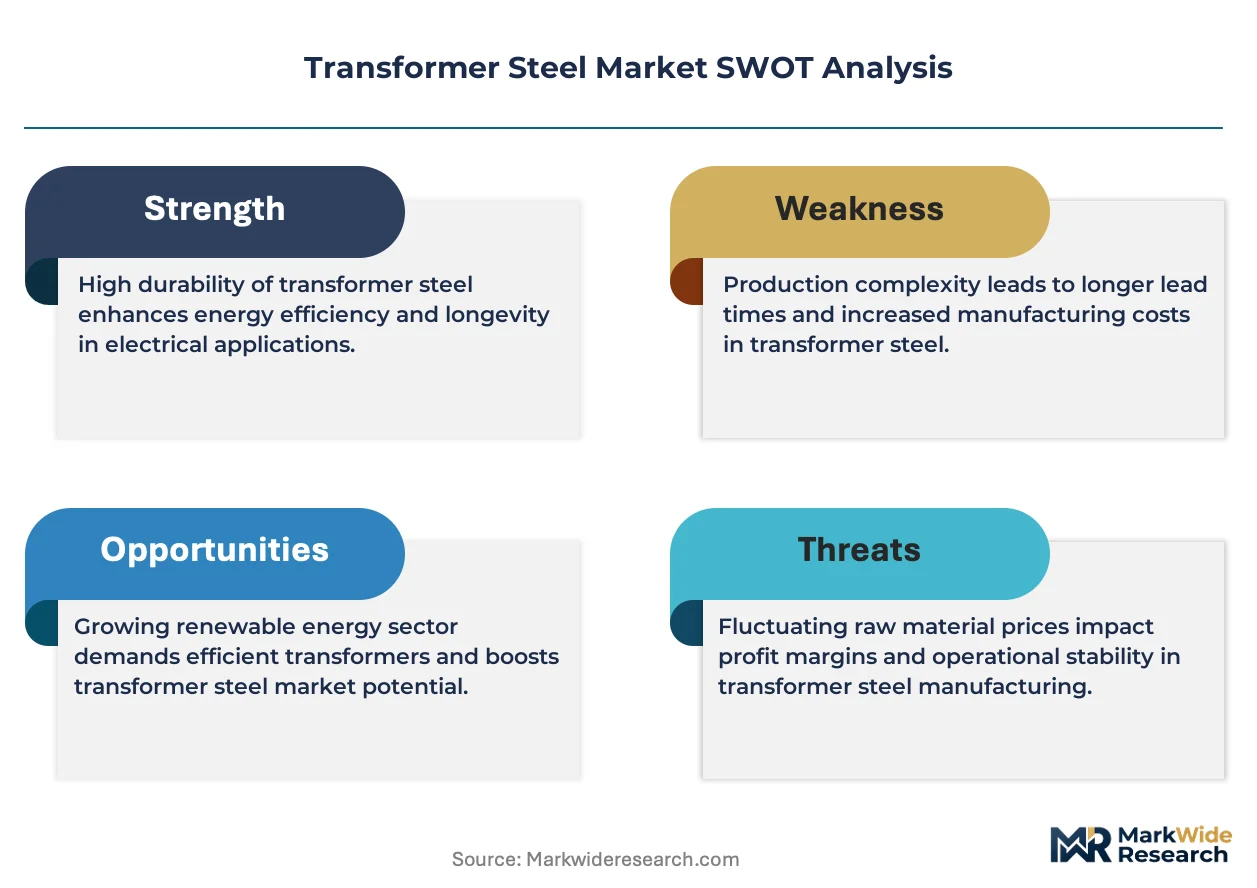
- Silicon metal price volatility:Ferrosilicon input costs swing with Chinese smelter output curbs, squeezing margin predictability for electrical steel rollers.
- Amorphous steel supply concentration:Hitachi Metals and limited Chinese producers control nearly all commercial amorphous ribbon capacity, creating single-source vulnerability.
- REACH compliance friction:ECHA substance restrictions on process chemicals complicate European mill qualification for Asian-sourced hot-rolled coil.
Strategic Opportunities
- India's rural electrification corridors:SAUBHAGYA scheme extensions are generating demand for millions of distribution transformers optimized for intermittent load profiles.
- Digital twin integration:Real-time core loss monitoring via IoT sensors is opening service-contract revenue streams beyond hardware supply.
- Carbon border adjustment mechanisms:EU CBAM phase-in from 2026 favors domestic European melt capacity over imported electrical steel from carbon-intensive blast furnaces.
Industry Challenges
- Ultra-thin rolling expertise scarcity:Grain-oriented silicon steel below 0.23mm thickness requires proprietary annealing atmospheres that few mill operators have mastered.
- Grid operator qualification timelines:National transmission utilities demand 18-36 month field validation before approving new core material suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transformer Steel Market |
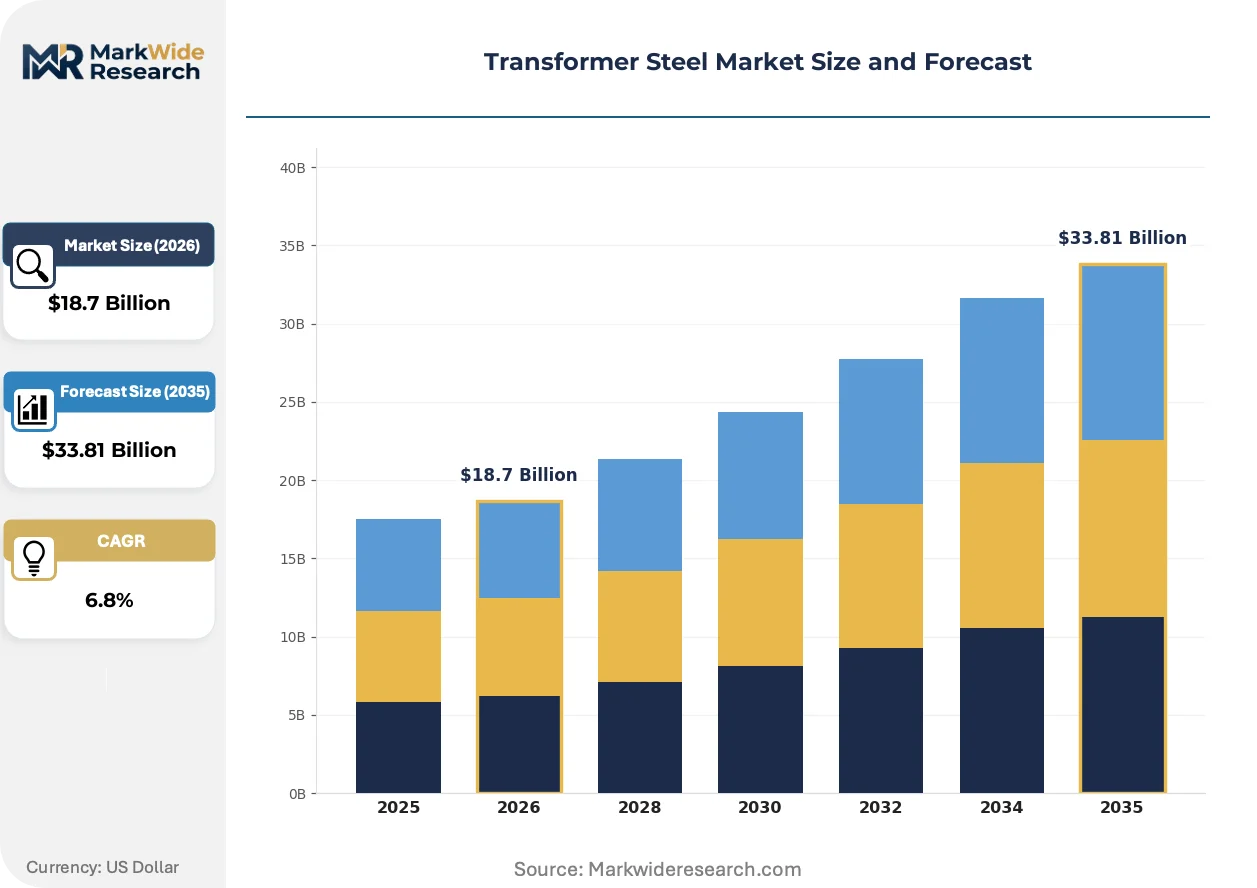
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicon Steel, Non-Silicon Steel, Amorphous Steel, Cold Rolled Steel End User: Utilities, Industrial Manufacturers, Power Generation, Onshore Wind Thickness: Thin, Medium, Thick, Ultra-Thin Application: Power Transformers, Distribution Transformers, Instrument Transformers, Specialty Transformers |
| Companies Covered | Nippon Steel Corporation, POSCO, JFE Steel Corporation, ArcelorMittal, China Baowu Steel Group, Thyssenkrupp, Cleveland-Cliffs, Tata Steel Limited, NLMK Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transformer Steel Market Evolving Landscape
Core material innovation is bifurcating the transformer supply base between premium ultra-thin silicon steel for bulk power applications and amorphous alloys for loss-sensitive distribution networks.
Amorphous steel ribbon is overtaking conventional silicon steel in distribution transformer specifications below 10 MVA rating. US rural electric cooperatives and European DSOs are accelerating adoption to meet EPA efficiency tiers and EU Ecodesign requirements. The technology is compressing addressable margin pools for commodity-grade silicon steel while creating captive demand for specialized annealing furnace operators.
EPA efficiency standards under the Energy Policy Act are tightening no-load loss allowances for liquid-immersed distribution transformers. The rulemaking forces core material substitution toward amorphous or domain-refined silicon steel grades. US-based transformer OEMs are qualifying Asian amorphous ribbon sources ahead of 2027 compliance deadlines.
Utility procurement departments are unbundling core material supply from finished transformer contracts. State Grid Corporation of China and India's Power Grid Corporation now specify core steel grades separately, enabling direct mill relationships. This pattern is most visible in Asia-Pacific procurement corridors where national standards permit grade-level substitution without full transformer requalification.
Transformer Steel Market Segmentation
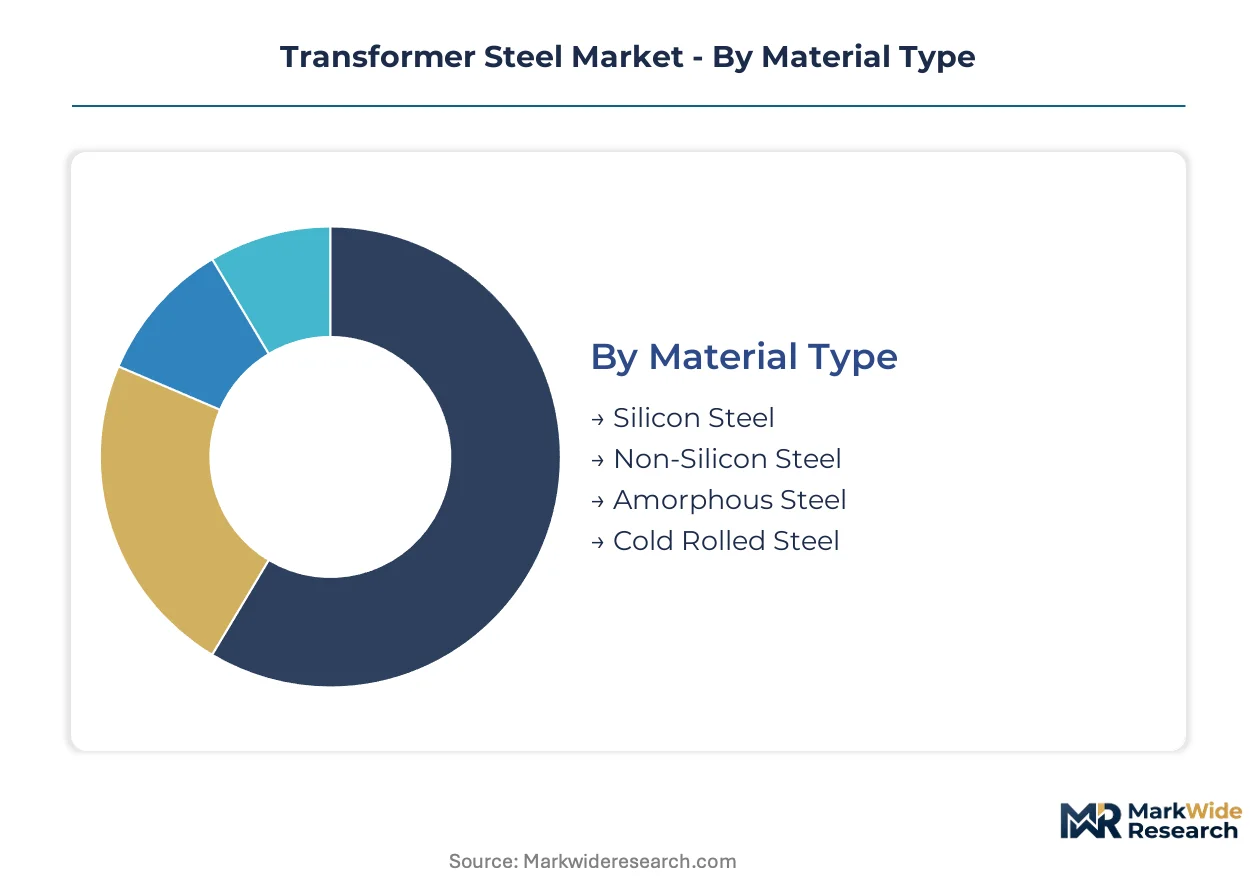
Transformer steel procurement splits across material chemistry, core geometry, and end-use voltage class. Each dimension shapes supplier qualification requirements and margin capture differently.
Material Type:
Core loss performance dictates material selection more than raw material cost.
- Silicon Steel:Grain-oriented electrical steel with 2.5-3.5% silicon content delivers magnetic permeability below 1.0 W/kg core loss at 1.5 Tesla. China's State Grid bulk tenders concentrate demand for premium grades in ultra-high-voltage corridors.
- Amorphous Steel:Thin-gauge iron-based alloys manufactured through rapid solidification enable 70-80% lower core losses than silicon equivalents. EU Green Deal efficiency mandates are accelerating substitution in European distribution networks.
- Non-Silicon Steel:Low-carbon electrical steels serve cost-sensitive applications where core loss tolerance permits.
- Cold Rolled Steel:Non-oriented grades fill auxiliary magnetic components outside main transformer cores.
Silicon steel leads on scale; amorphous steel leads on momentum.
End User:
Procurement scale and qualification timelines vary sharply across customer archetypes.
- Utilities:National grid operators run 18-36 month field validation cycles before approving new core material suppliers. India's Power Grid Corporation and China's State Grid dominate volume procurement through centralized tenders.
- Power Generation:Renewable project developers prioritize ultra-low-loss cores to minimize parasitic losses in remote generation assets. Wind and solar farm transformers specify amorphous or domain-refined silicon grades.
- Industrial Manufacturers:Captive transformer users in steel, cement, and chemical sectors specify core materials based on total cost of ownership rather than upfront procurement price.
- Onshore Wind:Turbine OEMs specify step-up transformers with cores optimized for variable loading profiles and grid-code compliance.
Utilities command volume; power generation commands specification intensity.
Thickness:
Gauge precision determines magnetic domain structure and eddy current suppression.
- Ultra-Thin:Sub-0.23mm grain-oriented silicon steel requires proprietary annealing atmospheres that few mill operators have mastered. Japanese and Korean producers anchor supply for premium power transformer segments.
- Thin:0.23-0.27mm grades balance core loss performance with manufacturing yield in distribution transformer applications.
- Medium:0.27-0.35mm specifications serve standard distribution transformers where loss tolerance permits.
- Thick:Above 0.35mm grades fill auxiliary reactors and specialty magnetic components.
Ultra-thin captures margin concentration; thin captures unit volume.
Application:
Voltage class and loading profile shape core material specification.
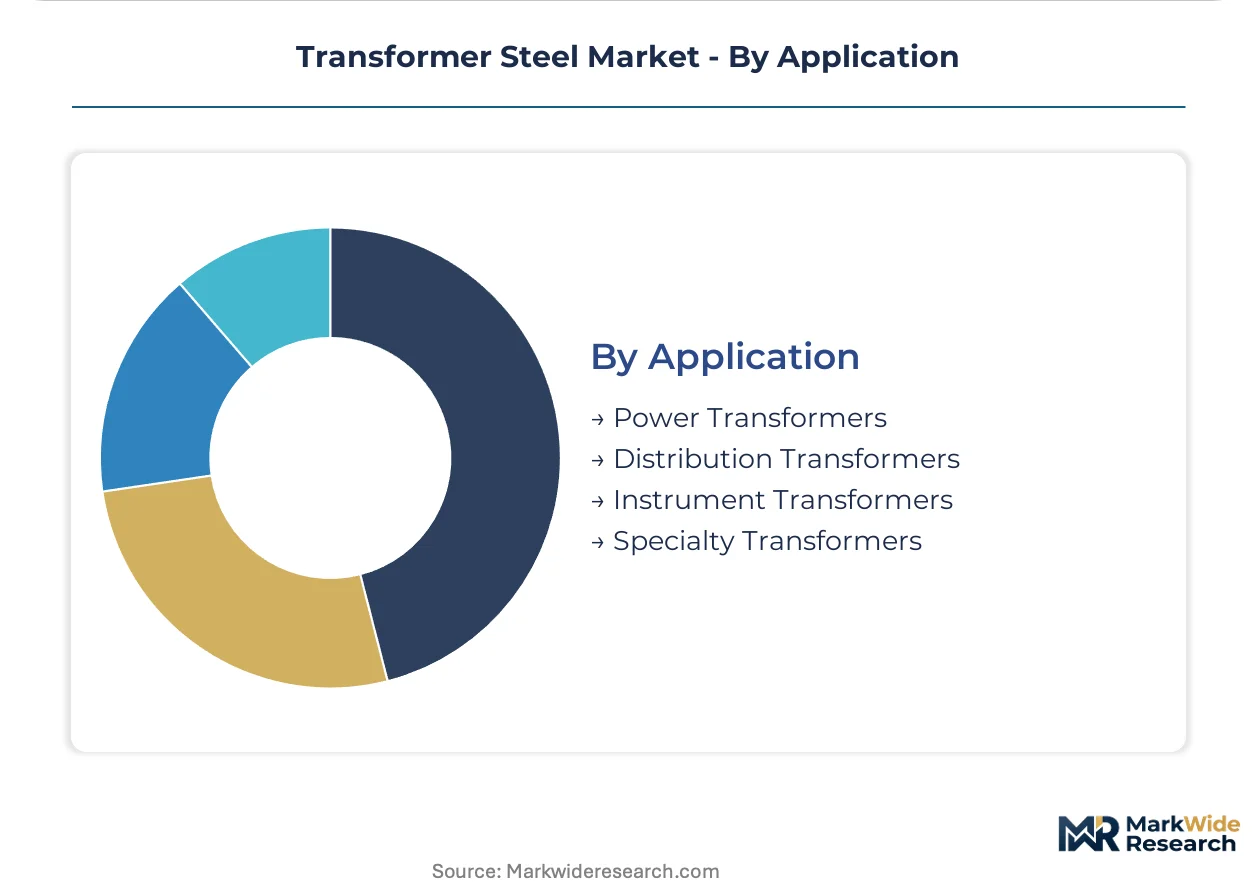
- Power Transformers:Bulk transmission assets above 100 MVA demand domain-refined ultra-thin silicon steel with extended qualification cycles. National grid operators in China, India, and the United States specify grades separately from finished transformer contracts.
- Distribution Transformers:Below-10 MVA units are shifting toward amorphous steel cores to meet EPA efficiency tiers and EU Ecodesign requirements. US rural electric cooperatives and European DSOs anchor adoption.
- Instrument Transformers:Voltage and current sensing applications require precise magnetic linearity rather than minimal core loss.
- Specialty Transformers:Furnace, rectifier, and traction applications specify custom core geometries outside standard distribution or power categories.
Power transformers anchor premium pricing; distribution transformers anchor technology transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical engineering talent concentrates in Japan, Germany, and South Korea, anchoring ultra-thin silicon steel production. These workforce clusters sustain proprietary annealing expertise that few competitors can replicate.
China
State Grid Corporation's centralized procurement corridors dominate demand for premium grain-oriented electrical steel specifications. SAMR-administered GB standards under dual carbon goals mandate efficiency upgrades across distribution networks. Shanghai and Baoshan industrial clusters host integrated melt-to-finish capacity serving domestic ultra-high-voltage transformer programs.
United States
Rural electric cooperatives and investor-owned utilities drive amorphous steel substitution in distribution transformer fleets. EPA efficiency standards under the Energy Policy Act tighten no-load loss allowances through 2027 compliance deadlines. Ohio and Indiana manufacturing corridors anchor domestic electrical steel rolling capacity serving Great Lakes transformer OEMs.
Germany
Distribution system operators accelerate amorphous core adoption to meet EU Ecodesign and EU Green Deal efficiency mandates. REACH compliance administered by ECHA restricts process chemicals in European mill qualification protocols. North Rhine-Westphalia's Ruhr industrial basin concentrates transformer OEM supply chains with proximity to EMA-regulated grid operators.
India
Power Grid Corporation and state utilities generate demand for millions of distribution transformers under SAUBHAGYA rural electrification extensions. BIS certification requirements fragment qualification protocols for imported hot-rolled coil. Gujarat and Maharashtra industrial corridors host emerging domestic electrical steel capacity serving western grid expansion.
Japan
Tokyo Electric Power and regional utilities specify domain-refined ultra-thin grades for premium power transformer segments. METI efficiency guidelines shape procurement priorities for loss-sensitive transmission assets. Kawasaki and Chiba industrial clusters sustain proprietary annealing atmospheres for sub-0.23mm grain-oriented silicon steel production.
Transformer Steel Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Integrated steel majors leverage captive hot metal capacity to anchor cost predictability in volatile ferrosilicon markets. Three archetypes dominate: Asian integrated mills with upstream melt control, European proximity-based suppliers serving regulated grid operators, and Japanese precision specialists commanding premium specifications. Competitive moves concentrate on strategic partnerships for amorphous ribbon technology access and selective capacity expansion in tariff-advantaged locations.
Among Japanese precision specialists, Nippon Steel Corporation and JFE Steel Corporation occupy positions defined by ultra-thin rolling mastery and extended qualification relationships with national grid operators. POSCO exemplifies the Asian integrated mill archetype with upstream control from hot metal through finished electrical steel. ArcelorMittal represents European proximity-based supply security for EMA-regulated operators seeking localized melt capacity under emerging carbon border adjustment mechanisms.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| POSCO |
| JFE Steel Corporation |
| ArcelorMittal |
| China Baowu Steel Group |
| Thyssenkrupp |
| Cleveland-Cliffs |
| Tata Steel Limited |
| NLMK Group |
| Others |
Value Network & Pricing Analysis
Ferrosilicon input costs swing through Chinese smelter output curbs and feed directly into three-tier pricing stratification across premium grain-oriented, domain-refined, and commodity silicon steel grades. State Grid Corporation bulk tenders compress margins on standard specifications while ultra-thin sub-0.23mm grades sustain premium capture through Japanese and Korean mill scarcity.
Pricing Analysis
The bundled transformer contract is unbundling as utilities specify core steel grades separately from finished equipment procurement. Premium-mid-economy pricing differentiation rests on thickness precision and qualification status with national grid operators, with sub-0.23mm domain-refined grades commanding substantial premiums over commodity 0.27-0.35mm distribution specifications. Cost compression in standard silicon steel intensifies because Chinese capacity expansion floods procurement corridors, while amorphous ribbon maintains pricing power through Hitachi Metals supply concentration. Industrial manufacturers prove least price-sensitive due to total-cost-of-ownership procurement logic, whereas rural electric cooperatives anchor the most price-sensitive tier amid SAUBHAGYA scheme volume mandates.
Supply Chain Analysis
Grid operator qualification gating stretches 18-36 month field validation cycles before new core material suppliers gain approval, tethering supply security to incumbent mill relationships. Production gravity centers on China, Japan, and South Korea for grain-oriented silicon steel, with limited Chinese producers and Hitachi Metals controlling amorphous ribbon capacity. Raw material flows draw from ferrosilicon smelters, hot-rolled coil feedstock, and proprietary annealing atmosphere gases. Single-source vulnerability in amorphous steel supply concentrates risk for distribution transformer OEMs racing EPA efficiency deadlines. Distribution runs through national utility procurement corridors, transformer OEM mill-direct relationships, and specialized electrical steel distributors serving smaller industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transformer steel has shifted to a late-cycle quality story as renewable integration forces utilities toward ultra-low-loss core specifications regardless of upfront cost premiums. Procurement departments now prioritize core loss performance over unit price in qualification protocols.
For Market Incumbents: To counter amorphous steel substitution in distribution networks, domain-refined silicon steel producers must deepen backward integration into ferrosilicon supply and accelerate sub-0.23mm capacity expansion in tariff-advantaged locations. Securing direct qualification relationships with State Grid Corporation and India's Power Grid Corporation locks out emerging competitors through extended validation timelines.
For New Entrants and Emerging Players: Transformer OEMs in India's western corridor represent the most penetrable channel partner type for amorphous ribbon distribution, given SAUBHAGYA scheme volume mandates and limited domestic supply. White-space targets include BIS-certified amorphous core assembly for distribution transformers below 10 MVA and qualification support services for mills navigating EMA and EPA compliance pathways. A go-to-market angle anchored in carbon-border-adjustment-compliant melt sourcing appeals to European DSO procurement priorities.
For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary annealing expertise concentrates in aging Japanese and Korean workforce clusters. Long-term viability favors integrated mills with captive hot metal capacity and qualification heritage with multiple national grid operators. Acquisition targets include specialized annealing furnace operators and amorphous ribbon technology licensors outside Hitachi Metals' orbit. The signal to watch is unbundling penetration rates in Asian utility procurement corridors, as direct mill relationships disintermediate traditional transformer OEM supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Ribbon Capacity Expansion | Captures EPA efficiency tier compliance demand from US rural electric cooperatives. |
| Backward Integration into Ferrosilicon | Insulates margin predictability against Chinese smelter output volatility. |
| Ultra-Thin Rolling Mastery Investment | Secures qualification lock-in with State Grid ultra-high-voltage programs. |
| Digital Twin Service Contract Launch | Opens recurring revenue beyond hardware through IoT core loss monitoring. |
| Carbon-Border-Adjusted Melt Sourcing | Positions supply security for EMA-regulated European grid operators. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down electrical steel production tracking forms the analytical core of this study. Primary interviews with transformer OEM procurement directors, national grid operator material engineers, electrical steel mill technical sales leads, and ferrosilicon smelter operations managers combined with secondary validation from SAMR GB standards filings, EMA grid codes, EPA efficiency rulemakings, and customs trade data. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of grain-oriented and amorphous steel shipments informed growth trajectory calibration across the projection horizon. The analytical framework modeled material type, thickness tier, application voltage class, and end-user procurement archetype as core segmentation dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating renewable integration targets and efficiency mandate compliance deadlines. Forecast inputs included transformer fleet replacement cycles, qualification timeline compression, and carbon border adjustment phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to amorphous steel supply expansion, ferrosilicon price volatility, and grid operator qualification protocol harmonization. Forecasts reflect assumptions about efficiency mandate enforcement continuity and renewable project development pace. A model refresh is warranted upon material change in EPA rulemaking timelines or EU CBAM implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
High Frequency Transformer Market
Transformers
Power Transformer Market
Transformers
Europe Oil Filled Distribution Transformer Market
Transformers
Asia Pacific Smart Transformers Market
Transformers
Transformer Bobbin Market
Transformers
Phase-Shifting Transformer Market
Transformers
Europe Telecom Transformers Market
Transformers
Transformer Oil Market
Transformers
India Power Transformer Market
Transformers
Electric Vehicle Charging Station Transformer Market
Transformers
Amorphous Core Transformers Market
Transformers
Traction Transformer Market
Transformers
Oil Filled Transformer Market
Transformers
Oil Immersed Transformer and Dry Type Transformer Market
Transformers
Global Large Power Transformers Market
Transformers
Step Up/Down Transformers Market