
 Venezuela Renewable Energy Market | 2026-2036
Venezuela Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Venezuela Renewable Energy Market Analytics
Lithium iron phosphate is hardening as the preferred battery chemistry for Venezuelan solar-plus-storage installations, displacing lead-acid systems across commercial and industrial microgrids. SOLINAL C.A. leverages its domestic installation network to anchor utility-scale photovoltaic projects in sun-belt states. INGESOL C.A. specializes in off-grid hybrid systems for remote mining camps in Bolívar state. Siemens Gamesa Renewable Energy, S.A. competes through technology leadership in wind turbine adaptation for Caribbean coastal wind regimes.
Venezuela renewable energy encompasses electricity generation from solar irradiance, kinetic wind, flowing water, and organic biomass feedstocks, typically converted through photovoltaic cells, horizontal-axis turbines, penstock-fed generators, or anaerobic digesters with nominal outputs ranging from kilowatt residential systems to multi-megawatt industrial arrays. Its primary purpose is to displace thermoelectric dependence on subsidized domestic natural gas and imported diesel in a country with chronic grid instability. Solar photovoltaic dominates installed capacity due to modular deployment and minimal fuel logistics, while off-grid deployment models capture the fastest growth trajectory as state utility reliability collapses. Small hydro technology retains mature margins in Andean watersheds where pre-existing civil infrastructure reduces capital intensity.
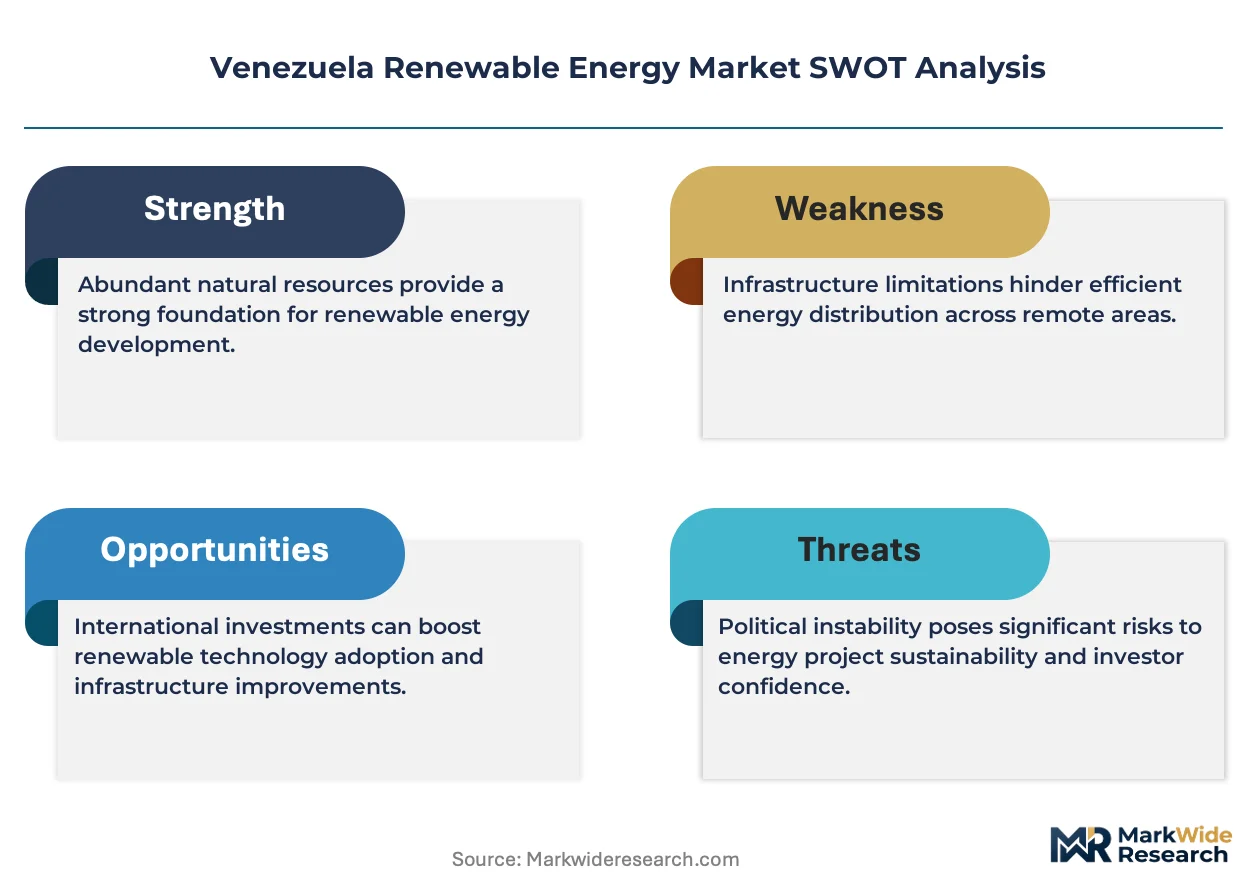
Venezuela's Ministry of Electric Power and state operator Corpoelec shape project permitting through overlapping jurisdiction that delays independent power producer licensing, while the country's national standards body applies electrical safety protocols adapted from older IEC frameworks. The absence of a functioning renewable energy auction mechanism forces developers toward bilateral offtake negotiations with large industrial consumers. Stakeholders must monitor whether future regulatory clarity on wheeling tariffs unlocks bankable project finance or perpetuates reliance on self-supply arrangements.
Market Dynamics
Venezuela's renewable energy sector is restructuring around grid independence as Corpoelec's operational collapse forces industrial consumers toward captive generation. Distributed solar-plus-storage systems are capturing capital flows that previously fed centralized thermoelectric maintenance.
Growth Catalysts
- Guayana Mining Electrification:Remote gold and bauxite operations in Bolívar state are abandoning diesel logistics for solar-battery microgrids. The operational cost arbitrage accelerates deployment timelines.
- Rural Electrification Mandates:Off-grid residential programs channel development finance toward photovoltaic installations in Amazonas and Delta Amacuro states.
- Lithium Iron Phosphate Chemistry:Battery cost curves and cycle life improvements are displacing lead-acid storage across commercial installations.
Market Restraints
- Import Dependency for Inverters:Currency convertibility failures restrict access to power electronics from Chinese and European suppliers.
- Corpoelec Wheeling Ambiguity:The absence of standardized interconnection tariffs blocks independent power producer licensing.
- Diesel Subsidy Distortion:Remaining liquid fuel price controls artificially compress the economic case for solar displacement.
Strategic Opportunities
- Andean Small Hydro Rehabilitation:Pre-existing penstock infrastructure in Mérida and Táchira reduces civil works capital intensity.
- Caribbean Coastal Wind:Zulia and Falcón states exhibit unexploited wind resource profiles suitable for utility-scale turbine deployment.
- Bilateral Offtake Contracts:Direct power purchase agreements with aluminum smelters and cement plants bypass regulatory auction failures.
Industry Challenges
- Certification Backlog:The national standards body's IEC framework adaptation delays equipment approval timelines.
- Technical Workforce Scarcity:Grid-tied inverter commissioning expertise concentrates in Caracas and Valencia, constraining rural deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venezuela Renewable Energy Market |
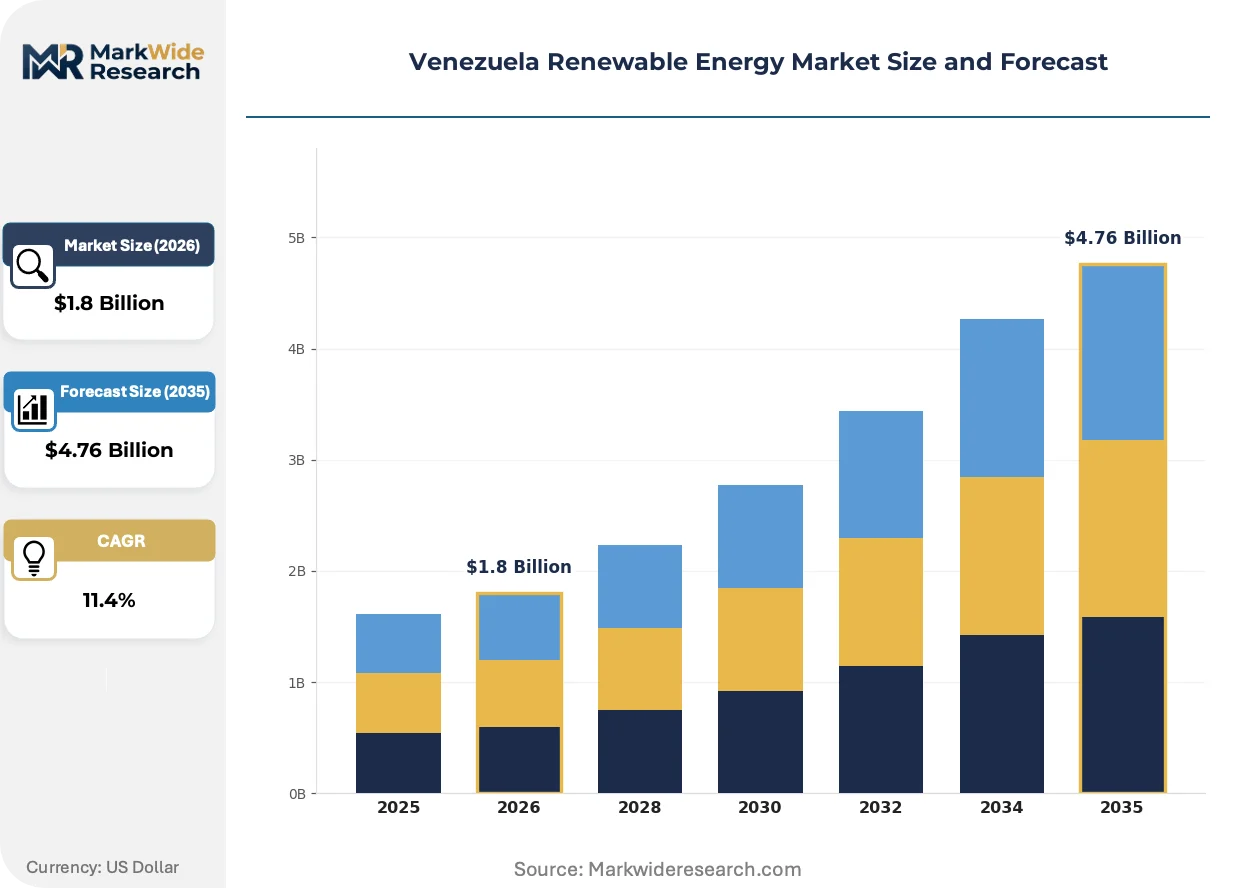
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Type: Solar, Wind, Hydro, Biomass Deployment Model: On-grid, Off-grid, Hybrid, Microgrid End User: Residential, Commercial, Industrial, Government Technology: Photovoltaic, Concentrated Solar Power, Wind Turbines, Small Hydro |
| Companies Covered | SOLINAL C.A., INGESOL C.A., Siemens Gamesa Renewable Energy, S.A., Andritz AG, Corpoelec, Zelestra SL, Vestas Wind Systems A/S, HPC Venezuela CA, Orinoco Solar Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venezuela Renewable Energy Market Evolving Landscape
Technology substitution and procurement fragmentation are reconfiguring how Venezuelan energy consumers source electricity. Modular generation assets are compressing the relevance of centralized infrastructure planning.
Solar-plus-storage hybrid architectures are electrifying commercial and industrial microgrids across the Orinoco Mining Arc. Mining operators in Bolívar state are deploying containerized lithium iron phosphate systems at 12-24 month payback thresholds. This electrification is collapsing the historical diesel logistics chains that consumed fifteen percent of remote site operating budgets.
Corpoelec's licensing jurisdiction overlaps with the Ministry of Electric Power, creating permitting friction that favors self-supply over grid-connected projects. Developers report eighteen-month approval timelines for independent power producer status. Large aluminum and steel consumers are responding by internalizing generation assets rather than pursuing wheeling arrangements.
Industrial procurement is fragmenting toward direct equipment import and EPC contractor relationships. State utility procurement channels have atrophied, pushing mining and manufacturing buyers toward Chinese module suppliers and regional installation contractors. This behavioral shift is most pronounced in Ciudad Guayana, where aluminum smelters now source ninety percent of new capacity through bilateral negotiations rather than public tenders.
Venezuela Renewable Energy Market Segmentation
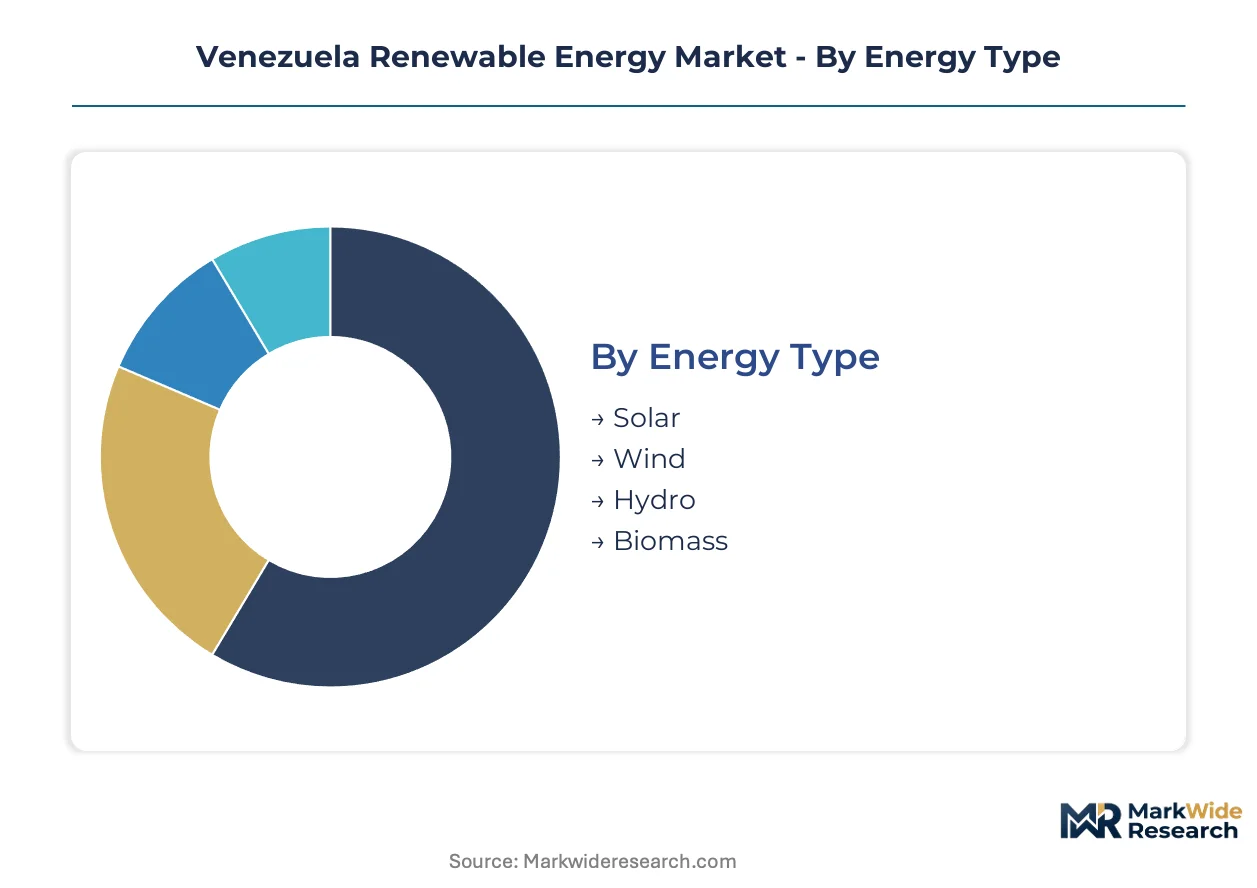
Venezuela's renewable energy market fragments across four critical dimensions that determine project economics, financing structures, and deployment velocity. Each segmentation axis reveals distinct capital allocation patterns shaped by Corpoelec's operational collapse and industrial self-supply imperatives.
Energy Type:
Supply concentration in photovoltaic module sourcing from Chinese manufacturers is compressing capital costs for solar relative to other generation technologies.
- Solar:Photovoltaic cells convert solar irradiance into direct current electricity through monocrystalline or polycrystalline silicon wafers. Demand concentrates in Bolívar state's mining corridor, where diesel logistics failures are forcing gold and bauxite operators toward solar-battery microgrids with twelve-to-twenty-four month payback thresholds.
- Wind:Horizontal-axis turbines capture kinetic energy from Caribbean coastal wind regimes. Zulia and Falcón states exhibit unexploited resource profiles, though currency convertibility failures restrict access to European and Chinese turbine suppliers.
- Hydro:Penstock-fed generators harness flowing water in Andean watersheds. Mérida and Táchira states leverage pre-existing civil infrastructure to reduce capital intensity for small hydro rehabilitation.
- Biomass:Anaerobic digesters process organic agricultural feedstocks into combustible biogas. Rural electrification programs in Amazonas state channel development finance toward agricultural residue-to-energy installations.
Today's leader: Solar. Tomorrow's challenger: Wind.
Deployment Model:
Cost tier differentiation separates capital-intensive grid-connected projects from modular self-supply architectures that bypass Corpoelec interconnection queues.
- On-grid:Utility-scale installations feed electricity into Corpoelec's national transmission network. Eighteen-month approval timelines for independent power producer status are blocking capital flows toward grid-connected assets.
- Off-grid:Standalone systems electrify communities beyond transmission infrastructure reach. Amazonas and Delta Amacuro states are capturing development finance for photovoltaic installations that displace diesel generator dependence.
- Hybrid:Dual-source configurations combine solar with battery storage or backup diesel. Mining camps in the Orinoco Mining Arc are deploying containerized lithium iron phosphate systems that collapse historical fuel logistics chains.
- Microgrid:Localized generation networks serve discrete industrial or residential clusters. Aluminum smelters in Ciudad Guayana are internalizing captive microgrids rather than pursuing wheeling arrangements through Corpoelec's ambiguous tariff structure.
Modular architectures are climbing the fastest. Centralized utility models are losing financing access.
End User:
Application-driven procurement fragmentation is redirecting equipment flows from state utility channels toward direct industrial relationships.
- Residential:Single-family and multi-unit dwellings deploy kilowatt-scale rooftop photovoltaic systems. Rural electrification mandates are expanding adoption among off-grid communities in remote states.
- Commercial:Retail, hospitality, and service sector facilities seek electricity cost stability. Caracas and Valencia commercial districts are sourcing distributed generation through regional EPC contractors rather than public tenders.
- Industrial:Mining, aluminum, steel, and cement operations require multi-megawatt reliability. Guayana mining electrification is accelerating deployment timelines as diesel operational cost arbitrage collapses historical fuel dependence.
- Government:Public facilities and infrastructure projects receive subsidized development finance. Ministry of Electric Power programs channel capital toward politically prioritized electrification zones.
Industrial buyers are driving volume now. Residential segments are expanding most quickly.
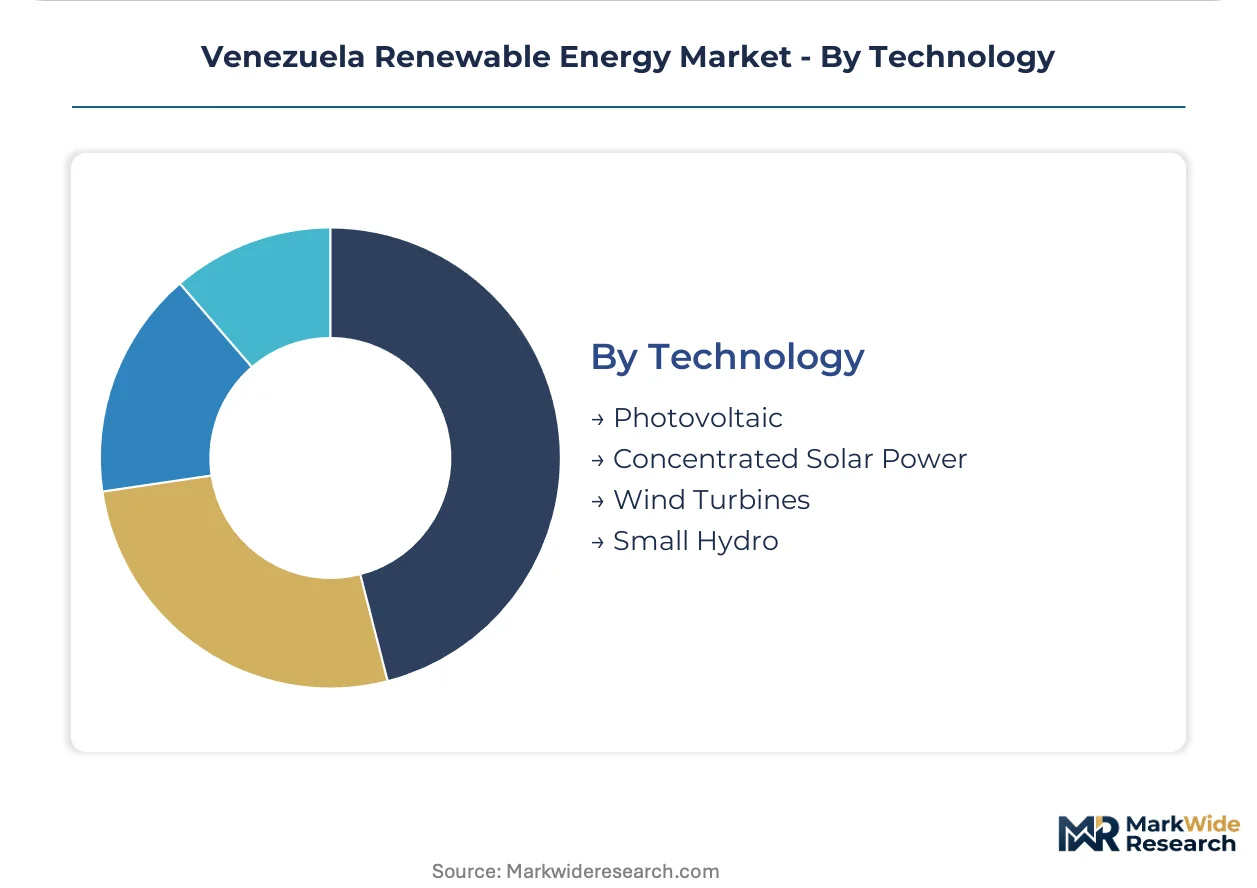
Technology:
Volume concentration in photovoltaic module procurement is displacing alternative generation technologies across commercial and industrial applications.
- Photovoltaic:Silicon-based cells convert sunlight directly to electricity without thermal intermediation. Modular deployment and minimal fuel logistics are dominating installed capacity growth.
- Concentrated Solar Power:Mirror arrays focus solar thermal energy onto heat-transfer fluids for steam generation. High capital intensity and water requirements are limiting deployment to specialized industrial applications.
- Wind Turbines:Horizontal-axis machines with three blades extract kinetic energy from airflow. Caribbean coastal wind regimes in Zulia remain unexploited due to supply chain constraints on nacelle and blade imports.
- Small Hydro:Run-of-river installations under ten megawatts avoid reservoir construction. Andean watersheds in Mérida retain mature margins where pre-existing penstock infrastructure reduces civil works requirements.
Photovoltaic holds current dominance. Small hydro rehabilitation presents the steepest expansion trajectory in Andean states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Orinoco Mining Arc anchors Venezuela's renewable energy deployment as industrial consumers abandon Corpoelec's failing grid. State-level electrification patterns diverge sharply between mining-intensive southern regions and Andean watersheds with legacy hydro infrastructure.
Bolívar State
Gold and bauxite operations in the Guayana Shield drive solar-battery microgrid demand as diesel logistics collapse. The Ministry of Electric Power maintains overlapping permitting jurisdiction with Corpoelec, delaying independent power producer licensing. Ciudad Guayana's aluminum smelters now source captive generation through direct bilateral negotiations rather than public tenders.
Zulia State
Caribbean coastal wind regimes remain unexploited despite favorable resource profiles for utility-scale turbine deployment. Currency convertibility failures restrict access to European and Chinese nacelle suppliers. Maracaibo's industrial corridor exhibits latent demand for hybrid wind-solar configurations that bypass grid interconnection queues.
Mérida State
Andean watersheds leverage pre-existing penstock infrastructure for small hydro rehabilitation at reduced civil works capital intensity. The national standards body applies adapted IEC frameworks to electrical safety protocols for run-of-river installations. Mountain communities around Mérida city retain mature margins where legacy hydro assets require modernization rather than greenfield construction.
Amazonas State
Rural electrification programs channel development finance toward photovoltaic installations displacing diesel generator dependence in off-grid communities. Ministry of Electric Power mandates prioritize politically prioritized electrification zones in indigenous territories. Puerto Ayacucho serves as the logistical hub for module distribution into remote riverine settlements.
Falcón State
Paraguaná Peninsula wind resources attract preliminary developer interest for coastal turbine deployment despite supply chain constraints. Corpoelec's operational collapse forces commercial consumers toward self-supply arrangements. Punto Fijo's oil refining complex represents a concentrated demand node for captive renewable generation.
Venezuela Renewable Energy Market Competitive Landscape
Global majors compete with regional champions across technology supply and installation services. The vendor base stratifies between European turbine manufacturers, Chinese module suppliers, and domestic EPC contractors with established local relationships. Three archetypes dominate: foreign technology licensors with brand recognition, regional installation networks with permitting expertise, and state-affiliated entities with legacy infrastructure control. Competitive moves concentrate on bilateral offtake contracting and direct equipment import relationships that bypass atrophied public procurement channels.
Among domestic specialists, SOLINAL C.A. and INGESOL C.A. occupy positions anchored in Venezuela's distributed generation expansion. SOLINAL C.A. exemplifies the regional installation network archetype through its utility-scale photovoltaic presence in sun-belt states. INGESOL C.A. represents the off-grid hybrid specialist segment with mining camp electrification expertise in Bolívar state. Siemens Gamesa Renewable Energy, S.A. anchors the foreign technology licensor tier with wind turbine adaptation capabilities for Caribbean coastal regimes.
| Leading Market Players |
|---|
| SOLINAL C.A. |
| INGESOL C.A. |
| Siemens Gamesa Renewable Energy, S.A. |
| Andritz AG |
| Corpoelec |
| Zelestra SL |
| Vestas Wind Systems A/S |
| HPC Venezuela CA |
| Orinoco Solar Corp |
| Others |
Value Network & Pricing Analysis
Polysilicon spot price volatility in China cascades through Venezuelan photovoltaic procurement, compressing module costs for mining operators while stranding residential buyers with currency-hedged premiums. Diesel arbitrage economics in Bolívar state create a dual-tier structure where industrial offtake secures containerized lithium iron phosphate systems at project rates, while rural electrification programs absorb inflated logistics markups through development finance subsidies.
Pricing Analysis
Input-cost pass-through from Chinese module manufacturers dominates Venezuelan pricing dynamics, with landed costs fluctuating on bolivar-dollar convertibility windows. Price differentiation hinges on certification tier—UL-listed inverters command substantial premiums over CE-marked alternatives—and volume scale, where Guayana mining consortiums secure pallet-rate pricing unavailable to fragmented commercial buyers. Pricing pressure stems from Corpoelec's operational collapse forcing bilateral negotiations that bypass standardized tariffs. Industrial buyers exhibit lowest price sensitivity due to diesel displacement economics, while residential segments in Amazonas face acute affordability constraints.
Supply Chain Analysis
Freight cost inflation through Caribbean transshipment ports elevates landed equipment costs for Venezuelan developers relative to Colombian or Peruvian counterparts. Geographic supply concentration centers on China for photovoltaic modules and lithium iron phosphate cells, with Germany and Spain contributing inverter and power electronics components. Raw material dependencies span polysilicon wafers, copper busbars, and rare-earth magnets for turbine generators. Single-source vulnerability pervades the inverter segment, where currency restrictions throttle access to European suppliers. Distribution runs through Brazilian and Colombian logistics hubs into Puerto Cabello and La Guaira, with final-mile deployment handled by domestic EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Venezuela's renewable energy market functions as a geographic-arbitrage play where diesel substitution economics in mining corridors offset regulatory opacity that would paralyze conventional power markets. The cost differential between subsidized residual fuel and unsubsidized solar-battery systems in Bolívar state generates payback thresholds unmatched elsewhere in Latin America.
For Market Incumbents: Hedge exposure to Corpoelec licensing volatility by deepening bilateral offtake relationships with aluminum smelters and cement plants in Ciudad Guayana. Prioritize backward integration into lithium iron phosphate assembly through regional partnerships that bypass import dependency for finished battery systems. Certification investment in UL-listed product lines defends margin position against Chinese competitors flooding the market with lower-tier alternatives. For New Entrants and Emerging Players: Enter via the Andean small hydro rehabilitation segment in Mérida and Táchira, where pre-existing penstock infrastructure reduces capital intensity and permitting friction. Target Caribbean coastal wind development in Zulia as the most penetrable geography, given unexploited resource profiles and latent industrial demand from Maracaibo's manufacturing corridor. Pursue direct equipment import relationships with Chinese module suppliers as the dominant go-to-market angle, circumventing atrophied state procurement channels. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic EPC contractors possessing established permitting expertise and Corpoelec relationship networks. Long-term viability over the next decade hinges on whether regulatory clarity on wheeling tariffs materializes or self-supply architectures permanently displace grid-connected investment. Acquisition targets should emphasize firms with proven mining camp electrification track records in Bolívar state. Monitor diesel subsidy elimination as the critical inflection signal for solar displacement economics.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Direct bilateral contracts with Guayana mining operators bypass Corpoelec interconnection queues entirely. |
| Technology Licensing for Wind Adaptation | Siemens Gamesa turbine designs calibrated for Caribbean coastal regimes unlock Zulia development potential. |
| Vertical Integration into Battery Assembly | Regional lithium iron phosphate cell production reduces import dependency and currency conversion exposure. |
| Small Hydro Rehabilitation Partnerships | Andean watershed infrastructure reuse in Mérida collapses civil works capital requirements versus greenfield construction. |
| Green Certification Program Development | International sustainability credentials attract ESG-mandated capital toward Venezuelan project finance. |
Research Methodology
Bottom-up mining electrification modeling reconciled against top-down module import tracking forms the analytical core of this study. Primary interviews with IPP project developers, EPC contractors in Bolívar state, aluminum smelter procurement officers, and Corpoelec planning officials supplied demand-side intelligence. Secondary validation drew from customs records, FERC-equivalent filings, IEA renewable energy databases, and project development registries. Top-down supply-side assessment triangulated against bottom-up installation capacity builds.
Input-output matrices mapped photovoltaic deployment by end-use segment against module supply flows from Chinese manufacturers across the projection horizon. Segmentation dimensions modeled include energy source, deployment architecture, end-user category, and technology type. CAGRs were derived through regression analysis of historical installation data and forward projection of diesel displacement economics. Key forecast inputs encompassed mining production schedules in the Orinoco Mining Arc and rural electrification mandate funding allocations.
Inputs from customs databases and project developer disclosures were available through the study window; gaps in Corpoelec operational data introduce uncertainty bands around grid-connected capacity forecasts. Forecasts reflect documented assumptions regarding currency convertibility and diesel subsidy persistence. Stakeholders should weight assumptions against their own operating context and risk tolerance for regulatory opacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Philippines Power Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Botswana Renewable Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Global Green Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Point Absorber Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Zimbabwe Renewable Energy Market