
 United States Power Transformer Market | 2026-2036
United States Power Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Power Transformer Market Analytics
Market Context
Texas is reshaping domestic power transformer demand through massive utility-scale solar and battery storage build-outs requiring stepped-up interconnection capacity. Siemens Energy leverages its domestic manufacturing footprint to capture utility procurement cycles, while Virginia Transformer Corporation anchors regional supply chains serving East Coast grid operators. General Electric Company competes on high-voltage direct current integration expertise for long-haul transmission projects.
Technical Definition and Segment Structure
A power transformer is a static electromagnetic device that transfers electrical energy between circuits through magnetic induction, typically operating at frequencies of 50-60 Hz with voltage ratings from 69 kV to 765 kV in US grid applications. Its primary purpose is to step voltage up for efficient long-distance transmission and step it down for safe distribution to end users. Oil-insulated units dominate installed base volumes due to superior thermal performance in utility-scale applications, while smart transformers represent the fastest-growing technology segment as grid operators deploy embedded sensors for real-time load monitoring and predictive maintenance. The above 500 MVA power rating category captures premium margin pools tied to generator step-up applications at combined-cycle natural gas and offshore wind interconnection points.
Regulatory Environment and Outlook
FERC Order 2023 reshapes interconnection queue management by requiring cluster studies and readiness deposits, directly accelerating transformer procurement timelines for developers seeking grid access. NERC reliability standards and EPA PCB regulations constrain material choices and end-of-life disposal protocols, while IEEE C57 series standards govern core construction and testing protocols. Stakeholders must monitor FERC rulemaking on regional transmission planning and state-level renewable portfolio standard acceleration as dual levers that will determine transformer specification requirements and procurement volumes across interconnection zones.
Market Dynamics
Interconnection queue backlogs are compressing procurement timelines as renewable developers face multi-year waits for transformer availability, forcing utilities to pre-position inventory before generator interconnection agreements finalize.
Growth Catalysts
- Offshore wind lease rounds:Atlantic Coast lease areas require collector substations with high-voltage step-up transformers, pulling forward demand from Massachusetts to North Carolina.
- IRA domestic content bonuses:The Inflation Reduction Act's tax credit adders incentivize US-manufactured core steel and winding assemblies, reshaping sourcing patterns for utility procurement teams.
- Data center load clusters:Hyperscale facilities in Northern Virginia and Phoenix are demanding dedicated substations with 500+ MVA units, creating non-correlated demand streams alongside traditional utility capex.
Market Restraints
- Grain-oriented electrical steel concentration:Domestic GOES supply remains captive to a single US producer and limited import quotas, constraining core manufacturing throughput.
- Copper price volatility:Winding material costs swing with commodity markets, compressing margin visibility for multi-year utility contracts.
- EPA PCB disposal protocols:End-of-life transformer retirement requires specialized handling and landfill restrictions, extending replacement cycles and complicating fleet renewal planning.
Strategic Opportunities
- Grid-enhancing technologies:Dynamic line rating and topology optimization software reduce nameplate transformer requirements, opening service revenue streams for OEMs.
- Texas ERCOT interconnection zones:West Texas solar and battery build-outs face transformer shortages, creating white space for regional inventory positioning.
- Remanufacturing and retrofill services:Aging infrastructure in the PJM footprint supports circular economy models for life extension and fluid replacement.
Industry Challenges
- Winding technician scarcity:Specialized craft labor for large power transformer assembly commands premium wages and extended training periods, constraining manufacturing expansion.
- Extended type-test durations:IEEE C57.12.00 compliance verification requires months of thermal and impulse testing, creating bottlenecks between production and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Power Transformer Market |
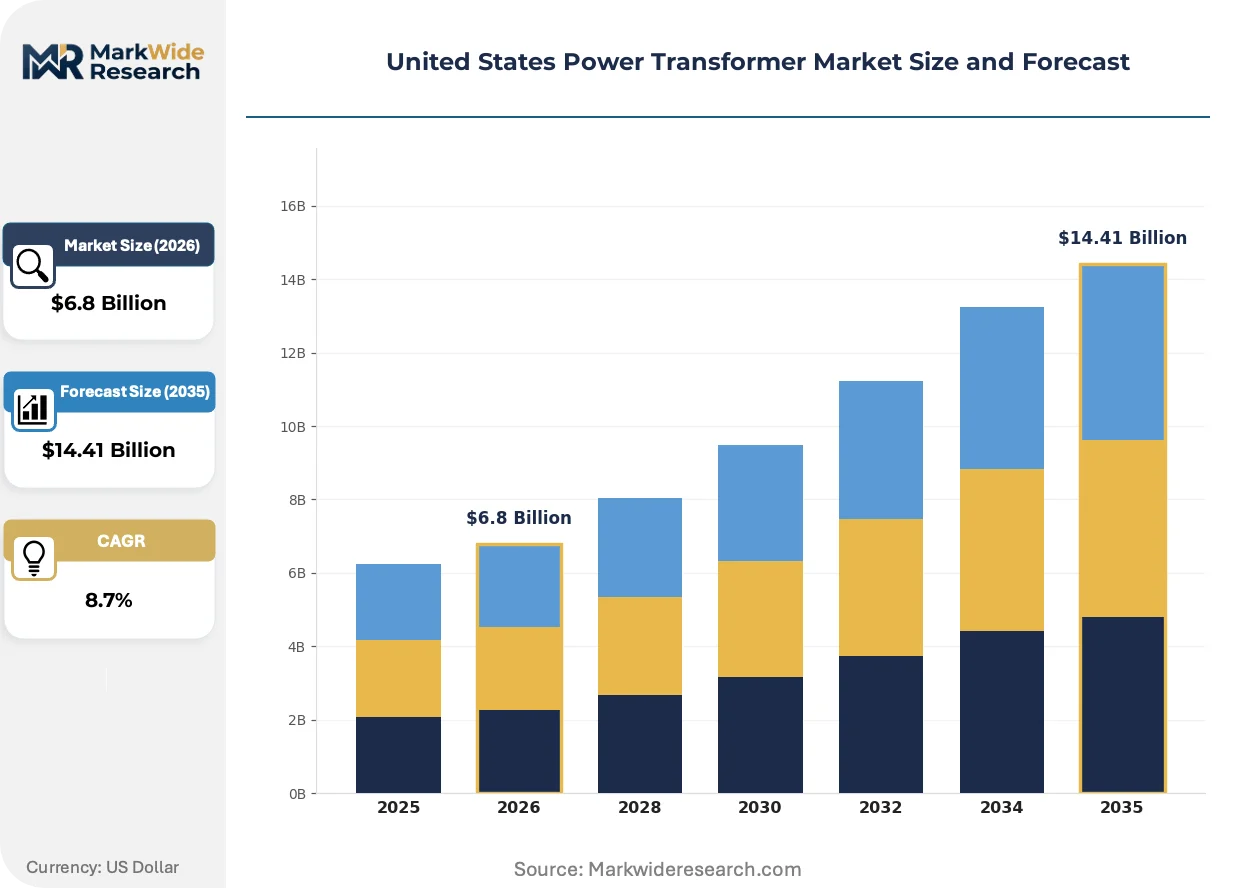
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Transmission Systems, Distribution Networks, Renewable Integration, Industrial Power Technology: Oil-Insulated, Dry-Type, Smart Transformers, Phase-Shifting Transformers Power Rating: Up to 100 MVA, 100-300 MVA, 300-500 MVA, Above 500 MVA End User: Utilities, Industrial Facilities, Renewable Energy Producers, Commercial Installations |
| Companies Covered | ABB, Hyundai Electric & Energy Systems, Siemens Energy, Eaton Corporation, Delta Star, General Electric Company, Mitsubishi Electric Corporation, Virginia Transformer Corporation, Hitachi Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Power Transformer Market Evolving Landscape
Digital instrumentation and alternative insulation chemistries are redefining transformer lifecycle economics, while procurement patterns shift toward performance-guaranteed service agreements rather than capital purchase models.
Natural ester insulating fluids are migrating from niche applications to mainstream utility specifications, offering superior fire safety and biodegradability compared to mineral oil. Southern California Edison and Pacific Gas and Electric are specifying these fluids for urban substations and wildland-urban interface zones. This chemistry shift is compressing the addressable market for conventional oil processing and reclamation services.
FERC Order 2023 mandates cluster studies and financial deposits for interconnection queue positions, accelerating transformer procurement timelines as developers seek to secure equipment before study completion. The rule compresses traditional planning cycles and forces equipment suppliers to commit capacity earlier in project development. Texas and California ISO zones are experiencing the most acute timeline compression.
Utility procurement teams are unbundling transformer supply from installation and commissioning, creating discrete vendor categories for OEMs, EPCs, and field service specialists. This disintermediation fragments supplier relationships and shifts risk allocation toward owner-operators. The pattern is most visible in municipal and cooperative utilities across the Southwest where in-house engineering capabilities support direct equipment purchasing.
United States Power Transformer Market Segmentation
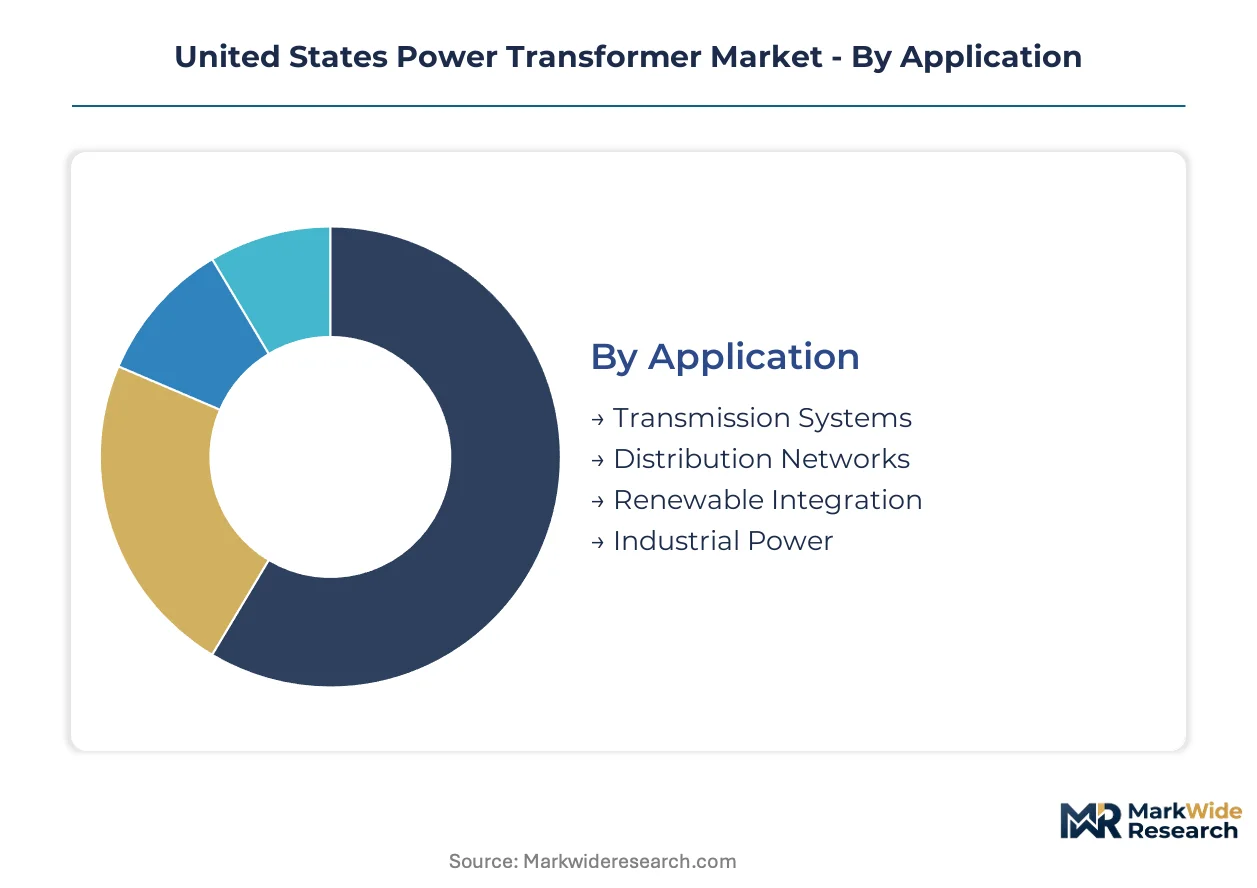
Power transformer procurement cycles vary dramatically across application contexts, with transmission utilities operating on decade-long replacement schedules while renewable developers face compressed 18-month delivery windows. Understanding these velocity differentials enables suppliers to align manufacturing capacity with cash flow profiles.
Application:
Transmission Systems turn over slowest due to asset longevity and regulatory approval cycles, while Renewable Integration moves fastest as interconnection queue deadlines force expedited procurement.
- Transmission Systems:Bulk power transfer between regional grids requires 345 kV to 765 kV step-up and step-down configurations. Demand concentrates in Texas and the PJM Interconnection where long-haul capacity expansion addresses renewable generation displacement. FERC Order 2023 cluster studies are compressing traditional planning timelines.
- Renewable Integration:Generator step-up transformers for solar and wind farms operate at 34.5 kV to 230 kV collector voltages. Texas ERCOT zones and California ISO territories face acute shortages as queue volumes strain manufacturing capacity. IRA domestic content bonuses reshape sourcing specifications.
- Distribution Networks:Substation and feeder-level units serving 69 kV to 138 kV urban infrastructure.
- Industrial Power:Dedicated substations for heavy manufacturing, petrochemical, and data center loads.
Transmission Systems dominate installed base. Renewable Integration is where expansion concentrates.
Technology:
Cost tiers separate mature oil-insulated designs from premium smart transformer platforms carrying embedded sensor suites and predictive analytics subscriptions.
- Oil-Insulated:Mineral oil or natural ester fluid provides superior thermal conductivity for utility-scale ratings above 100 MVA. Southern California Edison and Pacific Gas and Electric specify natural ester variants for wildland-urban interface zones. EPA PCB disposal protocols constrain end-of-life handling.
- Smart Transformers:Embedded fiber optic temperature monitoring, dissolved gas analysis, and tap changer diagnostics enable condition-based maintenance. Grid operators in Texas and PJM deploy these for critical path assets where failure carries cascading reliability consequences. Digital instrumentation commands 15-25% price premiums.
- Dry-Type:Cast resin or vacuum pressure impregnated windings for indoor commercial and industrial installations.
- Phase-Shifting Transformers:Power flow control devices for congested transmission corridors.
Oil-Insulated units anchor utility procurement volumes. Smart Transformers are gaining share fastest as reliability-centered maintenance programs expand.
Power Rating:
Volume concentrates in mid-range units while margin pools deepen at ratings above 500 MVA where manufacturing scarcity protects pricing.
- Above 500 MVA:Extra-high-voltage generator step-up transformers for combined-cycle natural gas plants and offshore wind collector platforms. Atlantic Coast lease areas from Massachusetts to North Carolina pull demand forward. Single-source procurement constraints limit supplier field.
- 300-500 MVA:Large industrial substations and urban transmission nodes serving data center clusters. Northern Virginia and Phoenix hyperscale facilities demand dedicated 500 MVA units. Lead times extend 24-36 months.
- 100-300 MVA:Standard utility substation workhorses for distribution and sub-transmission.
- Up to 100 MVA:Commercial, small industrial, and distributed generation interconnection.
100-300 MVA ratings dominate fleet population. Above 500 MVA is where supply tightness creates pricing power.
End User:
Customer type determines contract structure, with utilities favoring multi-year framework agreements and renewable developers accepting spot market premiums for delivery certainty.
- Utilities:Investor-owned, municipal, and cooperative grid operators responsible for transmission and distribution infrastructure. Texas utilities and PJM members face transformer availability constraints as renewable interconnection backlogs mount. Procurement teams unbundle supply from installation to shift risk.
- Renewable Energy Producers:Solar and wind developers requiring generator step-up transformers for interconnection. FERC Order 2023 readiness deposits force equipment commitment before study completion. Texas and California ISO zones experience the most acute timeline compression.
- Industrial Facilities:Heavy manufacturing, mining, and petrochemical operations with captive substations.
- Commercial Installations:Data centers, hospitals, and large commercial complexes with medium-voltage service.
Utilities anchor historical demand. Renewable Energy Producers are expanding most quickly as interconnection queues lengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2023 and the Infrastructure Investment and Jobs Act are reshaping transformer procurement geography across US interconnection zones. Texas, California, and PJM member states face acute equipment shortages as renewable queue volumes strain manufacturing capacity.
Texas
ERCOT's West Texas solar and battery build-outs demand stepped-up interconnection capacity. The state's competitive renewable energy zones program directs transmission investment toward generation clusters. Houston and Dallas-Fort Worth anchor utility procurement headquarters where transformer lead times now stretch beyond 24 months.
California
CPUC resource adequacy mandates and wildfire safety regulations accelerate grid hardening investments. The California ISO interconnection queue contains gigawatts of solar and storage awaiting transformer availability. Los Angeles Basin and Central Valley substations specify natural ester fluids for wildland-urban interface compliance.
PJM Interconnection States
Ohio, Pennsylvania, and Virginia face transformer scarcity as offshore wind lease areas from Massachusetts to North Carolina pull equipment inventories eastward. FERC Order 2023 cluster studies compress procurement timelines for Appalachian solar developers. Northern Virginia data center clusters demand dedicated 500 MVA substations.
Southwest
Arizona and New Mexico utilities expand transmission infrastructure to capture utility-scale solar economics. The IRA domestic content bonuses reshape sourcing specifications for Southwest procurement teams. Phoenix hyperscale facilities create non-correlated demand streams alongside traditional utility capex cycles.
Southeast
Florida and Georgia utilities modernize aging transformer fleets while accommodating distributed solar growth. NERC reliability standards govern replacement protocols for coastal substations exposed to hurricane risk. Atlanta and Charlotte anchor regional engineering centers serving municipal and cooperative grid operators.
United States Power Transformer Market Competitive Landscape
Vertically integrated multinationals and regional specialists split the market along voltage rating and service capability lines. Siemens Energy leverages domestic manufacturing footprints to capture utility procurement cycles, while Virginia Transformer Corporation anchors East Coast supply chains. General Electric Company competes on high-voltage direct current integration expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves as lead times extend.
Among US-based fabricators, Virginia Transformer Corporation exemplifies regional supply chain anchoring for East Coast grid operators. Siemens Energy occupies a position as a vertically integrated multinational with domestic production capabilities. General Electric Company represents the technology-licensing archetype through HVDC integration specialization. These three entities illustrate the strategic positioning spectrum from regional focus to global scale.
| Leading Market Players |
|---|
| ABB |
| Hyundai Electric & Energy Systems |
| Siemens Energy |
| Eaton Corporation |
| Delta Star |
| General Electric Company |
| Mitsubishi Electric Corporation |
| Virginia Transformer Corporation |
| Hitachi Energy |
| Others |
Value Network & Pricing Analysis
ERCOT interconnection zone undercapacity drives transformer suppliers toward advance payment structures and indexed material clauses, compressing buyer negotiating leverage while pushing procurement teams toward multi-year framework agreements.
Pricing Analysis
Texas-to-California price spreads for 500 MVA units now exceed 20% as regional supply tightness and logistics costs create geographic arbitrage. Project-based transactional pricing dominates utility procurement, with customization level and FERC compliance certification tier serving as primary differentiation drivers. Pricing pressure stems from grain-oriented electrical steel scarcity, forcing margin compression across mid-range ratings. Renewable developers exhibit highest price sensitivity due to interconnection deadline penalties, while data center operators absorb premiums for delivery certainty.
Supply Chain Analysis
Domestic contract manufacturing concentrates at Virginia Transformer Corporation facilities in Virginia and Pennsylvania, with Siemens Energy anchoring Texas and Georgia production hubs. The supply chain draws from US grain-oriented electrical steel, Mexican copper windings, and Canadian insulating fluid feedstocks. Single-source vulnerability in domestic GOES production creates structural exposure to import quota restrictions. Distribution runs through utility procurement headquarters in Houston, Dallas-Fort Worth, and Northern Virginia, with EPC contractors handling field installation and commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from grid-enhancing technologies that reduce nameplate transformer requirements through dynamic line rating and topology optimization software.
For Market Incumbents: Harden captive supply positions in grain-oriented electrical steel through backward integration or long-term offtake agreements with domestic producers. Secure winding technician pipelines through apprenticeship partnerships with technical colleges in Texas and Pennsylvania. Vertical integration into remanufacturing services defends against circular economy entrants targeting PJM fleet renewal cycles.
For New Entrants and Emerging Players: Establish a beachhead in Texas ERCOT West solar zones where transformer shortages create white-space procurement opportunities. Target renewable developers facing FERC Order 2023 readiness deposit deadlines with expedited delivery guarantees and lease-to-own financing structures. Partner with regional EPC contractors to unbundle supply from installation and capture direct procurement relationships with municipal utilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart transformer OEMs with embedded sensor subscriptions and predictive maintenance contracts. Five-to-ten year viability favors suppliers with domestic core steel sourcing and certified remanufacturing capabilities. Monitor FERC regional transmission planning rulemaking as the critical inflection signal for procurement volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Compliance Program | IRA bonus capture requires certified US-manufactured core steel and winding assemblies. |
| Smart Transformer Platform Launch | Embedded fiber optic monitoring commands 15-25% price premiums from Texas and PJM grid operators. |
| Remanufacturing Service Expansion | PJM aging fleet renewal supports circular economy revenue streams and EPA PCB compliance. |
| Winding Technician Pipeline Development | Apprenticeship partnerships with Texas and Pennsylvania technical colleges address craft labor scarcity. |
| Natural Ester Fluid Certification | Southern California Edison and Pacific Gas and Electric specifications open wildland-urban interface markets. |
Research Methodology
Cross-validation between utility procurement officer interviews and FERC interconnection queue databases anchors the qualitative findings in this analysis. Primary fieldwork encompassed transformer planning directors at investor-owned utilities, renewable developer project managers, EPC contractor procurement leads, and OEM sales executives across Texas, California, and PJM territories. Secondary sources included EIA Form 860 generator data, FERC Order 2023 docket filings, IEEE C57 standards documentation, and utility integrated resource plans. Bottom-up unit demand modeling triangulated against top-down transmission investment forecasts.
Calibration against historical procurement cycles and material cost indices shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed application context, insulation technology, power rating tier, and end-user archetype. CAGRs derived from regression analysis of utility capex trajectories and renewable interconnection queue velocities. Industry-specific inputs incorporated grain-oriented electrical steel capacity utilization and FERC cluster study completion rates.
Stress conditions across copper price volatility, GOES import quota restrictions, and FERC rulemaking timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding IRA domestic content bonus permanence and NERC reliability standard enforcement intensity. Quarterly review of ERCOT interconnection zone transformer lead times and PJM offshore wind procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
India Distribution Transformer Market
Transformers
Rectifier Transformers Market
Transformers
Europe Distribution Transformer Market
Transformers
Green Power Transformers Market
Transformers
Smart Transformer Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Neon Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
Global Transformer Market
Transformers
North America Power Transformer Market
Transformers
North America Dry Type Transformer Market
Transformers
China Transformer Market
Transformers
Three Phase Transformer Market
Transformers
Power Transformer Market
Transformers
Current Transformer Market
Transformers
Europe Smart Transformers Market