
 Global Electrical SCADA Market | 2026-2036
Global Electrical SCADA Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrical SCADA Market Analysis
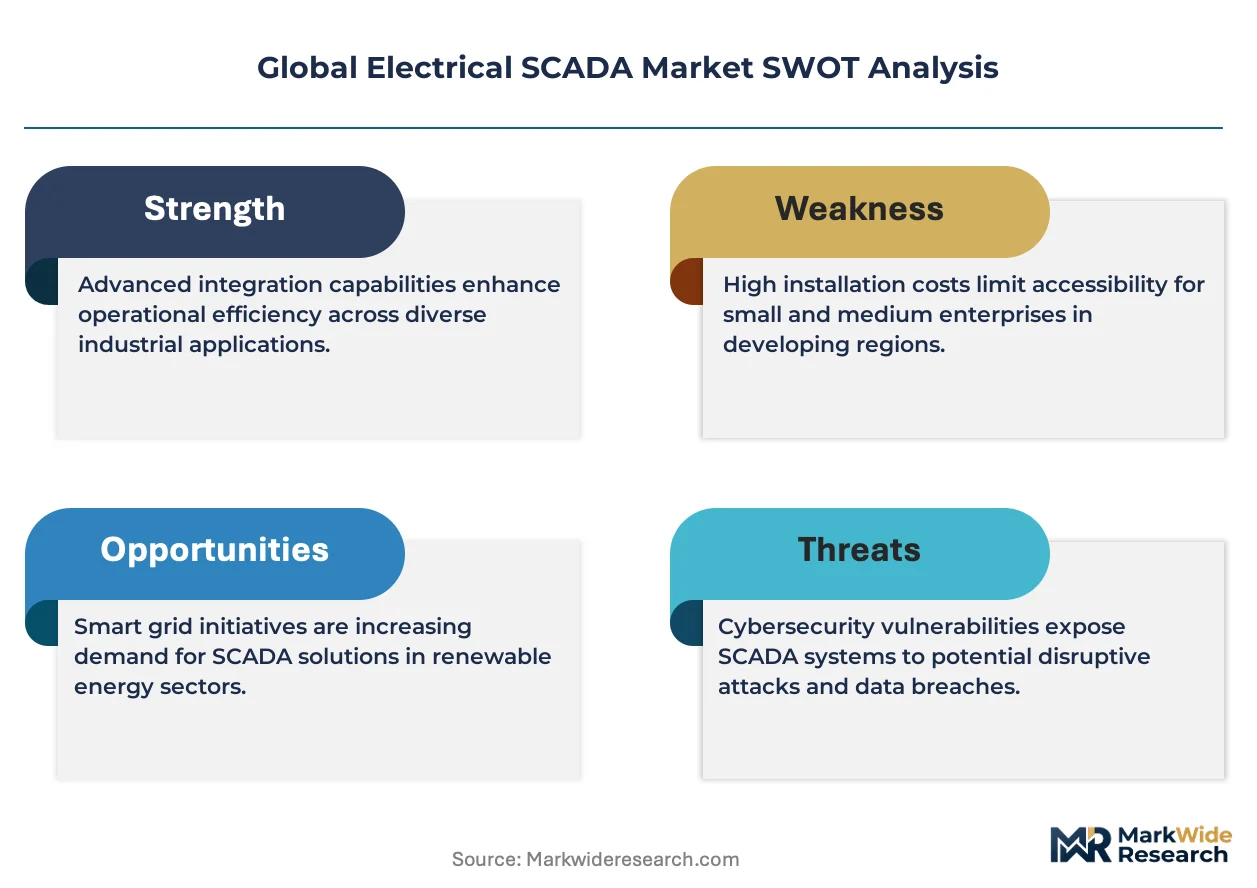
IEC 61850 certification is bifurcating the competitive landscape into qualified system integrators and legacy vendors facing recertification costs. Schneider Electric leverages its Triconex safety systems heritage to dominate high-availability power generation installations. ABB sustains technology leadership through its Ability platform integration with substation automation protocols. Siemens anchors European utility relationships with its Spectrum Power portfolio and deep IEC portfolio compliance.
Electrical SCADA denotes supervisory control and data acquisition systems purpose-built for electric power infrastructure, integrating remote terminal units, programmable logic controllers, and human-machine interfaces with sub-100-millisecond polling cycles for fault detection and load dispatch. The hardware segment retains the largest revenue share due to persistent on-premise deployment preferences among critical infrastructure operators, though cloud-based deployment is expanding fastest as utilities pilot virtualized control centers. Services and integration capture disproportionate margin pools as cybersecurity hardening and legacy protocol migration demand specialized engineering labor.
NERC CIP standards in the United States, IEC 61850 and GDPR in Europe, and India's CEA grid codes collectively elevate compliance spending and restrict vendor eligibility to certified participants. The EU AI Act introduces additional algorithmic transparency requirements for automated grid decision systems. Stakeholders must monitor evolving cybersecurity mandates and cloud sovereignty rules as determinants of deployment architecture selection and partnership strategy.
Market Dynamics
Cloud-native SCADA architectures are compressing deployment timelines from years to months, forcing incumbent vendors to reengineer legacy platforms while utilities demand subscription economics over perpetual licenses.
Growth Catalysts
- IEC 61850 Mandates:European grid codes require protocol interoperability for new substation installations, creating replacement demand for proprietary legacy systems.
- India's National Grid Modernization:CEA technical standards for transmission automation are accelerating SCADA procurement across state electricity boards.
- Edge Computing Integration:Distributed intelligence at remote terminal units reduces latency for fault isolation, driving hardware refresh cycles.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries dominate industrial-grade processor fabrication, exposing SCADA OEMs to allocation risk.
- Cybersecurity Certification Costs:NERC CIP compliance in the United States requires dedicated security operations centers, elevating total cost of ownership.
- Copper and Rare Earth Volatility:Magnet materials for RTU enclosures and cabling face price swings that compress hardware margins.
Strategic Opportunities
- Virtualized Control Centers:Brazilian utilities are piloting cloud-hosted SCADA to defer capital expenditures on physical control rooms.
- EU AI Act Alignment:Automated grid decision systems require algorithmic transparency documentation, creating services revenue for compliance engineering.
- Digital Twin Convergence:Integration with 3D substation modeling enables predictive maintenance workflows in German transmission networks.
Industry Challenges
- IEC 61850 Engineer Scarcity:Protocol certification programs produce fewer qualified integrators than deployment pipelines require.
- Multi-Protocol Integration:DNP3, Modbus, and IEC 60870-5-104 coexistence demands complex middleware development for brownfield sites.
- Cloud Sovereignty Requirements:German KRITIS regulations mandate domestic data residency, complicating hybrid architecture design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrical SCADA Market |
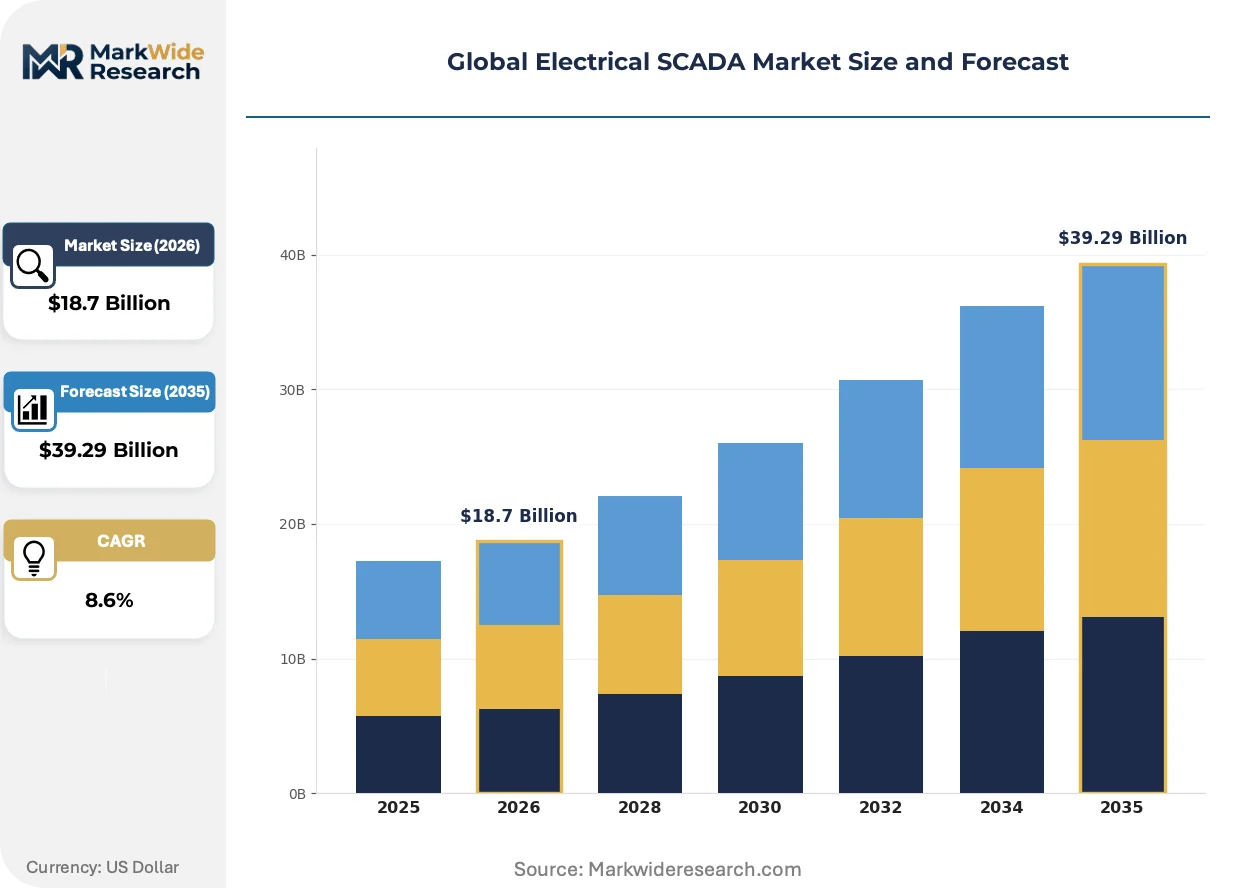
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Integration Deployment: On-Premise, Cloud-Based, Hybrid, Remote End User: Utilities, Manufacturing, Oil & Gas, Power Generation Application: Grid Management, Asset Monitoring, Energy Management, Process Control |
| Companies Covered | Schneider Electric, Rockwell Automation, ABB, Siemens, Emerson Electric, Honeywell International, General Electric, Yokogawa Electric, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrical SCADA Market Emerging Trajectories
Containerized SCADA software is decoupling control logic from proprietary hardware, enabling utilities to source compute infrastructure independently and compress vendor lock-in.
Time-sensitive networking over standard Ethernet is supplanting fieldbus architectures in substation automation. German transmission operators are retrofitting protection relays with TSN-capable interfaces. This convergence collapses cabling complexity and merges IT-OT network management under unified cybersecurity policies.
REACH restrictions on perfluorinated compounds are accelerating enclosure material transitions for outdoor RTU deployments. European manufacturers are qualifying aluminum and engineered polymer alternatives. The F-Gas Regulation adds pressure to eliminate SF6 insulation in switchgear integrated with SCADA monitoring.
Subscription-based SCADA licensing is displacing perpetual ownership models among North American municipal utilities. Managed service providers absorb lifecycle maintenance and cybersecurity patching. This shift concentrates buying power with procurement departments previously excluded from technical vendor selection.
Global Electrical SCADA Market Segmentation
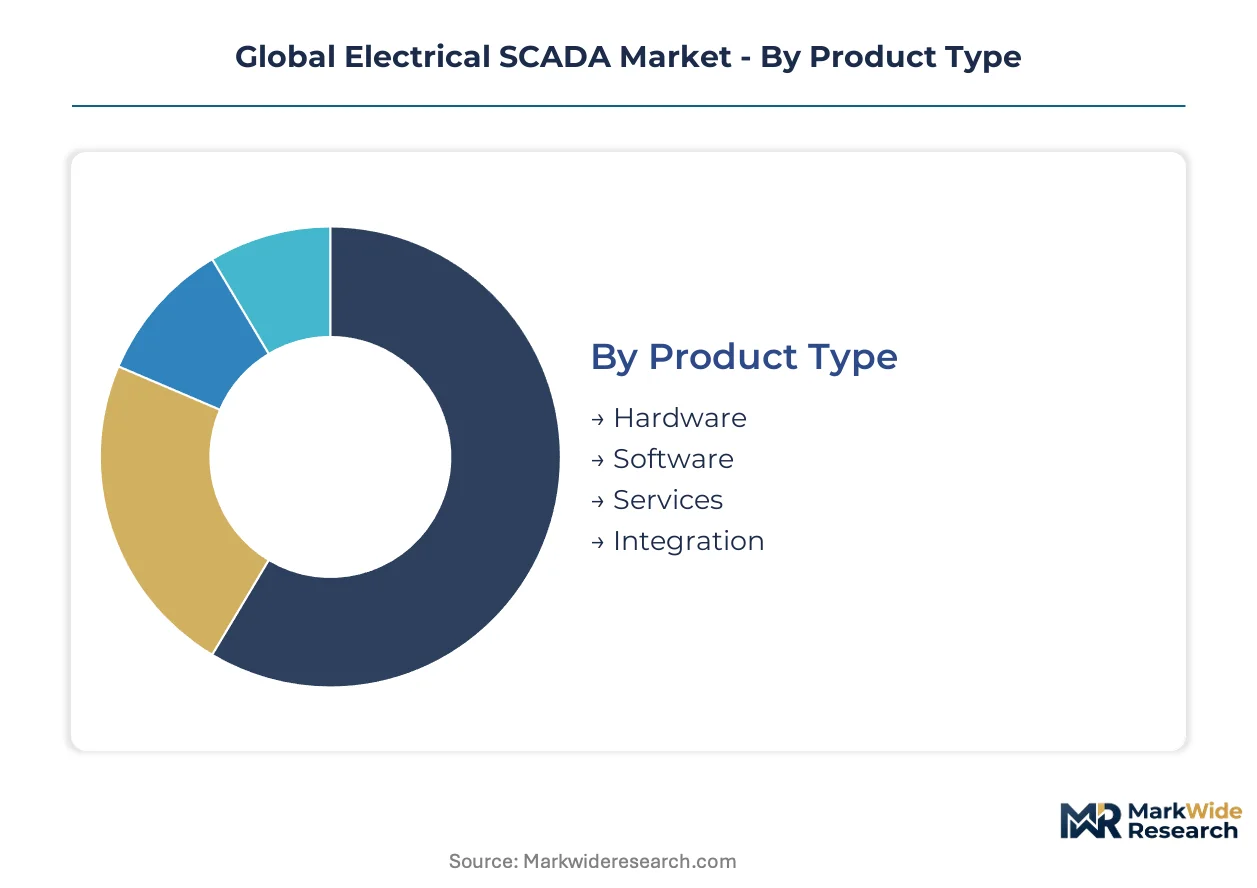
Electrical SCADA procurement patterns diverge sharply across deployment architectures and end-user risk profiles. Understanding these fault lines clarifies where substitution threats from OT cybersecurity platforms and edge-native control systems are eroding traditional revenue pools.
Product Type:
Software and services segments face acute substitution pressure from industrial IoT platforms offering SCADA-like functionality through API-first architectures. Hardware retains defensive moats through safety-certification requirements.
- Hardware:Comprises remote terminal units, programmable logic controllers, and industrial-grade servers with sub-100-millisecond polling cycles. Demand concentrates in German transmission network upgrades where KRITIS regulations mandate certified physical control systems with domestic data residency guarantees.
- Software:Encompasses HMI platforms, historian databases, and alarm management systems with containerized deployment options. Indian state electricity boards are piloting subscription licensing to defer capital expenditures, accelerating displacement of perpetual-license models.
- Services:Engineering labor for cybersecurity hardening and legacy protocol migration. The EU AI Act elevates algorithmic transparency documentation requirements, expanding compliance engineering contracts.
- Integration:System commissioning and multi-protocol middleware development. Brownfield sites in the United States require DNP3-IEC 61850 gateways for NERC CIP-compliant upgrades.
Hardware anchors the volume base while software gains share at the steepest rate.
Deployment:
Cost-tier segmentation separates capital-intensive physical control rooms from operating-expense-friendly virtualized alternatives. Municipal utilities in North America favor subscription economics while critical infrastructure operators absorb higher TCO for air-gapped architectures.
- On-Premise:Physically isolated control centers with dedicated server infrastructure and 24/7 manned operations. US nuclear and hydroelectric facilities require NERC CIP-compliant deployments with dedicated security operations centers.
- Cloud-Based:Virtualized control centers hosted on utility-managed or third-party infrastructure. Brazilian transmission operators are deferring capital expenditures through pilot programs with domestic cloud sovereignty guarantees.
- Hybrid:Split architectures retaining critical control functions on-premise while shifting data analytics and historical storage to cloud environments. German utilities navigate KRITIS regulations through tiered data classification strategies.
- Remote:Satellite or cellular-connected RTU deployments for geographically dispersed assets. Indian rural electrification programs rely on VSAT-linked monitoring for distribution transformer health.
On-premise retains the dominant revenue share while cloud-based deployment climbs the fastest as procurement departments gain technical influence.
End User:
Application maturity varies dramatically across verticals, with power generation demanding five-nines availability while manufacturing prioritizes cost-optimized process visibility over real-time control.
- Utilities:Transmission and distribution operators managing regional grid balancing and outage response. Germany, the United States, and India are expanding digitization programs with IEC 61850-compliant substation automation.
- Power Generation:Thermal, renewable, and nuclear facilities requiring safety-integrated control systems. High-availability installations specify Triconex-certified architectures with redundant controller configurations.
- Oil & Gas:Pipeline compressor stations and terminal automation requiring explosion-proof RTU enclosures. REACH restrictions on perfluorinated compounds are accelerating aluminum and engineered polymer enclosure transitions.
- Manufacturing:Industrial facilities integrating electrical SCADA with building energy management. Demand concentrates in energy-intensive sectors seeking load dispatch optimization for demand response programs.
Utilities command the largest procurement volume while power generation delivers the highest margin per installation.
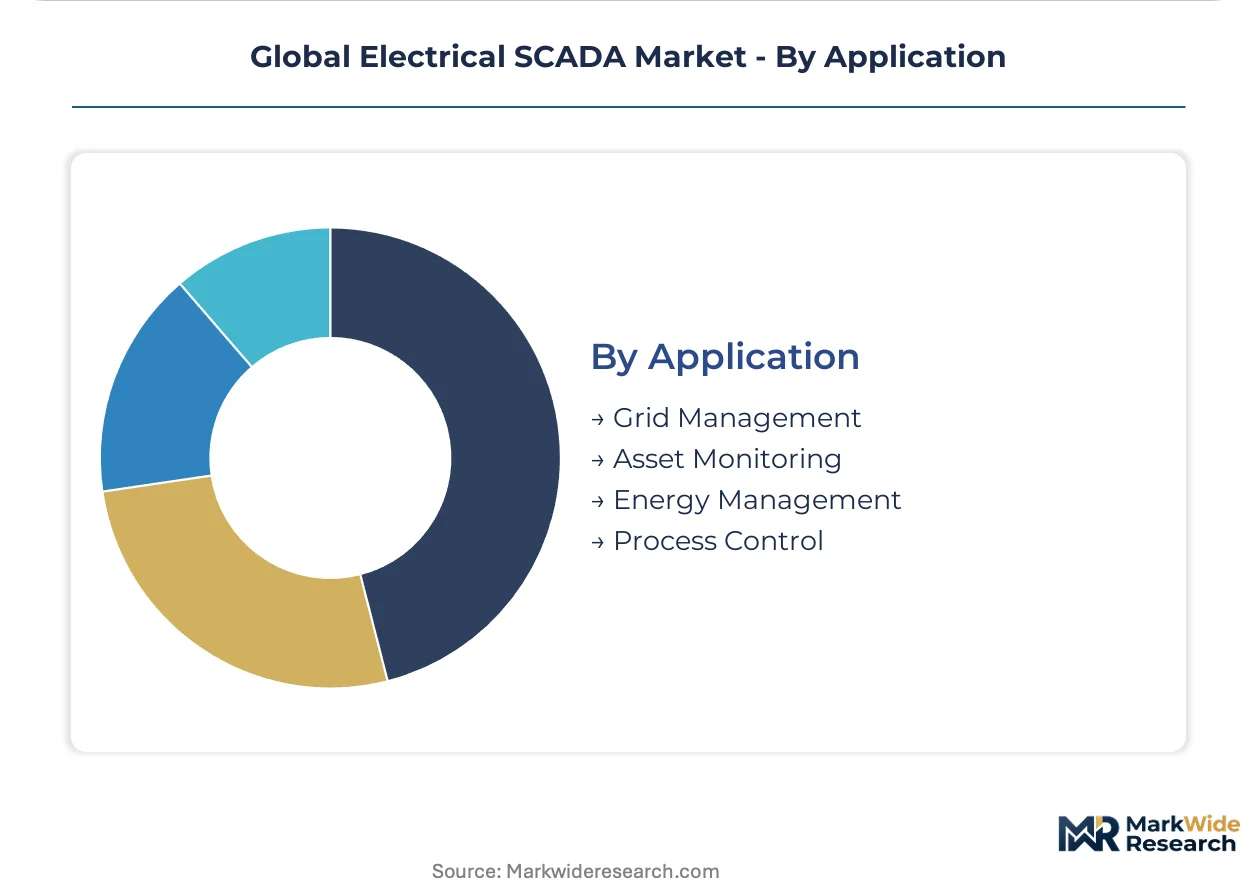
Application:
Functional segmentation tracks the progression from reactive fault management toward predictive asset strategies, with data-intensive applications requiring more sophisticated integration architectures.
- Grid Management:Real-time monitoring of transmission topology, automatic generation control, and load-frequency regulation. German transmission operators are deploying time-sensitive networking to collapse IT-OT cabling complexity.
- Asset Monitoring:Condition-based maintenance of transformers, switchgear, and protection relays through dissolved gas analysis and thermal imaging integration. Digital twin convergence with 3D substation modeling enables predictive workflows.
- Energy Management:Demand response coordination, renewable curtailment optimization, and wholesale market participation. F-Gas Regulation pressure is eliminating SF6-insulated switchgear from monitored asset portfolios.
- Process Control:Direct closed-loop control of generation output and voltage regulation. Safety-critical loops retain hardwired backup systems independent of SCADA networks.
Grid management absorbs the majority of current deployment spend while asset monitoring expands most quickly through digital twin integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NERC CIP compliance mandates and EU grid modernization funding are redirecting procurement toward certified system integrators. Germany, the United States, India, Brazil, and Japan concentrate deployment activity through distinct regulatory pathways and infrastructure investment cycles.
Germany
Transmission network digitization and KRITIS critical infrastructure regulations drive hardware demand for certified physical control systems. The EU AI Act imposes algorithmic transparency requirements on automated grid decision systems. The Rhine-Ruhr industrial corridor hosts concentrated substation automation upgrades with IEC 61850-compliant architectures.
United States
Utilities accelerate SCADA deployments to modernize aging grid infrastructure and meet NERC CIP cybersecurity standards. FERC Order 2222 enables distributed energy resource aggregation, expanding monitoring requirements. Texas and California transmission operators lead procurement volumes for high-availability control center installations.
India
State electricity boards expand transmission automation under CEA technical standards for national grid modernization. The PLI scheme incentivizes domestic manufacturing of power sector equipment. Maharashtra and Gujarat host the most active substation digitization programs with VSAT-linked rural distribution monitoring.
Brazil
Transmission operators pilot cloud-hosted SCADA architectures to defer capital expenditures on physical control rooms. ANEEL regulatory frameworks accommodate virtualized control center trials with domestic data sovereignty guarantees. The Southeast region around São Paulo anchors deployment activity for grid balancing infrastructure.
Japan
Utilities retrofit protection relays with time-sensitive networking interfaces under METI grid resilience initiatives. JIS standards compliance shapes procurement criteria for substation automation hardware. The Kanto region surrounding Tokyo concentrates demand for earthquake-resistant control system installations.
Global Electrical SCADA Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with safety-systems heritage and specialized automation vendors. The competitive structure concentrates around three strategic archetypes: integrated platform providers leveraging cloud-native architectures, safety-certified specialists dominating high-availability installations, and regional system integrators capturing compliance-driven replacement cycles. Dominant competitive moves include strategic partnerships for cybersecurity hardening capabilities and portfolio diversification into digital twin integration services.
Within the integrated platform tier, Schneider Electric, ABB, and Siemens occupy positions shaped by distinct geographic anchoring and protocol compliance strategies. Schneider Electric leverages its Triconex safety systems lineage to exemplify high-availability power generation positioning. ABB represents the cloud-native integration archetype through its Ability platform convergence with substation automation protocols. Siemens anchors European utility relationships through deep IEC portfolio compliance and regional manufacturing presence.
| Leading Market Players |
|---|
| Schneider Electric |
| Rockwell Automation |
| ABB |
| Siemens |
| Emerson Electric |
| Honeywell International |
| General Electric |
| Yokogawa Electric |
| Hitachi |
| Others |
Supply Flow & Price Mechanics
Industrial-grade processor fabrication scale in Taiwan and South Korea shapes both supply concentration and price floors for SCADA hardware, as foundry utilization rates above 85% sustain premium pricing for safety-certified controllers while compressing margins for non-certified alternatives.
Pricing Analysis
Certification level creates the primary spread between NERC CIP-compliant installations and standard industrial deployments. Three-tier pricing structure across safety-certified, IEC 61850-compliant, and legacy protocol systems reflects cybersecurity hardening costs. Subscription licensing for cloud-native platforms is displacing perpetual licenses as Brazilian and Indian utilities prioritize operating expenditure flexibility. Municipal utilities in North America exhibit highest price sensitivity due to procurement department influence, while nuclear and hydroelectric facilities absorb premium pricing for air-gapped architectures.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for industrial-grade processors, while China and Germany concentrate PLC and RTU final assembly. Copper magnet wire, rare earth permanent magnets, and engineered polymer enclosures constitute critical input dependencies. Single-source vulnerability in Taiwan-based foundry capacity exposes OEMs to allocation risk during semiconductor demand surges. Distribution runs through authorized system integrators with IEC 61850 certification, bypassing direct OEM sales for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as cloud-native architectures and edge computing integration create specialized niches beyond incumbent platform dominance. Procurement department empowerment and subscription economics are fragmenting traditional vendor-buyer relationships.
For Market Incumbents: Fortify high-availability positioning through deeper Triconex safety system integration and captive cybersecurity operations center capacity. Certification moats around IEC 61850 compliance resist substitution from industrial IoT platforms. Vertical integration into edge computing hardware preserves margin pools as containerized software decouples control logic from proprietary servers.
For New Entrants and Emerging Players: Anchor in Brazilian cloud-hosted SCADA pilots and Indian state electricity board subscription programs where incumbent relationships remain underdeveloped. Managed service provider partnerships bypass direct competition with Schneider Electric, ABB, and Siemens in European transmission markets. API-first architectures targeting brownfield protocol gateway development exploit multi-protocol integration complexity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers absorbing lifecycle maintenance and cybersecurity patching for municipal utilities. Long-term viability centers on compliance engineering capabilities as EU AI Act documentation requirements expand services revenue. Acquisition target archetype: regional system integrators with IEC 61850 certification backlog and utility relationships in Germany or India. Signal to watch: cloud sovereignty regulation proliferation mandating domestic data residency.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Containerized SCADA software decouples control logic from proprietary hardware, reducing vendor lock-in. |
| Strategic Partnership | Cybersecurity hardening alliances address NERC CIP compliance costs elevating total cost of ownership. |
| Acquisition of Specialist Firm | Digital twin integration capabilities enable predictive maintenance workflows in German transmission networks. |
| Geographic Expansion | Cloud-hosted pilots in Brazil defer capital expenditures while satisfying ANEEL data sovereignty requirements. |
| Product Launch | Time-sensitive networking interfaces collapse IT-OT cabling complexity for Japanese protection relay retrofits. |
Methodological Framework
A spread of perspectives from utility planning officers, SCADA system integrators, cybersecurity operations center managers, and industrial automation procurement leads converged on the working assumptions. Primary interviews combined with secondary validation from FERC filings, IEC standards documentation, CEA technical specifications, and utility capital expenditure disclosures. Bottom-up installation tracking across German transmission operators, US regional transmission organizations, and Indian state electricity boards triangulated against top-down market sizing.
Segmentation dimensions modeled span deployment architecture, end-user vertical, application function, and regional regulatory framework across the analysis window. Product type splits between hardware, software, services, and integration captured divergent margin pools. CAGRs derived from utility capital expenditure trajectories, grid modernization program announcements, and certification requirement implementation timelines. Edge computing integration intensity and cloud-native adoption curves served as industry-specific forecast inputs.
Material uncertainties — semiconductor allocation disruptions, cybersecurity mandate acceleration, and rare earth price volatility — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and utility procurement cycle normalization. Recalibration cycles align with material shifts in IEC 61850 adoption rates and cloud sovereignty rule proliferation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Carbon Brush Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Protective Relay Market