
 Australia Battery Market | 2026-2036
Australia Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Battery Market Outlook
Aftermarket service revenue is narrowing as original equipment manufacturers embed longer-cycle warranties and remote diagnostics into lithium-ion offerings. Century Yuasa Batteries leverages its nationwide distribution network to sustain aftermarket parts availability for legacy lead-acid fleets. Energy Renaissance anchors domestic cell assembly capacity through its Tomago facility near Newcastle. Magnis Energy Technologies differentiates via upstream graphite anode production from its Nachu project in Tanzania, feeding Australian cell manufacturing.
Australia batteries encompass electrochemical energy storage devices ranging from cylindrical 18650 lithium-ion cells to containerized flow battery systems with megawatt-hour capacity ratings, designed to convert chemical energy into electrical potential through reversible redox reactions for grid stabilization, transport electrification, and portable power applications. Lithium-ion chemistry dominates utility-scale procurement due to declining cell costs and proven cycle life exceeding 6,000 cycles at 80% depth of discharge. Solid-state technology occupies emerging R&D pipelines as developers target energy densities above 400 Wh/kg for aviation and defense applications. Lead-acid retains cost advantages in backup power systems where weight and energy density matter less than capital expenditure minimization.
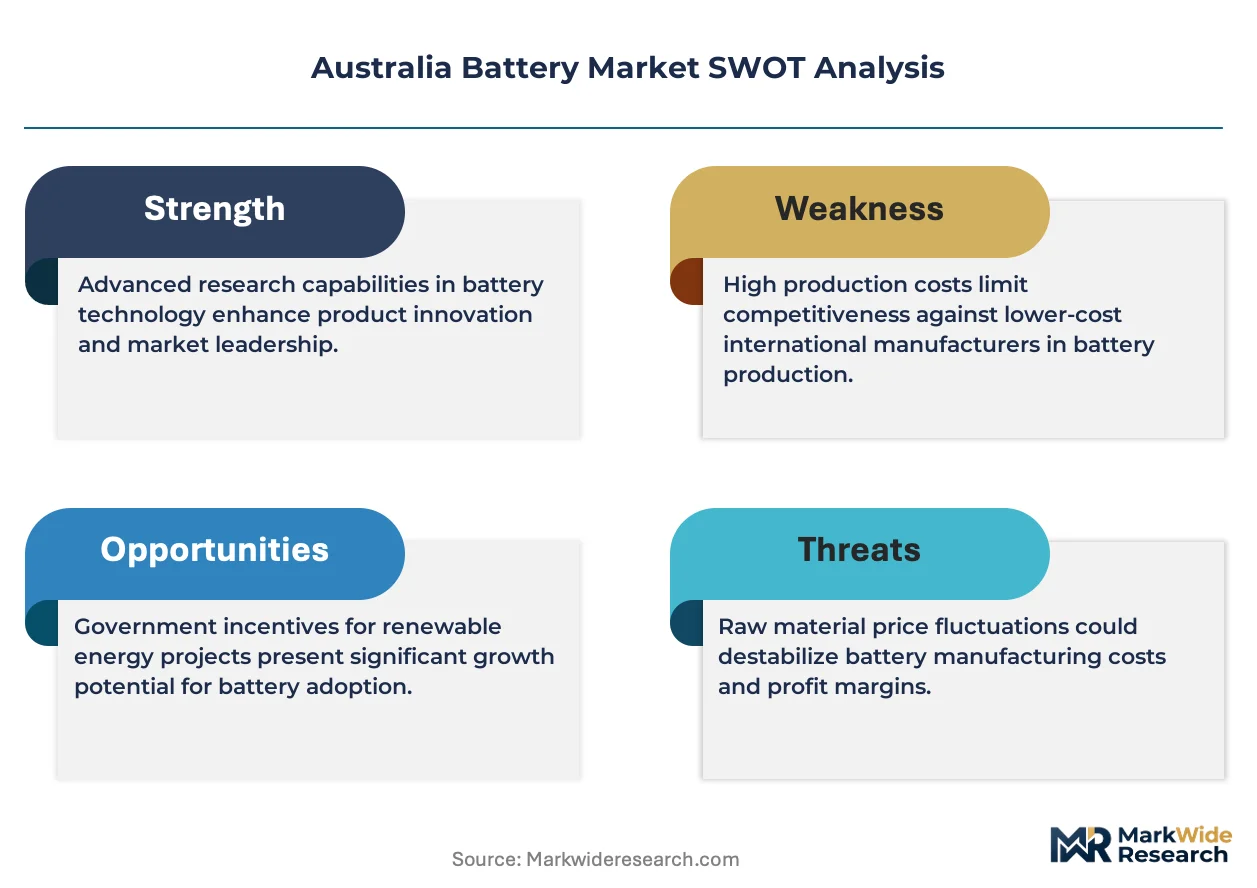
The Australian Energy Market Operator enforces connection standards that mandate grid-forming inverter capabilities for new battery installations, while the Clean Energy Regulator administers Large-scale Generation Certificate eligibility rules shaping revenue stacking strategies. State-level planning reforms in Victoria and New South Wales impose minimum storage durations for renewable energy zone allocations, directly influencing technology selection between lithium-ion and flow batteries. Stakeholders must monitor the evolution of capacity mechanism designs and inertia services markets, as these will determine which battery technologies capture the most attractive revenue streams in Australia's transitioning power system.
Market Dynamics
Australian battery procurement is pivoting toward grid-forming inverters as AEMO mandates reshape connection standards, compressing technology windows for legacy equipment and concentrating supplier capability around synchronous condenser alternatives.
Growth Catalysts
- Renewable Energy Zone mandates:Victoria and New South Wales impose minimum storage durations for zone allocations, forcing developers toward longer-duration chemistries.
- CEFC concessional debt:The Clean Energy Finance Corporation's financing instruments reduce weighted average cost of capital for utility-scale projects.
- Queensland solar arbitrage:Evening peak pricing spreads in solar-rich zones accelerate co-located storage deployment.
Market Restraints
- Graphite supply concentration:Spherical graphite anode material concentrates among Chinese processors, exposing Australian cell manufacturers to feedstock bottlenecks.
- Grid connection queues:AEMO's rigorous grid-forming certification timelines extend project commissioning by 12-18 months.
- Flow battery capex premiums:Vanadium redox systems carry 40-60% higher upfront costs versus lithium-ion at equivalent duration.
Strategic Opportunities
- Western Australia mining microgrids:Remote mine sites with diesel displacement mandates represent underpenetrated demand for containerized storage.
- ARENA grant stacking:The agency's funding programs enable revenue model innovation through combined frequency response and energy arbitrage.
- Solid-state aviation applications:Defense and regional aviation sectors target 400 Wh/kg energy density thresholds for electric propulsion.
Industry Challenges
- Power systems engineering talent:Grid-forming inverter expertise concentrates among a handful of specialized consultancies.
- Revenue stacking complexity:Developers must optimize across FCAS markets, wholesale arbitrage, and certificate schemes simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Battery Market |
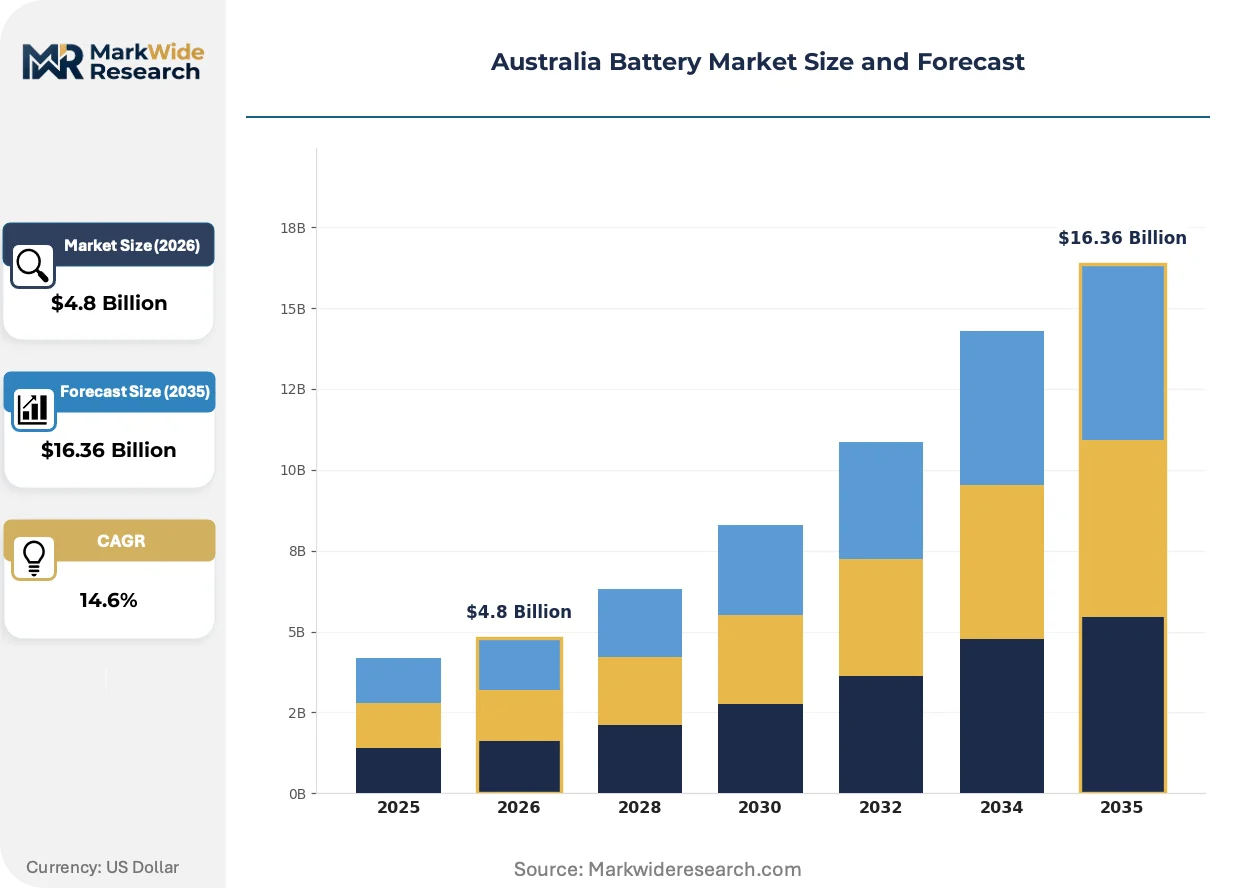
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Sodium-ion Application: Electric Vehicles, Renewable Energy Storage, Portable Electronics, Backup Power Systems End User: Consumer Electronics, Automotive, Industrial, Grid Storage Technology: Solid State, Flow Batteries, Ultra-capacitors, Thermal Storage |
| Companies Covered | Custom Lithium, Lithium Battery Systems, Energy Renaissance, PowerPlus Energy, Century Yuasa Batteries, Magnis Energy Technologies, Maximus Lithium Batteries, Magellan Power, Lithium Batteries Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Battery Market Strategic Shifts
Technology trajectories in Australian batteries are compressing around three vectors: chemistry evolution, regulatory stringency, and procurement sophistication. Each force is reshaping how projects secure financing and grid access.
Lithium iron phosphate chemistry is collapsing the competitive window for nickel-manganese-cobalt alternatives in Australian utility procurement. Developers favor LFP for its thermal stability and cycle life exceeding 6,000 cycles at 80% depth of discharge. AEMO's grid-forming requirements favor inverters paired with stable chemistries, accelerating LFP's displacement of NMC in New South Wales and Victoria tenders.
The Clean Energy Regulator's Large-scale Generation Certificate eligibility rules are tightening co-location requirements for battery-solar hybrids. Projects must demonstrate genuine charging from renewable sources to qualify, forcing developers toward more sophisticated metering and control architectures. This regulatory friction most impacts Queensland projects seeking certificate revenue alongside arbitrage.
Asset owners are bundling long-term service agreements into initial procurement, compressing aftermarket revenue windows for independent service providers. OEMs embed predictive diagnostics and performance guarantees into 15-year contracts. This shift is most visible in Victorian Renewable Energy Auction Scheme projects, where offtakers demand comprehensive availability warranties.
Australia Battery Market Segmentation
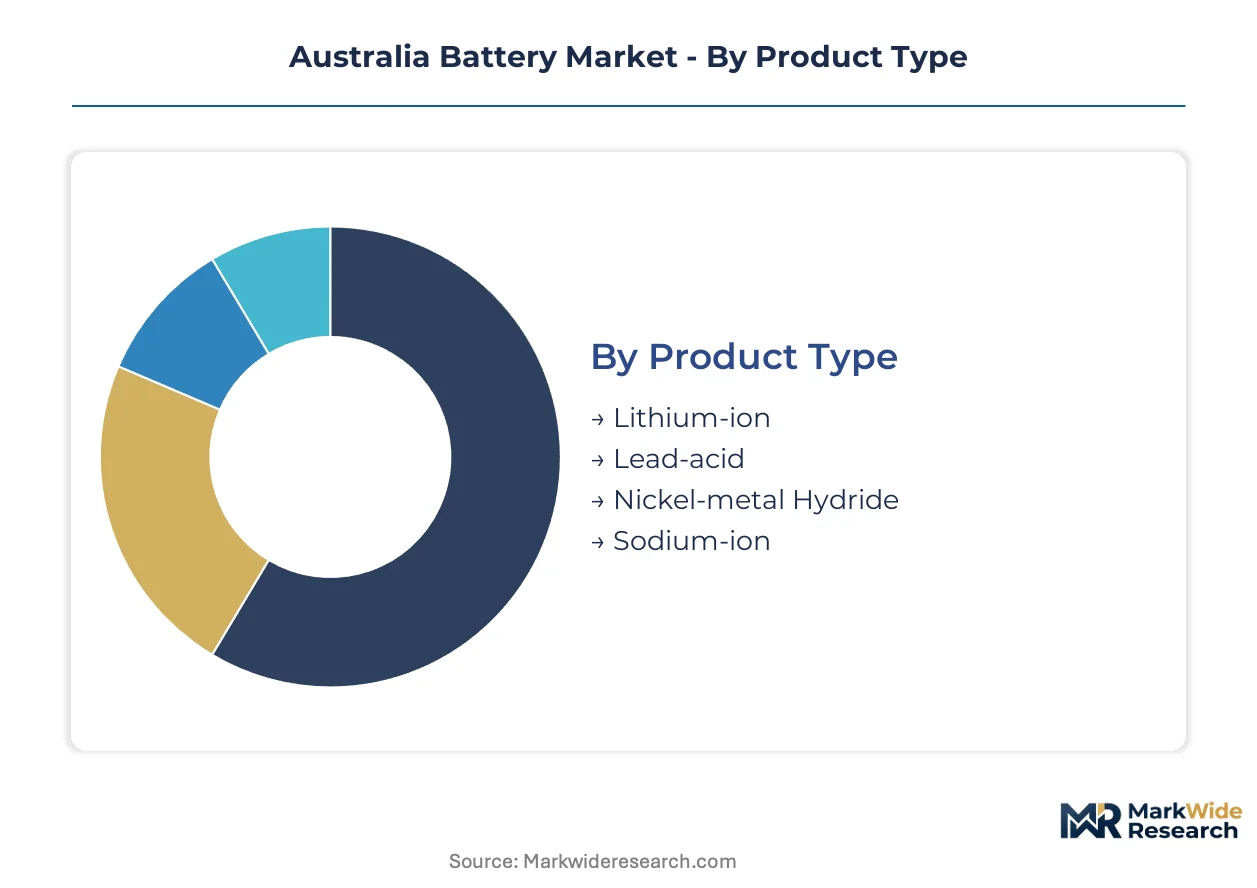
Segmentation reveals how chemistry selection, application requirements, and end-user economics fragment procurement patterns across Australia's battery market. Technology choices diverge sharply between cost-sensitive backup power and performance-driven transport electrification.
Product Type:
Mature and emerging chemistries coexist in procurement pipelines, with thermal stability and cycle life dictating utility-scale selections while capital cost governs legacy applications.
- Lithium-ion:Lithium iron phosphate dominates utility tenders due to thermal stability and cycle life exceeding 6,000 cycles at 80% depth of discharge. Grid-forming inverter mandates from AEMO favor this chemistry in New South Wales and Victoria renewable energy zones.
- Lead-acid:Flooded and valve-regulated designs retain cost advantages in backup power systems where weight and energy density matter less than capital expenditure minimization. Century Yuasa sustains aftermarket parts availability through its nationwide distribution network.
- Nickel-metal Hydride:Hybrid electric vehicle battery packs leverage this chemistry's tolerance for high-temperature operation.
- Sodium-ion:Emerging cell designs target stationary storage applications with reduced dependence on lithium feedstock.
Lithium-ion retains volume leadership; sodium-ion holds the steepest expansion curve.
Application:
Cost tier stratification separates premium transport electrification from commoditized backup power, with revenue stacking complexity concentrated in grid-connected segments.
- Electric Vehicles:Battery electric and plug-in hybrid platforms drive demand for high energy density cells. Queensland fleet operators accelerate procurement to capture state-level zero-emission vehicle incentives.
- Renewable Energy Storage:Co-located battery systems capture evening peak pricing spreads in solar-rich zones. Developers optimize across FCAS markets, wholesale arbitrage, and Large-scale Generation Certificate schemes.
- Portable Electronics:Cylindrical 18650 and 21700 formats power professional tools and consumer devices.
- Backup Power Systems:Lead-acid chemistry dominates uninterruptible power supply installations where discharge duration requirements remain modest.
Renewable energy storage commands premium pricing; electric vehicles deliver the steepest volume climb.
End User:
Customer type fragmentation separates price-tolerant early adopters from procurement departments optimizing total cost of ownership across decade-long asset lifecycles.
- Consumer Electronics:OEMs specify energy density and form factor over cycle life for smartphone and laptop applications.
- Automotive:Original equipment manufacturers embed 15-year service agreements into initial procurement, compressing aftermarket revenue windows. Victorian Renewable Energy Auction Scheme projects demand comprehensive availability warranties.
- Industrial:Mining microgrids in Western Australia represent underpenetrated demand for containerized storage with diesel displacement mandates.
- Grid Storage:Asset owners bundle long-term service agreements into utility-scale tenders. CEFC concessional debt instruments reshape project economics for installations exceeding 100 megawatt-hours.
Grid storage captures capital deployment; industrial applications expand most quickly.
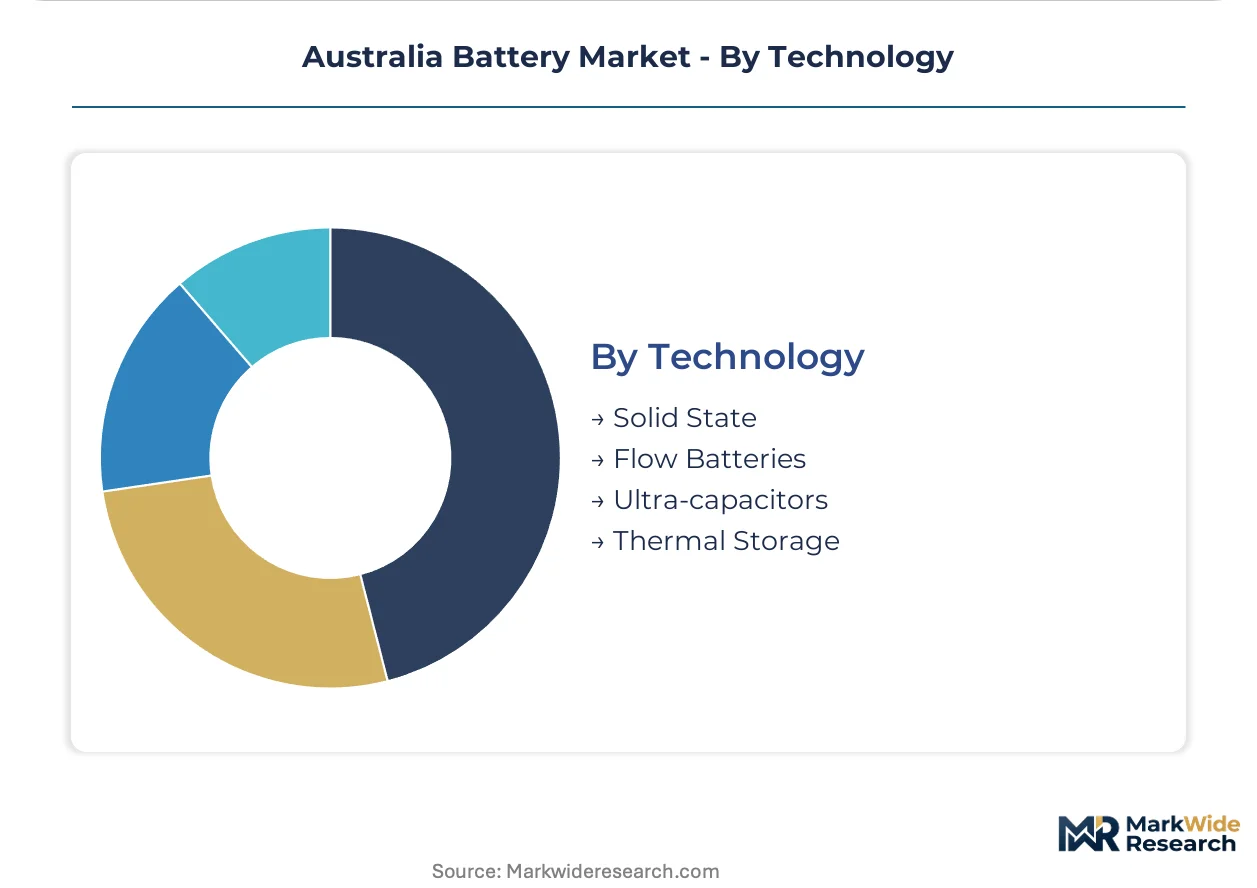
Technology:
Supply concentration shapes access to emerging technologies, with domestic cell assembly capacity anchoring solid-state development while vanadium processing bottlenecks constrain flow battery scaling.
- Solid State:Lithium-metal anodes paired with ceramic electrolytes target energy densities above 400 Wh/kg. Defense and regional aviation sectors prioritize this trajectory for electric propulsion systems.
- Flow Batteries:Vanadium redox systems carry 40-60% higher upfront costs versus lithium-ion at equivalent duration. Victoria and New South Wales minimum storage duration mandates force developers toward longer-duration chemistries.
- Ultra-capacitors:High power density devices supplement batteries in frequency response applications requiring sub-second response times.
- Thermal Storage:Molten salt and phase change materials capture arbitrage value in concentrated solar power installations.
Flow batteries retain duration leadership; solid-state technology gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level procurement patterns diverge sharply across Australia. Queensland developers prioritize solar co-location for evening arbitrage, while Western Australian mining corridors drive diesel displacement demand. Victoria and New South Wales impose distinct storage duration mandates that reshape technology selection.
New South Wales
Renewable energy zone allocations dominate procurement, with minimum storage duration mandates forcing developers toward longer-duration chemistries. The state's planning reforms require grid-forming inverter capabilities for all new battery installations. The Hunter Valley region anchors domestic cell assembly through Energy Renaissance's Tomago facility.
Victoria
The Victorian Renewable Energy Auction Scheme compresses aftermarket revenue windows through bundled 15-year service agreements. State-level regulations mandate comprehensive availability warranties from asset owners. The Latrobe Valley transition corridor concentrates utility-scale tender activity as coal retirements accelerate.
Queensland
Solar-rich zones generate evening peak pricing spreads that accelerate co-located storage deployment. The state's zero-emission vehicle incentives drive fleet operator procurement of battery electric platforms. South-east Queensland anchors distributed energy resource aggregation pilots.
Western Australia
Remote mine sites with diesel displacement mandates represent underpenetrated demand for containerized storage systems. The state's isolated grid architecture favors microgrid configurations over synchronous interconnection. The Pilbara mining corridor concentrates off-grid procurement volume.
South Australia
Grid stability services markets matured early here, with frequency control ancillary services revenue stacking now standard practice. The state's renewable integration challenges forced rapid battery procurement ahead of eastern markets. Adelaide anchors residential battery aggregation schemes.
Australia Battery Market Competitive Environment
Capability concentration sits with specialized cell assemblers and upstream material processors; scale advantage sits with established distributors with nationwide logistics networks. The market structures around three archetypes: domestic lithium-ion system integrators, legacy lead-acid distributors with aftermarket service infrastructure, and upstream graphite anode developers securing feedstock for local manufacturing. Competitive moves center on backward integration into cell production and strategic partnerships with mining microgrid developers.
Among domestic system integrators, Energy Renaissance anchors cell assembly capacity through its Newcastle-region facility. Century Yuasa Batteries exemplifies the legacy distributor archetype, sustaining aftermarket parts availability through established logistics networks. Magnis Energy Technologies occupies a position upstream, securing graphite anode feedstock from Tanzanian operations to supply Australian cell manufacturing.
| Leading Market Players |
|---|
| Custom Lithium |
| Lithium Battery Systems |
| Energy Renaissance |
| PowerPlus Energy |
| Century Yuasa Batteries |
| Magnis Energy Technologies |
| Maximus Lithium Batteries |
| Magellan Power |
| Lithium Batteries Australia |
| Others |
Value Chain & Pricing Dynamics
The Hunter Valley cell assembly cluster near Newcastle anchors domestic lithium-ion capacity, concentrating pricing power among integrated manufacturers serving New South Wales renewable energy zones. Downstream developers face compressed margins as grid-forming inverter mandates extend commissioning timelines and concentrate supplier capability around synchronous condenser alternatives.
Pricing Analysis
Long-term offtake contracts dominate utility-scale procurement, with project-based pricing for mining microgrids and spot transactions limited to aftermarket lead-acid replacement. Price differentiation hinges on certification grade for AEMO grid-forming compliance and volume scale for containerized storage systems. Cost compression in lithium iron phosphate cells is intensifying as Chinese cathode material floods Australian tenders. Mining operators in Western Australia show highest price sensitivity due to diesel displacement mandates, while grid storage developers prioritize availability warranties over unit economics.
Supply Chain Analysis
Spherical graphite anode material draws from Chinese processing hubs, with Magnis Energy Technologies attempting upstream control through Tanzanian feedstock development. Lithium carbonate concentrates among Chilean and Australian hard-rock spodumene converters, while South Korean and Japanese cell manufacturers dominate precursor chemical supply. Single-source vulnerability in purified spherical graphite exposes domestic assemblers to export restriction risk. Distribution runs through specialized EPC contractors with AEMO certification credentials rather than commodity logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state chemistry represents the substitution threat incumbents must navigate, with defense and aviation applications targeting energy density thresholds that could reshape stationary storage expectations if manufacturing costs collapse.
For Market Incumbents: Insulate core lithium iron phosphate revenue through captive cathode supply agreements with Australian spodumene processors. Secure grid-forming inverter engineering talent through acquisition of specialized consultancies before AEMO mandates tighten further. Sodium-ion emergence in stationary applications threatens mid-duration market share if lithium carbonate volatility persists.
For New Entrants and Emerging Players: Build out vanadium redox capabilities to capture Victoria and New South Wales minimum storage duration mandates where lithium-ion economics degrade beyond four-hour systems. Western Australian mining microgrids offer the most penetrable geography given diesel displacement urgency and limited incumbent service infrastructure. Target containerized storage with integrated power electronics as the go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors upstream material processors with offtake visibility into domestic cell assembly rather than pure-play system integrators. Long-term viability rests on graphite anode supply security through the projection horizon. Watch spherical graphite export licensing from Chinese processors as the inflection indicator for Australian manufacturing cost competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Processing | Magnis Energy Technologies' Tanzanian feedstock development reduces dependence on Chinese spherical graphite concentration. |
| Grid-Forming Inverter Capability Buildout | AEMO certification timelines favor early movers with synchronous condenser expertise in New South Wales tenders. |
| Long-Term Service Agreement Bundling | Victorian Renewable Energy Auction Scheme projects compress aftermarket windows through 15-year availability warranties. |
| Mining Microgrid Partnership Expansion | Western Australian diesel displacement mandates create underpenetrated demand for containerized storage with integrated controls. |
| Solid-State R&D Collaboration | Defense and aviation sector 400 Wh/kg targets position early developers for technology spillover into stationary applications. |
Study Parameters
Desk research of AEMO connection standards, CEFC financing disclosures, and ARENA grant allocations preceded structured interviews with utility planning officers, IPP project developers, EPC contractors with grid-forming certification, and mining microgrid procurement leads. Secondary validation drew from Clean Energy Regulator LGC eligibility determinations, state planning reform documentation, and customs data on lithium carbonate imports. Bottom-up project pipelines were triangulated against top-down capacity forecasts across chemistry, application, and end-user segments.
Assumptions held AEMO grid-forming mandates at current stringency levels and lithium carbonate feedstock pricing within observed volatility bands across the analysis window. Segmentation modeling incorporated chemistry selection, storage duration requirements, inverter capability tiers, and state-level regulatory frameworks. CAGRs derived from weighted average of project commissioning timelines and capacity factor assumptions. Forecast inputs included renewable energy zone allocation schedules and mining diesel displacement policy enforcement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese spherical graphite processors to restrict export licensing would shift outcomes toward accelerated domestic anode development. Cross-checking against AEMO's Integrated System Plan capacity forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Vanadium Redox Batteries Market
Batteries
Thin Film and Printed Battery Market
Batteries
East Europe Battery Market
Batteries
FORTELION Battery Module Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
Primary Battery Market
Batteries
China Battery Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
Forklift Battery Rental Market
Batteries
Low Temperature Battery Market
Batteries
Modular Battery Pack Market
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Breathing Battery Market