
 Traction Transformer Market | 2026-2036
Traction Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Traction Transformer Market Intelligence
India's massive railway electrification and modernization program is reshaping competitive positioning for traction transformer manufacturers. Siemens AG leverages its extensive portfolio and local manufacturing capabilities to secure major contracts in the region. Alstom SA competes through its integrated rolling stock solutions, embedding its transformers within complete trainsets. Meanwhile, Mitsubishi Electric Corporation differentiates with its advanced technology for high-speed rail applications.
A traction transformer is a specialized power conversion unit that steps down high-voltage electricity from overhead lines. It supplies a suitable, lower voltage to power the traction motors and auxiliary systems of electric railway vehicles. High-speed train applications represent the fastest-growing segment, demanding advanced performance and reliability. While oil-filled units dominate due to superior cooling, dry-type transformers see increased use in urban metro systems for safety reasons.
The International Electrotechnical Commission's IEC 60310 standard provides the foundational safety and performance criteria for traction transformers. In Europe, EN 50329 specifies requirements, while national standards like China's GB standards impose localized compliance demands. Navigating these varied technical specifications and achieving dual certification for key markets remains a central challenge for component suppliers.
Market Dynamics
The global push for transport decarbonization, driven by government policy and climate targets, provides the central structural force for the traction transformer market. This manifests as large-scale, state-funded railway electrification programs, creating long-cycle, concentrated demand from rolling stock manufacturers and rail operators.
Growth Catalysts
- Policy Mandates:The EU Green Deal and similar initiatives in other regions mandate a modal shift to rail for both passenger and freight transport, directly stimulating investment in new electric locomotives and multiple units.
- National Infrastructure Projects:India's National Rail Plan and China's continued high-speed network expansion represent massive, long-term sources of demand for traction transformers and related power conversion equipment.
- High-Speed Rail Expansion:The proliferation of high-speed rail lines globally requires advanced transformers capable of handling higher power densities and ensuring exceptional reliability, pulling the market's technology forward.
Market Restraints
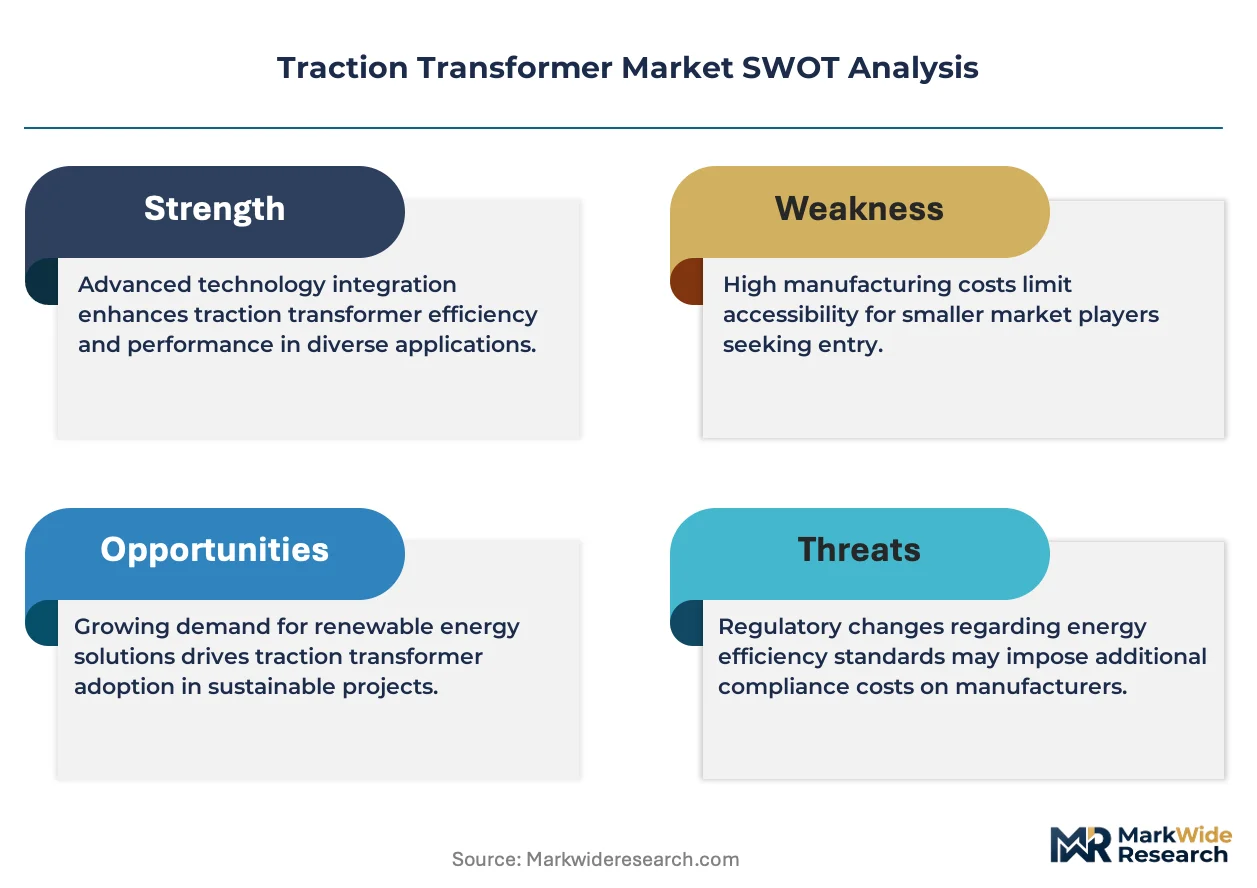
- Input Cost Volatility:Price fluctuations in essential raw materials, particularly high-conductivity copper and specialized electrical steel, create margin pressure and complicate long-term project bidding for transformer manufacturers.
- Technical Qualification Cycles:The extensive and costly testing and validation processes required to qualify new transformer designs for railway use can act as a significant barrier to entry and slow innovation adoption.
- Regulatory Fragmentation:Manufacturers must navigate a complex web of standards, including IEC 60310, Europe's EN 50329, and China's distinct GB standards, increasing design complexity and certification costs for global suppliers.
Strategic Opportunities
- Advanced Materials:Developing transformers with nanocrystalline cores or other lightweight composite materials presents an opportunity to reduce vehicle weight, improve energy efficiency, and capture a premium in next-generation trainsets.
- Retrofit and Modernization:A large global installed base of aging electric locomotives offers a substantial market for replacing older, less efficient transformers with modern, digitally-enabled units that support predictive maintenance.
- Urban Rail Development:The rapid expansion of metro and light rail transit systems in emerging economies across Southeast Asia and Latin America opens new geographic markets for both oil-filled and dry-type transformers.
Industry Challenges
- Compliance Complexity:Achieving dual certification to meet the technical and safety specifications of multiple major markets, such as Europe and China, remains a significant operational hurdle that consumes engineering resources and extends timelines.
- Legacy System Integration:Ensuring new, digitally-controlled transformers can interface seamlessly with existing, often decades-old, power supply infrastructure and signaling systems is a critical challenge in modernization projects.
- Specialized Talent Scarcity:A shortage of power electronics engineers with specific domain expertise in high-voltage railway applications constrains research and development capacity and project execution for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traction Transformer Market |
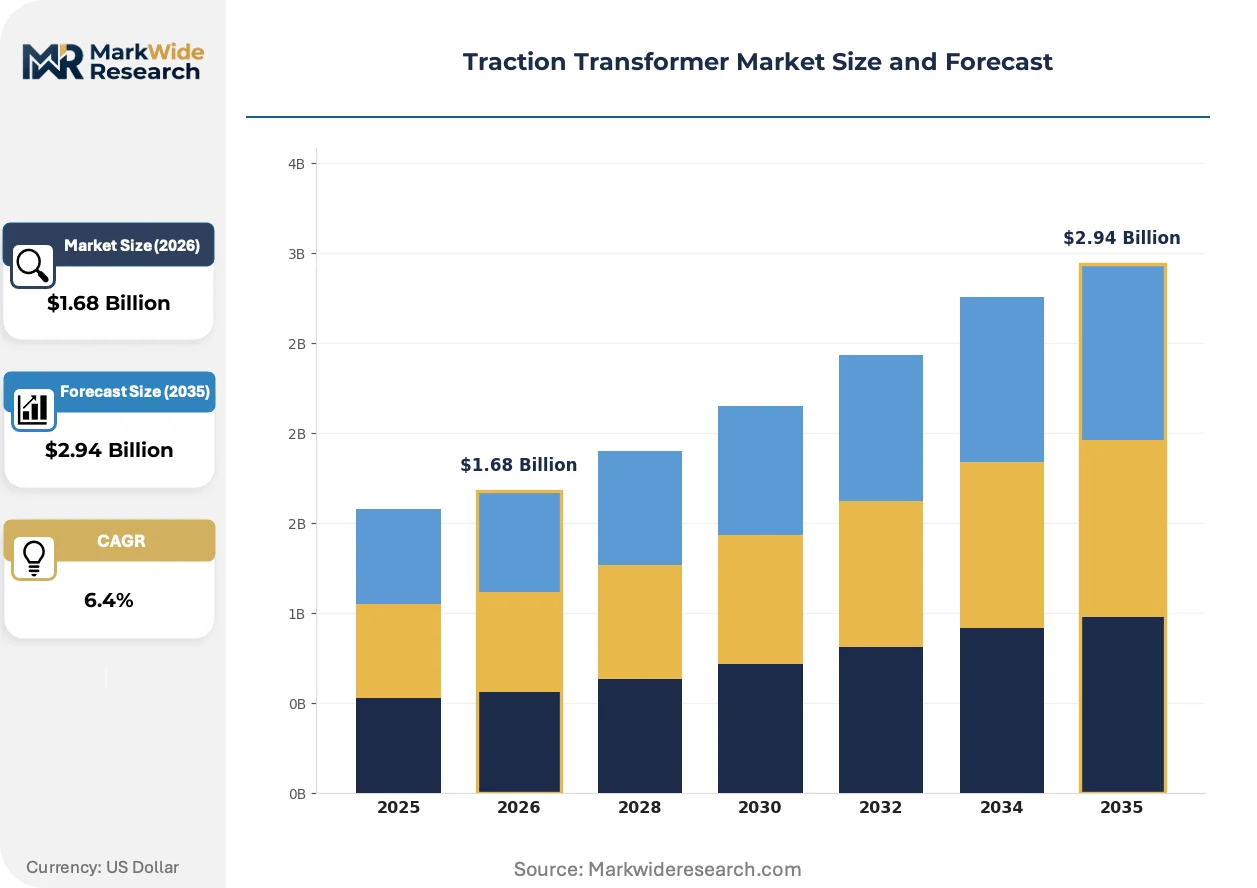
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Phase, Three Phase, Autotransformer, Dry Type, Oil Filled Application: Railway Locomotives, Urban Metro Systems, Electric Trams, High-Speed Trains, Light Rail Transit Technology: Cast Resin, Oil-Immersed, Vacuum Pressure Impregnated, Resin Impregnated, Natural Cooling End User: Rolling Stock Manufacturers, Transit Authorities, Maintenance Facilities, Railway Operators |
| Companies Covered | Siemens AG, ABB Ltd., Alstom SA, Mitsubishi Electric Corporation, General Electric Company, Hitachi Ltd., Toshiba Corporation, Schneider Electric SE, JST Transformateurs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traction Transformer Market Strategic Shifts & Innovations
The core technological evolution in the traction transformer market is reshaping the component from a passive electrical device into an intelligent, actively managed system. This transition toward digitalization is driven by operator demands for higher reliability, lower lifecycle costs, and predictive maintenance capabilities.
Solid-state transformers combine high-frequency power conversion with sophisticated digital controls to manage power flow with greater precision and efficiency. High-speed rail and heavy freight applications are the initial adopters, piloting these systems for their improved power quality and significantly smaller physical footprint. This technology is hybridizing the conventional transformer with advanced power electronics, creating an intelligent grid-interface node directly on the locomotive.
The International Electrotechnical Commission's IEC 60310 standard is being updated to formally include requirements for onboard digital monitoring and diagnostics. This change compels manufacturers to integrate sensors for thermal, vibration, and dielectric fluid analysis directly into the transformer assembly. Rolling stock operators in Europe, who must comply with the EN 50329 standard, are most affected, as they must now manage new data streams for predictive maintenance schedules.
Railway operators are progressively moving away from simple component-level procurement toward contracting for total lifecycle performance and guaranteed availability. This model transfers the responsibility for uptime and maintenance from the rail operator to the equipment supplier, often bundled within the broader rolling stock acquisition. This trend is most prominent in large-scale public-private partnership projects for new rail corridors in India and the Middle East.
Traction Transformer Market Segmentation
The traction transformer market's segmentation provides a detailed lens into the diverse requirements and purchasing dynamics across the global railway industry. Understanding these distinct categories allows manufacturers to tailor product development, certification efforts, and market entry strategies effectively. Each segment reflects specific operational challenges, technological preferences, and regulatory compliance needs within railway applications.
Product Type:
The product type segmentation delineates the functional and environmental use-case spectrum for traction transformers, from traditional robust designs to specialized safety-conscious units.
- Oil Filled:These transformers utilize mineral oil or synthetic esters for both insulation and cooling, offering superior thermal management and power density. Demand remains high in heavy-duty railway locomotives and long-distance passenger trains due to their proven reliability and cost-effectiveness.
- Dry Type:Employing solid insulation materials and air cooling, dry-type transformers eliminate the risk of oil leaks, making them ideal for urban metro systems and enclosed environments where fire safety is paramount. Their deployment is expanding in new light rail transit projects across Europe and Asia.
- Single Phase:These transformers are prevalent in AC traction systems, stepping down the single-phase high voltage from overhead lines for the locomotive's power electronics. They are commonly found in European and Indian railway networks.
- Three Phase:Less common in direct traction applications, three-phase transformers are typically used in auxiliary power units or static converters within specialized railway infrastructure.
- Autotransformer:Autotransformers are used in specific AC electrification systems to reduce voltage drops and balance current flow along the overhead line, particularly in high-power, long-distance routes.
Established volume favors Oil Filled units; emerging adoption favors Dry Type transformers.
Application:
Application segments highlight the varied operational environments and performance demands, influencing transformer design and power output requirements across different rail systems.
- High-Speed Trains:These applications demand transformers with high power density, minimal weight, and exceptional reliability to support rapid acceleration and sustained high velocities. Japan's Shinkansen and Europe's TGV networks drive continuous innovation in this segment.
- Railway Locomotives:Covering a broad range of freight and passenger services, this segment requires robust transformers capable of handling diverse load conditions and harsh environmental factors. India's extensive railway electrification program generates substantial demand for these units.
- Urban Metro Systems:Transformers for metro systems prioritize compactness, low noise, and enhanced safety features, often including dry-type designs, to operate within densely populated areas. New metro line constructions in Southeast Asian cities contribute to this segment.
- Electric Trams:These light rail vehicles utilize smaller, often dry-type transformers, designed for frequent stops and starts in urban street environments. European cities frequently upgrade their tram fleets, creating consistent demand.
- Light Rail Transit:Similar to trams but often operating on dedicated rights-of-way, LRT systems require transformers optimized for efficiency and passenger comfort in medium-speed urban and suburban settings.
Demand for advanced solutions concentrates in High-Speed Trains, while core volume remains with Railway Locomotives.
Technology:
Technology classifications differentiate transformers based on their insulation, cooling mechanisms, and manufacturing processes, impacting efficiency, size, and thermal management.
- Oil-Immersed:This traditional technology uses dielectric oil for both insulation and cooling, offering high efficiency and thermal stability for heavy-duty applications. It remains a foundational technology across global railway systems.
- Vacuum Pressure Impregnated:VPI technology involves impregnating transformer windings with resin under vacuum, resulting in a compact, robust, and environmentally resistant unit. This is increasingly adopted for modern, high-performance rolling stock due to improved insulation properties.
- Cast Resin:Cast resin transformers encapsulate windings in epoxy resin, providing excellent mechanical strength and fire resistance, making them suitable for specialized applications requiring enhanced safety. They are often chosen for confined spaces.
- Resin Impregnated:Similar to VPI, resin-impregnated transformers use resin to enhance insulation and mechanical integrity, offering an alternative to oil-filled units in certain operational contexts.
- Natural Cooling:This method relies on convection and radiation to dissipate heat without forced air or liquid circulation, suitable for smaller transformers or those operating in less demanding environments.
The market's technological evolution is driven by advancements in Vacuum Pressure Impregnated designs, complementing the established presence of Oil-Immersed units.
End User:
The end-user segmentation clarifies the primary purchasing entities and operational stakeholders who specify and deploy traction transformers within the railway ecosystem.
- Rolling Stock Manufacturers:These companies integrate traction transformers directly into new locomotives, multiple units, and other rail vehicles during the manufacturing process. They are primary decision-makers for component selection.
- Railway Operators:As the entities managing and running railway networks, operators define performance specifications and maintenance requirements, influencing transformer procurement for both new builds and retrofits. European and Indian railway operators heavily influence market demand.
- Transit Authorities:Responsible for urban and regional public transport systems, transit authorities procure transformers for metro, tram, and light rail projects. Their focus includes safety, efficiency, and lifecycle costs.
- Maintenance Facilities:These facilities are responsible for the upkeep, repair, and replacement of existing traction transformers within operational fleets. They drive demand for spare parts and modernization components.
Procurement decisions are primarily driven by Rolling Stock Manufacturers, with significant long-term influence from Railway Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global traction transformer market exhibits a distinct consumption-mix differential across key geographies. India and China focus on extensive railway electrification and modernization, driving volume for diverse transformer types. European and Japanese markets prioritize high-speed rail and urban metro systems, demanding advanced performance and safety features. This difference shapes product development and market entry strategies for manufacturers.
India
India's extensive railway electrification program drives significant demand for robust traction transformers, particularly for railway locomotives and freight lines. The National Rail Plan outlines ambitious targets for network expansion and upgrades, stimulating long-term investment. Local manufacturing facilities in Maharashtra and Gujarat are expanding to meet the requirements of projects like the Mumbai-Ahmedabad high-speed rail corridor.
China
China's sustained expansion of its high-speed rail network generates substantial demand for advanced traction transformers. The country's dual carbon goals also accelerate the shift towards electrified transport, influencing procurement. Manufacturers in regions like the Yangtze River Delta focus on developing specialized units for both high-speed trains and rapidly growing urban metro systems.
Germany
German railway operators prioritize high-performance and energy-efficient transformers for their extensive network and urban transit systems. The EU Green Deal mandates a modal shift to rail, stimulating investment in new electric locomotives. Engineering firms in Bavaria and North Rhine-Westphalia develop advanced components adhering to strict EN 50329 safety and performance criteria.
Japan
Japanese railway applications emphasize extreme reliability and compact, lightweight traction transformers for high-speed rail. Continuous modernization of the Shinkansen network and urban metro systems sustains demand for advanced units. Manufacturers in the Kanto and Kansai regions leverage strict JIS standards to innovate in areas like power density and acoustic performance.
France
French rail infrastructure, including the TGV network, requires high-performance traction transformers for both new builds and modernization. European rail directives and national investment plans drive electrification projects across regional lines. Rolling stock manufacturers in areas like Belfort and La Rochelle integrate advanced transformer solutions into their complete trainsets for domestic and export markets.
Traction Transformer Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the traction transformer market. The market exhibits a tiered structure, with established industrial conglomerates alongside specialized component manufacturers. One archetype involves vertically integrated rolling stock manufacturers embedding transformers, while another focuses on pure-play power electronics specialists. Strategic partnerships with rail operators and continuous portfolio diversification into advanced materials are dominant competitive moves.
Within the integrated solutions segment, Siemens AG and Alstom SA exemplify manufacturers leveraging extensive portfolios to secure major contracts. Siemens AG, with its broad industrial reach, often provides comprehensive rail electrification solutions, embedding its transformer technology. Alstom SA competes through its integrated rolling stock offerings, where transformers are a critical component of complete trainsets. Mitsubishi Electric Corporation represents a technology-focused approach, differentiating with advanced solutions for high-speed rail applications and specialized power electronics. These companies anchor different competitive strategies across diverse railway ecosystems.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Alstom SA |
| Mitsubishi Electric Corporation |
| General Electric Company |
| Hitachi Ltd. |
| Toshiba Corporation |
| Schneider Electric SE |
| JST Transformateurs |
Cost & Logistics Intelligence
Undercapacity in specialized high-speed rail transformer production is forcing suppliers to prioritize projects, influencing pricing power for advanced units. This utilization dynamic directly impacts both manufacturer investment strategies and the overall pricing posture for next-generation traction solutions.
Pricing Analysis
Project-based contracts define the dominant pricing model for traction transformers, especially for major electrification programs and new rolling stock acquisitions. Price differentiation stems from the level of technical specification, such as adherence to IEC 60310 standards, and the degree of customization required for specific trainset integrations. Pricing pressure stems from input cost volatility, particularly for high-conductivity copper and specialized electrical steel. Railway operators are highly price-sensitive for large volume orders of standard units, while high-speed train manufacturers prioritize performance and reliability, exhibiting lower price sensitivity for advanced solutions.
Supply Chain Analysis
Extended payment terms are common across the traction transformer supply chain, reflecting the long project cycles in railway infrastructure development. Geographic supply concentration is notable in China, India, and Germany for manufacturing, leveraging established industrial bases. Raw material dependencies include high-conductivity copper, specialized electrical steel, and advanced insulating materials. A structural risk is commodity price volatility for these key inputs, which can complicate long-term project bidding. Distribution runs through direct sales channels to major rolling stock manufacturers and national railway operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering expertise in high-voltage railway applications creates a significant barrier to entry, defining the market as one with a scarcity of critical human capital.
For Market Incumbents: Insulate core market share by deepening relationships with major rolling stock manufacturers through long-term service and maintenance contracts. Invest in advanced materials R&D to counter the threat of new solid-state transformer technologies. Leverage vertical integration into key component manufacturing for greater cost control against raw material price volatility.
For New Entrants and Emerging Players: Urban metro systems in Southeast Asia represent a highly penetrable entry point for specialized dry-type transformer manufacturers. Target these rapidly expanding urban rail networks with compact, safety-focused solutions. Go-to-market via strategic partnerships with local transit authorities and urban development consortiums, emphasizing fire safety compliance.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the high-speed rail segment, driven by advanced material and power electronics integration. Long-term viability is strong for specialized component suppliers with proven track records in reliability and innovation. Acquire mid-cap firms with intellectual property in solid-state transformers or advanced diagnostic systems. Watch for consolidation among power electronics specialists as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Materials R&D | Accelerates performance for high-speed rail, reducing weight and improving energy efficiency for trainsets. |
| Dual Certification Investment | Streamlines market access by meeting both IEC 60310 and localized GB standards for global suppliers. |
| Predictive Maintenance Integration | Enhances product value by enabling remote monitoring and reducing lifecycle costs for railway operators. |
| Regional Manufacturing Expansion | Addresses localized compliance demands and reduces logistics costs for large-scale projects in India. |
| Power Electronics Partnership | Accelerates development of solid-state transformers, integrating advanced controls for intelligent power management. |
Research Approach
A spread of perspectives from rolling stock manufacturers, railway operators, component engineers, and transit authority procurement leads converged on the working assumptions for the traction transformer market. Primary interviews were combined with extensive secondary validation, drawing from IEC standards documents, EN 50329 specifications, GB standards, and national railway electrification program reports. Bottom-up market sizing was triangulated with top-down validation.
Demand-supply balance modeling informed the quantitative framework across the analysis window, projecting market evolution. Segmentation dimensions modeled included product type, application, technology, end-user, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends and anticipated project pipeline. Forecast inputs included planned railway electrification investment and high-speed rail network expansion targets.
Macroeconomic conditions sit as an overlay; deviation in global infrastructure spending or raw material commodity prices would shift the trajectory of the traction transformer market. Forecasts reflect current market dynamics and anticipated policy landscapes. Regulatory changes or unexpected technological breakthroughs could revise projections. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Global Transformer Market
Transformers
Transformer Oil Market
Transformers
Phase-Shifting Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
North America Smart Transformers Market
Transformers
Europe Smart Transformers Market
Transformers
HVDC Converter Transformers Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Global Large Power Transformers Market
Transformers
Rectifier Transformers Market
Transformers
Green Transformer Market
Transformers
High Voltage (35-550 KV) Power Transformer Market
Transformers
South America Transformer Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Asia-Pacific Transformer Market