
 HVDC Converter Transformers Market | 2026-2036
HVDC Converter Transformers Market Size, Share, and Industry Trends Forecast 2026-2036
HVDC Converter Transformers Market Insights
Power purchase agreement-backed project finance is reshaping how offshore wind and interconnector developers procure HVDC converter transformers, shifting risk from balance sheets to specialized infrastructure funds. Siemens Energy leverages its manufacturing footprint in Europe to anchor long-term service contracts for subsea cable-linked converter stations. Hitachi Energy Ltd. dominates the large-scale segment through integrated offerings spanning valve halls and transformer bushings. Hyosung Heavy Industries competes aggressively on Korean peninsula interconnection projects and Southeast Asian grid links.
HVDC converter transformers are specialized oil-immersed power transformers designed to operate at the interface between AC grids and DC converter stations, typically rated from 200 kV to 800 kV and engineered to withstand harmonic loading and DC bias conditions. Their primary purpose is to step voltage between the AC system and the converter bridge while providing galvanic isolation and limiting fault currents. Converter transformers command the dominant margin pool within the product type spectrum due to their bespoke engineering and extended lead times. Among end users, renewable energy providers represent the fastest-expanding category as offshore wind capacity targets multiply across the North Sea and Asia-Pacific coastlines.
FERC Order 2023 and the EU Green Deal's offshore renewable energy targets are tightening grid interconnection mandates across the United States and European Union, directly stimulating converter transformer procurement for new HVDC corridors. China's GB standards and NMPA certification requirements for ultra-high voltage equipment create a parallel regulatory track that shapes domestic supply chains and limits market access for non-compliant manufacturers. Stakeholders must monitor how evolving carbon border adjustment mechanisms and local content rules reshape competitive positioning in transformer sourcing decisions.
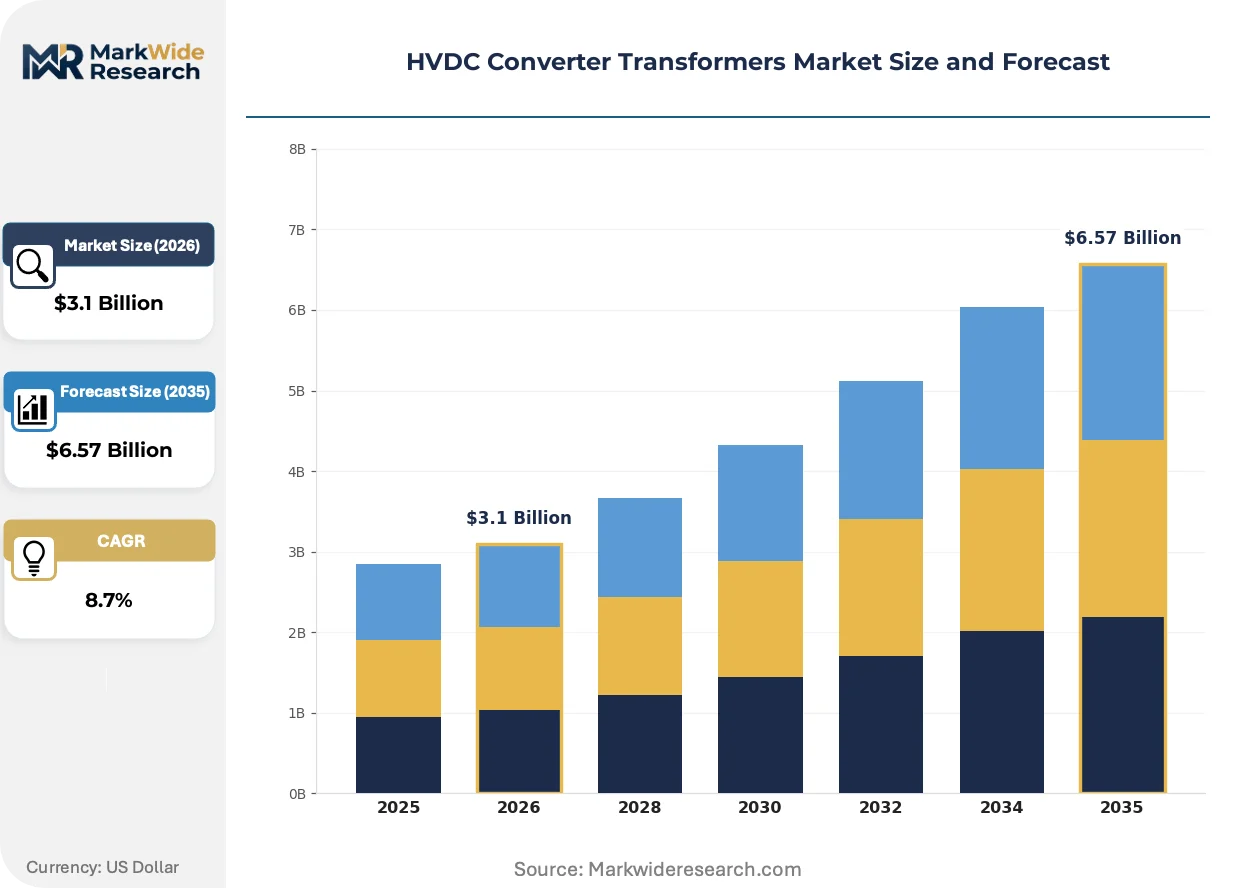
Market Dynamics
Power purchase agreement-backed project finance is redistributing procurement risk from utility balance sheets to specialized infrastructure funds, fundamentally altering how converter transformers are specified, priced, and contracted across offshore wind and interconnector developments.
Growth Catalysts
- EU Green Deal offshore mandates:Binding renewable energy targets for 2030 are accelerating HVDC corridor approvals across the North Sea, directly stimulating converter transformer orders for collector platforms and cross-border links.
- China's dual carbon framework:GB standards for ultra-high voltage transmission are expanding domestic manufacturing requirements and creating captive demand for 800 kV class equipment.
- Subsea cable standardization:Harmonized 525 kV DC cable specifications are reducing interface engineering costs and enabling modular converter station designs.
Market Restraints
- Grain-oriented electrical steel concentration:Supply of critical core material concentrates among Japanese and European producers, exposing transformer manufacturers to input cost volatility and allocation constraints.
- Extended certification timelines:NMPA approval cycles for ultra-high voltage equipment in China create 18-24 month market access barriers for non-domestic suppliers.
- Liquid-immersed transformer substitution limits:Dry-type alternatives cannot achieve required voltage ratings and harmonic tolerance, locking designs into oil-based systems with environmental compliance burdens.
Strategic Opportunities
- US offshore wind buildout:FERC Order 2023 interconnection mandates are opening procurement channels for converter transformers along the Atlantic coast where HVDC collector systems are being deployed.
- Digital twin integration:Convergence of physics-based modeling with real-time operational data is enabling predictive maintenance contracts and performance guarantees.
- Southeast Asian grid interconnection:Korean peninsula and ASEAN cross-border projects are creating demand for 400 kV class equipment with localized service requirements.
Industry Challenges
- Specialized winding engineering scarcity:Expertise in harmonic loading design and DC bias mitigation concentrates among aging specialists in Germany and Japan, constraining workforce expansion.
- Multi-standard compliance complexity:Simultaneous GB, IEC, and IEEE certification requirements for export-oriented manufacturers extend product development cycles and testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVDC Converter Transformers Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Station Transformers, Converter Transformers, Coupling Capacitors, Filter Reactors End User: Utilities, Industrial Sectors, Renewable Energy Providers, EPC Contractors Installation Type: Indoor, Outdoor, Rail-Bound, Maritime Capacity: Small Scale, Medium Scale, Large Scale, Super Large Scale |
| Companies Covered | Hitachi Energy Ltd., Siemens Energy, Mitsubishi Electric Corporation, General Electric, Toshiba Corporation, GE Vernova, Eaton, Hyosung Heavy Industries, NR Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVDC Converter Transformers Market Trends and Innovations
Digital instrumentation and predictive analytics are penetrating converter transformer design and operation, compressing maintenance intervals and enabling performance-based contracting models that reshape supplier-customer relationships.
Condition monitoring systems embedded in winding insulation and oil circulation paths are digitizing asset health assessment. Offshore wind operators in the North Sea are deploying these systems at scale to reduce unplanned outage exposure. Real-time thermal and dissolved gas analysis is digitizing maintenance scheduling from calendar-based to condition-based intervals.
The EU F-Gas Regulation is phasing down sulfur hexafluoride use in switchgear integrated with converter stations. This is forcing redesign of gas-insulated bushing interfaces and accelerating adoption of vacuum interrupter alternatives. German and Danish grid operators are prioritizing SF6-free specifications in tender evaluations.
Long-term service agreements are unbundling from initial equipment sales as buyers seek operational risk transfer. Infrastructure funds acquiring offshore wind assets are demanding 15-20 year performance guarantees with fixed pricing. This restructuring is visible across German and UK North Sea projects where operational expenditure certainty outweighs capital cost minimization.
HVDC Converter Transformers Market Segmentation
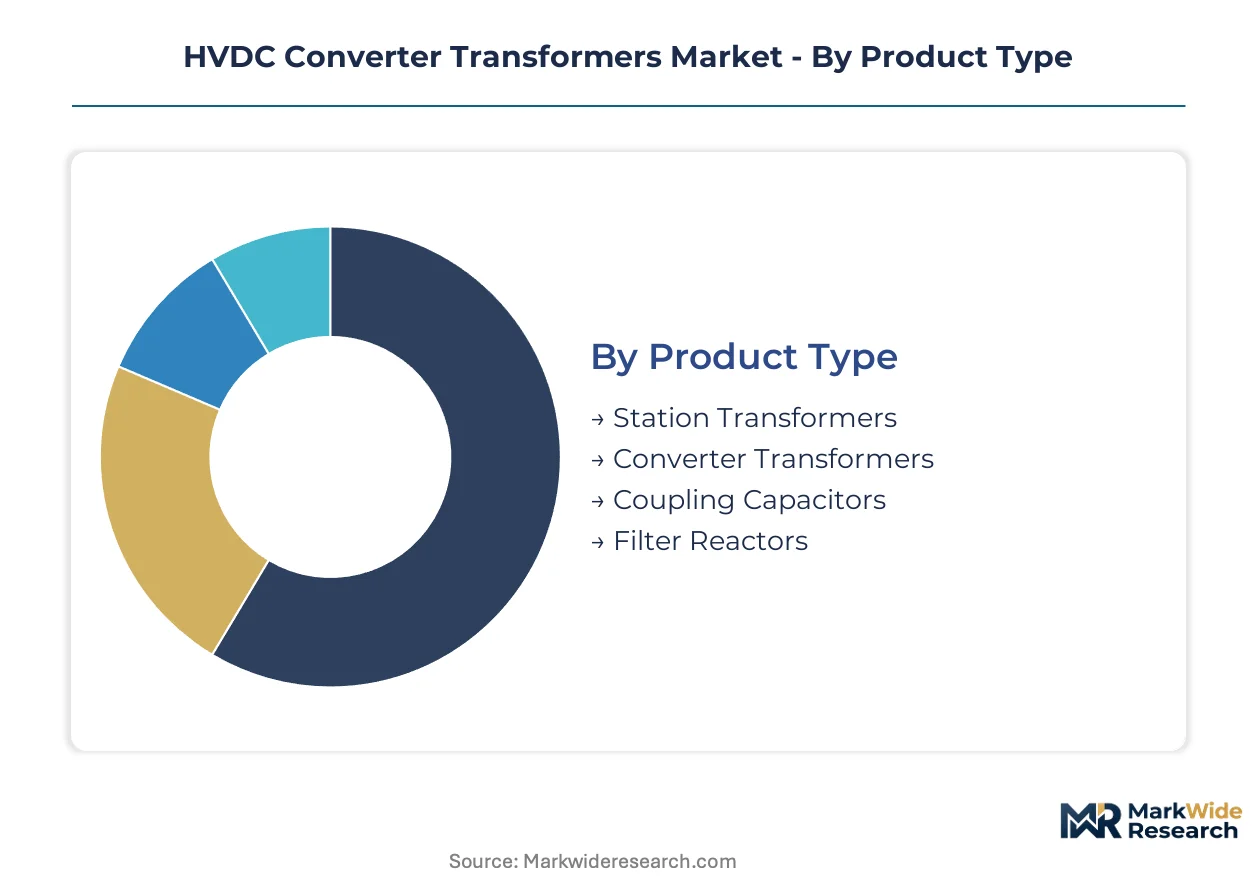
HVDC converter transformer procurement varies sharply across installation contexts and buyer types, with offshore wind developers demanding integrated service packages while utilities prioritize modular upgrade paths. Segmentation reveals how technical specifications, capacity thresholds, and environmental exposure reshape supplier-customer contracting structures.
Product Type:
After-sales service intensity diverges dramatically across product categories, with converter transformers requiring specialized harmonic loading expertise and extended warranty structures that station transformers rarely demand.
- Converter Transformers:Oil-immersed designs rated 200-800 kV withstand DC bias and harmonic loading at the AC-DC interface. North Sea offshore wind collector platforms concentrate procurement here, driven by EU Green Deal interconnection mandates and 525 kV cable standardization. Siemens Energy and Hitachi Energy anchor long-term service contracts around these assets.
- Station Transformers:Standard AC grid interconnection equipment stepping voltage between transmission levels. German and Chinese utilities dominate procurement for cross-border HVDC corridor landfall stations, with demand tightening around GB standards compliance and NMPA certification requirements.
- Coupling Capacitors:High-voltage capacitive voltage dividers for measurement and protection circuits in converter stations.
- Filter Reactors:Harmonic filtering components suppressing AC side distortion from converter switching operations.
Converter transformers hold the largest share; momentum sits with filter reactors as modular station designs proliferate.
End User:
Customer type determines contract structure, with infrastructure funds backing renewable projects demanding performance guarantees that traditional utility procurement rarely specifies.
- Renewable Energy Providers:Offshore wind developers in the North Sea and Asia-Pacific coastlines drive fastest-expanding demand. FERC Order 2023 interconnection mandates in the US Atlantic region and EU offshore targets are accelerating HVDC collector platform procurement with 15-20 year operational expenditure certainty clauses.
- Utilities:Grid operators in Germany and China anchor baseline volume for cross-border links and ultra-high voltage transmission networks. Procurement centers on GB standards, IEC compliance, and modular upgrade paths for existing converter stations.
- EPC Contractors:Engineering-procurement-construction firms bundle transformer supply into turnkey converter station projects.
- Industrial Sectors:Mining and petrochemical facilities procure smaller-scale units for isolated DC links and process power quality management.
Utilities retain the largest installed base; renewable energy providers are climbing the fastest as offshore wind capacity targets multiply.
Installation Type:
Environmental exposure dictates enclosure engineering and maintenance access economics, with maritime installations commanding premium pricing and specialized logistics.
- Maritime:Platform-mounted and floating offshore converter stations in the North Sea. Danish and German grid operators prioritize SF6-free bushing specifications here under EU F-Gas Regulation phase-down timelines, with condition monitoring systems embedded for remote asset health assessment.
- Outdoor:Land-based converter stations exposed to weather across transmission corridors. Chinese ultra-high voltage projects concentrate demand, with NMPA approval cycles creating 18-24 month access barriers for non-domestic suppliers.
- Indoor:Climate-controlled valve hall installations at major interconnection hubs.
- Rail-Bound:Traction power supply transformers for electrified railway DC feeder systems.
Outdoor installations hold the largest share; maritime applications are expanding most quickly as floating offshore wind platforms advance.
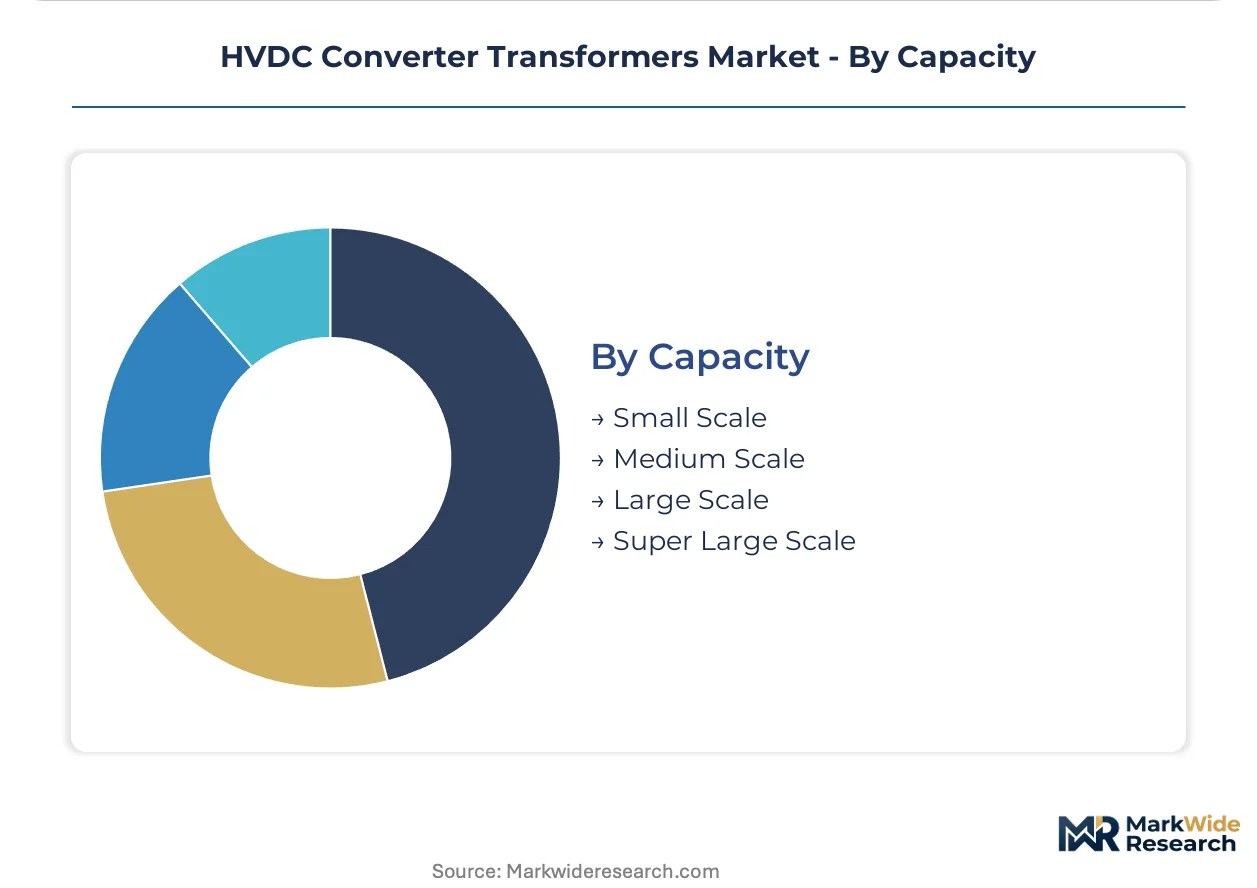
Capacity:
Scale thresholds align with voltage class and project finance structures, with super large scale units requiring captive manufacturing relationships and extended lead times.
- Large Scale:400-800 kV class equipment dominating cross-border interconnectors and ultra-high voltage networks. Hitachi Energy Ltd. leverages integrated valve hall offerings here, while Hyosung Heavy Industries competes on Korean peninsula and ASEAN grid links with localized service requirements.
- Super Large Scale:Custom 800 kV+ designs for China's domestic ultra-high voltage expansion under dual carbon goals. GB standards and NMPA certification create captive demand with limited import penetration, concentrating supply among state-backed manufacturers.
- Medium Scale:200-400 kV units for regional HVDC links and industrial process power.
- Small Scale:Sub-200 kV equipment for island interconnections and specialized industrial applications.
Large scale capacity holds the largest share; super large scale shows steepest expansion trajectory as China's transmission buildout accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in HVDC converter transformer trade are narrowing as China scales domestic manufacturing for ultra-high voltage networks while Germany and the United States deepen local sourcing for offshore wind interconnection projects.
China
Domestic absorption of 800 kV class equipment is accelerating under dual carbon goals and grid expansion mandates. GB standards and NMPA certification requirements create 18-24 month access barriers for non-domestic suppliers, concentrating procurement among state-backed manufacturers. Yangtze River Delta industrial clusters around Shanghai and Suzhou anchor production capacity for ultra-high voltage transmission networks.
Germany
North Sea offshore wind collector platforms are driving procurement of platform-mounted converter transformers rated 525 kV and above. EU F-Gas Regulation phase-down timelines are forcing SF6-free bushing specifications in tender evaluations. Hamburg and Bremen harbor zones concentrate logistics infrastructure for subsea cable-linked converter station deployments.
United States
FERC Order 2023 interconnection mandates are opening procurement channels along the Atlantic coast where HVDC collector systems are being deployed for offshore wind buildout. Infrastructure funds are demanding 15-20 year performance guarantees with fixed operational expenditure pricing. Northeast corridor states from Massachusetts to Virginia concentrate project development activity.
South Korea
Korean peninsula interconnection projects and ASEAN grid links are creating demand for 400 kV class equipment with localized service requirements. Government-backed energy transition programs are accelerating HVDC corridor approvals to island and coastal renewable zones. Busan-Ulsan industrial zones anchor manufacturing and port logistics for regional export.
United Kingdom
North Sea floating offshore wind platforms are expanding maritime installation demand for converter transformers with embedded condition monitoring systems. Contract structures are unbundling long-term service agreements from initial equipment sales as infrastructure funds acquire operational assets. Scottish and English east coast clusters concentrate platform fabrication and installation activity.
HVDC Converter Transformers Market Competitive Landscape
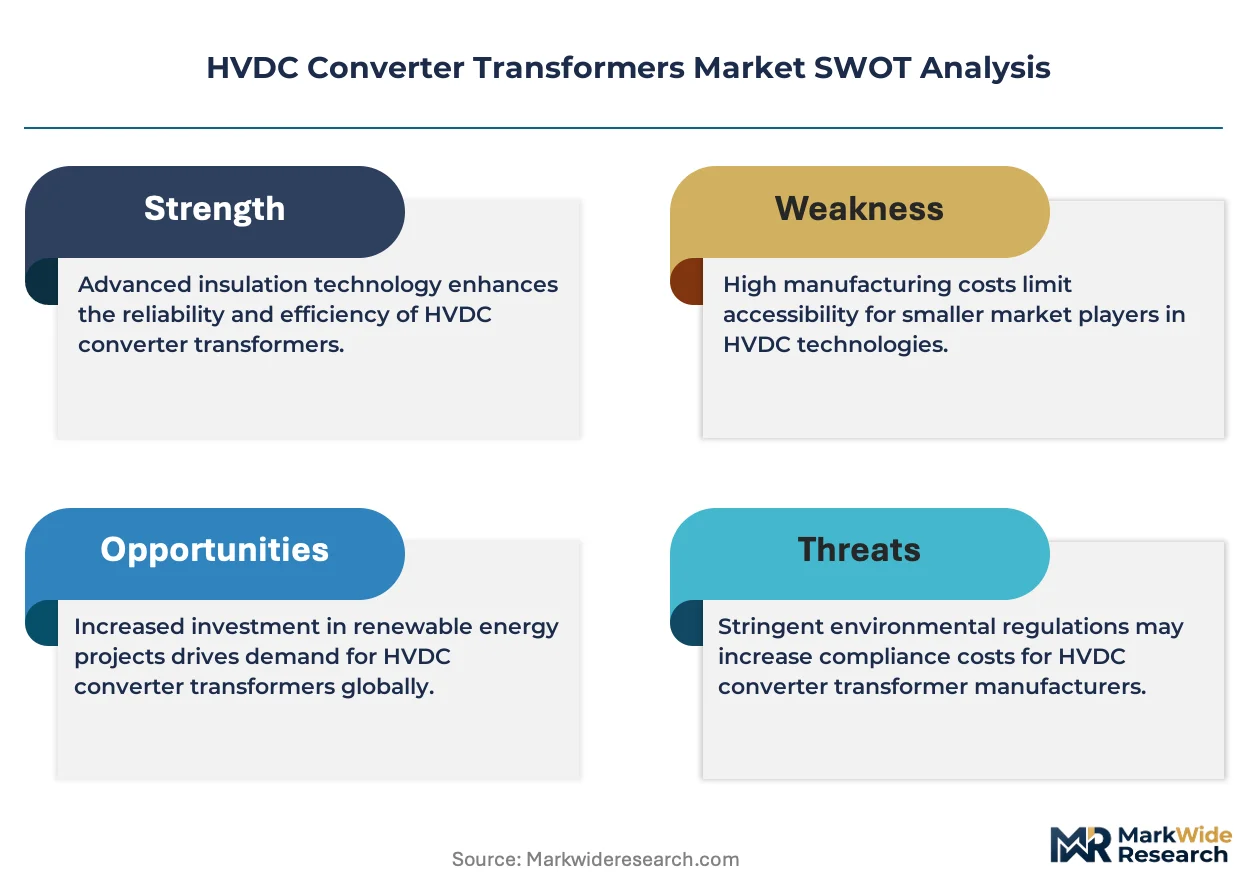
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical positioning. The market structures around a consolidated core of full-system providers and a fragmented periphery of niche engineering houses. Two archetypes dominate: integrated valve hall suppliers capturing long-term service contracts, and regional fabricators competing on localized certification compliance. Competitive moves center on captive manufacturing relationships for super large scale units and predictive maintenance capability integration.
Among the integrated tier, Hitachi Energy Ltd. and Siemens Energy occupy positions exemplifying full-system platform supply with bundled service architectures. Hyosung Heavy Industries represents the regional specialist archetype, anchoring Korean peninsula and Southeast Asian procurement channels through localized certification pathways. These three entities illustrate how competitive positioning splits between global scope with integrated offerings and regional depth with compliance-advantaged access.
| Leading Market Players |
|---|
| Hitachi Energy Ltd. |
| Siemens Energy |
| Mitsubishi Electric Corporation |
| General Electric |
| Toshiba Corporation |
| GE Vernova |
| Eaton |
| Hyosung Heavy Industries |
| NR Electric Co. |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta industrial clusters around Shanghai and Suzhou anchor production capacity for ultra-high voltage transmission networks, concentrating manufacturing scale that translates into asymmetric pricing power for domestic suppliers serving China's 800 kV expansion. GB standards compliance and NMPA certification timelines create captive demand structures that insulate state-backed manufacturers from import competition, while grain-oriented electrical steel concentration among Japanese and European producers exposes transformer fabricators to input cost volatility.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing for converter transformers, with three-tier pricing structure across premium, standard, and economy levels determined by voltage class and harmonic loading specification complexity. Price differentiation rests on certification grade—GB, IEC, and IEEE compliance tiers—and volume scale, with super large scale 800 kV+ units commanding captive manufacturing relationships. Cost compression in the standard tier is intensifying because infrastructure funds demand 15-20 year fixed operational expenditure clauses, while renewable energy providers show highest price sensitivity due to project finance leverage constraints.
Supply Chain Analysis
Export control regimes limiting semiconductor and advanced materials flows have amplified scrutiny of critical input sourcing for converter transformer manufacturing. Geographic supply concentration centers on China, Germany, and South Korea for finished equipment, while grain-oriented electrical steel draws from Japan and European specialty mills. Raw material dependencies include copper winding stock, transformer oil formulations, and ceramic bushing insulators. Single-source vulnerability in electrical steel allocation creates structural risk. Distribution runs through EPC contractor bundling and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with specialized service providers as long-term performance guarantees unbundle from initial equipment sales across North Sea and Asia-Pacific offshore wind projects. Modular converter station designs and digital twin integration create niche entry points for predictive analytics specialists.
For Market Incumbents: Harden service contract architectures against emerging digital-native competitors by embedding physics-based modeling capabilities into 15-20 year operational agreements. Deepen backward integration into grain-oriented electrical steel sourcing to mitigate Nippon Steel and ThyssenKrupp allocation constraints. Prioritize GB standards pre-certification for Chinese ultra-high voltage corridor access before NMPA approval cycles lengthen further. For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian grid interconnection projects where Korean peninsula linkages demand 400 kV class equipment with localized service requirements. Target US Atlantic coast offshore wind procurement channels opened by FERC Order 2023 interconnection mandates. Pursue digital twin integration partnerships with existing valve hall operators as the go-to-market angle, offering predictive maintenance capabilities without manufacturing asset overhead. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-services compounding play because operational expenditure certainty clauses are restructuring buyer priorities toward performance guarantees over capital cost minimization. Acquisition targets should concentrate on regional fabricators with GB or NMPA certification pathways and embedded condition monitoring technology. Watch for inflection when carbon border adjustment mechanisms reshape transformer sourcing decisions in European procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Steel | Captive supply of grain-oriented core material mitigates Nippon Steel allocation constraints and input volatility. |
| Digital Twin Platform Development | Physics-based modeling convergence enables predictive maintenance contracts with offshore wind infrastructure funds. |
| GB Standards Pre-Certification | Early compliance with Chinese ultra-high voltage requirements bypasses 18-24 month NMPA approval barriers. |
| SF6-Free Bushing Specification | EU F-Gas Regulation alignment captures German and Danish grid operator tender preferences. |
| Long-Term Service Agreement Unbundling | Performance guarantee separation from equipment sales matches infrastructure fund risk transfer demands. |
Research Methodology
A standing panel of utility planning officers, EPC contractor procurement leads, offshore wind project developers, and transformer aftermarket service heads provided ongoing calibration across primary interview cycles. Secondary validation drew from FERC interconnection filings, IEA transmission investment databases, Chinese GB standards documentation, and EU Green Deal implementation progress reports. Bottom-up project pipeline aggregation triangulated against top-down grid expansion forecasts from national transmission operators.
Scenario-bracketing framed analytical projections across the modeling period, with segmentation dimensions spanning voltage class tier, installation environment exposure, end-user contract structure, and regional regulatory framework cluster. CAGRs were derived from unit volume buildups weighted by capacity-specific pricing trajectories. Forecast inputs incorporated offshore wind capacity target revisions and ultra-high voltage corridor approval timelines.
Sensitivities concentrate around electrical steel supply allocation shocks, NMPA certification timeline extensions, and carbon border adjustment mechanism implementation scope. Forecasts reflect documented assumptions on project finance availability and grid interconnection mandate enforcement. Material shifts in EU F-Gas Regulation phase-down schedules or Chinese dual carbon policy acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Liquid-Immersed Transformers Market
Transformers
Europe Transformer Market
Transformers
India Power Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Transformer Core Market
Transformers
United Arab Emirates Transformer Market
Transformers
North America Dry Type Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
India Transformer Market
Transformers
Latin America Transformer Market
Transformers
Power Transformer Market
Transformers
North America Smart Transformers Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Current Transformer Market
Transformers
China Transformer Market
Transformers
United States Power Transformer Market