
 Transfer Case Market | 2026-2036
Transfer Case Market Size, Share, and Industry Trends Forecast 2026-2036
Transfer Case Market Intelligence
Aftermarket service and component remanufacturing revenue is reshaping the competitive positioning of drivetrain suppliers. This shift creates new margin opportunities outside of original equipment manufacturer contracts. BorgWarner Inc. leverages its portfolio of electronic controls for active transfer case systems. Magna International Inc. competes with integrated drivetrain solutions that cater to both internal combustion and electric vehicle architectures. American Axle & Manufacturing Inc. specializes in durable systems for light commercial vehicles and high-performance trucks.
A transfer case is an electro-mechanical gearbox that distributes engine power from the transmission to both the front and rear axles. These systems typically feature selectable gear ranges, such as high-range for standard driving and low-range for increased torque in off-road conditions. The primary purpose is to enable four-wheel or all-wheel drive capability in a vehicle. Electronic shift systems are gaining share over traditional part-time mechanical units due to better fuel economy and driver convenience. While SUVs and pickups remain the dominant vehicle type segments, adoption in light commercial vehicles is also expanding.
Fuel economy regulations from the US Environmental Protection Agency (EPA) and vehicle emissions standards in the European Union push manufacturers toward lighter, more efficient transfer case designs. Concurrently, China's GB standards dictate performance and safety requirements for components used in the domestic automotive market. Suppliers must decide whether to optimize legacy mechanical systems for cost-sensitive segments or to invest in the software and controls for advanced electric all-wheel drive platforms.
Market Dynamics
The fundamental dynamic in the transfer case market is the technological transition from mechanical to electronic shift-on-the-fly systems. This evolution is driven by automaker demands for improved fuel efficiency, seamless integration with vehicle stability controls, and enhanced driver convenience.
Growth Catalysts
- Consumer Preference for AWD/4WD:Strong and sustained consumer demand for all-wheel and four-wheel drive configurations in SUVs and pickup trucks, particularly in the United States and China, directly fuels installations of new transfer case units.
- Emissions and Fuel Economy Standards:Regulations like the US EPA's fuel economy mandates and the European Union's vehicle emissions standards push for lighter, more efficient drivetrain components, favoring advanced electronic transfer cases over heavier mechanical ones.
- Expansion in Light Commercial Vehicles:Adoption is expanding beyond consumer vehicles into the light commercial vehicle segment, where 4WD capability is required for utility, construction, and last-mile delivery applications in varied terrain.
Market Restraints
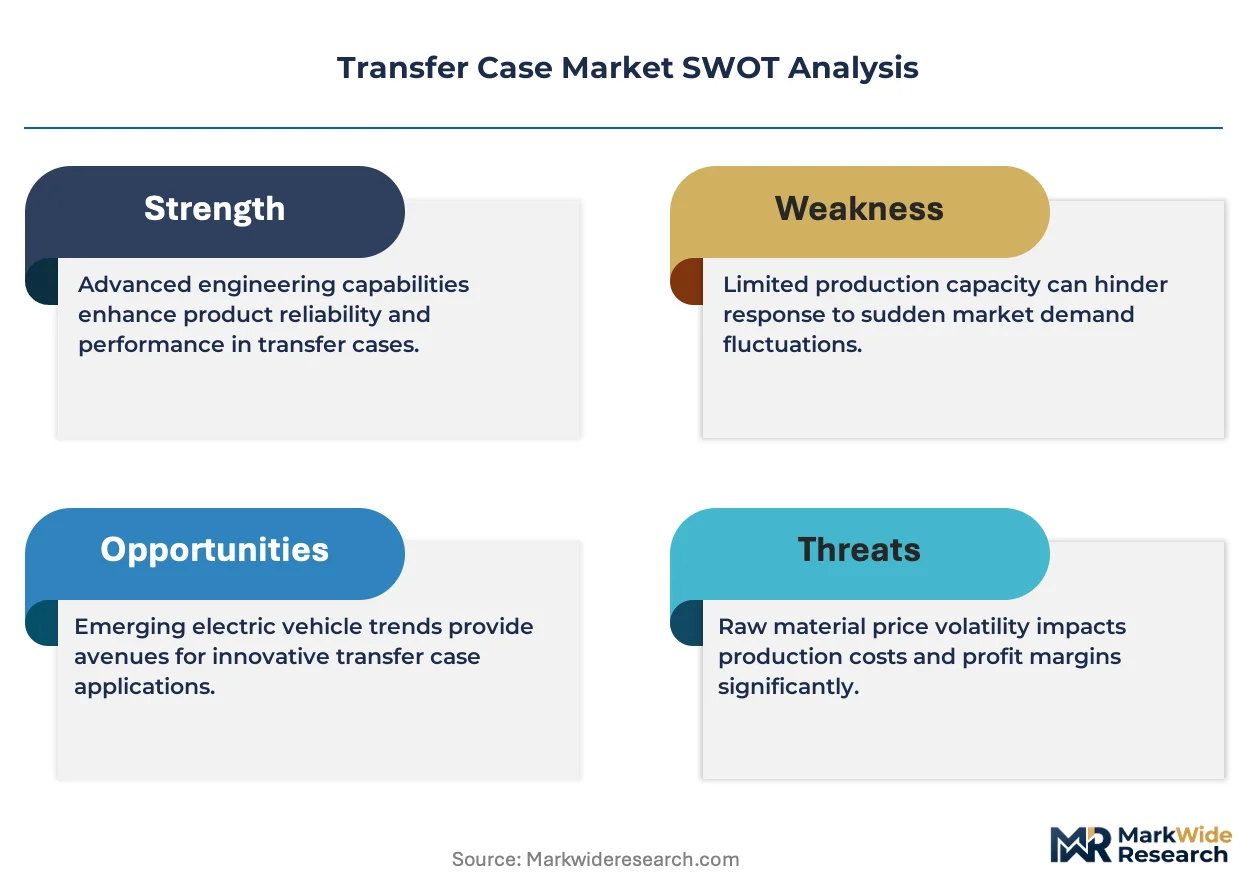
- Substitution by EV Architectures:The proliferation of battery-electric vehicle platforms using dual-motor e-axle designs for all-wheel drive capability directly substitutes the need for a traditional transfer case, posing a long-term structural threat.
- Higher System Cost and Complexity:Electronically controlled transfer cases carry a higher bill of materials and require more complex software integration than legacy mechanical systems, creating a cost barrier for economy and price-sensitive vehicle segments.
- Input Material Price Volatility:The cost of specialty steels, aluminum alloys, and electronic components like microcontrollers and sensors is subject to significant price fluctuations, impacting manufacturer margins and production planning.
Strategic Opportunities
- Aftermarket and Remanufacturing:Developing robust aftermarket service programs and remanufacturing capabilities for transfer cases and their sub-components presents a significant margin opportunity outside of OEM supply contracts.
- Integration with Predictive Drivetrains:There is an opportunity to integrate transfer case control logic with predictive terrain response systems that use sensor fusion and mapping data to proactively adjust torque distribution for optimal performance.
- Lightweight Material Development:Investing in the research and application of advanced composite materials or novel metal alloys can create a competitive advantage by offering lighter systems that help OEMs meet fuel economy targets.
Industry Challenges
- Software and Mechatronics Talent Gap:A shortage of engineers with combined expertise in mechanical systems, electronic controls, and software development creates a bottleneck for designing and validating next-generation active transfer case systems.
- Legacy System Integration:Ensuring backward compatibility and seamless communication between new electronic transfer case modules and existing vehicle bus architectures presents a significant technical and validation challenge for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transfer Case Market |
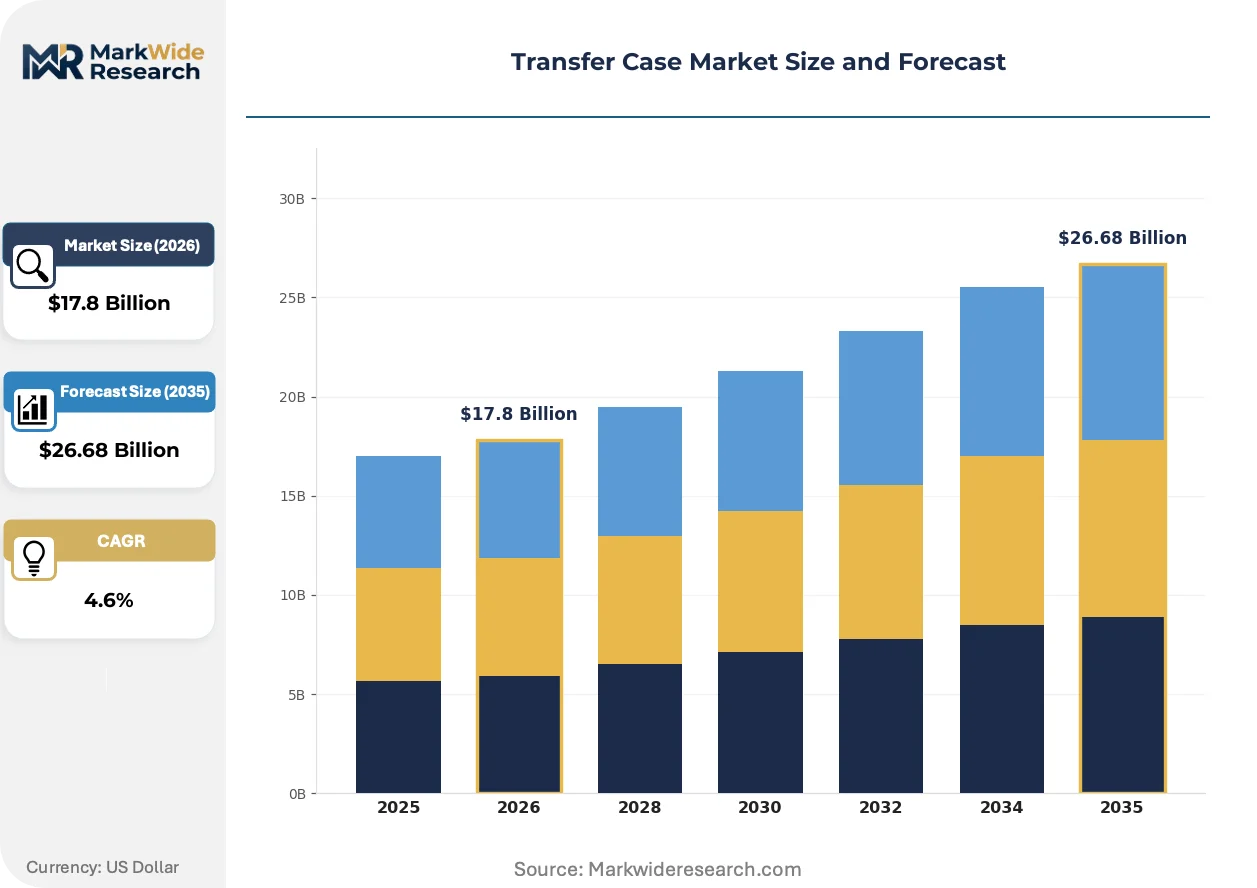
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Part-Time, Full-Time, Active, Electronic Shift Vehicle Type: Light Commercial Vehicles, Heavy Duty Vehicles, SUVs, Pickups Drive Type: Four-Wheel Drive, All-Wheel Drive, Rear-Wheel Drive, Front-Wheel Drive Distribution Channel: Original Equipment Manufacturer, Aftermarket Dealers, Online Retailers, Specialty Stores |
| Companies Covered | BorgWarner Inc., Magna International Inc., ZF Friedrichshafen AG, Aisin Corporation, GKN Automotive Ltd., American Axle & Manufacturing Inc., Dana Incorporated, JTEKT Corporation, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transfer Case Market Strategic Shifts & Innovations
The market's trajectory is defined by a push towards intelligent power distribution and system simplification. Innovations focus on reducing parasitic driveline losses and integrating control functions to support both internal combustion and hybrid powertrain architectures efficiently.
Active transfer cases with integrated electronic control units provide on-demand torque distribution between front and rear axles. SUV and pickup truck manufacturers are rapidly adopting these systems to improve traction, stability, and fuel economy without driver intervention. The proliferation of these intelligent systems is collapsing the traditional barrier between mechanical power transfer and software-defined vehicle dynamics control.
Strict fuel economy standards from the US Environmental Protection Agency (EPA) and vehicle CO2 targets in Europe are primary design constraints. This regulatory pressure forces engineers to minimize driveline drag and component weight, accelerating the development of disconnect systems that can decouple the front or rear axle when not needed. The full-size truck and SUV segments are most impacted, driving investment in lightweight casings and more efficient gearsets.
A notable behavioral change is emerging in vehicle procurement, particularly within commercial fleets and the performance enthusiast community. Buyers are increasingly prioritizing systems that offer selectable drive modes, such as sport, eco, or off-road, which require sophisticated transfer case software. This trend is most visible in the North American and Middle Eastern markets, where vehicle customization and specialized performance are highly valued.
Transfer Case Market Segmentation
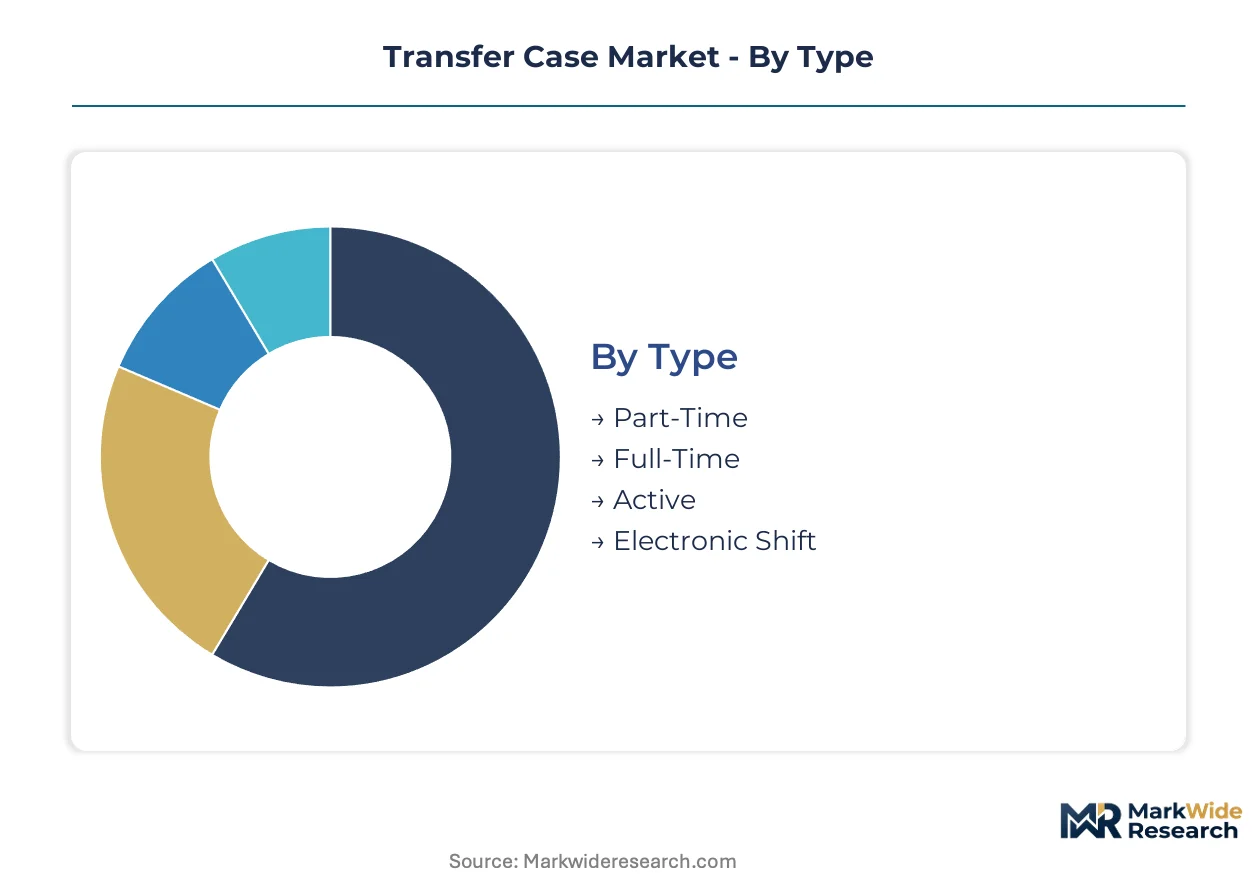
The Transfer Case Market segmentation provides a detailed understanding of how technology, vehicle application, and sales channels influence market dynamics. Analyzing these distinct categories helps identify specific growth pockets and competitive battlegrounds across the industry landscape. This granular view is essential for strategic planning and product development within the drivetrain sector.
Type:
The market's type segmentation reflects the spectrum of power distribution mechanisms available to vehicle manufacturers.
- Active:These systems employ electronic sensors and actuators to continuously monitor driving conditions, dynamically adjusting torque distribution between axles for optimal traction. Demand concentrates in premium SUV and performance pickup truck segments, driven by consumer preference for enhanced safety and handling.
- Electronic Shift:This type utilizes electronic controls for seamless engagement of two-wheel, four-wheel high, and four-wheel low modes, replacing mechanical levers. Adoption is widespread in modern SUVs and light commercial vehicles, offering driver convenience and integration with vehicle stability systems.
- Part-Time:Part-time transfer cases provide manually selectable 2WD, 4WD High, and 4WD Low modes, offering robust mechanical locking for off-road conditions.
- Full-Time:Full-time systems allow continuous power to all wheels, often incorporating a differential to manage speed differences between front and rear axles.
Established volume favors Part-Time systems; emerging adoption favors Electronic Shift technology.
Vehicle Type:
Vehicle type segmentation highlights the primary applications where transfer cases are integrated, influencing design and durability requirements.
- SUVs:Sport Utility Vehicles are a dominant application, integrating transfer cases to provide all-wheel or four-wheel drive capability for diverse terrains. Strong consumer preference in the United States and China fuels installations, particularly for recreational and family use.
- Pickups:Pickup trucks heavily utilize transfer cases for enhanced towing, hauling, and off-road performance, essential for commercial and recreational applications. Demand in North America remains robust, driven by utility requirements and payload capacities.
- Light Commercial Vehicles:This segment includes vans and smaller trucks requiring 4WD for varied work environments, including construction sites and delivery routes.
- Heavy Duty Vehicles:Heavy-duty trucks and specialized vehicles use transfer cases for extreme off-road capability and high-torque applications in sectors like mining and defense.
The SUV and Pickup segments collectively represent the most substantial volume, while Light Commercial Vehicles exhibit expanding demand.
Drive Type:
Drive type segmentation categorizes transfer cases by the specific wheel configurations they enable, impacting traction and vehicle dynamics.
- Four-Wheel Drive:Four-wheel drive systems offer selectable modes for transferring power to all four wheels, crucial for severe off-road conditions and heavy-duty tasks. Demand is concentrated in pickup trucks and rugged SUVs, particularly in markets like the United States.
- All-Wheel Drive:All-wheel drive systems continuously distribute power to all wheels, often with electronic control, enhancing traction and stability on paved and slippery surfaces. This configuration is gaining share in passenger SUVs and crossovers due to improved safety features.
- Rear-Wheel Drive:While not directly using a transfer case for power distribution, rear-wheel drive vehicles form the base for many 4WD and AWD conversions.
- Front-Wheel Drive:Front-wheel drive vehicles typically do not incorporate a transfer case, as power is directed solely to the front axle for propulsion.
Four-Wheel Drive systems command significant market presence, with All-Wheel Drive configurations demonstrating rapid market penetration.
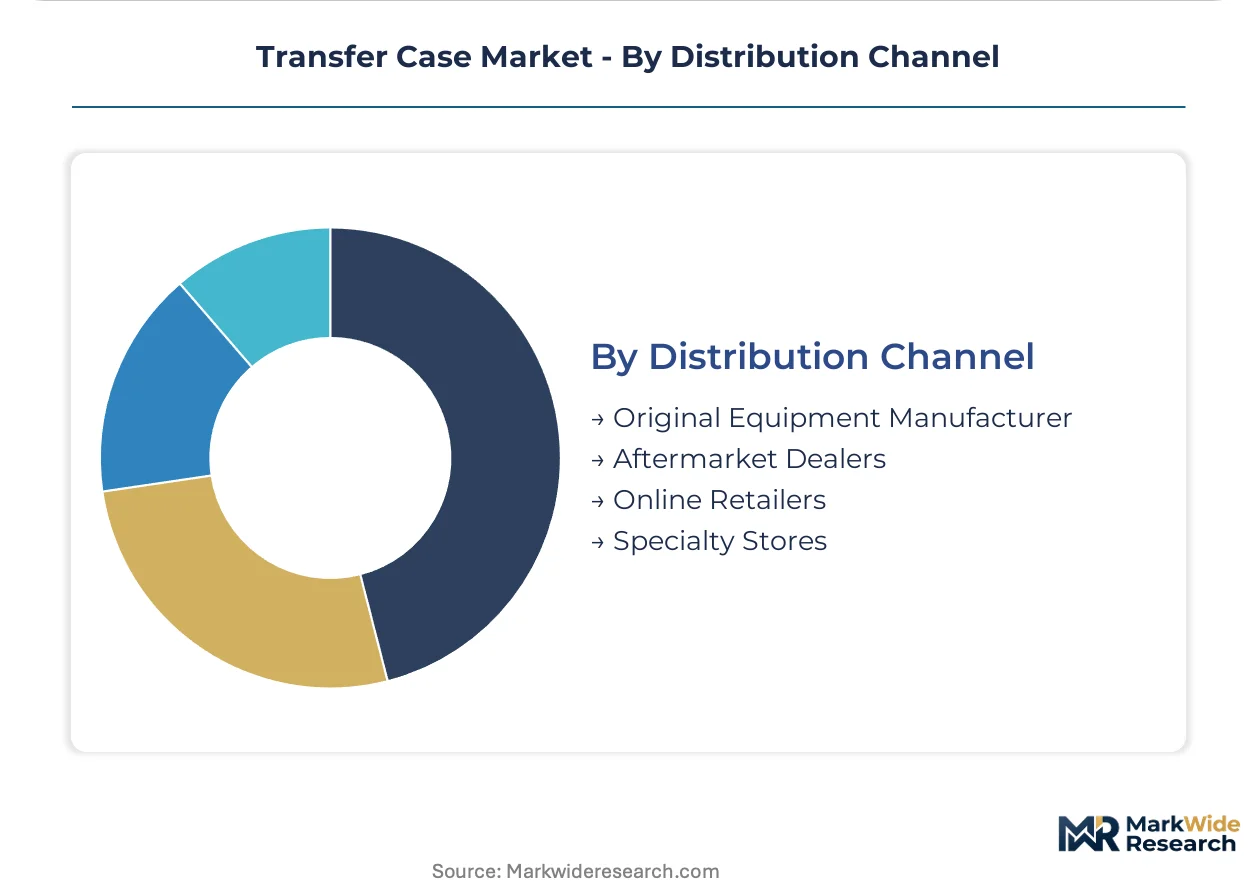
Distribution Channel:
Distribution channel segmentation outlines the primary routes through which transfer case components reach end-users and vehicle assemblers.
- Original Equipment Manufacturer:The OEM channel involves direct supply of transfer cases to vehicle manufacturers for integration into new vehicle production lines. This segment represents the largest volume, driven by new vehicle sales and model refreshes across all vehicle types.
- Aftermarket Dealers:Aftermarket dealers supply replacement transfer cases and components for vehicle repairs, maintenance, and performance upgrades. This channel offers significant margin opportunities, particularly for older vehicles and specialized off-road modifications.
- Online Retailers:Online platforms provide direct-to-consumer sales of transfer cases and related parts, offering convenience and competitive pricing for DIY enthusiasts and repair shops.
- Specialty Stores:Specialty stores cater to niche markets, providing high-performance or custom transfer cases for off-road racing, rock crawling, and other specialized vehicle applications.
Original Equipment Manufacturer contracts drive initial market volume, with aftermarket channels crucial for maintenance and component replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for transfer cases varies significantly across global markets. Premium vehicle segments in developed economies often prioritize advanced electronic systems, showing lower price sensitivity. Conversely, cost-sensitive segments in emerging markets still favor robust, simpler mechanical units.
United States
Demand for four-wheel drive and all-wheel drive vehicles remains strong in the United States, particularly for large SUVs and pickup trucks. US EPA fuel economy regulations drive manufacturers towards lighter, more efficient transfer case designs. Automotive production in Michigan's Detroit area focuses on integrating advanced active transfer case systems into new vehicle platforms.
China
Consumer preference for SUVs and light commercial vehicles drives substantial transfer case installations in China. China's GB standards dictate performance and safety requirements for automotive components, influencing local production. Manufacturing hubs in the Yangtze River Delta concentrate on developing and producing electronic shift transfer cases for the domestic market.
Germany
European vehicle emissions standards push German automakers towards highly efficient and lightweight transfer case solutions. The EU Green Deal accelerates the adoption of advanced electronic systems for improved fuel economy. Automotive suppliers in Bavaria focus on precision engineering and software integration for premium active transfer cases.
Japan
Japanese vehicle manufacturers prioritize reliability and compact design in transfer case development for both domestic and export markets. METI guidelines encourage the adoption of advanced technologies that enhance vehicle performance and environmental efficiency. Automotive component clusters in Aichi Prefecture specialize in sophisticated drivetrain manufacturing and assembly.
India
The expanding light commercial vehicle segment and increasing SUV sales in India create a consistent demand for durable transfer cases. India's national automotive regulations influence component design to suit varied road conditions. Automotive manufacturing zones like Pune and Chennai are seeing increased production of both part-time and electronic shift transfer cases.
Transfer Case Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, defining the competitive landscape. The market exhibits a tiered structure, with established automotive suppliers dominating the original equipment manufacturer segment. Several strategic archetypes emerge, including integrated drivetrain specialists, component manufacturers, and aftermarket service providers. Key competitive moves involve strategic partnerships for technology development and portfolio diversification into electronic systems.
Integrated drivetrain specialists, exemplified by suppliers like BorgWarner Inc., focus on advanced electronic control units and active transfer case systems, catering to premium and performance vehicles. Canadian-based Magna International Inc. represents companies offering comprehensive drivetrain solutions for both internal combustion and electric vehicle architectures, emphasizing modularity. American Axle & Manufacturing Inc. occupies a position among specialists in durable systems for light commercial vehicles and high-performance trucks, ensuring robust performance. These companies anchor innovation and supply chain reliability across diverse vehicle segments globally.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Magna International Inc. |
| ZF Friedrichshafen AG |
| Aisin Corporation |
| GKN Automotive Ltd. |
| American Axle & Manufacturing Inc. |
| Dana Incorporated |
| JTEKT Corporation |
| Schaeffler AG |
Cost & Logistics Intelligence
Input material price volatility for specialty steels and microcontrollers determines both pricing tier spreads and the supply chain shape for transfer case manufacturers. This fluctuation impacts manufacturer margins and production planning across all segments.
Pricing Analysis
Aftermarket service and component remanufacturing revenue drives lifetime value for drivetrain suppliers. The dominant pricing structure for original equipment manufacturers involves contract-based long-term offtake agreements. Price differentiation stems from technology sophistication, such as active electronic controls, and the durability required for heavy-duty applications. Pricing pressure intensifies within economy vehicle segments due to the higher bill of materials for electronic shift systems. Premium SUV and performance pickup truck buyers exhibit lower price sensitivity compared to cost-conscious light commercial vehicle segments.
Supply Chain Analysis
Single-source vulnerability for advanced electronic components like microcontrollers presents a structural risk within the transfer case supply chain. Production concentrates in key automotive manufacturing hubs, including China, Germany, and Japan. Manufacturers rely on specialty steels and aluminum alloys for casings, alongside complex sensor arrays. The primary distribution model involves direct supply to Original Equipment Manufacturers for new vehicle production lines. Aftermarket channels provide replacement units for maintenance and upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transfer case market is at a platform-economics inflection point, driven by the collapsing barrier between mechanical power transfer and software-defined vehicle dynamics control. This shift necessitates seamless integration with predictive drivetrains and vehicle stability systems.
For Market Incumbents: Insulate core market share by accelerating investment in software and controls for advanced electric all-wheel drive platforms. Develop robust aftermarket service programs and remanufacturing capabilities to counter margin pressure from new OEM contracts. This strategic lever helps mitigate the long-term structural threat of substitution by dual-motor EV architectures. Focus R&D on integrated electronic control units to maintain competitive edge.
For New Entrants and Emerging Players: Establish a beachhead in the expanding light commercial vehicle segment, which requires durable 4WD capability for varied terrain. Focus on developing cost-effective electronic shift systems that offer enhanced fuel economy for price-sensitive buyers. A key white-space target involves integrating transfer case control logic with predictive terrain response systems. The go-to-market angle should emphasize efficiency gains and ease of integration with existing vehicle architectures.
For Investors and Strategic Acquirers: The EU Green Deal reshapes the acquisition landscape, favoring companies with advanced electronic and lightweight transfer case solutions. Long-term viability for this market remains strong over the next decade, particularly for intelligent power distribution. Acquisition targets should include firms specializing in software and mechatronics. The signal to watch is the accelerating adoption rate of dual-motor e-axle designs in mainstream SUV and pickup platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Control Investment | Enhances drivetrain efficiency and integration with modern vehicle safety controls for OEMs. |
| Lightweight Material Development | Helps vehicle manufacturers meet US EPA fuel economy regulations and EU emissions standards. |
| Aftermarket Service Expansion | Creates new margin opportunities outside of original equipment manufacturer contracts. |
| Predictive Drivetrain Integration | Allows proactive torque distribution for optimal performance using sensor fusion and mapping data. |
| Electrified Drivetrain Compatibility | Prepares transfer case systems for seamless integration with hybrid and electric vehicle architectures. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews. Discussions involved OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and drivetrain R&D directors. This primary data was validated against extensive secondary research, including vehicle production databases, IHS Markit registration data, and relevant industry reports. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
Market sizing calibration involved a multi-stage process, integrating historical trends with projected shifts across the analysis window. The quantitative model segmented data by type, vehicle type, drive type, distribution channel, and electronic integration level. Compound annual growth rates were derived from volume and value data. Key forecast inputs included vehicle production forecasts and regulatory compliance timelines.
Sensitivities concentrate around geopolitical shifts, raw material price fluctuations, and the pace of EV adoption. Forecasts reflect underlying assumptions regarding technological advancements. Input material price volatility and EV architecture substitution pose key risks for revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Automotive Paint Robots Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
Qatar Commercial Vehicles Lubricants Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Automotive Lifts Market