
 South Africa Automotive Lubricants Market | 2026-2036
South Africa Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Lubricants Market Analytics
SABS 1191 certification for automotive lubricant quality is collapsing the supplier base to technically qualified blenders. Sasol leverages its Secunda refinery complex to sustain captive base oil supply. Shell plc anchors retail throughput via Engen Petroleum's forecourt network. BP PLC (Castrol) differentiates through OEM co-branding with domestic vehicle assemblers.
Automotive lubricants are formulated mixtures of base oils and additive packages engineered to reduce friction, dissipate heat, and prevent wear in powertrain components, with viscosity grades such as SAE 5W-30 defining cold-start and operating-temperature performance. Engine oil dominates value capture due to high drain-frequency requirements across aging passenger vehicle parc. Transmission fluid represents the fastest-growing product category as automatic gearbox penetration rises in urban commuter segments. Heavy machinery end users generate premium margin pools through bulk supply contracts tied to mining and construction uptime guarantees.
The Department of Mineral Resources and Energy enforces fuel and lubricant specifications under the Petroleum Products Act, while SABS maintains voluntary quality marks that major fleet operators mandate in procurement tenders. The National Regulator for Compulsory Specifications can declare lubricant standards mandatory, reshaping market access for imported formulations. Stakeholders must monitor alignment between SABS testing protocols and OEM service-fill specifications as powertrain electrification alters fluid duty cycles.
Market Dynamics
The South Africa Automotive Lubricants Market is undergoing structural compression as SABS 1191 certification requirements eliminate technically deficient blenders and consolidate procurement authority among fleet operators with preventive maintenance mandates.
Growth Catalysts
- Emissions compliance timelines:The Department of Transport has tightened commercial vehicle emissions standards, forcing fleet operators to expand oil analysis programs and shorten drain intervals to protect aftertreatment systems.
- Gauteng logistics concentration:The Johannesburg-Pretoria freight corridor generates the highest lubricant throughput in the country, with distribution nodes clustering around major highway interchanges and industrial parks.
- Automatic transmission penetration:Urban commuter segments are adopting automatic gearboxes at accelerating rates, creating pull-through demand for specialized transmission fluids with extended service-life formulations.
Market Restraints
- Base oil supply concentration:Captive refinery output from Secunda limits independent blender access to Group II and III base stocks, constraining formulation flexibility for mid-tier suppliers.
- Import dependency for additive packages:Specialty friction modifiers and detergents arrive through Durban port channels, exposing blenders to currency volatility and shipping schedule disruptions.
- Powertrain electrification substitution:Battery electric vehicle adoption in corporate fleets is eliminating internal combustion engine oil demand in premium urban delivery segments.
Strategic Opportunities
- Western Cape underpenetration:Cape Town's port logistics and wine industry transport fleets remain underserved by technical service programs, offering white space for certified distributors with mobile oil analysis capabilities.
- Mining uptime guarantees:Heavy machinery operators in platinum and coal belts are negotiating bulk supply contracts tied to equipment availability metrics, creating premium margin pools for suppliers with predictive maintenance integration.
- OEM co-branding frameworks:Domestic vehicle assemblers are seeking lubricant partners for factory-fill and service-fill specifications, rewarding blenders with aligned testing protocols and local technical support infrastructure.
Industry Challenges
- SABS 1191 certification timeline compression:Blend facilities must complete laboratory accreditation and product testing cycles before tender deadlines, straining quality assurance staffing and capital equipment budgets.
- Electrified powertrain fluid complexity:Thermal management fluids for battery packs and electric motors require new additive chemistry expertise that existing formulators lack, demanding recruitment of specialized tribologists and chemists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Lubricants Market |
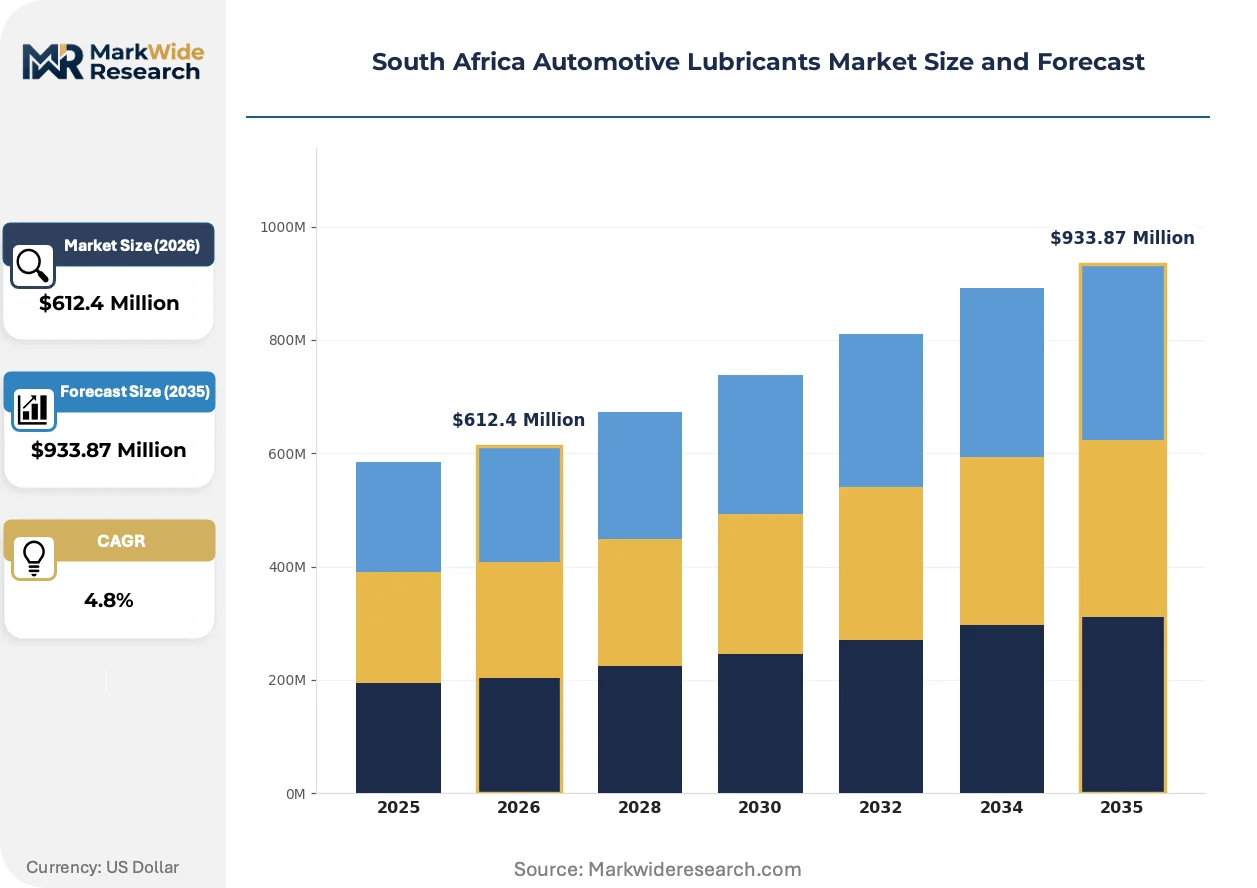
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $933.87 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Grease End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery Distribution Channel: Online Retail, Auto Parts Store, Service Stations, Supermarkets Service Type: Preventive Maintenance, Fluid Change, Inspections, Refueling Services |
| Companies Covered | BP PLC (Castrol), Sasol, Shell plc, TotalEnergies, Engen Petroleum Ltd, ExxonMobil Corporation, FUCHS, Puma Energy, Astron Energy Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Lubricants Market Evolving Landscape
Fluid formulation chemistry and procurement authority are simultaneously shifting in the South Africa Automotive Lubricants Market, with technical certification requirements and fleet operator consolidation rewriting competitive access rules.
Lower-viscosity engine oil grades are fragmenting the product mix as OEM specifications push toward SAE 0W-16 and 5W-20 formulations for fuel economy compliance. Passenger vehicle dealerships in Gauteng and KwaZulu-Natal are adopting these grades for newer model-year fleets, compressing demand for traditional 15W-40 mineral oils and forcing blenders to reconfigure base oil procurement toward Group III synthetics.
The Department of Mineral Resources and Energy is tightening enforcement under the Petroleum Products Act, with draft amendments expected to empower the National Regulator for Compulsory Specifications to mandate lubricant quality standards. This regulatory trajectory is accelerating blender consolidation, as smaller operators lack capital to upgrade testing infrastructure for compulsory specification compliance, and is redirecting import flows toward pre-certified formulations from established supply relationships.
Fleet procurement departments are centralizing lubricant buying decisions and unbundling after-sales service from product supply. Large commercial operators in mining and long-haul trucking are negotiating direct contracts with certified blenders, bypassing traditional distributor networks in favor of bulk tank installations and scheduled technical service visits, with this pattern most visible in the platinum belt around Rustenburg and the coal transport corridors through Mpumalanga.
South Africa Automotive Lubricants Market Segmentation
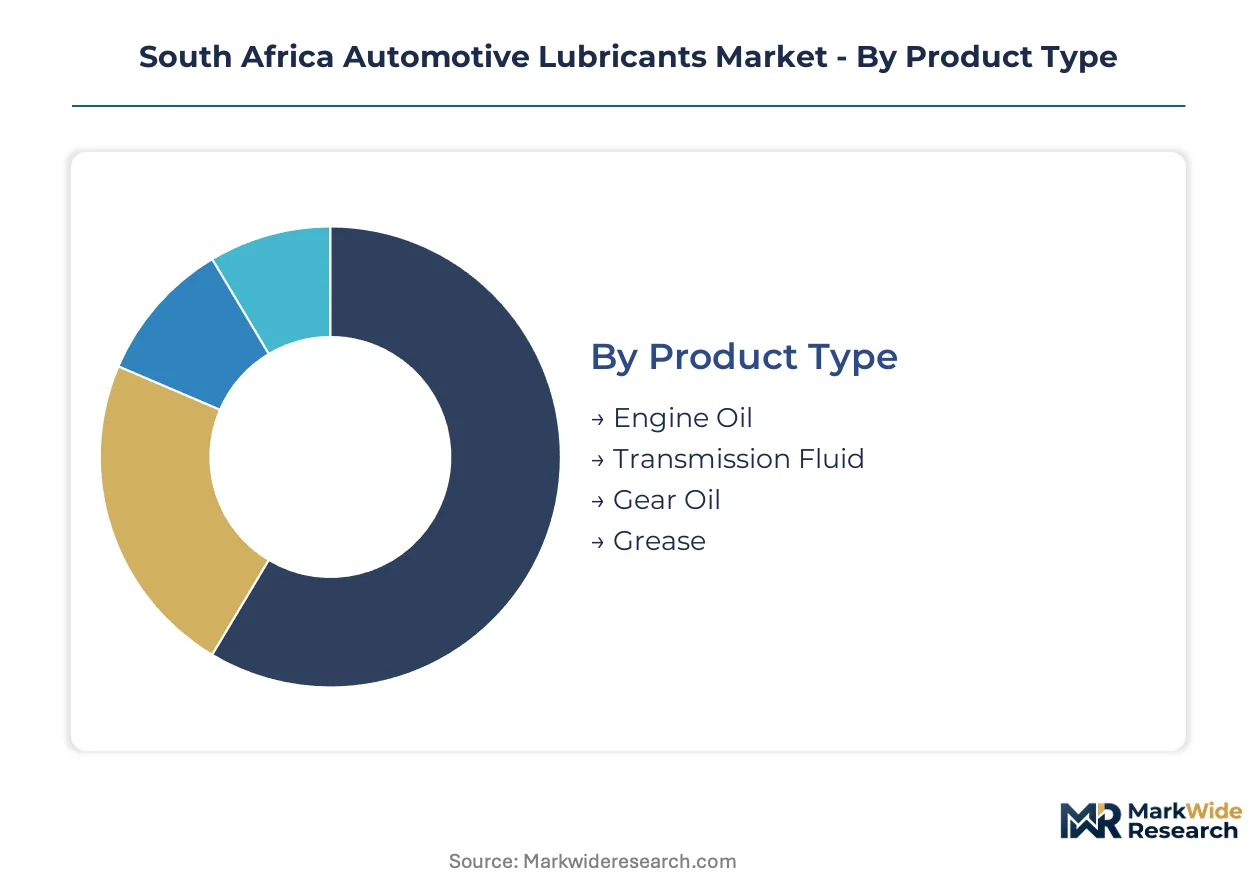
Segmentation in South Africa's automotive lubricants market reveals how regulatory pressure and fleet consolidation are reshaping demand concentration across product categories. Each dimension exposes different vulnerability to electrification substitution and certification barriers.
Product Type:
Electrification poses asymmetric substitution threats across lubricant chemistries, with powertrain-specific formulations facing divergent demand trajectories as battery electric vehicles penetrate corporate fleets.
- Engine Oil:Formulated from base oil stocks blended with detergent-dispersant, anti-wear, and viscosity-index improver packages to protect internal combustion powertrains. Demand concentrates in Gauteng's aging passenger vehicle parc and long-haul trucking corridors, where extended drain intervals clash with tightened emissions compliance timelines forcing more frequent changes.
- Transmission Fluid:Specialized hydraulic fluids engineered with friction modifiers and oxidation inhibitors for gearbox thermal management. Johannesburg-Pretoria urban commuter segments are driving accelerated adoption of automatic transmissions, pulling through demand for extended-service-life synthetic formulations that command premium positioning.
- Gear Oil:High-viscosity lubricants with extreme-pressure additives for differential and axle protection in commercial applications.
- Grease:Semi-solid lubricants combining base oil with thickening agents for chassis and bearing applications in mining equipment.
Engine oil anchors the volume base while transmission fluid gains share at the steepest rate.
End User:
Cost tier stratification separates premium technical service contracts from commodity spot purchases, with certification requirements acting as a pricing wedge between fleet operators and individual consumers.
- Passenger Vehicles:Individual owners and small fleet operators maintaining sedans, SUVs, and light trucks through dealer networks and independent service centers. KwaZulu-Natal dealership channels are adopting lower-viscosity synthetic grades for newer model-year vehicles, compressing demand for traditional mineral formulations.
- Commercial Vehicles:Long-haul trucking and urban delivery fleets with centralized procurement departments negotiating direct blender contracts. The Department of Transport's tightened emissions standards are forcing oil analysis programs and shortened drain intervals to protect aftertreatment systems across the Johannesburg-Pretoria freight corridor.
- Two-Wheelers:Motorcycle and scooter owners in urban commuter segments with price-sensitive maintenance patterns.
- Heavy Machinery:Mining and construction operators in platinum and coal belts negotiating bulk supply contracts tied to equipment availability guarantees.
Commercial vehicles dominate value capture while heavy machinery commands the highest margin per liter.
Distribution Channel:
Volume concentration follows logistics infrastructure, with highway-adjacent nodes capturing the bulk of fleet procurement while digital channels fragment the retail base.
- Auto Parts Store:Independent retailers and chain outlets serving DIY mechanics and small workshops with immediate availability requirements. Western Cape distributors are expanding technical service capabilities to capture underserved Cape Town port logistics and wine industry transport fleets.
- Service Stations:Forecourt-attached workshops and quick-lube bays handling drive-in maintenance for time-sensitive operators. Engen Petroleum's network anchors retail throughput in Gauteng and KwaZulu-Natal, with bulk tank installations replacing packaged goods for fleet accounts.
- Online Retail:E-commerce platforms targeting price-comparison shoppers with delivery friction limiting penetration.
- Supermarkets:Mass-market retailers stocking economy-grade packaged lubricants for emergency top-up purchases.
Service stations retain the highest throughput while auto parts stores are expanding technical differentiation fastest.
Service Type:
Customer type bifurcation separates predictive maintenance contracts from reactive service events, with procurement centralization favoring integrated fluid management over transactional exchanges.
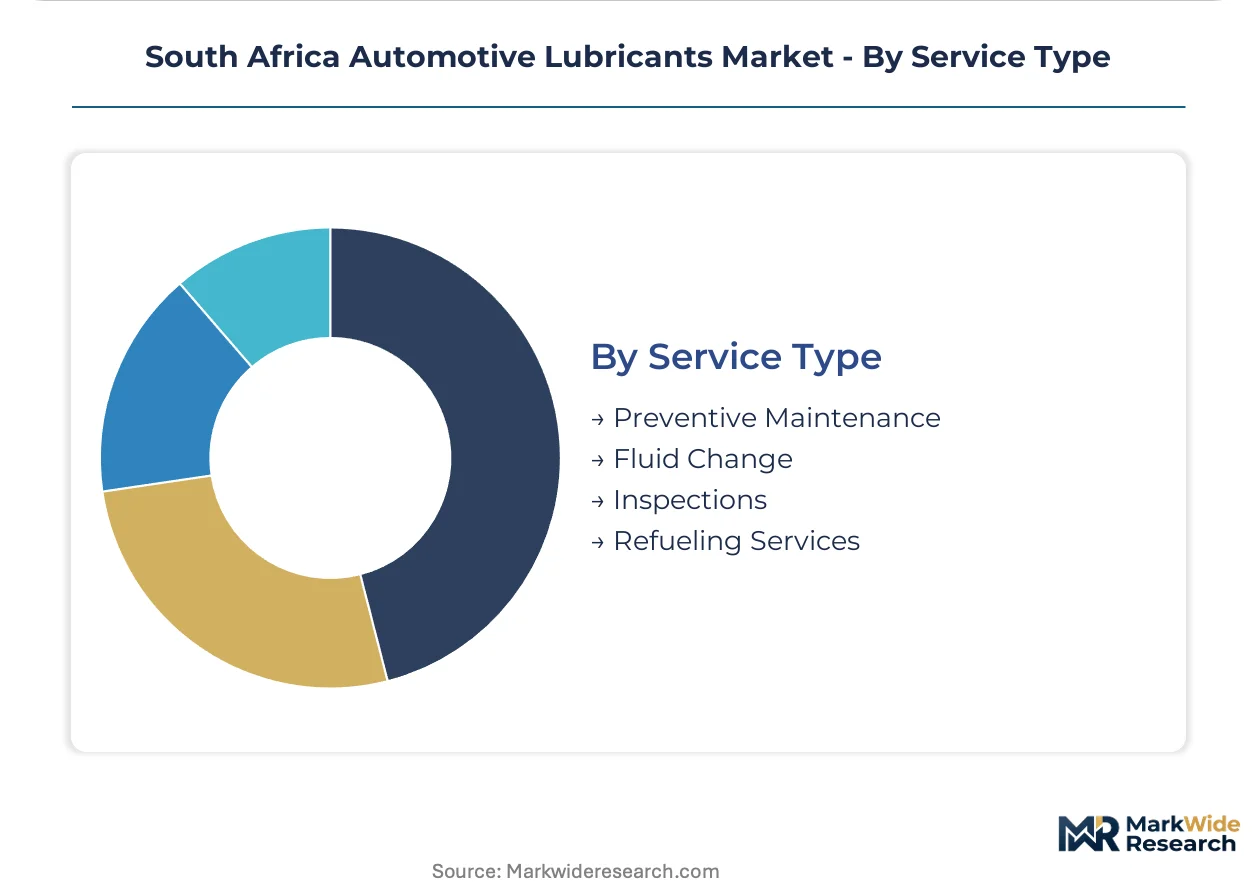
- Preventive Maintenance:Scheduled oil analysis and component replacement programs designed to eliminate unplanned downtime. Rustenburg platinum belt and Mpumalanga coal transport corridor operators are unbundling after-sales service from product supply, negotiating direct blender relationships with predictive maintenance integration.
- Fluid Change:Standard drain-and-fill operations at prescribed intervals, still dominant in individual owner segments but losing share to condition-based approaches in fleet accounts.
- Inspections:Diagnostic assessments of lubricant condition and component wear without immediate fluid replacement.
- Refueling Services:Combined fuel and lubricant top-up operations at highway service centers for long-haul operators.
Preventive maintenance commands expanding contract value while fluid change retains the highest transaction frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Transport's emissions compliance timelines are redistributing lubricant demand across South Africa's provinces, with fleet operators centralizing procurement in logistics-dense corridors and certified blenders following technical service contracts into underpenetrated territories.
Gauteng
The Johannesburg-Pretoria freight corridor generates the highest lubricant throughput in South Africa, with distribution nodes clustering around major highway interchanges and industrial parks. Fleet operators here are shortening drain intervals to protect aftertreatment systems under tightened emissions standards. Rustenburg platinum belt operators negotiate direct blender contracts with predictive maintenance integration, bypassing traditional distributor networks.
KwaZulu-Natal
Dealership channels in Durban and surrounding areas are adopting lower-viscosity synthetic grades for newer model-year vehicles, compressing demand for traditional mineral formulations. The province's port infrastructure channels additive package imports through Durban, exposing blenders to currency volatility and shipping schedule disruptions. Engen Petroleum's forecourt network anchors retail throughput across coastal urban centers.
Western Cape
Cape Town's port logistics and wine industry transport fleets remain underserved by technical service programs, offering white space for certified distributors with mobile oil analysis capabilities. SABS 1191 certification requirements are collapsing the supplier base as smaller operators lack capital to upgrade testing infrastructure. Auto parts stores are expanding technical differentiation fastest in this region.
Mpumalanga
Coal transport corridors through this province are driving bulk supply contract negotiations tied to equipment availability metrics, creating premium margin pools for suppliers with predictive maintenance integration. Heavy machinery operators here demand grease and gear oil formulations with extreme-pressure additives for mining equipment uptime guarantees. The concentration of mining activity sustains year-round demand irrespective of passenger vehicle seasonal patterns.
North West
The platinum mining belt around Rustenburg is unbundling after-sales service from product supply, with operators negotiating direct relationships with certified blenders for bulk tank installations and scheduled technical service visits. SABS 1191 certification is eliminating technically deficient blenders from tender participation in this procurement-centralized segment. Mining uptime guarantees are reshaping contract structures toward outcome-based fluid management.
South Africa Automotive Lubricants Market Competitive Landscape
Player mix skews toward integrated refinery operators and multinational petroleum majors with captive distribution networks. The market exhibits tiered concentration, with three to four entities controlling base oil supply and forecourt access while mid-tier blenders compete on certification compliance and fleet contract specialization. Strategic archetypes include upstream-integrated refiners, global lubricant formulators with OEM co-branding frameworks, and regional distributors expanding mobile technical service capabilities. Competitive moves center on SABS 1191 certification acquisition and direct fleet contract negotiation, with secondary pressure on additive package sourcing security.
Among upstream-integrated operators, Sasol leverages its Secunda refinery complex to sustain captive base oil supply, representing the refiner-archetype with backward integration into Group II and III base stocks. Shell plc anchors retail throughput via Engen Petroleum's forecourt network, exemplifying the multinational-major model with distribution density in Gauteng and KwaZulu-Natal. BP PLC (Castrol) occupies a position within the OEM-aligned tier, differentiating through co-branding relationships with domestic vehicle assemblers for factory-fill and service-fill specifications.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| Sasol |
| Shell plc |
| TotalEnergies |
| Engen Petroleum Ltd |
| ExxonMobil Corporation |
| FUCHS |
| Puma Energy |
| Astron Energy Pty Ltd |
| Others |
Value Network & Pricing Analysis
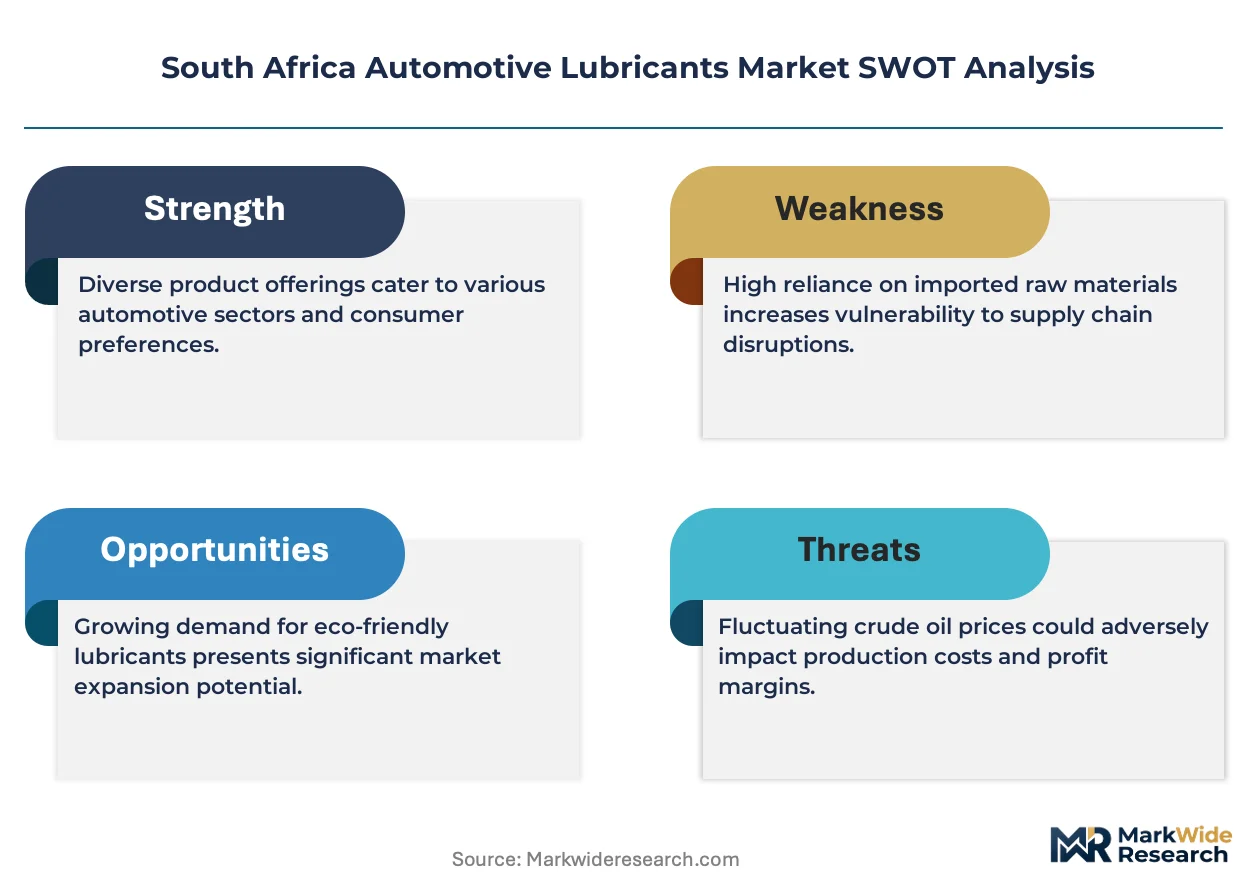
Group III synthetic base oil substitution for mineral stocks is redrawing procurement geography toward Secunda refinery output while compressing margin structures for blenders locked into import-dependent additive sourcing. This input shift simultaneously concentrates supply leverage among upstream-integrated operators and forces mid-tier competitors into cost-pass-through pricing against currency-exposed import bills.
Pricing Analysis
Certification level under SABS 1191 creates the primary spread between premium technical service contracts and commodity spot purchases. Three-tier pricing structure across SABS-certified premium, standard commercial, and unmarked economy levels stratifies the market, with fleet procurement centralization in Gauteng and Mpumalanga driving volume discounts that squeeze distributor margins. Cost compression in the mid-tier is intensifying because independent blenders lack captive base oil access and must absorb rand-dollar volatility on additive package imports. Individual passenger vehicle owners through auto parts stores exhibit highest price sensitivity, while mining operators with uptime guarantees show lowest sensitivity due to outcome-based contract structures.
Supply Chain Analysis
Inventory lead times for specialty friction modifiers and detergent packages extend 8-12 weeks through Durban port channels, exposing blenders to shipping schedule disruptions and foreign exchange risk. Geographic supply concentration centers on South Africa's Secunda refinery complex for Group II and III base stocks, with additive chemistry dependencies drawing from Germany, Singapore, and the United States. Single-source vulnerability pervades the mid-tier blender segment, where formulation flexibility rests on pre-certified additive relationships with limited supplier alternatives. Distribution runs through highway-adjacent bulk tank installations for fleet accounts and Engen Petroleum forecourt networks for retail throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation offers entry niches as SABS 1191 certification eliminates technically deficient blenders and fleet procurement centralization unbundles service from product supply.
For Market Incumbents: Compound defensive positioning through backward integration into additive package sourcing and predictive maintenance service capabilities. Sasol's captive Secunda refinery supply demonstrates the leverage available from upstream control over base oil stocks. Shell plc's Engen Petroleum forecourt density in Gauteng and KwaZulu-Natal illustrates channel lock-in against distributor disintermediation. Threat substitution from battery electric vehicle fleet adoption demands accelerated thermal management fluid R&D to capture electrified powertrain service-fill specifications. For New Entrants and Emerging Players: SABS 1191 certification fast-track through laboratory accreditation partnerships offers the clearest path around capital-intensive testing infrastructure barriers. Western Cape technical service underpenetration presents the most accessible white space, with Cape Town port logistics and wine industry transport fleets lacking mobile oil analysis capabilities. Mining uptime guarantee contracts in the platinum belt around Rustenburg reward predictive maintenance integration over commodity product supply. Go-to-market positioning as certified fluid managers rather than packaged goods distributors aligns with fleet procurement centralization trends. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier blenders with SABS 1191 compliance and established fleet contract relationships in mining or long-haul trucking corridors. The 5-10 year viability window favors suppliers with demonstrated predictive maintenance integration and backward integration pathways into base oil or additive sourcing. Acquisition target archetypes include regional distributors with mobile technical service capabilities in underpenetrated provinces. The signal to watch is National Regulator for Compulsory Specifications declarations mandating lubricant standards, which would accelerate consolidation by eliminating non-compliant operators from tender participation.| Strategic Initiative | Industry Significance |
|---|---|
| SABS 1191 Certification Investment | Qualifies blenders for fleet procurement tenders as regulatory compliance tightens. |
| Backward Integration into Additive Sourcing | Reduces currency exposure and secures formulation flexibility for mid-tier competitors. |
| Predictive Maintenance Service Integration | Captures premium margins from mining uptime guarantee contracts in Rustenburg belt. |
| Western Cape Distribution Expansion | Addresses technical service gaps in Cape Town port logistics and wine transport fleets. |
| Thermal Management Fluid Development | Positions suppliers for battery electric vehicle service-fill specifications as electrification advances. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Petroleum Products Act enforcement records, SABS certification databases, customs import data, and OEM service-fill specifications. Primary interviews engaged lubricant blender operations managers, fleet procurement directors at mining and trucking operators, aftermarket distribution channel heads, and Department of Mineral Resources and Energy regulatory officers. Secondary validation drew from Engen Petroleum network disclosures, Sasol refinery output reports, and vehicle registration parc data. Bottom-up demand modeling triangulated against top-down market sizing from base oil consumption and additive import volumes.
Segmentation dimensions modeled include product type across engine oil, transmission fluid, gear oil, and grease categories; end user segments spanning passenger vehicles, commercial vehicles, and heavy machinery; distribution channels through service stations, auto parts stores, and direct fleet contracts; and service type bifurcation between preventive maintenance and reactive fluid change. CAGRs were derived from trend extrapolation of base oil demand, fleet expansion patterns, and emissions compliance timeline impacts across the projection horizon. Industry-specific forecast inputs incorporated automatic transmission penetration rates and battery electric vehicle fleet adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained mining activity levels, stable rand-dollar exchange rates, or unchanged SABS certification timelines would require recalibration. Forecasts reflect documented assumptions about fleet procurement centralization velocity and powertrain electrification substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Steering System Market
Automotive Parts
Suspension Spring Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Oil Filter Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Speed Bump Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
South America Passenger Vehicles Lubricants Market