
 ASEAN Automotive Bearings Market | 2026-2036
ASEAN Automotive Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Automotive Bearings Market Outlook
Modular bearing-hub assemblies is repositioning procurement patterns across ASEAN vehicle assemblers. NTN Bearing Corporation leverages its integrated manufacturing footprint in Thailand to supply localized hub units. Schaeffler AG anchors European OEM programs with precision tapered bearing systems engineered for tropical operating conditions. JTEKT Corporation dominates steering-column bearing contracts through direct technical collaboration with Japanese vehicle assemblers operating in the region.
Automotive bearings are precision-engineered rotational components manufactured from hardened steel alloys or ceramic composites, designed to reduce friction between moving shaft and stationary housing interfaces while managing radial and axial loads in powertrain, chassis, and steering subsystems. Ball bearings occupy the highest volume tier across ASEAN passenger vehicle assembly lines due to standardized dimensional envelopes and established supplier tooling. Roller bearings sustain premium pricing in commercial vehicle and heavy-duty equipment applications where load ratings exceed ball bearing thresholds. Ceramic material formulations represent the fastest-growing specification segment as thermal management requirements intensify in electrified powertrains.
Thailand's Industrial Standards Institute enforces TISI certification for bearing fatigue life and dimensional tolerance, conditioning market access for imported components. Indonesia's Ministry of Industry implements domestic content requirements through TKDN regulations that compel local bearing assembly or forging operations. Vietnam's Ministry of Science and Technology aligns national standards with ISO 492 and ISO 281 through Decree 107, harmonizing quality benchmarks across ASEAN supply chains. Stakeholders must monitor regulatory divergence between national content mandates and harmonized technical standards as electrification redefines bearing performance specifications.
Market Dynamics
Electric vehicle powertrain electrification is compressing bearing count per vehicle while escalating thermal and rotational precision requirements, forcing ASEAN suppliers to retool forging lines toward ceramic hybrid specifications and integrated hub architectures.
Growth Catalysts
- Thailand's BOI EV Component Localization Incentives:Tax holidays and import duty exemptions for localized bearing forging and assembly operations are redirecting Tier-1 supplier capital toward the Eastern Economic Corridor.
- Ceramic Hybrid Bearing Adoption:Silicon nitride rolling elements are penetrating electrified powertrains to manage thermal loads exceeding 150°C in motor-generator units.
- TKDN Domestic Content Mandates:Indonesia's Ministry of Industry regulations compel foreign bearing manufacturers to establish local forging or heat-treatment facilities to qualify for OEM supply contracts.
Market Restraints
- Alloy Steel Input Cost Volatility:Chrome-molybdenum billet prices fluctuate with nickel and molybdenum exchange rates, compressing margin buffers for mid-scale forging operations in Vietnam and Malaysia.
- Japanese Supplier Concentration:JTEKT, NSK, and NTN control approximately 60% of ASEAN steering and transmission bearing supply, creating procurement bottlenecks during capacity allocation disputes.
- TISI Certification Timeline Friction:Thailand's Industrial Standards Institute fatigue-life testing protocols extend new product qualification cycles by 8-12 months versus ISO 281 baselines.
Strategic Opportunities
- Vietnam's Underpenetrated Commercial Vehicle Segment:Heavy-duty truck assembly expansion in Hai Phong and Binh Duong provinces lacks localized tapered roller bearing capacity, inviting greenfield forging investment.
- Integrated Sensor-Bearing Units:Magnetic encoders embedded in hub assemblies are converging with ADAS wheel-speed monitoring requirements, opening software-hardware bundling revenue streams.
- Singapore's Regional Distribution Hub Function:Free-trade-zone warehousing and ASEAN-wide customs harmonization enable consolidated inventory positioning for just-in-time delivery to Thai and Indonesian assembly plants.
Industry Challenges
- Ceramic Material Processing Skill Scarcity:Silicon nitride powder metallurgy and hot isostatic pressing expertise concentrates in Japanese and German engineering centers, constraining ASEAN workforce development.
- Dual Certification Burden:Suppliers must simultaneously satisfy TISI dimensional tolerances, TKDN local content verification, and OEM-specific PPAP documentation, fragmenting quality management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Automotive Bearings Market |
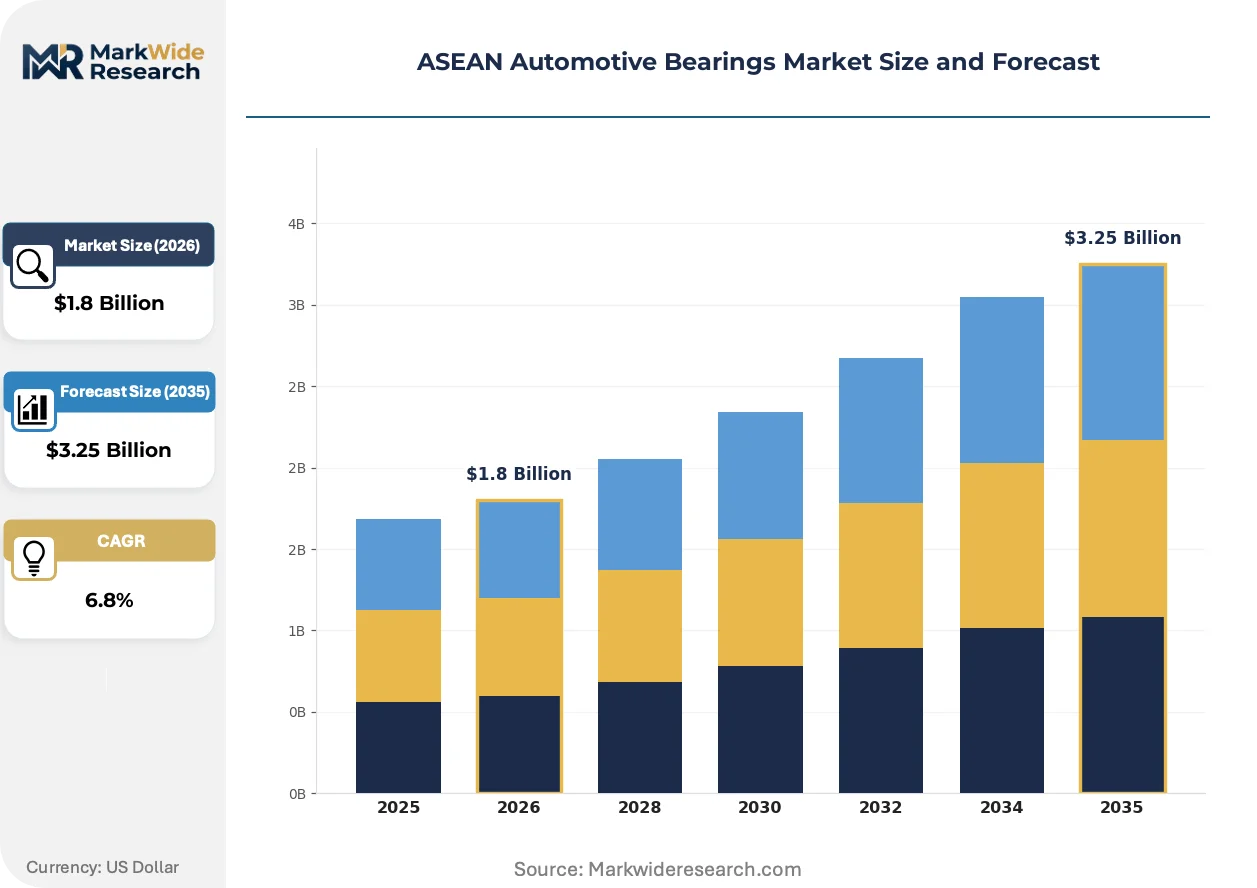
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Tapered Bearings, Spherical Bearings End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Steel Alloys, Ceramic, Polymer, Composite Materials Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Equipment |
| Companies Covered | Minebea Mitsumi Inc., NTN Bearing Corporation, Schaeffler AG, Harbin Bearing Manufacturing Co. Ltd., Myonic GmbH, JTEKT Corporation, NSK Ltd, Timken, AB SKF, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Automotive Bearings Market Strategic Shifts
Bearing architectures across ASEAN are compressing from discrete components toward integrated functional modules, with thermal management and condition-monitoring capabilities becoming baseline specifications rather than premium options.
Hybrid ceramic-steel bearing configurations are unifying thermal resilience and cost efficiency in electrified powertrains. Chinese and Japanese OEMs operating Thai assembly plants specify these for motor support bearings and reduction gear shafts. The technology is unifying what were previously separate high-temperature and standard-load product lines into single platform designs, collapsing supplier SKU portfolios by 30-40%.
Indonesia's TKDN domestic content regulations are tightening enforcement thresholds for bearing subcomponents. Forging operations must now demonstrate 40% local value-add to qualify for automotive sector procurement, pressuring Japanese and Korean suppliers to transfer heat-treatment and grinding capabilities to Batam and Karawang industrial zones. Commercial vehicle axle bearing contracts face the most acute compliance recalibration.
Fleet operators and independent repair networks are consolidating aftermarket purchases through distributor-managed inventory programs. Traditional jobber channels in Bangkok and Jakarta are losing share to integrated supply contracts linking bearing distributors directly with logistics and bus fleet maintenance depots. This concentration is most visible in Thailand's Eastern Seaboard corridor, where Japanese-owned transport fleets negotiate annual hub-unit replacement schedules with single-source distributors.
ASEAN Automotive Bearings Market Segmentation
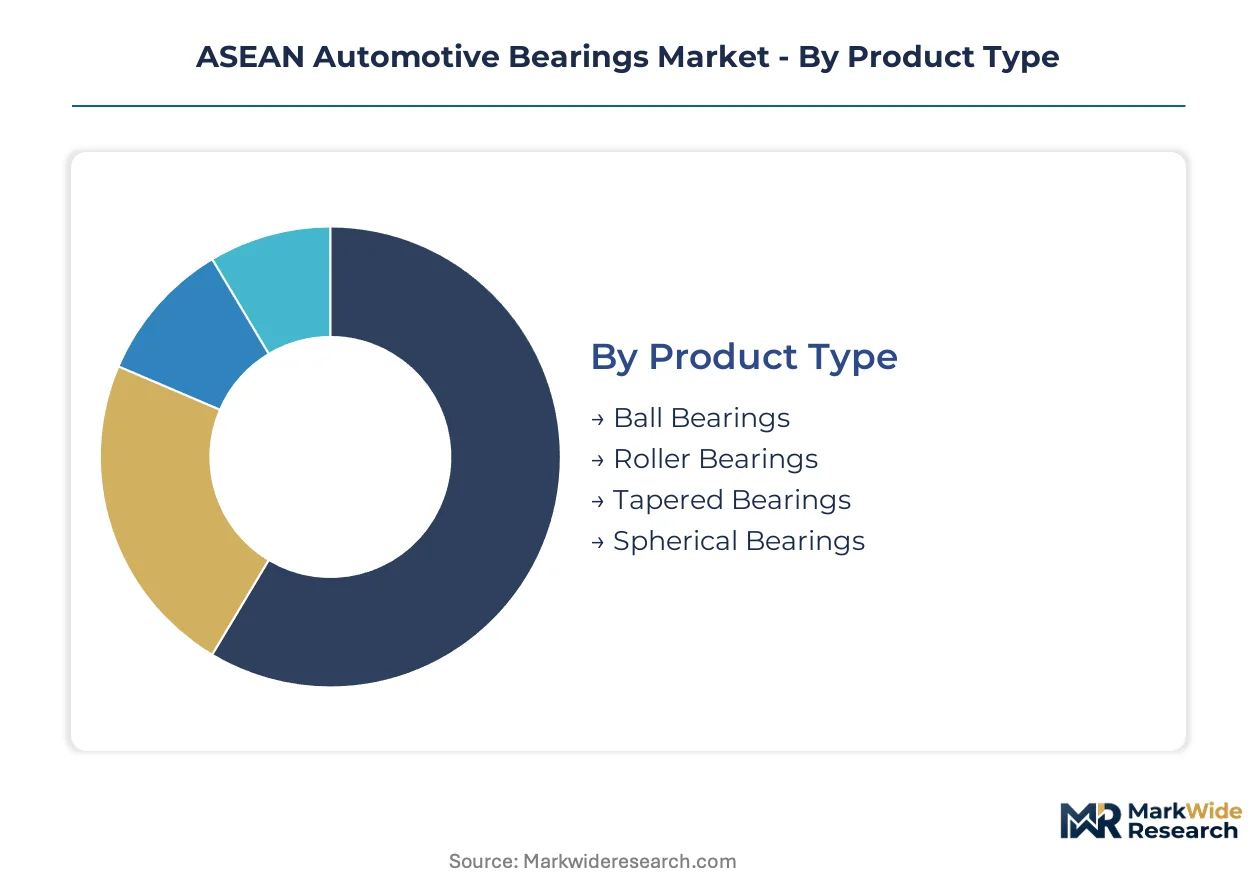
Precision bearing specifications diverge sharply across ASEAN's automotive assembly corridors. Material chemistry, load-bearing geometry, and thermal tolerance requirements reshape procurement patterns as electrified powertrains displace conventional drivetrain architectures.
Product Type:
Rotational load management defines competitive positioning across Thailand's Eastern Economic Corridor forging operations.
- Ball Bearings:Standardized deep-groove and angular-contact configurations dominate ASEAN passenger vehicle transmission and auxiliary systems. Thai assembly plants specify these for motor support brackets in electrified platforms where space envelopes compress.
- Roller Bearings:Cylindrical and needle variants sustain radial loads in commercial vehicle axle and gearbox applications. Indonesian TKDN compliance pressures concentrate investment in Batam-based forging for heavy-duty tapered roller variants serving Isuzu and Hino truck programs.
- Tapered Bearings:Precision-machined raceways manage combined radial-axial loads in wheel hub and differential assemblies.
- Spherical Bearings:Self-aligning geometries accommodate shaft deflection in suspension linkages and steering columns.
Ball bearings lead on scale; ceramic-hybrid roller configurations lead on momentum.
End User:
Procurement authority concentrates with entities controlling design validation and volume commitment.
- OEMs:Japanese and Chinese vehicle assemblers in Thailand's Eastern Seaboard specify bearing performance envelopes directly. Toyota and BYD technical teams validate fatigue life specifications through joint development agreements with NTN and Schaeffler engineering centers.
- Aftermarket Providers:Distributor-managed inventory programs consolidate replacement demand across Bangkok and Jakarta fleet maintenance depots. Annual hub-unit replacement schedules now bypass traditional jobber channels.
- Tier-1 Suppliers:Integrated hub assembly manufacturers source bearings as subcomponents for brake and suspension module integration.
- Vehicle Assemblers:Contract manufacturers without full design authority rely on Tier-1 specification compliance.
OEMs lead on scale; aftermarket consolidation leads on momentum.
Material:
Thermal resilience requirements are compressing traditional steel-centric supply chains.
- Steel Alloys:Chrome-molybdenum and case-hardened grades retain cost advantages in chassis and steering applications. Vietnamese forging operations in Hai Phong depend on imported billet subject to nickel exchange volatility.
- Ceramic:Silicon nitride rolling elements penetrate motor-generator units where operating temperatures exceed 150°C. Japanese powder metallurgy expertise constrains ASEAN localization of hot isostatic pressing capacity.
- Polymer:Self-lubricating formulations reduce maintenance in sealed auxiliary systems.
- Composite Materials:Hybrid ceramic-steel architectures balance thermal performance with forging cost efficiency.
Steel alloys lead on scale; ceramic hybrid formulations lead on momentum.
Application:
Vehicle category determines load spectrum, duty cycle, and regulatory compliance intensity.
- Passenger Vehicles:ASEAN's highest-volume segment demands standardized dimensional envelopes for platform-sharing across Thai, Indonesian, and Malaysian assembly plants. Ball bearing specifications dominate powertrain and HVAC auxiliary systems.
- Commercial Vehicles:Heavy-duty truck expansion in Vietnam's Binh Duong province lacks localized tapered roller capacity. Indonesian axle bearing contracts face acute TKDN recalibration as domestic content thresholds tighten.
- Two-Wheelers:High-volume, low-margin assemblies concentrate in Thai and Vietnamese export-oriented manufacturing.
- Heavy-Duty Equipment:Construction and agricultural machinery specify oversized spherical and cylindrical roller variants.
Passenger vehicles lead on scale; commercial vehicle localization leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese bearing manufacturers established Thailand's automotive component industry during the 1980s assemblers' regional expansion. Thai forging operations now supply precision bearings across ASEAN assembly corridors.
Thailand
Thailand's Board of Investment EV component localization incentives redirect Tier-1 supplier capital toward the Eastern Economic Corridor. The Industrial Standards Institute enforces TISI certification for bearing fatigue life and dimensional tolerance. Japanese and Chinese assemblers expand regional hub capacity across Chonburi and Rayong provinces.
Indonesia
Indonesia's Ministry of Industry implements domestic content requirements through TKDN regulations that compel local bearing assembly or forging operations. Forging operations must demonstrate 40% local value-add to qualify for automotive sector procurement. Commercial vehicle axle bearing contracts face acute compliance recalibration in Batam and Karawang industrial zones.
Vietnam
Vietnam's Ministry of Science and Technology aligns national standards with ISO 492 and ISO 281 through Decree 107. Heavy-duty truck assembly expansion in Hai Phong and Binh Duong provinces lacks localized tapered roller bearing capacity. Vietnamese forging operations depend on imported chrome-molybdenum billet subject to nickel exchange volatility.
Malaysia
Malaysian assembly plants serve as export-oriented production nodes for regional OEM supply chains. Alloy steel input cost volatility compresses margin buffers for mid-scale forging operations. Penang and Selangor industrial corridors concentrate precision machining capacity for Japanese transmission programs.
Singapore
Singapore's free-trade-zone warehousing and ASEAN-wide customs harmonization enable consolidated inventory positioning. Regional distribution hub functions support just-in-time delivery to Thai and Indonesian assembly plants. Jurong Port and Tuas logistics clusters handle transshipment of precision bearing consignments.
ASEAN Automotive Bearings Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification intensity and thermal specification tiers. Japanese and German engineering groups anchor steering-column and precision tapered bearing supply through direct OEM technical collaboration. Three archetypes dominate: integrated hub-assembly specialists, ceramic hybrid technology licensors, and forged-steel commodity suppliers. Capacity expansion and backward integration into heat-treatment operations constitute the dominant competitive moves.
Within the precision-engineered tier, NTN Bearing Corporation and Schaeffler AG occupy positions defined by integrated manufacturing footprints and tropical-condition engineering capabilities. JTEKT Corporation exemplifies the direct-OEM collaboration archetype through steering-system specialization. Minebea Mitsumi Inc. represents the miniature-bearing precision segment serving auxiliary automotive systems.
| Leading Market Players |
|---|
| Minebea Mitsumi Inc. |
| NTN Bearing Corporation |
| Schaeffler AG |
| Harbin Bearing Manufacturing Co. Ltd. |
| Myonic GmbH |
| JTEKT Corporation |
| NSK Ltd |
| Timken |
| AB SKF |
| Others |
Value Chain & Pricing Dynamics
Chrome-molybdenum billet costs cascade from nickel exchange volatility through Vietnamese forging operations into mid-tier bearing price points, compressing margin buffers before reaching Thai and Indonesian OEM procurement desks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs ASEAN bearing procurement, with ceramic hybrid specifications commanding premiums over chrome-molybdenum steel grades based on TISI certification intensity and thermal performance ratings. Price differentiation hinges on ISO 281 fatigue-life validation and TKDN domestic content compliance tiers. Cost compression in standard-grade ball bearings is intensifying because Indonesian and Vietnamese forging operations compete on alloy steel conversion margins. Fleet operators in Thailand's Eastern Seaboard corridor exhibit highest price sensitivity through annual hub-unit replacement tenders, while Japanese OEM technical teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Container freight rates from Japanese and Korean engineering centers to Thai EEC ports directly influence landed cost structures for precision tapered bearing consignments. Supply concentrates in Thailand, Japan, and China, with Thai forging operations serving as the regional hub for ASEAN vehicle assembly programs. Raw material dependencies center on chrome-molybdenum billet, silicon nitride powder, and case-hardened steel grades. Single-source vulnerability persists in hot isostatic pressing capacity for ceramic hybrid formulations, which remains concentrated in Japanese and German engineering centers. Distribution runs through Singapore free-trade-zone warehousing into just-in-time delivery networks serving Chonburi and Rayong assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ASEAN automotive bearings market represents a late-cycle quality story as electrified powertrains displace conventional drivetrains and thermal specification requirements escalate toward ceramic hybrid standards.
For Market Incumbents: Lock in ceramic hybrid technology licensing agreements before Japanese powder metallurgy expertise becomes further concentrated. Defend hub assembly contracts through backward integration into heat-treatment operations in Batam and Karawang industrial zones. Prioritize TISI certification pipeline investment to compress 8-12 month qualification cycles that currently disadvantage new product introductions against ISO 281 baselines. For New Entrants and Emerging Players: Vietnamese commercial vehicle fleet operators represent the most penetrable buyer archetype given localized tapered roller bearing capacity gaps in Hai Phong and Binh Duong provinces. Target integrated sensor-bearing units for ADAS wheel-speed monitoring applications where software-hardware bundling opens margin expansion. Pursue greenfield forging investment with TKDN compliance engineering to qualify for Isuzu and Hino truck axle contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale Vietnamese and Malaysian forging operations face alloy steel input cost volatility without captive billet sourcing. Long-term viability favors precision-engineered tier players with tropical-condition engineering capabilities and direct OEM technical collaboration channels. Monitor ceramic material processing skill scarcity as the inflection indicator for acquisition timing—Japanese and German engineering center concentration signals localization bottlenecks that ASEAN workforce development cannot resolve independently.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Hybrid Technology Licensing | Silicon nitride rolling element expertise unlocks electrified powertrain motor-generator unit contracts. |
| TKDN Compliance Engineering Investment | Batam and Karawang heat-treatment facilities qualify suppliers for Indonesian commercial vehicle axle programs. |
| Integrated Sensor-Bearing Unit Development | Magnetic encoder embedding converges with ADAS wheel-speed monitoring requirements across Thai assembly plants. |
| Singapore Distribution Hub Consolidation | Jurong Port free-trade-zone positioning enables just-in-time inventory management for EEC assembly corridors. |
| TISI Certification Pipeline Acceleration | Thai Industrial Standards Institute fatigue-life testing compression reduces new product qualification cycle disadvantage. |
Study Parameters
Multiple input streams — primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket distribution heads; secondary validation through vehicle production databases, IHS Markit registration data, and customs/trade records; and technical standard documentation from TISI, TKDN, and ISO 281 frameworks — were reconciled through bottom-up and top-down triangulation to construct market size and growth estimates.
Historical production volume trajectories were cross-referenced against panel input from forging operation managers and ceramic material processing specialists to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from slope analysis of fitted trend lines applied to validated baseline data points, with specific weighting for EV powertrain penetration rates and TKDN enforcement threshold escalations.
Inputs from Thai Board of Investment disclosure filings and Indonesian Ministry of Industry regulatory circulars were available through the study window; gaps in real-time alloy steel spot pricing and ceramic powder metallurgy capacity utilization introduce uncertainty bands around cost structure projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Timing Gear Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Brake Pad Market
Automotive Parts
Automotive Suspension Control Arms Market