
 Global Hybrid and Full Electric Marine Propulsion Market | 2026-2036
Global Hybrid and Full Electric Marine Propulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid and Full Electric Marine Propulsion Market Intelligence
IMO Tier III certification for nitrogen oxide emissions is collapsing the addressable market for pure diesel propulsion suppliers. Wärtsilä leverages its dual-fuel engine portfolio to bridge hybrid architectures across commercial vessel classes. ABB sustains technology leadership through its Azipod electric propulsion systems deployed in ice-class and cruise segments. Rolls-Royce competes via its Power Systems division, which specializes in integrated hybrid packages for naval and offshore applications.
Hybrid and full electric marine propulsion encompasses drivetrain configurations where electric motors—powered by batteries, fuel cells, or generator sets—deliver thrust through fixed or azimuthing propulsors, with power ratings spanning from under 500 kW harbor tugs to above 5000 kW cruise liners. The primary industrial purpose centers on reducing fuel consumption, enabling zero-emission operation in regulated zones, and improving vessel maneuverability through distributed power architectures. Full electric and battery-only configurations now capture the fastest expansion within propulsion type segmentation, driven by shore-charging infrastructure maturation in coastal routes. Diesel-electric hybrid systems retain dominant share across cargo ships and research vessels where endurance requirements exceed pure battery feasibility. Margin pools concentrate in the 2000-5000 kW power rating band, where system complexity and integration engineering create vendor stickiness.
The International Maritime Organization enforces carbon intensity indicators and energy efficiency design indices that mandate emission reductions across existing fleets, directly accelerating retrofit demand for hybrid systems. EPA marine engine standards in the United States and EU MRV monitoring requirements collectively reshape product certification pathways, with EMA and national flag administrations verifying compliance at port state control. China MIIT promotes domestic electric propulsion component manufacturing through dual carbon policy implementation timelines. Stakeholders must monitor regulatory divergence between IMO global frameworks and regional enforcement intensity, as compliance cost asymmetries will determine which vessel operators accelerate full electrification versus incremental hybrid adoption.
Market Dynamics
IMO carbon intensity indicators are compressing vessel operator decision windows, forcing premature retirement of conventional diesel architectures and redirecting capex toward hybrid-electric retrofits and newbuild electrification programs.
Growth Catalysts
- EU MRV monitoring requirements:Mandatory emissions reporting for vessels above 5000 gross tonnage operating in European waters is accelerating data transparency and investment in measurable efficiency upgrades.
- Shore-charging infrastructure maturation:Port authorities in Norway, Denmark, and Sweden are deploying high-capacity grid connections that enable pure battery operation on coastal ferry routes.
- Harbor tug electrification:Municipal port authorities are mandating zero-emission operation in designated zones, creating immediate demand for sub-500 kW electric propulsion packages.
Market Restraints
- Battery cell supply concentration:Cathode material processing and cell manufacturing capacity clusters heavily in China, exposing European and North American system integrators to supply chain disruption and input cost volatility.
- Energy density limitations:Lithium-ion cell chemistry constraints restrict pure electric range for cargo vessels and research ships requiring transoceanic endurance.
- Port grid capacity bottlenecks:Aging electrical infrastructure at secondary ports limits simultaneous multi-vessel fast-charging, constraining route electrification feasibility.
Strategic Opportunities
- Japan coastal shipping electrification:METI funding programs for domestic vessel efficiency create entry points for integrated hybrid systems in the underpenetrated Japanese archipelago market.
- Fuel cell-battery hybrid convergence:Proton exchange membrane fuel cells paired with lithium-ion buffers enable extended range for medium-distance cargo routes without shore charging dependency.
- California Harbor Craft Regulation:The state's phased emission standards for commercial harbor vessels mandate tiered compliance deadlines through 2032, generating predictable retrofit demand cycles.
Industry Challenges
- Marine electrical engineering talent scarcity:Shortages of power electronics specialists and high-voltage system integrators are extending project timelines and inflating labor costs for shipyard electrification programs.
- Type approval certification complexity:Flag administration variability in interpreting IEC 60092 electrical installation standards creates uncertainty in cross-border vessel registration and resale liquidity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid and Full Electric Marine Propulsion Market |
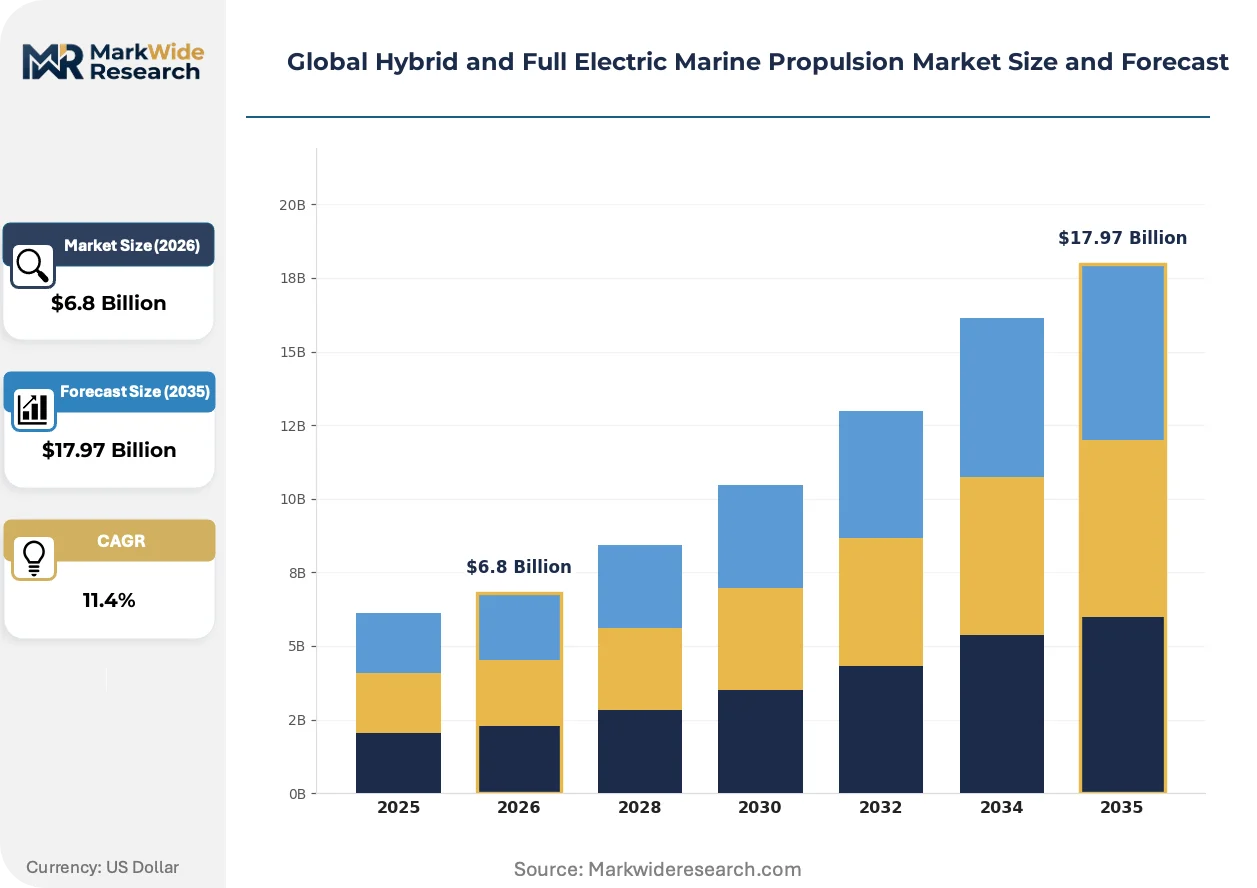
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Hybrid Drive, Full Electric, Diesel-Electric, Fuel Cell, Battery Only Vessel Application: Cruise Ships, Ferries, Research Vessels, Navy Patrol Boats, Cargo Ships Power Rating: Under 500 kW, 500-2000 kW, 2000-5000 kW, Above 5000 kW End User: Shipbuilders, Offshore Operators, Marine Fleet Owners, Specialized Repair Yards |
| Companies Covered | Wärtsilä, ABB, Siemens AG, MAN Energy Solutions, Caterpillar, General Electric, BAE Systems, Rolls-Royce, Cummins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid and Full Electric Marine Propulsion Market Strategic Shifts & Innovations
Electrification architectures are fragmenting into specialized configurations optimized for distinct operational profiles, with technology choices diverging sharply between short-route coastal operators and long-haul cargo carriers.
Modular battery pack architectures are decomposing traditional monolithic power system designs. Ferry operators in Scandinavia are adopting swappable containerized battery units that enable route-specific energy capacity configuration. This modularity is decomposing vendor lock-in patterns and compressing upgrade cycle timelines from decades to individual charter periods.
EPA marine engine standards are tightening nitrogen oxide and particulate matter thresholds for Category 3 engines operating in US waters. Engine manufacturers must recertify existing platforms or exit commercial segments. The offshore supply vessel segment is responding by accelerating diesel-electric hybrid retrofits ahead of 2027 compliance deadlines.
Charter rate structures are incorporating emissions performance clauses that tie vessel hire premiums to verified carbon intensity metrics. Cruise line procurement departments are rewriting tender specifications to prioritize lifetime CO2 performance over upfront capital cost. This behavioral shift is most visible in Northern European contracting, where public sector ferry procurement mandates now require 30-year total cost of ownership modeling.
Global Hybrid and Full Electric Marine Propulsion Market Segmentation
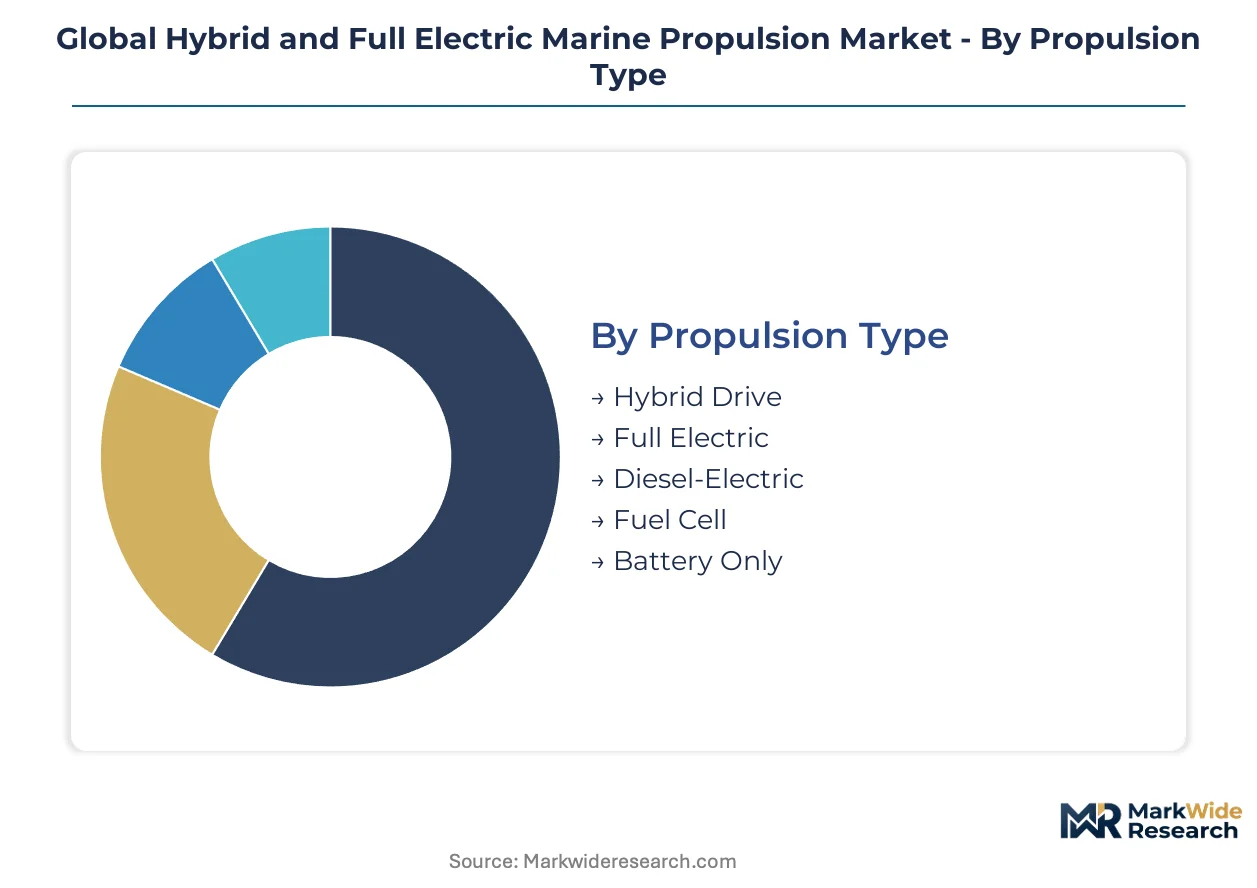
Segmentation in marine propulsion reveals how power architecture choices map to operational economics and regulatory exposure. Vessel operators select configurations based on route distance, port infrastructure availability, and flag state compliance timelines.
Propulsion Type:
System integrators route hybrid architectures through shipyard newbuild contracts, while full electric packages flow via retrofit specialists and ferry operator direct procurement.
- Hybrid Drive:Combines diesel generator sets with electric motors and battery buffers, enabling load optimization and zero-emission harbor maneuvering. Demand concentrates in offshore supply vessels operating under EPA marine engine standards, where operators must meet Tier III nitrogen oxide thresholds without sacrificing transoceanic range.
- Full Electric:Eliminates onboard combustion entirely, relying on shore charging and battery banks for propulsion and hotel loads. Norwegian ferry operators dominate procurement, leveraging high-capacity grid connections at terminals along coastal routes to achieve complete diesel displacement.
- Diesel-Electric:Traditional generator-motor architecture without battery storage, common in icebreakers and large cargo vessels where continuous power demand favors thermal efficiency over cycling.
- Fuel Cell:Proton exchange membrane systems paired with hydrogen storage, emerging for medium-distance routes where shore charging gaps exceed battery feasibility.
- Battery Only:Pure lithium-ion architectures for harbor tugs and short-haul ferries with predictable duty cycles and guaranteed berth access.
By volume, Diesel-Electric leads. By growth pace, Full Electric is gaining share fastest.
Vessel Application:
Margin concentration varies sharply across vessel classes, with passenger carriers prioritizing emission branding and cargo operators focusing on fuel cost amortization.
- Cruise Ships:Azipod azimuthing thrusters and integrated hybrid packages dominate newbuild specifications, driven by port city emission regulations in Barcelona, Venice, and Juneau that restrict conventional diesel operation.
- Ferries:Coastal operators in Denmark and Sweden are standardizing battery-electric or hybrid configurations, with procurement specifications now mandating 30-year total cost of ownership models.
- Research Vessels:Diesel-electric hybrids prevail due to endurance requirements for extended oceanographic missions without shore support.
- Navy Patrol Boats:Integrated electric propulsion enables acoustic signature reduction and weapons system power allocation, with procurement channeled through defense ministry shipyard partnerships.
- Cargo Ships:Slow-steaming optimization and auxiliary power electrification dominate, with full battery architectures limited to short-sea shipping in the Baltic and North Sea.
Cargo Ships generate the largest addressable installed base. Ferries are climbing the fastest on electrification mandates.
Power Rating:
Engineering complexity and vendor stickiness peak in the mid-range band, where system integration demands exceed commodity component supply.
- Under 500 kW:Harbor tugs and pilot boats drive procurement, with California Harbor Craft Regulation mandating tiered compliance through 2032 for vessels operating in Los Angeles, Long Beach, and Oakland.
- 500-2000 kW:Coastal ferries and offshore support vessels concentrate demand, requiring modular battery architectures that enable route-specific energy configuration.
- 2000-5000 kW:Cruise ships and large research vessels dominate, where margin pools concentrate due to integration engineering complexity and flag administration certification requirements.
- Above 5000 kW:Limited to specialized ice-class vessels and naval surface combatants, with procurement channeled through sovereign shipyard programs.
The 2000-5000 kW band commands premium pricing. Under 500 kW is expanding most quickly on port decarbonization mandates.
End User:
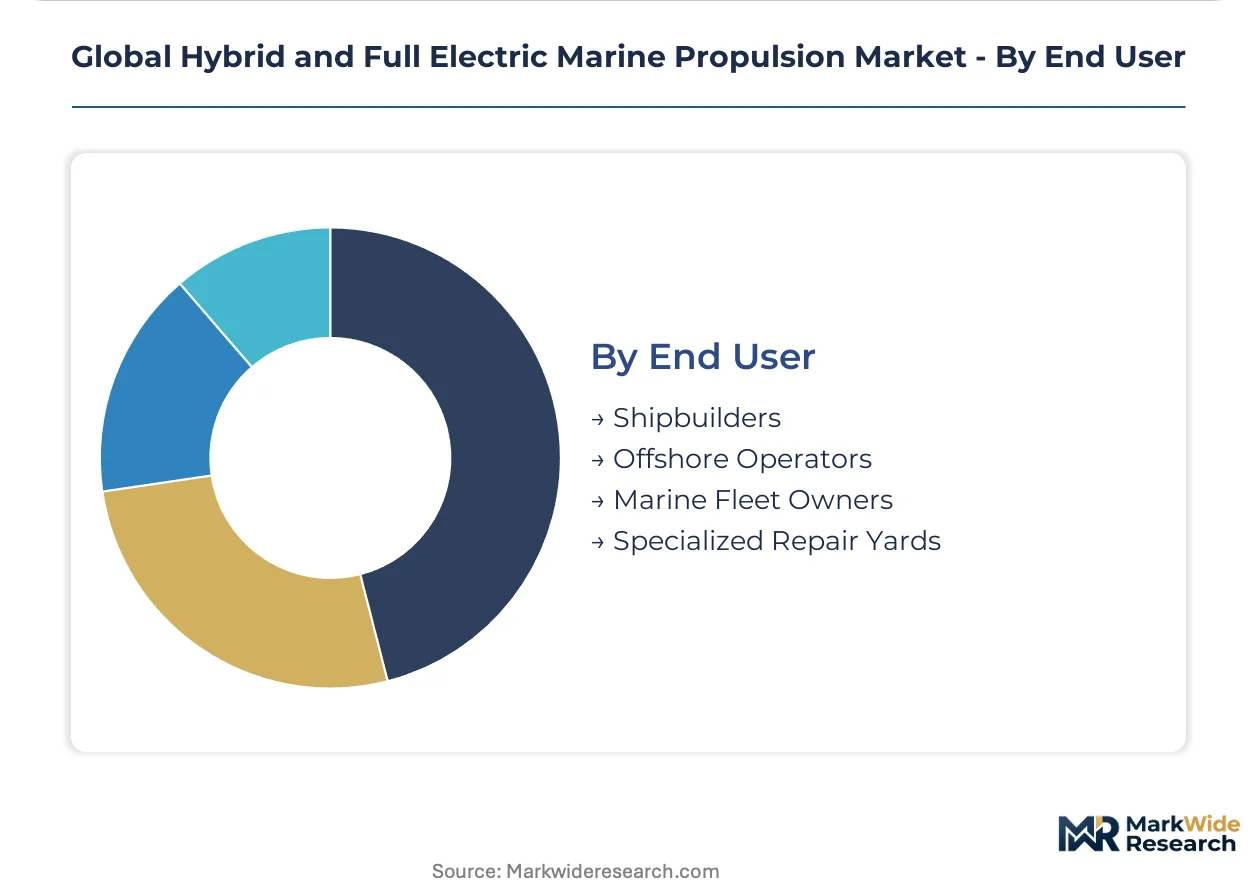
Procurement authority fragmentation shapes sales channel strategy, with shipbuilders controlling newbuild specifications and fleet owners driving retrofit demand.
- Shipbuilders:Korean and Chinese yards specify integrated propulsion packages for export vessels, with EU MRV compliance requirements influencing design choices for European-bound tonnage.
- Offshore Operators:North Sea oil service companies retrofit diesel-electric hybrids ahead of 2027 EPA compliance deadlines, procuring through specialized marine engineering contractors.
- Marine Fleet Owners:Scandinavian ferry operators deploy direct procurement teams to negotiate battery system supply agreements, bypassing traditional shipyard intermediaries.
- Specialized Repair Yards:German and Singaporean facilities capture retrofit demand for existing fleets, with IMO carbon intensity indicators compressing owner decision windows.
Shipbuilders handle the greatest contract volume. Marine Fleet Owners are moving fastest toward direct supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Norway, China, and the United States account for the majority of hybrid and full electric marine propulsion procurement volumes. Each market exhibits distinct regulatory drivers and infrastructure maturity profiles that shape technology adoption trajectories.
Norway
Coastal ferry electrification dominates procurement activity, with operators replacing diesel fleets on short-hop routes. The Norwegian Maritime Authority enforces zero-emission mandates in designated heritage fjords by 2026. Bergen and Stavanger terminals now host Europe's densest shore-charging cluster, supporting battery-electric vessel rotation schedules.
China
Domestic shipyards integrate electric propulsion for inland waterway vessels and port service craft. MIIT's dual carbon policy timelines accelerate component localization requirements. The Yangtze River Delta anchors manufacturing concentration, with Shanghai and Ningbo facilities producing battery packs and power electronics for regional vessel programs.
United States
Harbor craft electrification drives demand in California, Washington, and New York port complexes. EPA marine engine standards mandate Tier III nitrogen oxide compliance for Category 3 engines by 2027. Los Angeles and Long Beach port authorities are co-funding shore-power infrastructure to enable tug and pilot boat battery operation.
Germany
Research vessel and offshore support fleet retrofits concentrate in North Sea and Baltic ports. The KBA enforces EU MRV monitoring compliance for vessels above 5000 gross tonnage calling at Hamburg and Bremen. German shipyards specialize in diesel-electric hybrid integration for ice-class and heavy-lift applications.
Japan
Coastal shipping electrification lags Northern Europe but accelerates under METI efficiency funding programs. Domestic archipelago routes favor fuel cell-battery hybrid architectures for medium-distance endurance. Nagoya and Osaka shipyards are developing integrated systems for regional ferry and cargo operators.
Global Hybrid and Full Electric Marine Propulsion Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with marine heritage divisions, supplemented by specialized power electronics firms and emerging battery system integrators. Consolidation pressure intensifies as vessel operators demand single-source accountability for hybrid architecture performance. Two strategic archetypes dominate: integrated propulsion packagers combining engines, generators, and control systems; and component specialists supplying batteries, inverters, or azimuthing thrusters to third-party integrators. Competitive moves center on shipyard partnership exclusivity and shore-charging infrastructure consortia formation.
Within the integrated packager tier, Wärtsilä and ABB occupy anchor positions representing Nordic and Swiss-German engineering traditions respectively. Rolls-Royce exemplifies the defense-industrial crossover archetype, leveraging naval electric propulsion expertise for commercial offshore applications. These three conglomerates sit within a vendor landscape where technology licensing and joint venture structures predominate over pure product competition.
| Leading Market Players |
|---|
| Wärtsilä |
| ABB |
| Siemens AG |
| MAN Energy Solutions |
| Caterpillar |
| General Electric |
| BAE Systems |
| Rolls-Royce |
| Cummins |
| Others |
Cost & Logistics Intelligence
Twenty-four-month battery cell procurement lead times concentrate pricing power with cathode material processors in China, compressing margin buffers for European system integrators while amplifying cost pass-through to ferry operators locked into fixed-price newbuild contracts.
Pricing Analysis
Cost-plus contracts indexed to lithium carbonate and nickel sulfate spot markets dominate battery pack procurement, with premium tiers commanding spreads for IEC 62619-certified marine-grade cells versus standard industrial formats. Price differentiation separates IMO-certified integrated systems from uncertified component bundles, with Scandinavian ferry operators least sensitive due to total cost of ownership mandates while Asian shipyards face acute pressure from domestic content requirements. Pricing pressure intensifies as Chinese cell manufacturers absorb cathode cost volatility through state-backed inventory financing.
Supply Chain Analysis
Strategic stockpiling of power electronics and high-voltage cable assemblies characterizes tier-one integrator behavior, contrasting with just-in-timelithium-ion cell flows from South Korean and Japanese producers. Geographic concentration centers on China for cathode processing, South Korea for cell manufacturing, and Germany for inverter assembly. Raw material dependencies span cobalt from the Democratic Republic of Congo, lithium from Australia and Chile, and rare earth elements for permanent magnet motors. Single-source vulnerability in silicon carbide wafer supply creates chokepoint exposure. Distribution runs through sovereign shipyard programs and specialized marine engineering contractors rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against hydrogen fuel cell architectures, which threaten to displace battery-electric systems on medium-distance coastal routes as electrolyzer costs decline and bunkering infrastructure matures.
For Market Incumbents: Shield core positions by securing backward integration into power electronics manufacturing and locking shipyard exclusivity agreements for Azipod-class azimuthing thrusters. Accelerate certification investment for IEC 60092-507 high-voltage standards to raise regulatory barriers against modular battery entrants. The priority lever rests on controlling shore-charging infrastructure consortia in Norwegian and Danish ports. For New Entrants and Emerging Players: Anchor in Japanese coastal shipping electrification, where METI funding programs create white-space demand for fuel cell-battery hybrid architectures absent dominant incumbents. Target German specialized repair yards serving North Sea offshore operators facing compressed IMO compliance windows. The most penetrable segment sits in sub-500 kW harbor tug retrofits under California Harbor Craft Regulation mandates, with go-to-market through municipal port authority procurement channels. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory capture play because IMO carbon intensity indicators and EU MRV enforcement create durable demand visibility independent of fuel price cycles. Acquisition targets should emphasize power electronics specialists with marine certification track records and existing shipyard relationships. The signal to watch is flag administration harmonization on electrical installation standards, which would unlock cross-border resale liquidity and consolidate vendor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Shipyard Partnership Exclusivity | Locks out competitors from Norwegian ferry newbuild specifications through multi-vessel framework agreements. |
| Shore-Charging Infrastructure Consortium | Captures recurring revenue streams from port authority electrification mandates in Scandinavian terminals. |
| Power Electronics Backward Integration | Reduces dependency on German and Japanese inverter suppliers while compressing integration timelines. |
| Fuel Cell-Battery Hybrid Development | Positions systems for Japanese archipelago routes where shore charging gaps exceed pure battery feasibility. |
| IEC 60092 Certification Investment | Creates regulatory moats against uncertified competitors in 2000-5000 kW cruise and research vessel segments. |
Research Approach
Cross-validation between primary interviews with shipyard procurement directors, ferry operator fleet managers, and marine electrical engineering contractors anchors the qualitative findings against secondary validation from IMO regulatory filings, EU MRV emissions databases, and national maritime authority certification records. Bottom-up vessel order book analysis triangulates with top-down market sizing across propulsion type, power rating, and vessel application segments.
Sensitivity analysis on battery cell cost trajectories and shore-charging infrastructure deployment rates frames the forecast envelope across the projection horizon. Segmentation modeling incorporates propulsion architecture, power rating bands, vessel application classes, and regional regulatory cluster intensity. CAGRs derive from installed base turnover analysis and newbuild specification trend extrapolation, with marine electrical engineering labor scarcity and flag administration certification timelines as key industry-specific inputs.
Material uncertainties — cathode supply disruption, port grid capacity bottlenecks, and regulatory divergence between IMO global frameworks and regional enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions on technology cost curves and compliance timeline adherence without guarantee. Revision becomes warranted when hydrogen fuel cell system costs cross competitive thresholds against battery-electric architectures on medium-distance routes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Reciprocating Engine Market
Marine Vehicles
Marine Fuel Injection System Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Marine Trailers Market
Marine Vehicles
Yacht Market
Marine Vehicles
Small Boats Market
Marine Vehicles
Global Luxury Boat Market