
 Global Connected, Autonomous, Shared, and Electric (CASE) Market | 2026-2036
Global Connected, Autonomous, Shared, and Electric (CASE) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Connected, Autonomous, Shared, and Electric (CASE) Market Intelligence
The emergence of new buyer categories, including mobility providers and logistics companies, is recalibrating the traditional automotive value chain. This shift challenges established automakers like Volkswagen Group, which now competes on software and services. Meanwhile, technology specialists such as Robert Bosch GmbH leverage deep expertise in sensors and control units. Tesla differentiates through its integrated software stack and direct-to-consumer model, setting a high bar for legacy manufacturers.
Connected, Autonomous, Shared, and Electric (CASE) represents the convergence of four automotive megatrends enabled by advanced digital technologies. This includes the integration of V2X communication protocols, which allow vehicles to exchange data with their surroundings for enhanced safety and traffic efficiency. The market's technology segment shows rapid advancement in LiDAR sensors and AI-based navigation. Among service models, ride-hailing and subscription services represent the fastest-growing areas, driven by urban mobility demands and fleet management needs from logistics companies.
Regulatory frameworks are critical in shaping market development, with standards like the EU's GDPR influencing data privacy in connected cars. In the US, the NHTSA sets guidelines for autonomous vehicle testing, while China's MIIT directs policies for intelligent connected vehicles. These disparate regulations create a complex compliance landscape for global OEMs. The key strategic decision for stakeholders now centers on developing platform architectures that can adapt to divergent regional standards and consumer preferences.
Market Dynamics
The convergence of automotive and technology industries, driven by software-defined vehicle architectures, is the central force shaping the market. This shift is accelerated by strong regulatory pressures, including the EU Green Deal's emissions targets and China's strategic industrial policies.
Growth Catalysts
- Policy Mandates:The EU Green Deal's emissions targets and China's NEV incentives accelerate the industry's transition to electric vehicle platforms.
- Technology Maturation:Advancements in LiDAR sensors and AI algorithms enable the deployment of more sophisticated and reliable autonomous driving features.
- Urban Mobility Demand:Fleet management needs of ride-hailing and logistics companies in dense urban areas drive adoption of connected and shared technologies.
Market Restraints
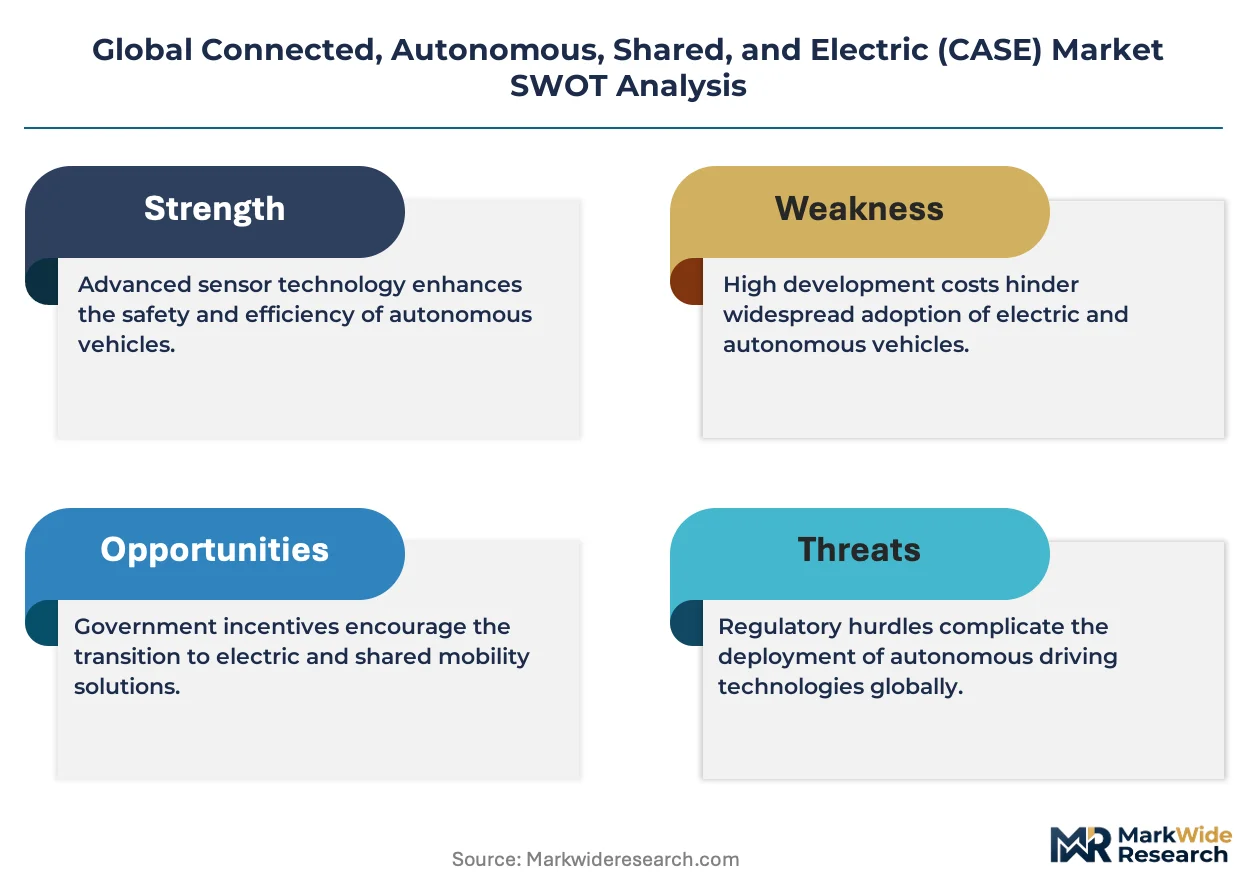
- High Development Costs:The validation of autonomous systems requires immense R&D investment and testing, creating high barriers to entry for many firms.
- Regulatory Fragmentation:Divergent standards for autonomous vehicles from the US NHTSA and China's MIIT complicate global development and delay deployment.
- Semiconductor Supply Constraints:A persistent shortage of automotive-grade microcontrollers directly limits vehicle production and the rollout of new electronic features.
Strategic Opportunities
- Subscription Services:Automakers can create recurring revenue streams by selling software-based features and upgrades to customers via over-the-air updates.
- V2X Infrastructure:Smart city projects, particularly in Europe and Asia, offer opportunities to build and monetize vehicle-to-everything communication network services.
- Logistics Fleet Electrification:The last-mile delivery market is a prime target for specialized electric vans and trucks integrated with fleet management platforms.
Industry Challenges
- Cybersecurity Vulnerabilities:Protecting connected vehicles from remote attacks requires continuous development of sophisticated, multi-layered security protocols against evolving threats.
- Data Privacy Compliance:Navigating disparate regulations like the EU's GDPR when handling vehicle and driver data presents a major legal and operational hurdle.
- Software Talent Scarcity:The automotive industry faces a significant shortage of software engineers and AI specialists, hindering progress on advanced CASE features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Connected, Autonomous, Shared, and Electric (CASE) Market |
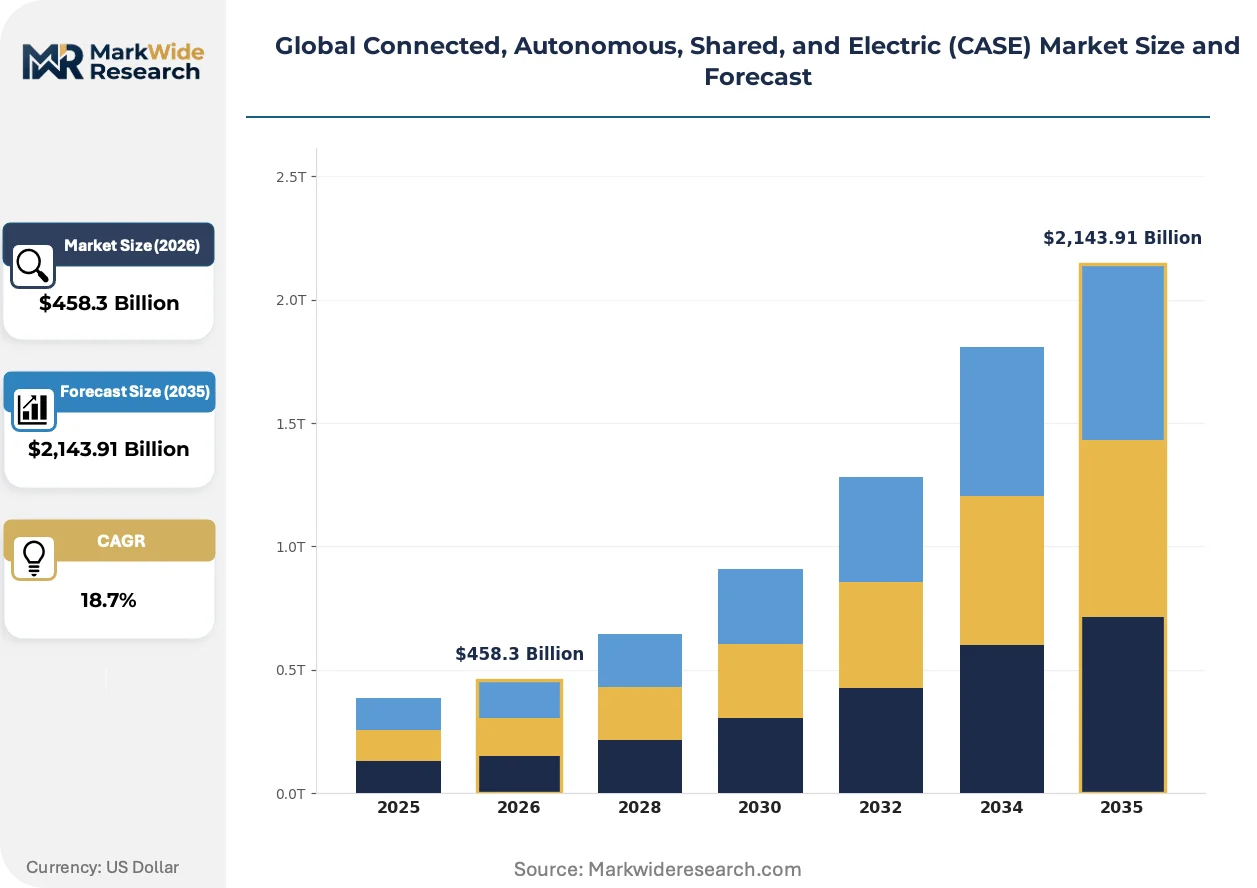
| Market Size in 2026 | $458.3 Billion |
| Market Size in 2035 | $2,143.91 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Trucks, Two-Wheelers, Electric Buses Technology: V2X Communication, LiDAR Sensors, AI-Based Navigation, Battery Management Systems, Telematics Service Model: Ride-Hailing, Car Sharing, Subscription Services, Fractional Ownership, Fleet Management End User: OEMs, Mobility Providers, Logistics Companies, Public Transportation Authorities, Vehicle Leasing Firms |
| Companies Covered | Tesla, BMW Group, Ford Motor Company, General Motors, Volkswagen Group, Toyota Motor Corporation, Robert Bosch GmbH, Continental AG, BYD Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Connected, Autonomous, Shared, and Electric (CASE) Market Strategic Shifts & Innovations
Software is fundamentally redefining vehicle value, shifting focus from mechanical hardware to upgradable digital platforms. This transformation creates new revenue models based on services and challenges traditional automotive engineering and business structures.
Centralized compute architectures are becoming standard in next-generation EVs. Automakers and Tier-1 suppliers are adopting powerful system-on-chip (SoC) solutions to manage vehicle functions. This approach is unifying dozens of previously separate electronic control units into a cohesive, software-defined platform that can be updated and enhanced remotely over its lifetime.
The European Union's updated General Safety Regulation (GSR) mandates a suite of advanced driver-assistance systems in all new vehicles. This policy compels the standardization of technologies like intelligent speed assistance and lane-keeping aids across the market. Mass-market vehicle segments are most affected, requiring significant hardware and software integration to achieve compliance.
A clear preference for vehicle usership over ownership is emerging, especially in urban centers. This behavioral change disrupts the conventional dealer-centric sales model in favor of direct-to-consumer channels, subscription services, and car-sharing platforms. The trend is most visible in major North American and European cities with high population density.
Global Connected, Autonomous, Shared, and Electric (CASE) Market Segmentation
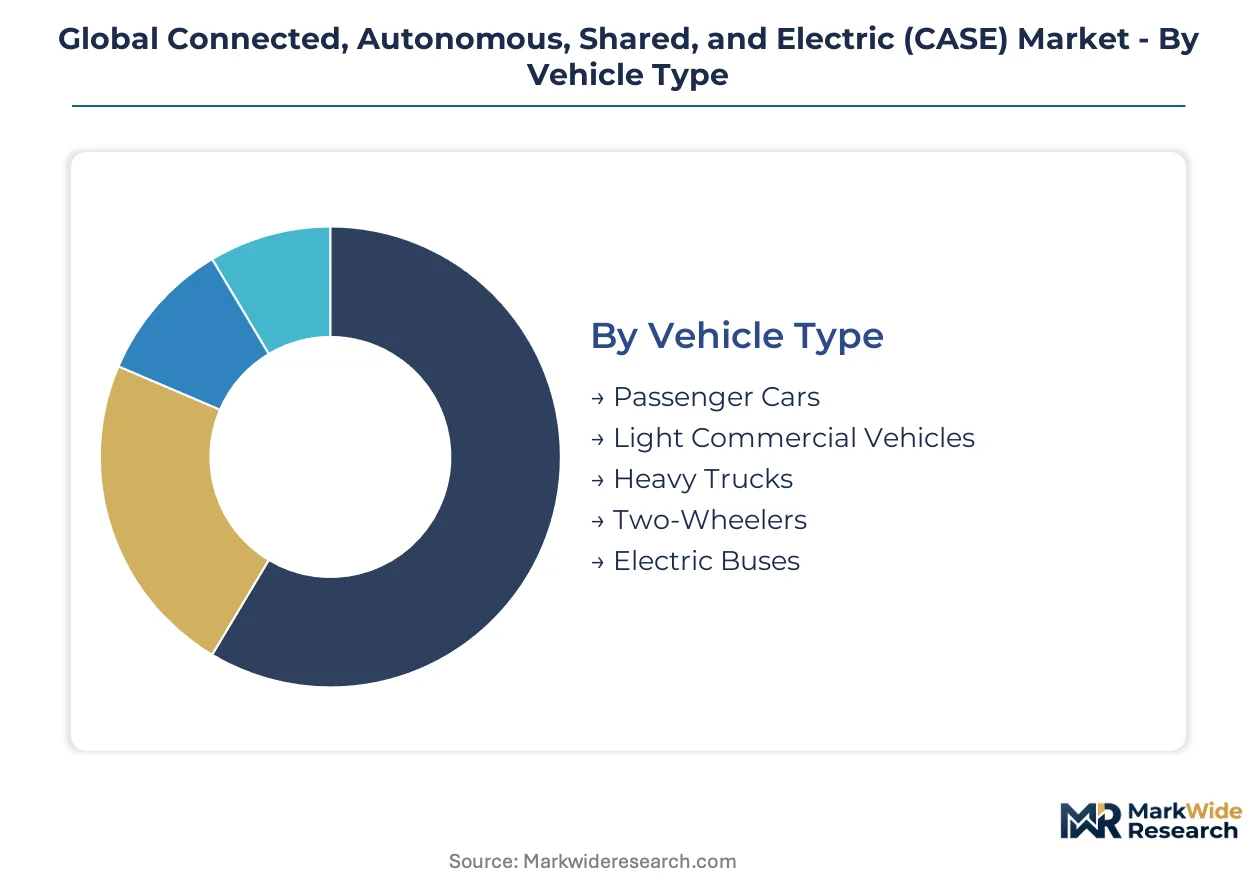
Understanding the multifaceted Global Connected, Autonomous, Shared, and Electric (CASE) market requires a granular segmentation analysis. This breakdown clarifies distinct value propositions, investment pathways, and the diverse regulatory landscapes influencing product development and service deployment across various segments.
Vehicle Type:
Vehicle type segmentation highlights varying certification burdens and safety standards required for market entry across different platforms.
- Passenger Cars:These vehicles integrate advanced driver-assistance systems and connectivity features, often requiring certifications like the EU's General Safety Regulation. Demand concentrates in China and European Union cities, driven by consumer preference for personal mobility and stringent emissions targets.
- Heavy Trucks:These robust vehicles are designed for long-haul logistics, incorporating advanced autonomous driving capabilities that require specific national road safety approvals. Demand is strong in North America and Europe, where logistics companies seek to optimize supply chains and reduce operational costs.
- Light Commercial Vehicles:These vehicles serve last-mile delivery and urban logistics, increasingly adopting electric powertrains.
- Two-Wheelers:This segment includes electric motorcycles and scooters, gaining traction in dense urban environments.
- Electric Buses:Public transportation authorities deploy these vehicles to meet urban mobility demands and air quality regulations.
Leading the category by volume: Passenger Cars. Growing fastest: Electric Buses.
Technology:
Technology segmentation often reflects varying development costs and intellectual property investments required for market leadership.
- LiDAR Sensors:These optical remote sensing technologies measure distance by illuminating the target with laser light, crucial for precise environmental mapping. Adoption is accelerating in autonomous vehicle development across Germany and the United States, driven by the need for high-fidelity perception in complex driving scenarios.
- AI-Based Navigation:These systems leverage machine learning algorithms to process sensor data, enabling real-time path planning and decision-making for autonomous vehicles. Development is concentrated in technology hubs like California and Beijing, fueled by significant investment in artificial intelligence research and development.
- V2X Communication:This technology allows vehicles to exchange data, enhancing safety and traffic flow in smart city initiatives.
- Battery Management Systems:These electronic control units optimize battery performance and lifespan, critical for EV efficiency.
- Telematics:This segment integrates telecommunications and informatics to track vehicle location and behavior, supporting fleet management.
LiDAR Sensors command significant market value, while AI-Based Navigation is experiencing the steepest expansion trajectory.
Service Model:
Service model segmentation highlights distinct customer acquisition strategies and operational complexities for mobility providers.
- Ride-Hailing:This service model connects passengers with drivers via digital platforms, offering on-demand transportation solutions in urban areas. Demand is highest in major metropolitan centers like New York City and Shanghai, driven by convenience and reduced car ownership preferences.
- Fleet Management:These comprehensive solutions integrate telematics, predictive maintenance, and route optimization to enhance the efficiency of commercial vehicle operations. Logistics companies and last-mile delivery providers in Europe and Asia are rapidly adopting these systems to reduce costs and improve service reliability.
- Car Sharing:This model provides short-term vehicle access, appealing to urban residents seeking flexible mobility.
- Subscription Services:Automakers offer vehicle access for a monthly fee, providing a flexible alternative to traditional leasing.
- Fractional Ownership:This niche model allows multiple individuals to co-own a vehicle, sharing costs and usage.
Ride-Hailing services generate substantial revenue, with Subscription Services gaining share fastest.
End User:
End user segmentation reveals varying margin structures and purchasing power across the CASE value chain.
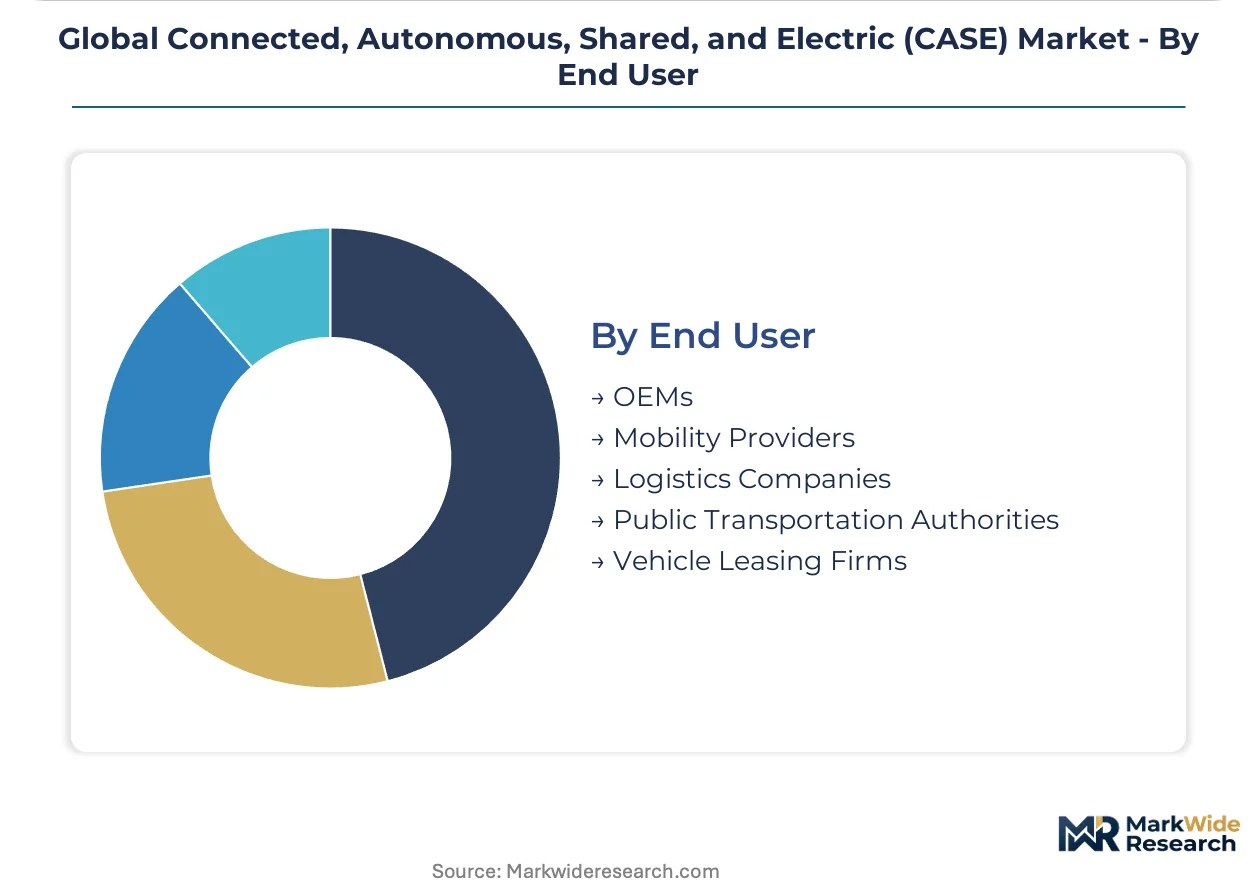
- OEMs:Original Equipment Manufacturers integrate CASE technologies directly into new vehicles, setting industry standards for safety and performance. Investment in CASE features is pervasive across global automotive manufacturers, driven by competitive pressure and evolving consumer expectations in Japan and South Korea.
- Mobility Providers:These companies operate large fleets of connected and autonomous vehicles, delivering services like ride-hailing and car-sharing to urban populations. Major cities in the United States and India exhibit high demand for these services, fueled by urbanization and the need for efficient public transport alternatives.
- Logistics Companies:These firms adopt CASE technologies to electrify delivery fleets and optimize routes.
- Public Transportation Authorities:Government bodies deploy electric buses and smart traffic systems to improve urban mobility.
- Vehicle Leasing Firms:These companies offer CASE-enabled vehicles, catering to businesses and individuals seeking flexible access.
OEMs represent the foundational end-user base, while Mobility Providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for CASE technologies is most evident in China, where government incentives create a favorable environment for adoption. This market expansion reflects varying regional priorities and regulatory landscapes. Each major region contributes uniquely to the overall CASE ecosystem.
China
Demand for electric vehicles and intelligent connected vehicles is high due to rapid urbanization. China's MIIT directs policies for intelligent connected vehicles, supporting domestic development. In Beijing, significant investment in artificial intelligence research drives advancements in AI-based navigation systems.
Germany
The country's robust automotive industry drives demand for advanced autonomous driving features and integrated software. The EU Green Deal's emissions targets accelerate the transition to electric vehicle platforms across the nation. Stuttgart's automotive cluster focuses on developing sophisticated LiDAR sensors and centralized compute architectures for next-generation vehicles.
United States
Consumer preference for advanced driver-assistance systems and fleet management solutions fuels market growth. The NHTSA sets guidelines for autonomous vehicle testing, shaping deployment strategies for OEMs. California's technology hubs, particularly Silicon Valley, lead in AI-based navigation development and software-defined vehicle architectures.
Japan
OEMs in Japan actively integrate CASE technologies into new vehicles, setting high industry standards for performance. METI promotes strategic investments in connected car technologies and advanced mobility solutions. Tokyo's dense urban environment fosters demand for ride-hailing services and efficient electric two-wheelers.
India
Urban mobility demands and logistics companies' fleet management needs drive the adoption of connected and shared technologies. The PLI scheme supports domestic manufacturing of advanced automotive components, including EV batteries. Major cities like Bengaluru are seeing increased deployment of ride-hailing services and electric buses to address public transport needs.
Global Connected, Autonomous, Shared, and Electric (CASE) Market Key Industry Players
Chinese producers anchor one tier, focusing on rapid electrification and integrated digital ecosystems. European and North American specialists hold another, emphasizing advanced autonomous driving and software-defined architectures. Strategic archetypes include established automakers, technology specialists, and new mobility providers. Companies are engaging in strategic partnerships and portfolio diversification to navigate this evolving market.
Within the established automaker tier, Volkswagen Group and Ford Motor Company occupy positions as traditional automotive giants adapting to software-defined vehicle architectures. Tesla exemplifies the integrated software stack and direct-to-consumer model, setting a high bar for legacy manufacturers in the electric vehicle space. Robert Bosch GmbH, a German technology specialist, leverages deep expertise in sensors and control units for advanced autonomous driving systems. These companies represent distinct approaches to capturing value across the diverse segments of the CASE market.
| Leading Market Players |
|---|
| Tesla |
| BMW Group |
| Ford Motor Company |
| General Motors |
| Volkswagen Group |
| Toyota Motor Corporation |
| Robert Bosch GmbH |
| Continental AG |
| BYD Company Ltd. |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's emissions targets compel automakers to adopt electric vehicle platforms, which in turn drives demand for specialized components and influences their pricing structures. This demand-side pressure necessitates responsive supply chain adjustments and impacts cost recovery across the value chain.
Pricing Analysis
Volume-based contracts for core CASE components often yield lower margins, while specialized software features command premium pricing. The dominant pricing model is hybrid, combining transactional hardware sales with recurring subscription services for software. Price differentiation stems from certification levels, particularly for advanced driver-assistance systems under the EU's General Safety Regulation, and customization for specific fleet management solutions. Pricing pressure intensifies on hardware components due to global competition and semiconductor supply constraints. Logistics companies exhibit the highest price sensitivity for fleet electrification, whereas OEMs prioritize regulatory compliance for critical safety systems.
Supply Chain Analysis
Dual-sourcing requirements for critical automotive components mitigate risk, yet the CASE supply chain remains geographically concentrated. Key manufacturing hubs in China, Germany, and Taiwan supply essential components like EV batteries, LiDAR sensors, and advanced microcontrollers. This market depends on raw materials such as lithium and rare earth elements, creating commodity price volatility. A significant structural risk is the persistent semiconductor supply constraint, impacting vehicle production globally. Distribution runs primarily through Tier-1 suppliers directly to OEMs, with software and services increasingly delivered over-the-air to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CASE market is undergoing a profound technology-transition phase, with software-defined vehicle architectures displacing traditional hardware-centric designs. This shift redefines value creation and competitive dynamics across the industry.
For Market Incumbents: Deploy significant R&D investment into integrated software stacks to counter the threat from agile technology specialists like Tesla. Automakers must accelerate platform standardization across their vehicle portfolios to reduce development costs and complexity. Deepen vertical integration into battery production and software development to secure critical supply chains. This strategy mitigates margin pressure from new entrants and ensures compliance with global emissions targets.
For New Entrants and Emerging Players: AI-based navigation algorithms offer a technology-first wedge into urban logistics fleet management solutions. Target specialized electric vans for last-mile delivery, where efficiency gains and emissions reductions are critical for logistics companies. Focus on developing V2X infrastructure services for smart city initiatives in Europe and Asia. A direct-to-business subscription model provides a recurring revenue stream and fosters deeper customer integration.
For Investors and Strategic Acquirers: Re-rating potential sits with software-defined vehicle platform providers given the market's long-term shift towards recurring service revenue. Focus on specialist firms in AI-based navigation, LiDAR sensor integration, or V2X communication protocols for strategic acquisitions. These targets offer critical intellectual property and talent over a five-to-ten-year horizon. The signal to watch is the widespread standardization of V2X communication protocols across major regulatory bodies, indicating readiness for scaled deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces development costs for Volkswagen Group across diverse vehicle segments. |
| Software-Defined Vehicle Investment | Enhances vehicle functionality and creates new revenue streams for Tesla. |
| Battery Supply Agreement | Secures critical raw materials and production capacity from China for OEMs. |
| Charging Infrastructure Partnership | Expands electric vehicle adoption and supports urban mobility in Europe. |
| AI-based Navigation Development | Improves autonomous driving capabilities and competitive advantage for California technology hubs. |
Research Approach
Document review covered regulatory filings from NHTSA and MIIT, academic research on AI algorithms, and industry reports on EV adoption, complemented by interviews. Primary research involved discussions with OEM platform engineers, mobility service executives, Tier 1 sensor developers, and logistics fleet managers. Secondary validation utilized vehicle production databases and smart city project reports. This approach ensured robust bottom-up market sizing, cross-referenced with top-down validation across all segments.
The quantitative model produced volume and value projections across the analysis window, integrating historical data with future growth drivers. The analytical framework segmented the market by vehicle type, technology, service model, end user, and regional regulatory compliance. Compound annual growth rates were derived from regression analysis of historical trends and projected market shifts. Forecast inputs included electric vehicle sales forecasts and autonomous system deployment rates in key markets.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts and disruptive new energy storage technologies. Forecasts reflect current regulatory trajectories and technological development speeds. Deviation in global semiconductor supply or major cybersecurity breaches would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Autonomous Electric Bus Market