
 Global Intelligent All-Wheel Drive System Market | 2026-2036
Global Intelligent All-Wheel Drive System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent All-Wheel Drive System Market Outlook
German powertrain engineering is consolidating around electrified axle architectures. BorgWarner Inc. leverages its eAxle portfolio to anchor North American EV supply chains. ZF Friedrichshafen AG dominates modular driveline platforms for European OEMs. Magna International Inc. extends manufacturing scale across Ontario and Graz assembly corridors.
An intelligent all-wheel drive system distributes torque across axles through electronically controlled differentials, multi-plate clutches, or motor-driven units with response latencies under 100 milliseconds. It maintains traction across variable friction surfaces while optimizing fuel efficiency through predictive terrain mapping. Electronic product types lead current volume owing to mature ESC integration pathways, yet AI-Driven technology categories capture widening margin pools as neural-network torque allocation displaces rule-based controllers. Passenger Vehicles anchor application demand, though Performance Vehicles segment specialization sustains premium pricing for predictive drift-control modules.
NHTSA rollover-resistance protocols and Euro NCAP stability-assessment frameworks compel OEM fitment of predictive torque-vectoring hardware. EPA corporate fleet efficiency standards and China's MIIT dual-carbon compliance pathways further bias demand toward electrified AWD architectures with decoupling capability. Stakeholders must monitor software-defined vehicle platform roadmaps to determine whether driveline intelligence migrates to central compute or remains axle-embedded.
Market Dynamics
Electrification of axle architectures is compressing development cycles and forcing suppliers to consolidate control electronics with motor-inverter units. Torque-vectoring hardware now ships as integrated eAxle modules rather than discrete clutch packs, reshaping procurement specifications across OEM engineering departments.
Growth Catalysts
- MIIT dual-carbon compliance pathways:China's fleet efficiency mandates accelerate electrified AWD fitment with decoupling capability. Domestic OEMs in the Yangtze River Delta cluster prioritize torque-vectoring architectures for export-bound SUVs.
- Performance Vehicle specialization:Predictive drift-control modules command sustained premium pricing. Track-day enthusiasts and motorsport homologation programs drive specification of sub-50 millisecond torque allocation systems.
- Euro NCAP stability-assessment frameworks:Tightening traction-system requirements compel European OEMs to standardize predictive torque-vectoring hardware across C-segment and above platforms.
Market Restraints
- Neodymium supply concentration:Rare earth magnet dependency for motor-driven units exposes supply chains to processing bottlenecks in China's Inner Mongolia refining corridor.
- NHTSA rollover-resistance protocol complexity:Validation testing for multi-surface torque distribution adds 14-18 months to platform homologation timelines.
- Rule-based controller substitution:Legacy electronic limited-slip differentials retain cost advantage in emerging-market pickup applications, delaying neural-network adoption.
Strategic Opportunities
- Software-defined vehicle convergence:Centralized compute architectures create openings for axle-embedded intelligence to migrate to domain controllers, enabling subscription-based torque-vectoring feature activation.
- India's PLI scheme for automotive:Localized eAxle assembly for compact SUVs targets ASEAN export markets with cost-optimized clutch-based systems.
- AI-Driven neural-network allocation:Machine learning torque prediction trained on terrain databases enables predictive surface adaptation before wheel slip detection.
Industry Challenges
- Embedded systems cybersecurity certification:ISO/SAE 21434 compliance for torque-control ECUs demands specialized firmware engineering talent scarce in traditional driveline suppliers.
- Legacy CAN bus integration:Mixed-voltage architectures complicate real-time torque commands between new axle controllers and older vehicle networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent All-Wheel Drive System Market |
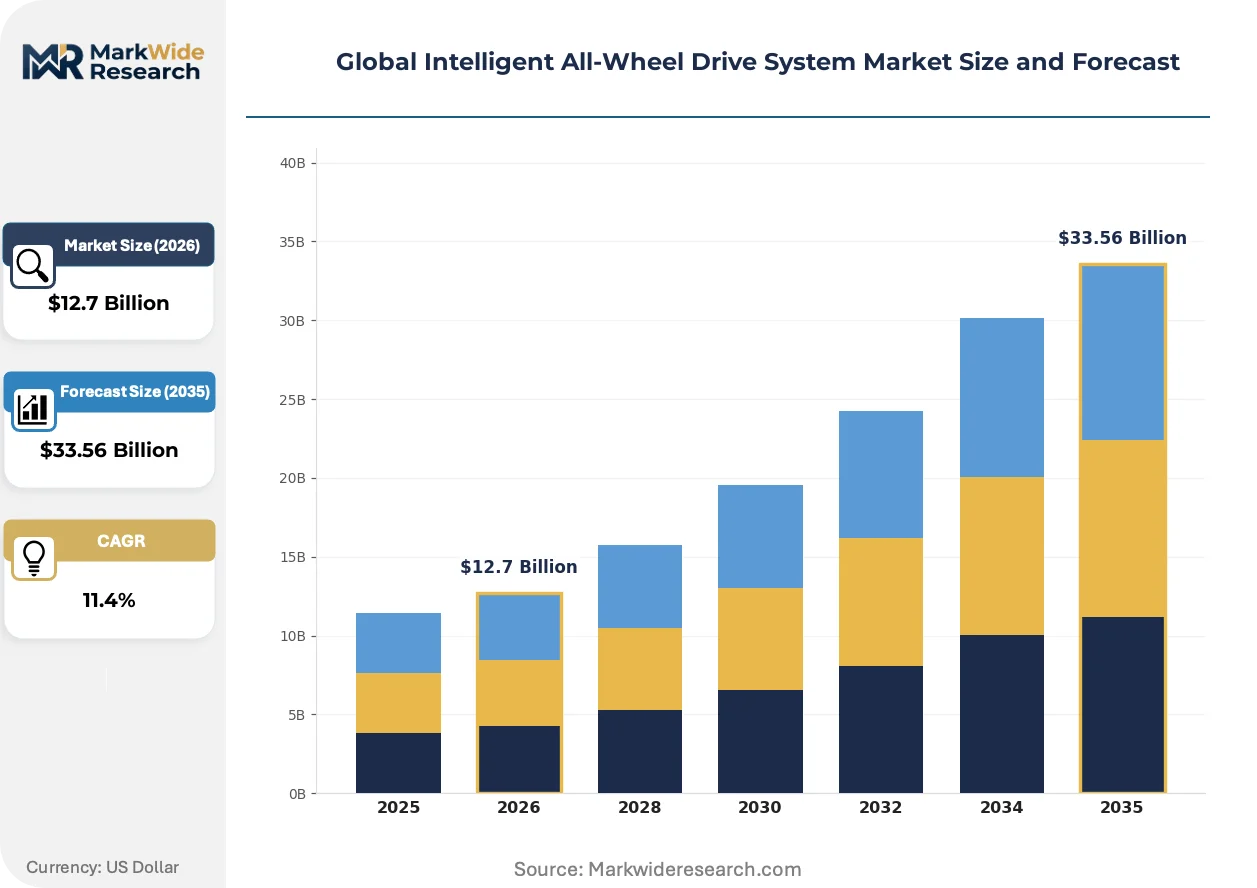
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Mechanical, Hybrid, Adaptive End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Sensor-Based, Control Algorithms, Feedback Systems, AI-Driven Application: Passenger Vehicles, Commercial Vehicles, SUVs, Performance Vehicles |
| Companies Covered | GKN Automotive, JTEKT Corporation, BorgWarner Inc., Dana Incorporated, Eaton Corporation, ZF Friedrichshafen AG, Continental AG, Haldex AB, Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent All-Wheel Drive System Market Strategic Shifts
Neural-network torque allocation is compressing response latencies below mechanical system physical limits. The technology frontier centers on predictive terrain mapping that anticipates friction surface changes before wheel contact.
AI-Driven torque-vectoring controllers process fused camera and radar inputs to pre-position differentials before slip detection. Premium SUV manufacturers in Germany and Japan specify these systems for highway-adjacent gravel transitions. Rule-based PID controllers is overtaking legacy map-based calibration in volume segments as training data costs decline and edge compute capacity expands.
EPA corporate fleet efficiency standards tighten through 2030, biasing AWD architectures toward full decoupling capability. Electrified drivelines with axle-disconnect clutches qualify for compliance credits under light-duty truck categories. Mid-size crossover platforms in the US market respond with on-demand rear-axle engagement systems replacing full-time mechanical layouts.
Fleet procurement specifications now embed predictive maintenance clauses for torque-vectoring hardware. Leasing companies and commercial operators in China's Yangtze River Delta automotive cluster demand usage-based service contracts with clutch-wear telemetry. This unbundles after-sales revenue from unit sales and shifts supplier relationships toward data-sharing partnerships with telematics platform operators.
Global Intelligent All-Wheel Drive System Market Segmentation
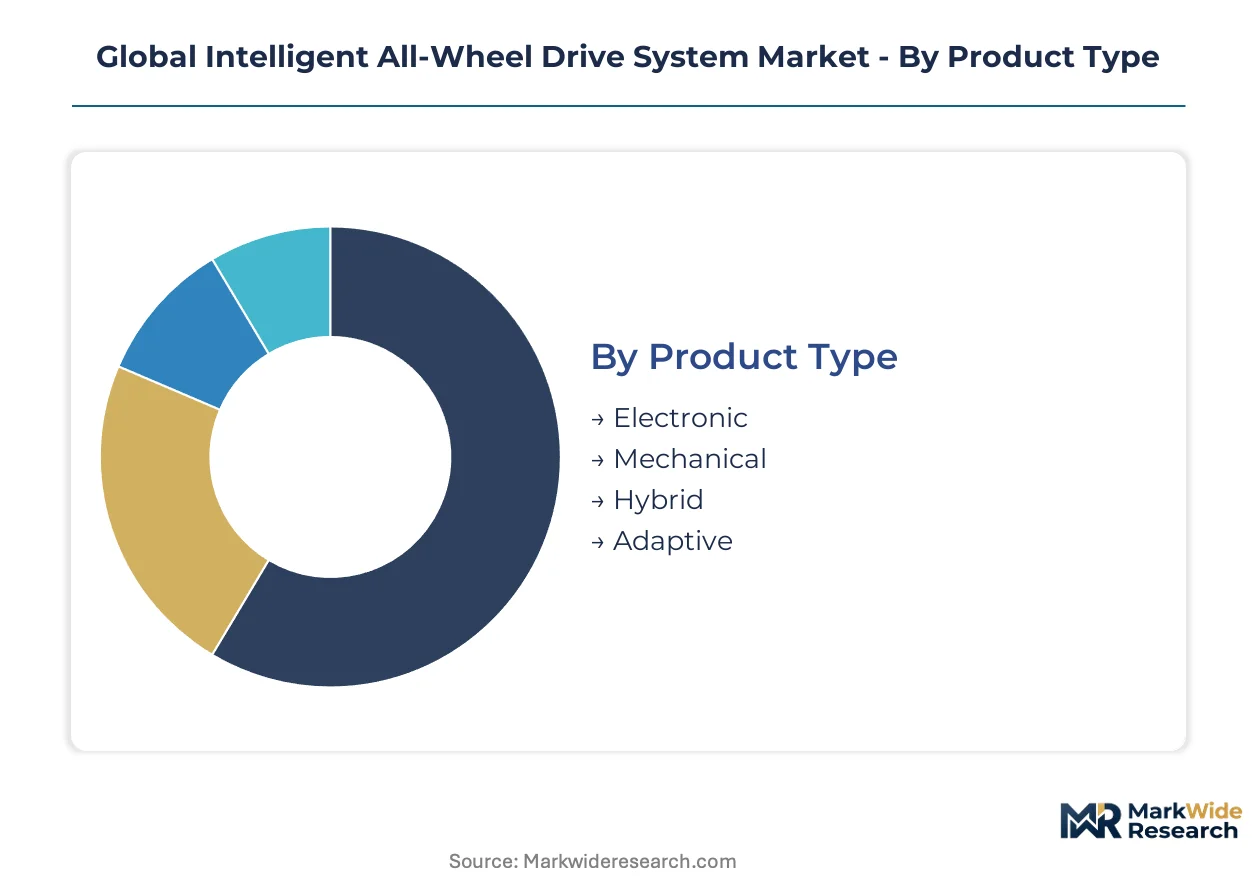
Intelligent all-wheel drive procurement splits across four critical dimensions. Product type determines hardware integration complexity. Technology tier separates rule-based controllers from neural-network architectures. Application scope governs torque-vectoring specifications. End-user category dictates warranty terms and software-update liability.
Product Type:
Buyer selection hinges on electrification roadmap compatibility and ESC integration maturity.
- Electronic:Multi-plate clutch packs and electronically controlled differentials deliver sub-100 millisecond torque redistribution. Passenger vehicle OEMs in Germany and Japan specify these systems for C-segment platforms seeking NHTSA rollover compliance without full electrification cost.
- AI-Driven:Neural-network controllers process fused sensor inputs to pre-position torque before wheel slip detection. Premium SUV manufacturers specify these architectures for predictive terrain mapping, though training data costs constrain volume deployment.
- Mechanical:Viscous couplings and limited-slip differentials retain cost advantage in emerging-market pickup applications.
- Hybrid:Combined mechanical-electronic architectures bridge legacy platforms toward electrified drivelines.
- Adaptive:Self-calibrating systems adjust torque maps based on driving history and surface telemetry.
Electronic systems lead on scale; AI-Driven systems lead on momentum.
Technology:
Control architecture sophistication determines margin capture and software-update revenue potential.
- AI-Driven:Machine learning torque prediction trained on terrain databases enables sub-50 millisecond allocation decisions. Performance vehicle specialists in Japan command premium pricing for predictive drift-control modules with motorsport homologation.
- Sensor-Based:Wheel-speed, steering-angle, and accelerometer arrays feed rule-based controllers. China's Yangtze River Delta OEMs prioritize these systems for export-bound SUVs targeting Euro NCAP stability benchmarks.
- Control Algorithms:PID and map-based calibration suites dominate mid-size crossover procurement.
- Feedback Systems:Real-time clutch-wear telemetry enables usage-based service contracts for fleet operators.
Sensor-Based architectures dominate current volume; AI-Driven categories capture widening margin pools.
Application:
Vehicle category dictates torque-vectoring precision requirements and decoupling capability specifications.
- Passenger Vehicles:On-demand rear-axle engagement systems replace full-time mechanical layouts in US mid-size crossovers. EPA fleet efficiency credits drive decoupling-capable electrified architectures.
- Performance Vehicles:Track-day enthusiasts and motorsport programs demand sub-50 millisecond torque allocation with predictive drift control. German OEMs specify these modules for highway-adjacent gravel transition scenarios.
- SUVs:Premium torque-vectoring hardware standardizes across C-segment and above platforms under tightening Euro NCAP protocols.
- Commercial Vehicles:Fleet procurement embeds predictive maintenance clauses with clutch-wear telemetry for leasing operators.
Passenger Vehicles anchor absolute demand; Performance Vehicles sustain premium pricing power.
End User:
Supply chain position determines liability allocation and software-defined vehicle integration responsibility.
- OEMs:Vehicle manufacturers specify integrated eAxle modules rather than discrete clutch packs, compressing supplier development cycles. German powertrain engineering consolidates around electrified axle architectures with embedded intelligence.
- Tier-1 Suppliers:Driveline specialists face procurement pressure to consolidate control electronics with motor-inverter units.
- Aftermarket Providers:Retrofit torque-vectoring kits target enthusiast segments with legacy CAN bus integration challenges.
- Vehicle Assemblers:Contract manufacturers in India's PLI scheme target ASEAN export markets with cost-optimized clutch-based systems.
OEMs command specification authority; Tier-1 Suppliers absorb integration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German torque-vectoring engineering commands premium SUV specifications while China's Yangtze River Delta cluster drives electrified AWD volume. Japan's motorsport heritage sustains sub-50 millisecond allocation development. India's PLI scheme and US EPA fleet standards reshape regional procurement patterns.
China
Domestic OEMs in the Yangtze River Delta prioritize torque-vectoring architectures for export-bound SUVs. MIIT dual-carbon compliance pathways mandate electrified AWD fitment with decoupling capability. Shanghai and Suzhou assembly corridors concentrate eAxle module production for ASEAN markets.
Germany
Premium SUV manufacturers specify predictive drift-control modules for highway-adjacent gravel transitions. Euro NCAP stability-assessment frameworks compel standardization across C-segment and above platforms. Baden-Württemberg and Bavaria anchor powertrain engineering consolidation around electrified axle architectures.
United States
Mid-size crossover platforms respond with on-demand rear-axle engagement systems replacing full-time mechanical layouts. EPA corporate fleet efficiency standards tighten through 2030, biasing architectures toward full decoupling capability. Michigan and Ohio assembly corridors integrate torque-vectoring hardware with ESC platforms.
Japan
Performance vehicle specialists command premium pricing for predictive drift-control modules with motorsport homologation. METI efficiency benchmarks accelerate neural-network controller adoption. Nagoya and Tokyo engineering centers develop sub-50 millisecond allocation systems for track-day enthusiasts.
India
Localized eAxle assembly for compact SUVs targets ASEAN export markets with cost-optimized clutch-based systems. PLI scheme incentives attract driveline suppliers to Tamil Nadu and Maharashtra manufacturing zones. Domestic OEMs prioritize sensor-based architectures for Euro NCAP-bound exports.
Global Intelligent All-Wheel Drive System Market Competitive Environment
German producers anchor the premium electrified axle tier; Japanese specialists hold performance torque-vectoring positions. The vendor base splits between consolidated eAxle integrators and fragmented clutch-pack suppliers. Three archetypes dominate: integrated module suppliers, discrete component specialists, and software-defined vehicle platform partners. Competitive intensity centers on M&A consolidation of control electronics with motor-inverter units and strategic partnerships for AI-Driven neural-network allocation.
Within the integrated module tier, BorgWarner Inc., ZF Friedrichshafen AG, and Magna International Inc. occupy positions exemplifying the shift toward axle-embedded intelligence. BorgWarner represents North American EV supply chain anchoring through its eAxle portfolio. ZF Friedrichshafen AG exemplifies European modular driveline platform dominance. Magna International Inc. sits within the manufacturing scale archetype across Ontario and Graz assembly corridors. These three entities illustrate how suppliers consolidate procurement specifications through integrated offerings rather than discrete components.
| Leading Market Players |
|---|
| GKN Automotive |
| JTEKT Corporation |
| BorgWarner Inc. |
| Dana Incorporated |
| Eaton Corporation |
| ZF Friedrichshafen AG |
| Continental AG |
| Haldex AB |
| Magna International Inc. |
| Others |
Value Chain & Pricing Dynamics
MIIT dual-carbon compliance pathways in China are forcing export-bound SUV manufacturers to specify electrified AWD architectures with decoupling capability, compelling suppliers to absorb motor-inverter integration costs and compressing channel margins for discrete clutch-pack vendors.
Pricing Analysis
Distributor margins for electronic limited-slip differentials have compressed as OEM procurement shifts toward integrated eAxle modules. Pricing stratifies across AI-Driven neural-network tiers, sensor-based rule controllers, and legacy mechanical systems based on certification complexity and software-update entitlement. Cost compression in electronic clutch packs is intensifying because electrified axle architectures eliminate discrete component procurement. Fleet operators in China's Yangtze River Delta cluster exhibit highest price sensitivity through usage-based service contract negotiations, while German premium SUV manufacturers demonstrate lowest sensitivity for predictive drift-control modules.
Supply Chain Analysis
India's PLI scheme for automotive is reshaping sourcing patterns by incentivizing localized eAxle assembly for ASEAN export markets. Manufacturing concentrates in China, Germany, and Japan for torque-vectoring hardware, with control electronics sourcing anchored in Taiwan and South Korea. Neodymium magnet processing for motor-driven units rests on China's Inner Mongolia refining corridor, creating single-source vulnerability for rare earth inputs. Distribution runs through Tier 1 driveline integrators who consolidate procurement specifications with embedded intelligence modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA rollover-resistance mandates and Euro NCAP stability protocols create irreversible demand for predictive torque-vectoring hardware across C-segment and above platforms.
For Market Incumbents: Anticipate neural-network controller displacement of rule-based architectures by accelerating firmware engineering recruitment for ISO/SAE 21434 cybersecurity certification. Consolidate control electronics with motor-inverter units through selective acquisition of inverter specialists. Defend against software-defined vehicle platform migration by embedding axle intelligence with predictive maintenance telemetry that central compute cannot replicate.
For New Entrants and Emerging Players: Aftermarket retrofit providers serving legacy CAN bus vehicles represent an underserved buyer archetype with limited incumbent attention. Target India's PLI scheme corridors with cost-optimized clutch-based systems for compact SUV export programs. Pursue white-space in fleet telematics partnerships by unbundling clutch-wear monitoring from unit sales through data-sharing agreements with Yangtze River Delta leasing operators.
For Investors and Strategic Acquirers: Asymmetric upside sits with AI-Driven torque-vectoring specialists possessing terrain database training assets and sub-50 millisecond allocation patents. Long-term viability favors vendors who control neural-network torque prediction IP rather than mechanical hardware fabrication. Monitor software-defined vehicle platform roadmaps as the inflection signal determining whether driveline intelligence migrates to domain controllers or remains axle-embedded.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Neural-Network Allocation | Machine learning torque prediction trained on terrain databases enables predictive surface adaptation before wheel slip detection. |
| eAxle Module Integration | Consolidated control electronics with motor-inverter units reshape procurement specifications across German and Japanese OEM engineering departments. |
| Predictive Maintenance Telemetry | Clutch-wear monitoring unbundles after-sales revenue from unit sales through data-sharing partnerships with Yangtze River Delta fleet operators. |
| Cybersecurity Certification Investment | ISO/SAE 21434 compliance for torque-control ECUs demands specialized firmware engineering talent scarce in traditional driveline suppliers. |
| Localized Assembly Under PLI Schemes | India's automotive PLI incentives attract driveline suppliers to Tamil Nadu and Maharashtra for ASEAN export market penetration. |
Study Parameters
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations specialists grounded the qualitative assessment. Secondary validation drew from vehicle production databases, IHS Markit registration data, NHTSA homologation filings, and Euro NCAP stability-assessment protocols. Bottom-up and top-down triangulation cross-checked segment-level volume assumptions against aggregate market sizing.
Bottom-up modeling of content-per-vehicle trajectories across passenger, performance, SUV, and commercial vehicle categories combined with top-down regulatory mandate analysis. Segmentation dimensions included product type, technology tier, application scope, and end-user category across regional production clusters. CAGRs were derived from fitted growth curves incorporating EPA fleet efficiency tightening, MIIT dual-carbon pathway phase-ins, and neural-network controller adoption S-curves.
Underlying measurement precision varies by segment; AI-Driven technology categories carry tighter precision than mechanical legacy systems owing to visible patent filings and disclosed training partnerships. Forecasts reflect assumptions regarding electrification roadmap timing and software-defined vehicle platform migration that regulatory shifts or technological breakthroughs could revise. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Automotive Belts and Hoses Market