
 Africa Automotive Engine Oils Market | 2026-2036
Africa Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Automotive Engine Oils Market Outlook
Refinery expansion across North African petrochemical complexes is pivoting toward higher Group II and Group III base oil output for regional blending. TotalEnergies leverages its Egyptian lubricant blending facility to supply East African markets through Red Sea logistics corridors. Shell Plc anchors its competitive position through an extensive retail network spanning South Africa, Nigeria, and Kenya. ExxonMobil Corporation differentiates via technology leadership in synthetic formulations tailored to high-temperature African operating conditions.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines operating under severe thermal and particulate loads typical of African road conditions. Their primary commercial purpose is to extend engine life and maintain performance in vehicles subjected to dust-laden environments, irregular maintenance intervals, and variable fuel quality. Synthetic grades command premium positioning due to extended drain intervals and superior oxidation stability under extreme heat, while conventional oils retain volume dominance in price-sensitive aftermarket channels across West and East Africa. Heavy-duty trucks represent the most structurally concentrated end-user segment, with fleet operators driving bulk procurement through wholesale and direct distribution arrangements rather than fragmented retail purchases.
South Africa's SABS standards, Nigeria's SON certification requirements, and Kenya's KEBS quality marks collectively shape product registration barriers and formulation compliance costs for lubricant suppliers entering national markets. These frameworks push multinational blenders toward localized testing facilities and regional certification strategies rather than single-country approvals. Stakeholders must monitor evolving national fuel quality standards and emission protocols, as sulfur content reductions in diesel and petrol will necessitate corresponding additive package adjustments in engine oil formulations across the continent's major automotive markets.
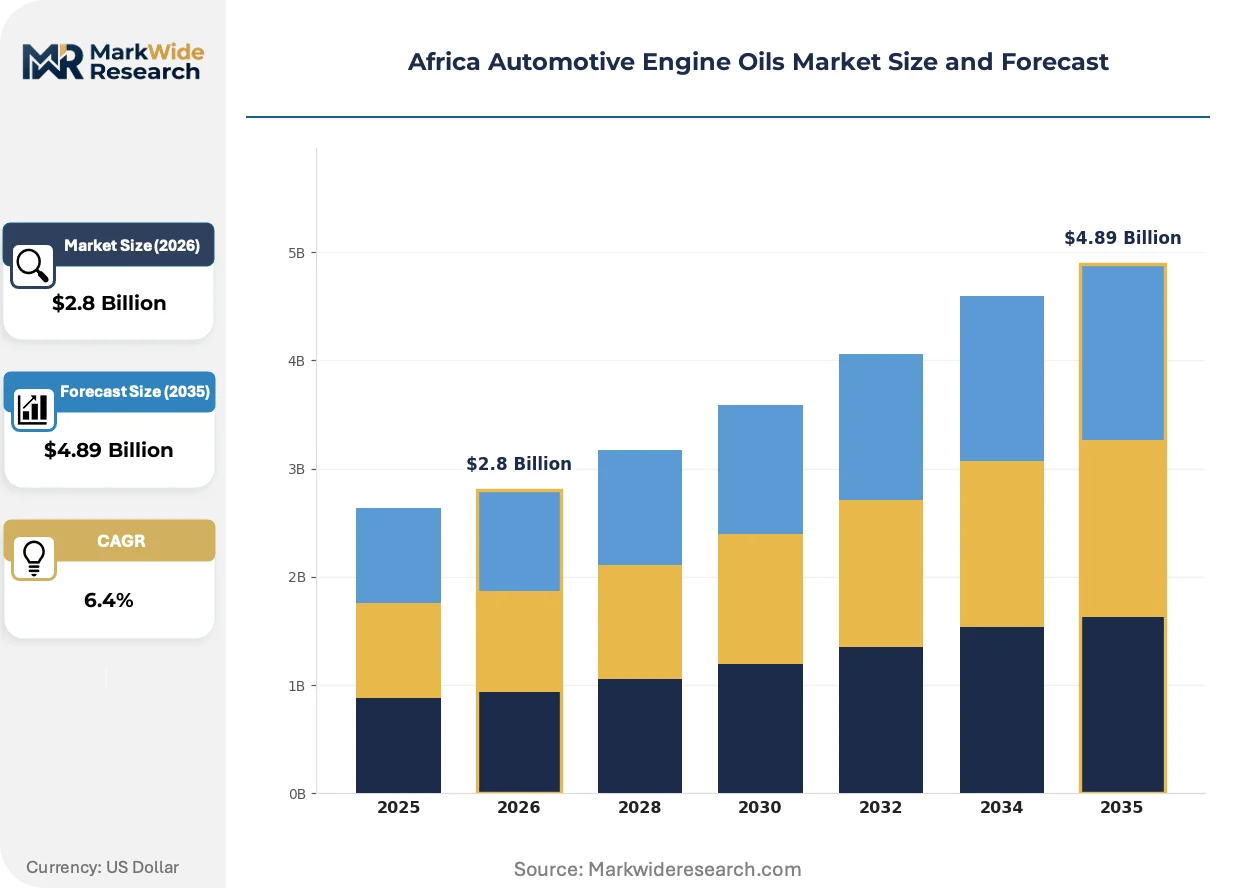
Market Dynamics
Refinery modernization across North Africa is concentrating Group II and Group III base oil production within regional petrochemical complexes, compressing import dependence and altering blending economics for lubricant suppliers serving sub-Saharan distribution networks.
Growth Catalysts
- Logistics corridor expansion:Nigeria's northern transport corridor linking Lagos to Kano is generating concentrated heavy-duty truck fleet operations that consume bulk lubricant volumes through direct procurement arrangements.
- Quality standard enforcement:South Africa's SABS 1258 specifications for engine oil formulations are mandating additive package upgrades that premium-grade suppliers can leverage for margin expansion.
- Synthetic formulation adoption:Extended drain interval technologies are penetrating fleet operator maintenance protocols in Kenya's Mombasa-Nairobi trucking route, reducing total cost of ownership calculations.
Market Restraints
- Base oil supply concentration:Egyptian and Algerian refinery complexes control regional Group II/III output, creating bottleneck vulnerability for blenders lacking long-term offtake agreements.
- Counterfeit product infiltration:Unlicensed blending operations in Nigeria's informal sector erode certified supplier volumes and compress legitimate pricing power in aftermarket channels.
- Fuel quality variability:High sulfur diesel prevalent in West African markets accelerates engine oil degradation, shortening drain intervals and complicating synthetic product value proposition communication.
Strategic Opportunities
- East African market development:Tanzania's Dar es Salaam corridor and Rwanda's Kigali logistics hub remain underpenetrated by multinational blenders with established Kenyan distribution infrastructure.
- Emission protocol alignment:Anticipated sulfur reduction mandates in Nigerian and South African fuel standards will necessitate low-ash, low-SAPS lubricant formulations that first-movers can certify ahead of compliance deadlines.
- Direct fleet contracting:Mining and agricultural equipment operators in Zambia's Copperbelt and Ghana's cocoa regions are consolidating maintenance procurement under centralized fleet management systems.
Industry Challenges
- Certification timeline compression:SON, KEBS, and SABS parallel approval requirements force redundant testing cycles and extended product registration timelines for new market entrants.
- Technical service capacity scarcity:Field engineering expertise for synthetic oil conversion support and used oil analysis interpretation remains concentrated in Johannesburg and Lagos, limiting rural penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Automotive Engine Oils Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
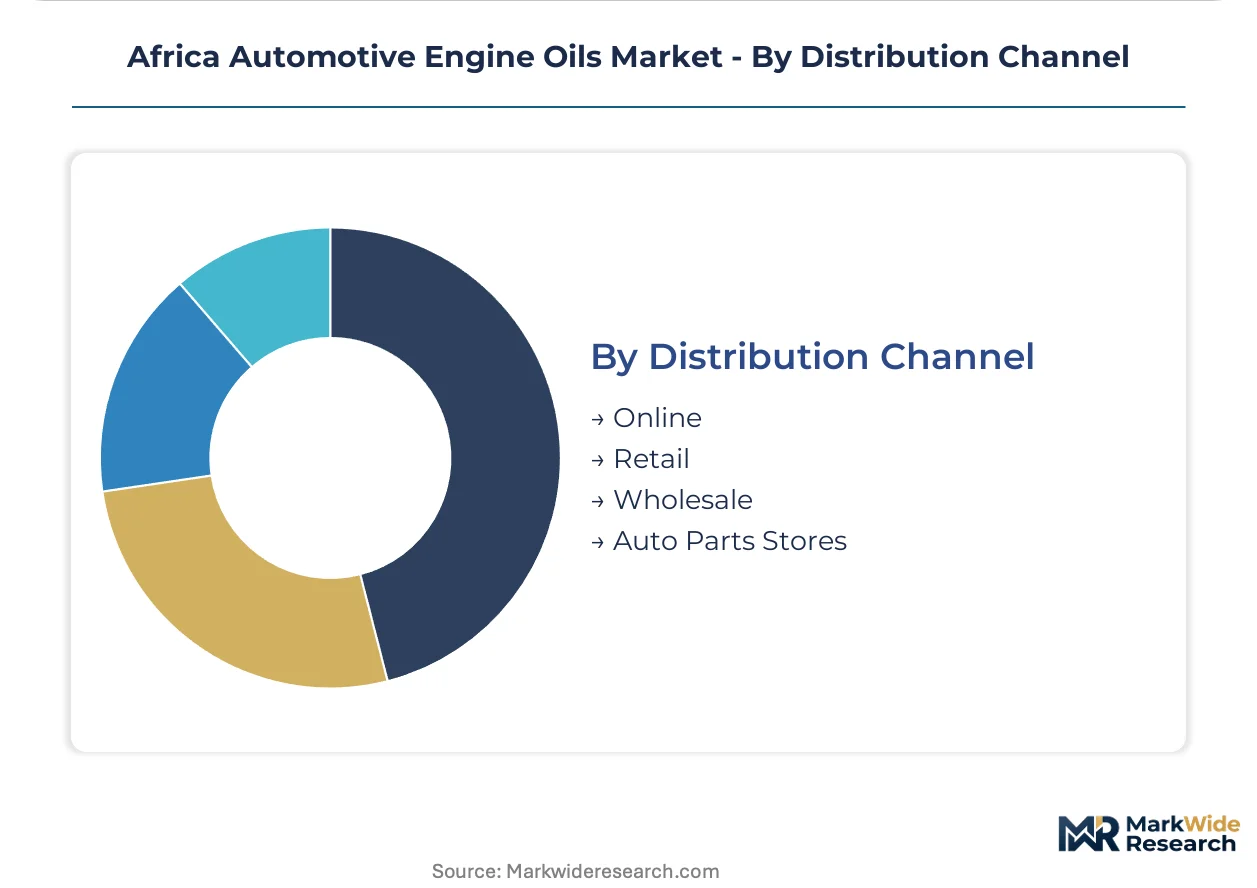
| Segmentation | Product Type: Synthetic, Conventional, Semi-Synthetic, Bio-Based End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Grade: SAE 10W-30, SAE 15W-40, SAE 5W-20, SAE 20W-50 Distribution Channel: Online, Retail, Wholesale, Auto Parts Stores |
| Companies Covered | TotalEnergies, ExxonMobil Corporation, Shell Plc, BP Plc (Castrol), Engen Petroleum Ltd, Chevron Corporation, Astron Energy Pty Ltd, FUCHS, Sasol, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Automotive Engine Oils Market Strategic Shifts
Reformulation priorities are pivoting toward thermal stability and soot-handling capabilities as African operating conditions expose conventional additive packages to accelerated degradation. Three developments are restructuring competitive positioning.
Polymer-modified viscosity index improvers are decentralizing lubricant performance standardization across temperature extremes. Fleet operators in Nigeria's northern corridor are adopting these formulations to maintain oil film strength during desert transit. The technology is decentralizing quality differentiation from multinational brand recognition toward measurable drain interval extension.
South Africa's SABS 1258 alignment with ACEA and API specifications is compressing formulation tolerance ranges for phosphorus and sulfur content. Domestic blenders must recertify existing product lines or exit premium segments. Heavy-duty diesel engine oils face the steepest compliance cost escalation as soot dispersancy requirements tighten.
Fleet procurement consolidation is displacing fragmented retail purchasing in commercial vehicle segments. Transport operators in Kenya's Northern Corridor are negotiating direct supply agreements with blenders, bypassing traditional distributor markups. This channel compression is most visible in Lagos and Mombasa, where logistics companies with 50+ unit fleets now represent the dominant volume concentration.
Africa Automotive Engine Oils Market Segmentation

Segmentation across Africa's automotive engine oils market reveals how formulation technology, vehicle duty cycles, and procurement channel structures interact to determine supplier margin profiles. Understanding these divisions exposes where premium pricing power concentrates versus where volume commoditization dominates.
Product Type:
Synthetic base stocks and additive chemistry sophistication define performance tiering and drain interval economics across African operating conditions.
- Synthetic:Formulated from Group III or PAO base oils with advanced additive packages delivering thermal oxidation resistance and extended drain intervals. Demand concentrates in South Africa's long-haul fleet sector where SABS 1258 compliance and total cost of ownership calculations justify premium positioning. Fleet operators in the Johannesburg-Durban corridor are converting to these formulations to reduce maintenance downtime.
- Conventional:Mineral base oil formulations with standard additive treatments meeting basic API service categories. Volume concentrates in Nigeria's northern transport corridor and Kenya's informal aftermarket where price sensitivity dominates procurement decisions. High sulfur diesel prevalence in these markets accelerates oil degradation, limiting the economic case for premium conversion.
- Semi-Synthetic:Blends combining Group I/II mineral bases with synthetic components balancing cost and performance. Adoption is expanding in Ghana's emerging commercial fleet sector.
- Bio-Based:Vegetable oil-derived base stocks with biodegradable additive systems targeting environmental compliance applications. Deployment remains nascent in South Africa's mining rehabilitation equipment segment.
Mature deployment sits with Conventional formulations across West and East African price-sensitive channels. Newer deployment is concentrated in Synthetic grades within South African and Kenyan fleet operations prioritizing extended service intervals.
End User:
Vehicle duty intensity and operating environment severity determine lubricant consumption rates and formulation specification requirements.
- Heavy-Duty Trucks:Vehicles exceeding 15-tonne gross vehicle weight operating continuous duty cycles under thermal stress and particulate loading. Bulk lubricant consumption concentrates along Nigeria's Lagos-Kano corridor and Kenya's Mombasa-Nairobi route where logistics fleet density is highest. Direct procurement agreements between transport operators and blenders are displacing traditional distributor channels.
- Commercial Vehicles:Light and medium-duty trucks, buses, and delivery vehicles with moderate duty cycles. Demand clusters in urban distribution networks across Lagos, Nairobi, and Johannesburg where stop-start operation increases soot loading.
- Passenger Cars:Private and corporate vehicle fleets with variable maintenance discipline. Volume is fragmented across informal service channels in Nigeria and Kenya.
- Two-Wheelers:Motorcycles and three-wheelers operating high-revving, air-cooled engines in dusty conditions. Consumption is concentrated in West African urban delivery and rural transport applications.
Volume leadership belongs to Heavy-Duty Trucks through concentrated fleet procurement. Passenger Cars and Two-Wheelers represent the most fragmented demand structure with lowest supplier bargaining power.
Grade:
Viscosity specification selection reflects ambient temperature range, engine design generation, and manufacturer warranty requirements across the continent's climatic diversity.
- SAE 15W-40:Multigrade formulation balancing cold-start pumpability with high-temperature film strength. Dominates heavy-duty diesel applications in Nigeria's northern corridor and Kenya's high-altitude routes where diurnal temperature swings exceed 25°C. Fleet operators specify this grade for compatibility with older engine designs prevalent in African import vehicle pools.
- SAE 10W-30:Lower viscosity grade reducing parasitic friction losses in newer engine designs. Adoption is climbing fastest in South Africa's Euro IV/V compliant fleet where fuel economy regulations tighten operational cost structures.
- SAE 5W-20:Ultra-low viscosity formulations for modern gasoline direct injection engines. Deployment is limited to South African premium passenger car segments.
- SAE 20W-50:Higher viscosity grade for high-mileage engines and extreme heat conditions. Retains share in West African informal service channels.
Specification authority rests with SAE 15W-40 across commercial fleet procurement. SAE 10W-30 is gaining share fastest where newer vehicle imports and fuel economy priorities converge.
Distribution Channel:
Channel structure determines pricing transparency, technical service attachment, and counterfeit product exposure risk for end users.
- Wholesale:Direct bulk supply agreements between blenders and fleet operators, mining companies, and agricultural conglomerates. Volume concentrates in Zambia's Copperbelt mining operations and Ghana's cocoa processing logistics where centralized procurement consolidates lubricant purchasing under maintenance management systems. This channel commands lowest unit pricing but requires technical service bundling.
- Retail:Branded service stations and dedicated lubricant outlets serving fragmented vehicle owner demand. Network density is highest in South Africa's metropolitan areas and Nigeria's southern states.
- Auto Parts Stores:Independent aftermarket distributors serving mechanical workshops and DIY consumers. Counterfeit infiltration risk is elevated in Nigeria's informal sector.
- Online:E-commerce platforms and direct-to-fleet digital procurement portals. Penetration remains limited but is expanding in Kenyan urban markets.
Procurement consolidation is reshaping Wholesale channel structure. Retail and Auto Parts Stores retain dominance in fragmented vehicle owner segments where trust in branded physical presence overrides price optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North African petrochemical complexes in Egypt and Algeria supply Group II and Group III base oils that feed blending operations across sub-Saharan distribution networks. Refinery modernization in these localities compresses import dependence and alters logistics economics for lubricant suppliers serving fleet operators from Lagos to Nairobi.
Nigeria
Heavy-duty truck fleets along the Lagos-Kano transport corridor consume bulk lubricant volumes through direct procurement arrangements with blenders. The Standards Organisation of Nigeria enforces SON certification requirements that push multinational suppliers toward localized testing facilities. Northern corridor logistics operators specify SAE 15W-40 grades for compatibility with older engine designs prevalent in the import vehicle pool.
South Africa
Long-haul fleet operators in the Johannesburg-Durban corridor are converting to synthetic formulations to reduce maintenance downtime and meet SABS 1258 specifications. The South African Bureau of Standards mandates additive package upgrades that premium-grade suppliers leverage for margin expansion. Mining equipment operators in the Platinum Belt are consolidating maintenance procurement under centralized fleet management systems.
Kenya
Transport operators along the Mombasa-Nairobi trucking route negotiate direct supply agreements with blenders, bypassing traditional distributor markups. The Kenya Bureau of Standards administers KEBS quality marks that shape product registration barriers for new market entrants. Logistics companies with 50-plus unit fleets in Mombasa now represent the dominant volume concentration in the commercial vehicle segment.
Egypt
TotalEnergies leverages its Egyptian lubricant blending facility to supply East African markets through Red Sea logistics corridors. The Egyptian General Authority for Standardization and Quality oversees petroleum product specifications that align with regional export requirements. Alexandria and Suez petrochemical complexes control regional Group II and Group III base oil output, creating supply leverage for blenders with long-term offtake agreements.
Ghana
Emerging commercial fleet operators in the cocoa processing logistics sector are adopting semi-synthetic formulations balancing cost and performance. The Ghana Standards Authority enforces petroleum product quality standards that compress formulation tolerance ranges for imported lubricants. Agricultural equipment operators in the Ashanti Region are consolidating maintenance procurement under centralized systems.
Africa Automotive Engine Oils Market Competitive Environment
Global majors compete with regional champions across formulation technology and distribution reach in Africa's automotive engine oils market. The supplier base organizes into three tiers: multinational integrated oil companies with captive base oil supply, regional blenders with established national certification portfolios, and independent formulators serving price-sensitive aftermarket channels. Competitive positioning hinges on additive package sophistication, fleet direct contracting capabilities, and compliance with parallel SON, KEBS, and SABS approval requirements. Leading suppliers defend market position through backward integration into base oil production and technical service bundling with wholesale accounts.
Within the multinational integrated tier, TotalEnergies, ExxonMobil Corporation, and Shell Plc exemplify archetypes of competitive positioning. TotalEnergies occupies a position anchored by North African refinery assets and Red Sea logistics corridors. ExxonMobil Corporation represents technology leadership in synthetic formulations tailored to high-temperature African operating conditions. Shell Plc sits within the retail network density archetype, with extensive branded service station presence spanning South Africa, Nigeria, and Kenya. These three companies illustrate how geographic origin, company structure as publicly traded corporations, and strategic archetype differentiation combine to structure competitive dynamics across the continent's fragmented national markets.
| Leading Market Players |
|---|
| TotalEnergies |
| ExxonMobil Corporation |
| Shell Plc |
| BP Plc (Castrol) |
| Engen Petroleum Ltd |
| Chevron Corporation |
| Astron Energy Pty Ltd |
| FUCHS |
| Sasol |
| Others |
Value Chain & Pricing Dynamics
Group II and Group III base oil indices from Egyptian and Algerian refinery complexes cascade through Africa's lubricant supply chain, compressing formulation economics for synthetic grades while amplifying cost advantages for blenders with captive upstream supply. This raw-material concentration stratifies end-market pricing across certification tiers, with SABS 1258-compliant products commanding structural premiums over uncertified alternatives.
Pricing Analysis
Warranty-backed technical service bundling separates premium synthetic formulations from unbundled conventional products in fleet procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects additive package sophistication and drain interval economics. Price differentiation hinges on SON/KEBS/SABS certification status and volume scale in direct contracting arrangements. Cost compression in conventional grades is intensifying because counterfeit infiltration erodes legitimate supplier volumes. Informal aftermarket channels in Nigeria exhibit highest price sensitivity, while South African mining fleet operators show lowest elasticity due to total cost of ownership calculations.
Supply Chain Analysis
Dual-sourcing mandates from multinational mining and logistics operators force blenders to qualify secondary base oil suppliers beyond Egyptian and Algerian complexes. Geographic supply concentration centers on Egypt, Algeria, and South Africa for Group II/III base stocks. Raw material dependencies include viscosity index improvers, detergent-dispersant packages, and anti-wear additives from specialty chemical suppliers. Single-source vulnerability persists for long-term offtake agreements with North African refineries. Distribution runs through Red Sea corridors to East African ports, with Lagos and Durban serving as sub-Saharan consolidation hubs.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's automotive engine oils market sits in a formulation-technology transition, with synthetic base stocks and low-SAPS additive packages displacing conventional mineral oils as sulfur-reduction mandates advance across major economies.
For Market Incumbents: Anticipate regulatory compression in Nigerian and South African fuel standards by pre-certifying low-ash, low-SAPS formulations ahead of compliance deadlines. Deepen backward integration into Egyptian or Algerian base oil production to secure offtake priority as refinery modernization concentrates regional supply. Counterfeit infiltration in West African aftermarket channels demands enhanced authentication technologies and distributor audit protocols. For New Entrants and Emerging Players: SABS 1258 alignment with ACEA specifications in South Africa opens a window for premium-grade suppliers to capture fleet conversion demand as domestic blenders face recertification costs. Target Tanzania's Dar es Salaam corridor and Rwanda's Kigali logistics hub, where multinational penetration remains limited relative to established Kenyan infrastructure. Direct fleet contracting capabilities, bundling used oil analysis and technical field support, offer the most penetrable go-to-market angle against incumbent distributor networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional blenders with established SON, KEBS, and SABS certification portfolios in East African markets. Long-term viability rests on formulation flexibility for emission-protocol alignment and channel control in fleet-direct segments. Watch sulfur-content reduction mandates in Nigerian diesel standards as the inflection signal for additive package demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive supply from Egyptian refineries secures cost advantage as regional Group II/III output concentrates. |
| Low-SAPS Formulation Certification | Pre-compliance with anticipated South African and Nigerian sulfur-reduction mandates captures first-mover positioning. |
| Direct Fleet Contracting Infrastructure | Bypassing distributor markups in Kenya's Mombasa-Nairobi corridor concentrates volume with logistics operators. |
| Technical Service Capacity Expansion | Field engineering hubs beyond Johannesburg and Lagos enable synthetic conversion support in underpenetrated regions. |
| Counterfeit Authentication Technology Deployment | Traceability systems in Nigerian wholesale channels protect certified supplier volumes and pricing power. |
Study Parameters
Document review covered customs and trade data for base oil imports, SABS/SON/KEBS regulatory filings, and petroleum refinery expansion announcements, complemented by interviews with lubricant blenders, fleet procurement managers at logistics operators, mining maintenance directors, and aftermarket distributors across Lagos, Nairobi, and Johannesburg. Secondary validation drew from industry association reports, national standards authority publications, and petrochemical complex disclosure documents. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for commercial vehicle fleet expansion.
Quantitative outputs span product type, end-user segment, viscosity grade specification, and distribution channel dimensions across the projection horizon. CAGRs derive from regression analysis of historical lubricant consumption against vehicle registration data and fleet utilization rates. Modeled inputs include logistics corridor freight volume growth, refinery capacity additions in North Africa, and national fuel quality standard implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for synthetic formulation penetration in price-sensitive West African markets would alter the outlook. Forecasts reflect assumptions regarding sulfur-reduction mandate timing and enforcement consistency. Deviation in Egyptian or Algerian refinery output expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Tappet Market
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Commercial Vehicle Brake Chambers Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Timing Gear Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Automotive Canister Purge Valve Market