
 Global Automotive Selective Catalytic Reduction System Market | 2026-2036
Global Automotive Selective Catalytic Reduction System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Selective Catalytic Reduction System Market Intelligence
The substitution of high-cost platinum group metals with advanced zeolite catalysts is pivoting the product economics for SCR systems. Bosch GmbH leverages its extensive R&D in catalyst coating technology to offer cost-effective solutions for global platforms. Faurecia SE specializes in complete exhaust system integration, optimizing performance for commercial vehicle OEMs. Tenneco Inc. competes on its global manufacturing footprint and extensive aftermarket channel presence through its brands.
An automotive selective catalytic reduction system is an active emissions control technology converting harmful nitrogen oxides (NOx) into diatomic nitrogen and water. It injects a liquid-reductant agent, typically automotive-grade urea known as AdBlue, through a specialized catalyst into the exhaust stream of a diesel engine. Heavy-duty trucks and buses form the dominant vehicle type segment due to strict emissions rules for commercial transport. Zeolite catalysts are displacing older ceramic formulations, offering superior thermal durability and higher NOx conversion efficiency in demanding applications.
Emission standards from the US EPA, Europe's Euro VI and Euro 7 framework, and China's National VI regulations are primary market drivers. These mandates set firm limits on NOx output, compelling OEMs to integrate SCR technology as a standard feature on diesel vehicles. Stakeholder focus now turns to adapting SCR systems for hybrid powertrains and the use of low-carbon alternative fuels.
Market Dynamics
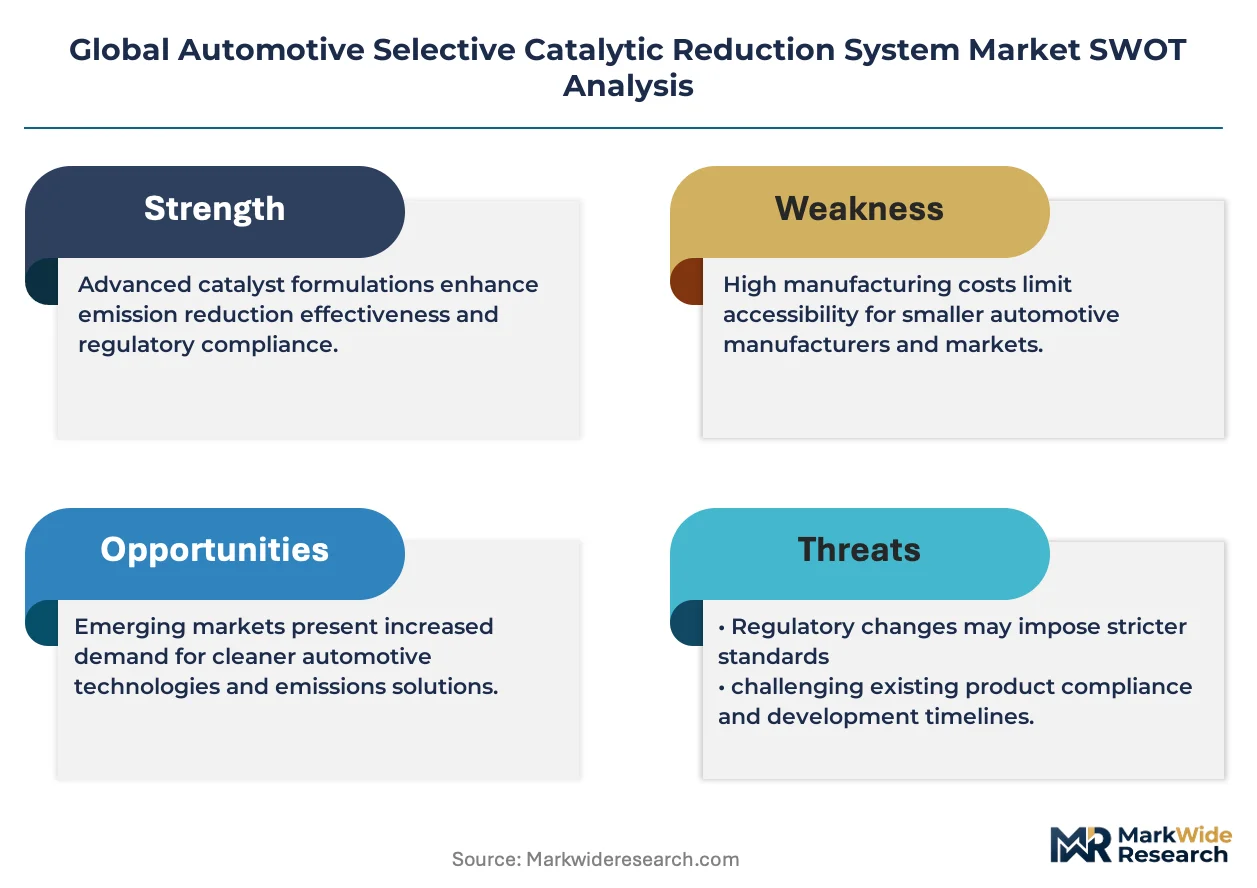
The central structural force shaping the automotive selective catalytic reduction system market is the global regulatory push for near-zero NOx emissions. This pressure compels continuous material science innovation to balance performance requirements against the high cost of precious metal catalysts.
Growth Catalysts
- Stringent Emission Mandates:Regulations like China's National VI and Europe's upcoming Euro 7 standards set firm NOx limits for new vehicles, making SCR system integration a non-negotiable requirement for diesel engine manufacturers.
- Advanced Catalyst Materials:The development of advanced zeolite catalysts provides superior thermal stability and higher NOx conversion efficiency, enabling compliance in demanding heavy-duty truck and bus applications while reducing platinum group metal content.
- Expansion into Off-Highway Vehicles:Adoption is accelerating in non-road mobile machinery (NRMM), including construction and agricultural equipment, as these segments fall under stricter emissions controls in North America and the European Union.
Market Restraints
- Input Cost Volatility:The system's economic viability is sensitive to price fluctuations in platinum group metals like platinum and palladium, which are essential for catalyst formulations and subject to geopolitical supply risks.
- Urea Infrastructure Gaps:In certain developing regions across South America and Africa, the limited availability and distribution network for automotive-grade urea (AdBlue) acts as a significant barrier to widespread vehicle adoption.
- Low-Temperature Performance:SCR systems exhibit reduced NOx conversion efficiency during low-load, low-temperature engine operation, posing a technical challenge for integration with hybrid-electric powertrains and in urban stop-start traffic.
Strategic Opportunities
- Retrofit Market Development:There is a significant opportunity to retrofit older, in-service heavy-duty truck fleets in markets like India, Mexico, and Brazil as they progressively implement stricter, Euro-equivalent emission standards.
- Alternative Fuel Compatibility:Adapting and validating SCR systems for engines running on low-carbon alternative fuels, such as hydrogenated vegetable oil (HVO) and other biofuels, opens a new avenue for emissions reduction in legacy fleets.
- System-Level Integration:Tighter integration of SCR control logic with powertrain control modules and vehicle telematics enables real-time emissions monitoring and adaptive dosing strategies, creating value through fuel efficiency and compliance assurance.
Industry Challenges
- Diagnostic and Repair Complexity:The growing number of sensors and complex control software within modern SCR systems increases the skill requirement for vehicle technicians, creating a need for advanced training and diagnostic tools in the aftermarket.
- Ensuring Long-Term Compliance:Preventing system tampering and the use of non-compliant or diluted urea solutions remains a persistent operational challenge for regulators and fleet operators aiming to maintain emissions performance over the vehicle's lifetime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Selective Catalytic Reduction System Market |
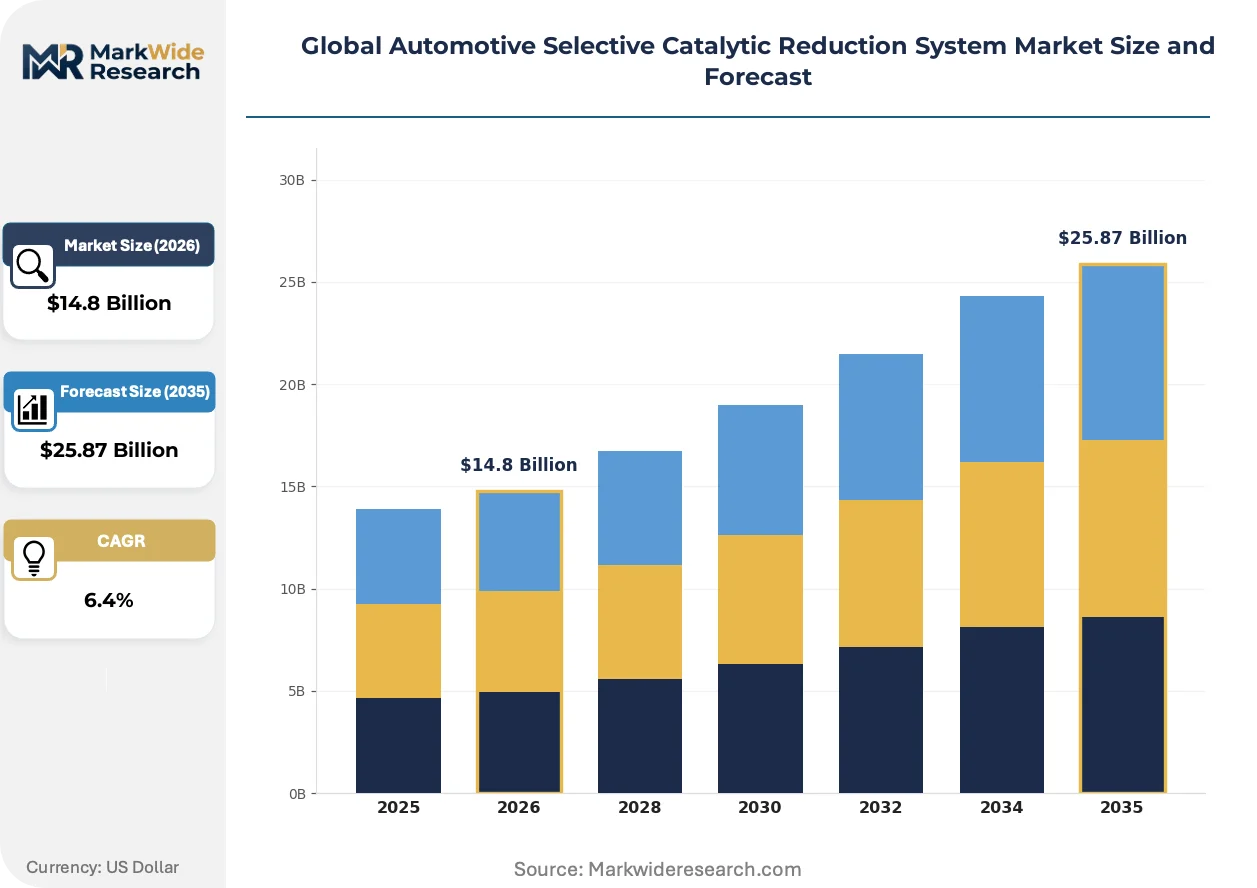
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ceramic Catalysts, Metal Catalysts, Zeolite Catalysts, Platinum-Based Catalysts, Palladium-Based Catalysts Vehicle Type: Light Commercial Vehicles, Heavy-Duty Trucks, Passenger Cars, Buses, Off-Highway Vehicles Aftermarket Channel: Authorized Dealers, Independent Workshops, E-Commerce Platforms, Fleet Operators, Specialty Distributors End User: OEMs, Tier-1 Component Suppliers, Vehicle Assemblers, Retrofitters, Fleet Maintenance Providers |
| Companies Covered | Denso Corporation, Bosch GmbH, BASF SE, Faurecia SE, Tenneco Inc., Johnson Matthey Plc, Continental AG, Umicore SA, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Selective Catalytic Reduction System Market Strategic Shifts & Innovations
The market's trajectory is defined by a dual focus on material science breakthroughs and intelligent system control. Innovation centers on developing more durable catalysts and integrating aftertreatment systems more deeply into the vehicle's electronic architecture for optimized performance.
Advanced zeolite catalysts featuring specific pore structures are a primary focus of material development for SCR systems. Heavy-duty vehicle OEMs are rapidly adopting these materials to meet stringent NOx limits under real-world driving conditions. This material innovation is consolidating the supply of high-performance catalysts among a few specialized chemical producers who control the core intellectual property.
Europe's impending Euro 7 framework is a significant regulatory driver that expands emissions testing to a wider range of operating conditions. This forces a holistic redesign of the entire aftertreatment system to manage pollutants beyond just NOx, including ammonia and nitrous oxide. Commercial vehicle OEMs are most affected, responding by engineering more compact and efficient systems with integrated diesel particulate filters and ammonia slip catalysts.
Fleet operators are increasingly specifying complete, pre-validated aftertreatment modules from Tier 1 suppliers rather than purchasing individual components. This shift disrupts the traditional aftermarket parts channel, favoring suppliers who can offer fully integrated and warranted systems that minimize vehicle downtime. This procurement behavior is most prevalent in the logistics sectors of North America and Europe, where total cost of ownership is a primary concern.
Global Automotive Selective Catalytic Reduction System Market Segmentation
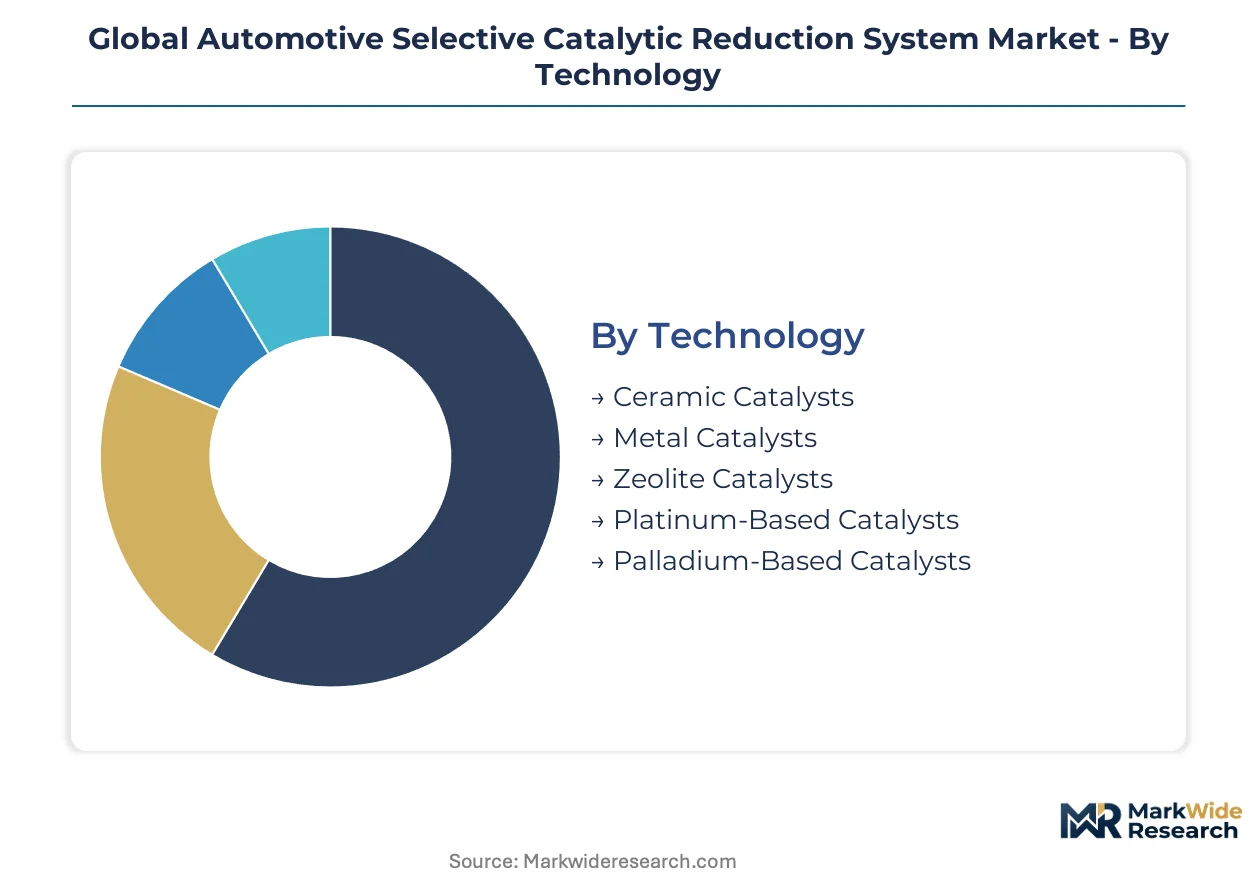
The segmentation of the global automotive selective catalytic reduction system market reveals distinct purchasing behaviors and technological priorities across various categories. Understanding these segments is critical for manufacturers to tailor product development and market strategies effectively.
Technology:
Buyers prioritize catalyst material composition to meet stringent NOx reduction targets under diverse operating conditions.
- Ceramic Catalysts:These foundational catalysts are typically composed of a porous ceramic substrate coated with active materials, offering a cost-effective solution for less demanding emission standards. Demand is stable in regions with moderate regulatory pressure.
- Metal Catalysts:Featuring metallic substrates, these catalysts provide enhanced thermal conductivity and mechanical robustness compared to ceramic variants, particularly beneficial in high-temperature exhaust environments. Commercial vehicle applications often integrate metal catalysts for durability.
- Zeolite Catalysts:Advanced zeolite catalysts utilize specific pore structures to achieve superior thermal durability and higher NOx conversion efficiency, especially at lower exhaust temperatures. Heavy-duty truck manufacturers in Europe and China are rapidly adopting these materials for Euro 7 and National VI compliance.
- Platinum-Based Catalysts:These catalysts incorporate platinum group metals, known for their high catalytic activity and stability across a broad temperature range, but are subject to significant input cost volatility. Passenger car applications previously relied heavily on platinum for emissions control.
- Palladium-Based Catalysts:Palladium offers an alternative to platinum, providing strong catalytic performance for NOx reduction and often used in conjunction with other precious metals to optimize cost and efficiency. Certain heavy-duty diesel engines integrate palladium for specific duty cycles.
Zeolite Catalysts leads on scale; Palladium-Based Catalysts leads on momentum.
Vehicle Type:
Vehicle type dictates the specific SCR system design and integration challenges, reflecting varying engine sizes and duty cycles.
- Light Commercial Vehicles:This segment includes vans and smaller trucks, where SCR systems are designed for compactness and efficiency, balancing performance with vehicle packaging constraints. European LCV manufacturers integrate SCR to meet Euro 6d and upcoming Euro 7 standards.
- Heavy-Duty Trucks:These vehicles represent the dominant application for SCR systems due to strict regulations for commercial transport and high mileage accumulation. US EPA and EU Euro VI standards drive significant SCR technology deployment in this segment.
- Passenger Cars:While diesel passenger car sales are declining in some regions, SCR systems are essential for remaining diesel models to comply with stringent emissions regulations. German automotive brands were early adopters of SCR in premium diesel cars.
- Buses:Urban and intercity buses utilize SCR technology to reduce NOx emissions, particularly important in densely populated areas for air quality improvement. Public transport authorities in major global cities mandate SCR-equipped buses.
- Off-Highway Vehicles:This category includes construction, agricultural, and mining equipment, where SCR integration addresses emissions from large diesel engines operating under demanding, variable load conditions. North American and European regulations are expanding to cover NRMM.
Heavy-Duty Trucks drive the largest volumes; Off-Highway Vehicles show the steepest expansion trajectory.
Aftermarket Channel:
The distribution model for replacement components influences accessibility and service quality for SCR system maintenance.
- Authorized Dealers:These channels provide genuine OEM parts and specialized diagnostic services, ensuring proper system function and warranty compliance. Fleet operators often prefer authorized dealers for their expertise and guaranteed parts.
- Independent Workshops:Offering competitive pricing and localized service, independent workshops cater to a broad base of vehicle owners, particularly for routine maintenance and non-warranty repairs. Small businesses and individual truck owners frequent these workshops.
- E-Commerce Platforms:Online platforms facilitate direct access to SCR components and consumables like AdBlue, offering convenience and potentially lower prices. Remote regions with limited physical distribution benefit from online availability.
- Fleet Operators:Large fleet operators often manage their own maintenance facilities, procuring SCR parts and AdBlue directly from manufacturers or specialized distributors for cost control and operational efficiency. Logistics companies maintain extensive in-house workshops.
- Specialty Distributors:These distributors focus on specific product categories or geographic regions, providing a comprehensive range of SCR components and technical support to workshops and smaller fleets. European distributors serve a dense network of repair shops.
Authorized Dealers secure substantial market share; E-Commerce Platforms are gaining traction fastest.
End User:
Position within the automotive value chain determines the procurement and integration needs for SCR systems, from initial manufacturing to ongoing maintenance.
- OEMs:Original Equipment Manufacturers integrate SCR systems directly into new vehicle production lines, requiring seamless supply chain coordination and adherence to strict engineering specifications. Global automotive brands partner with Tier 1 suppliers for complete SCR modules.
- Tier-1 Component Suppliers:These suppliers develop and manufacture complete SCR systems or major sub-assemblies, delivering them to OEMs for integration. Bosch GmbH and Faurecia SE are prominent Tier-1 suppliers in this market.
- Vehicle Assemblers:Companies that assemble vehicles from components supplied by various manufacturers also procure and install SCR systems. Regional vehicle assemblers often source from multiple Tier 1 suppliers.
- Retrofitters:Retrofitters modify older, in-service vehicles with SCR technology to enable compliance with updated emission standards, particularly in regions implementing stricter regulations. Indian and Brazilian markets present opportunities for retrofitting heavy-duty fleets.
- Fleet Maintenance Providers:These entities manage the ongoing service and repair of vehicle fleets, including the maintenance and replacement of SCR system components and reductant refilling. Large logistics companies utilize these providers to ensure vehicle uptime.
OEMs represent the largest purchasing block; Retrofitters are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive manufacturing base drives significant demand for selective catalytic reduction systems, influenced by stringent environmental mandates. The country's National VI emission standards compel widespread adoption across commercial vehicle fleets. This regulatory pressure positions China as a critical hub for SCR technology deployment and innovation.
China
China's heavy-duty truck sector drives substantial demand for advanced SCR systems. National VI emission standards mandate the integration of sophisticated aftertreatment technologies for all new commercial vehicles. Major automotive manufacturing hubs like the Yangtze River Delta actively develop and integrate these systems.
Germany
German commercial vehicle OEMs integrate SCR systems to comply with Europe's stringent Euro VI and impending Euro 7 emission standards. These regulations necessitate high-efficiency NOx reduction across diverse operating conditions. Automotive research centers in Stuttgart and Munich focus on optimizing SCR performance for both heavy-duty and niche passenger car applications.
United States
United States heavy-duty truck and off-highway vehicle segments require robust SCR systems to meet US EPA emission standards. The EPA's mandates for NOx reduction in commercial transport continue to drive technological advancements. Manufacturers in the Detroit automotive corridor and Midwest industrial heartland focus on durable and high-performing SCR solutions.
India
Indian commercial vehicle manufacturers are rapidly adopting SCR technology to adhere to Bharat Stage VI emission norms. Significant opportunities exist in retrofitting older heavy-duty truck fleets as emission controls tighten across the country. Automotive production centers in Chennai and Pune are expanding their capacity for SCR system integration.
Japan
Japanese commercial vehicle and bus manufacturers integrate SCR systems to comply with the country's strict emission standards and promote cleaner urban transport. The focus includes balancing NOx reduction with overall fuel efficiency in dense city environments. Major automotive companies around Tokyo and Nagoya continuously refine SCR technologies for domestic and export markets.
Global Automotive Selective Catalytic Reduction System Market Key Industry Players
Technology licensing and strategic partnerships dominate the current landscape, driven by the specialized nature of catalyst materials. The market structure features a mix of highly consolidated Tier 1 suppliers and more fragmented specialized catalyst producers. Strategic archetypes include integrated exhaust system providers, pure-play catalyst developers, and diversified industrial conglomerates. Capacity expansion in advanced zeolite catalyst production and portfolio diversification into alternative fuel compatibility are also prevalent competitive moves.
Specialists in complete exhaust system integration, Bosch GmbH and Faurecia SE, exemplify the Tier 1 supplier archetype, offering comprehensive aftertreatment solutions for global automotive platforms. Bosch GmbH, a German-based company, consistently invests in catalyst coating technology for cost-effective solutions. Faurecia SE, a French industrial group, focuses on optimizing performance for commercial vehicle OEMs through system-level integration. Tenneco Inc., an American corporation, represents a diversified player with a broad manufacturing footprint and an extensive aftermarket channel presence, servicing a wide range of vehicle types and leveraging its brands for market penetration. These entities collectively shape the competitive dynamics through their distinct operational models.
| Leading Market Players |
|---|
| Denso Corporation |
| Bosch GmbH |
| BASF SE |
| Faurecia SE |
| Tenneco Inc. |
| Johnson Matthey Plc |
| Continental AG |
| Umicore SA |
| Cummins Inc. |
| Others |
Cost & Logistics Intelligence
Platinum group metal pricing directly impacts the cost of selective catalytic reduction systems, influencing procurement decisions from Tier 1 suppliers to commercial vehicle OEMs.
Pricing Analysis
Input cost pass-through for platinum group metals directly influences SCR system pricing for Tier 1 suppliers. The dominant pricing model for OEMs involves contract-based long-term offtake agreements, securing consistent supply and predictable costs. Price differentiation stems from catalyst performance and the volume scale of procurement. Pricing softness stems from the increasing substitution of high-cost platinum group metals with advanced zeolite catalysts. OEMs are the most price-sensitive buyers, meticulously evaluating total system cost, while fleet operators balance cost with compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with specialized chemical producers controlling advanced zeolite catalyst intellectual property. Geographic supply concentrates in China for manufacturing and South Africa for platinum group metals. The market depends on raw materials like platinum group metals, automotive-grade urea, and specialized zeolite precursors. Commodity price volatility for platinum group metals represents a significant structural supply chain risk. Distribution runs through direct OEM supply channels and a fragmented aftermarket network comprising authorized dealers and specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive SCR market presents a geographic-arbitrage opportunity, driven by varying emission standard timelines and manufacturing cost structures between China and Europe.
For Market Incumbents:Acquire specialized intellectual property in advanced zeolite catalyst formulations to counteract margin pressure from platinum group metal substitution. Invest heavily in R&D for next-generation catalyst materials and coating technologies to meet stringent Euro 7 and National VI standards. Deepen system-level integration capabilities to offer complete aftertreatment modules, mitigating the threat from emerging catalyst developers. Strengthen aftermarket channel control through certified service networks to ensure long-term compliance and customer loyalty.
For New Entrants and Emerging Players:Fleet operators in developing regions, particularly in India and Brazil, represent a significant underserved buyer archetype for SCR retrofit solutions. Target the off-highway vehicle segment in North America with robust, cost-effective SCR systems designed for demanding operational conditions. Focus on developing retrofit kits for older heavy-duty truck fleets in markets implementing stricter, Euro-equivalent emission standards. A go-to-market angle emphasizing ease of installation and local service support will appeal to independent workshops and smaller fleet operators.
For Investors and Strategic Acquirers:Consolidation pressure builds where material science expertise and manufacturing scale create high barriers to entry for catalyst production. The long-term viability of SCR technology remains strong for diesel engines over the next decade, particularly in heavy-duty transport. Target pure-play catalyst developers with proprietary zeolite technology or specialized aftertreatment system integrators. The signal to watch is the pace of alternative fuel adoption in heavy-duty transport, which could shift long-term demand dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion: Advanced Zeolite Catalyst Production | Ensures supply for Euro 7 and National VI compliance in heavy-duty trucks. |
| Platform Standardization: Aftertreatment System Modules | Reduces OEM integration costs and accelerates deployment across vehicle types. |
| Strategic Partnership: Alternative Fuel Compatibility | Validates SCR systems for low-carbon fuels like HVO, expanding market reach. |
| Acquisition of Specialist Firm: Diagnostic Software | Enhances system-level integration and aftermarket service capabilities for complex SCR units. |
| Distribution Channel Expansion: Aftermarket Retrofit Kits | Captures growth in India and Brazil for older heavy-duty truck fleets. |
Research Approach
Multiple input streams — primary interviews, proprietary databases, and regulatory filings — were reconciled to build a robust market perspective. Primary data collection involved conversations with Tier 1 procurement leads, commercial vehicle OEM engineers, fleet maintenance managers, and catalyst R&D directors. Secondary validation drew from EPA reports, EU Euro standards documentation, China's MEE publications, and industry association statistics. This approach facilitated bottom-up and top-down triangulation to ensure comprehensive data coverage.
Data-stream reconciliation across primary and secondary sources informed the analytical framework used for market projections over the projection horizon. The quantitative model segmented the market by technology, vehicle type, aftermarket channel, end-user, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected regulatory impacts. Key industry-specific forecast inputs included diesel engine production volumes and emission standard implementation timelines across major economies.
Underlying measurement precision varies by segment; heavy-duty truck and OEM procurement data carry tighter precision than aftermarket repair trends. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption rates. Geopolitical supply risks for platinum group metals and the pace of electric vehicle adoption in commercial transport represent specific risk factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Automotive Tonneau Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Automotive Carbon Canister Market