
 Japan Automotive Parts Zinc Die Casting Market | 2026-2036
Japan Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Parts Zinc Die Casting Market Foresight
Buyer concentration among Japan's domestic OEMs is decoupling from traditional keiretsu supply structures as electrification programs diversify sourcing criteria. Dynacast leverages its precision casting footprint to serve hybrid transmission programs across multiple Japanese automakers. Sandhar Technologies Ltd anchors its position through dedicated engineering centers focused on lightweight chassis components. Continental Castings LLC competes on high-volume engine part contracts where tooling amortization drives total cost economics.
Japan automotive parts zinc die casting involves injecting zinc alloys at pressures exceeding 10 MPa into hardened steel molds to produce complex, thin-walled metal components with dimensional tolerances near 0.05 mm, primarily serving vehicle weight reduction and corrosion resistance requirements in powertrain and structural assemblies. Engine components remain the largest product type category, though transmission cases are gaining share as hybrid architectures multiply gearset complexity and housing demand. Among material grades, alloyed zinc formulations dominate mass production due to superior creep resistance at elevated under-hood temperatures, while coated zinc variants capture premium positioning where extended salt-spray performance is specified.
METI enforces energy efficiency benchmarks and industrial decarbonization targets that directly shape foundry investment decisions and alloy selection protocols across Japan's automotive supply base. JIS standards govern dimensional precision and material certification, creating compliance thresholds that filter out non-specialized suppliers from Tier-1 qualification pools. Stakeholders must monitor how battery electric vehicle platform architectures alter load-bearing requirements and whether zinc die casting retains its cost position against aluminum and polymer alternatives in next-generation chassis designs.
Market Dynamics
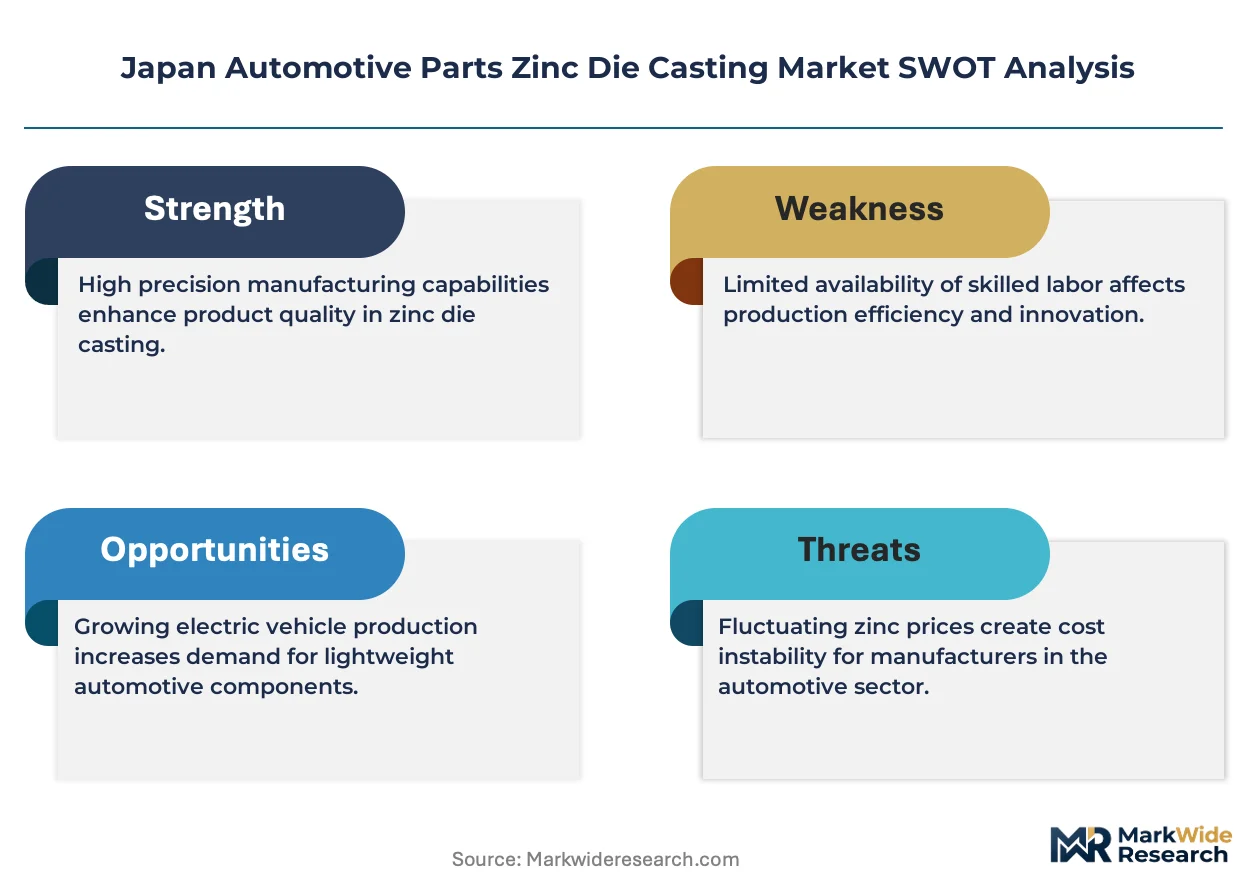
Japan's automotive zinc die casting sector faces structural recalibration as METI's vehicle weight reduction mandates force OEMs to reassess material selection criteria across powertrain architectures. The tension between hybrid system complexity and lightweighting imperatives is compressing supplier qualification timelines while elevating precision requirements for transmission housings and structural nodes.
Growth Catalysts
- Hybrid Powertrain Expansion:Dual-motor and multi-speed hybrid architectures multiply gearset housing demand, pulling precision zinc castings into transmission case applications previously served by aluminum gravity die processes.
- METI Decarbonization Roadmap:Energy efficiency benchmarks and industrial emissions targets channel foundry investment toward high-pressure die casting cells with superior material utilization rates versus conventional sand casting.
- Kanto Corridor Cluster Effects:Proximity between Tier-1 engineering centers in Tokyo, Kanagawa, and Saitama prefectures compresses logistics costs and accelerates prototype-to-production cycles for chassis component programs.
Market Restraints
- Zinc Alloy Price Volatility:London Metal Exchange zinc price swings and concentrated smelter supply from Chinese producers inject margin instability into fixed-price OEM contracts with annual renegotiation windows.
- Aluminum Substitution Pressure:Thixomolding advances and recycled aluminum alloy cost reductions threaten zinc's position in non-structural engine brackets and small housing applications where corrosion resistance is secondary.
- Keiretsu Supply Lock-In:Historical cross-shareholding arrangements between Japanese OEMs and incumbent casting suppliers erect qualification barriers for non-traditional entrants despite technical parity.
Strategic Opportunities
- Chassis Electrification White Space:Battery electric vehicle platforms with distributed motor architectures create demand for new zinc cast structural nodes and mounting brackets with integrated thermal management passages.
- JIS Certification Arbitrage:Specialized suppliers achieving JIS H 5301 precision grade certification can capture premium positioning in safety-critical brake and steering component segments with extended contract durations.
- Multi-Material Assembly Convergence:Zinc-aluminum hybrid casting techniques and insert molding with polymer composites enable weight-optimized subassemblies that single-material processes cannot replicate.
Industry Challenges
- Tooling Amortization Compression:Accelerated platform refresh cycles and declining model production volumes strain the economics of hardened steel mold investments requiring 200,000+ shot lifespans to achieve payback.
- Process Engineer Scarcity:Retiring veteran die casting technicians and insufficient vocational pipeline output create bottlenecks in cell commissioning, process window optimization, and defect root-cause analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Parts Zinc Die Casting Market |
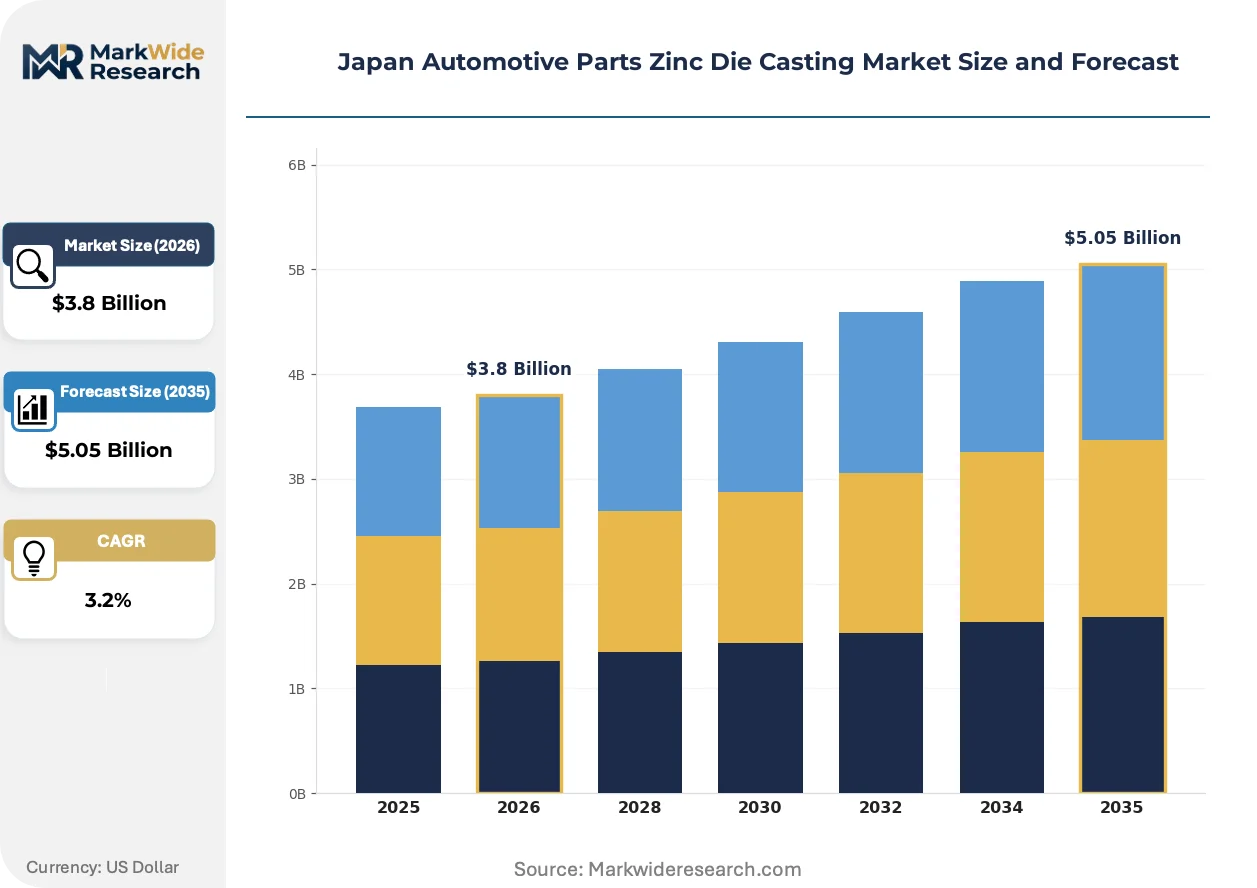
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.05 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Cases, Chassis Parts, Fasteners Material Grade: High Purity Zinc, Alloyed Zinc, Coated Zinc, Others End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Dealerships Manufacturing Stage: Prototyping, Mass Production, Secondary Operations, Finishing |
| Companies Covered | Dynacast, Continental Castings LLC, Ashok Minda Group, Kemlows Die Casting Products Ltd, Carteret Die Casting Corporation, Sandhar Technologies Ltd, Brillcast Manufacturing LLC, Chamundi Die Cast Pvt Ltd, Pace Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Parts Zinc Die Casting Market Shifts & Advancements
Active transformation across Japan's automotive zinc die casting base centers on precision enhancement, regulatory compliance integration, and supply chain compression. These shifts are redefining competitive differentiation beyond traditional cost-per-kilogram metrics.
Thin-wall zinc die casting technology is consolidating around vacuum-assisted and squeeze-casting process variants that achieve wall thickness below 1.2 millimeters in transmission case applications. Tier-1 suppliers in Kanagawa prefecture are adopting these cells for hybrid gearset housings where dimensional stability under thermal cycling is non-negotiable. The technology is consolidating supplier tiers by eliminating secondary machining operations that previously justified separate Tier-2 finishing relationships.
METI's 2030 industrial decarbonization targets and associated energy efficiency benchmarks are mandating foundry investment in electric melting furnaces and waste heat recovery systems. Compliance documentation requirements now extend through Tier-2 material suppliers, forcing alloy certification traceability back to smelter origin. Small and mid-size casting operations in Saitama prefecture face disproportionate compliance costs relative to integrated multi-site producers with dedicated sustainability engineering staff.
Buyer engineering teams are embedding zinc die casting specialists earlier in platform development cycles, collapsing traditional sequential handoffs between design release and supplier process validation. This concurrent engineering model replaces arm's-length specification exchanges with co-located technical teams at OEM technical centers in Tokyo. The shift is most visible in hybrid powertrain programs where housing complexity demands real-time design-for-manufacturability feedback loops.
Japan Automotive Parts Zinc Die Casting Market Segmentation
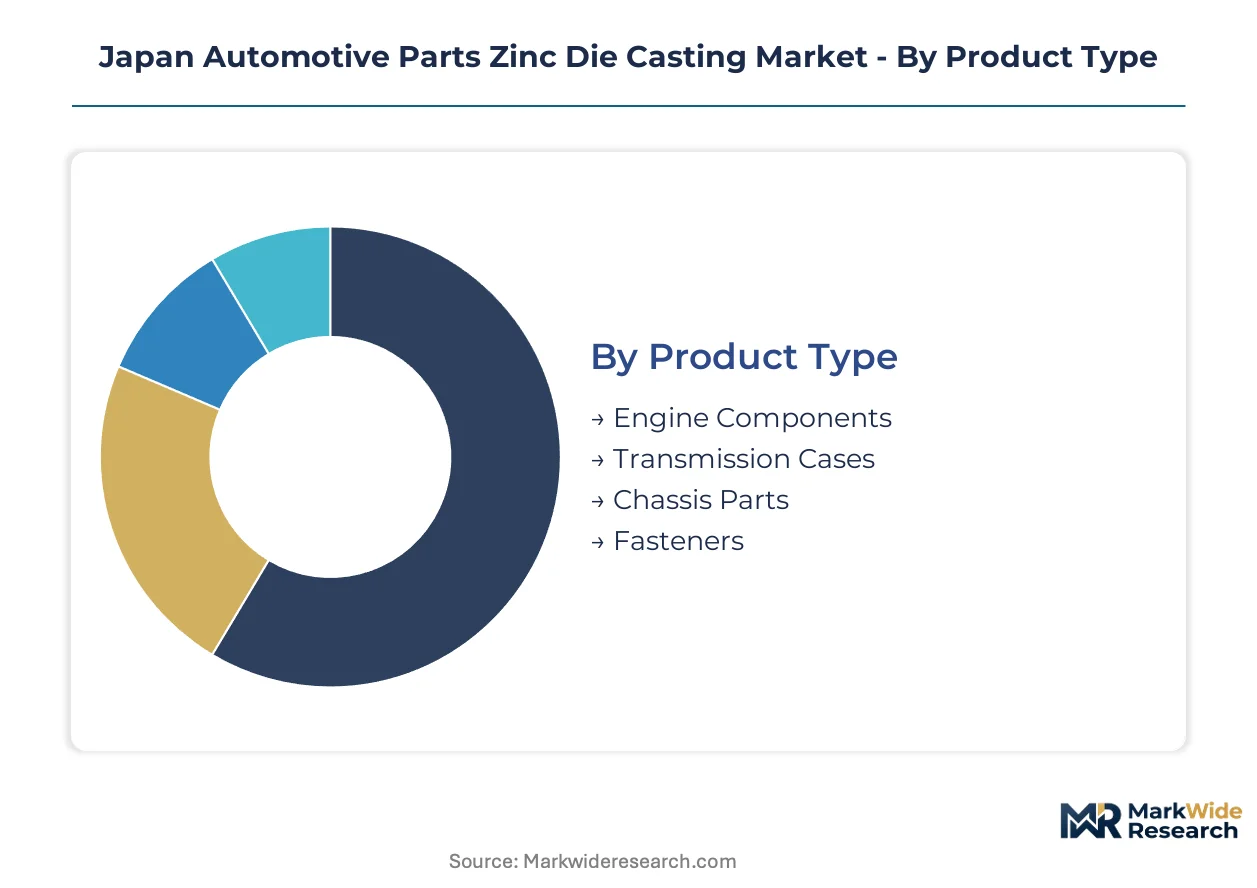
Segmentation in Japan's automotive zinc die casting market reveals how component function, material specification, and supply chain position determine technical requirements and commercial terms. Each dimension carries distinct JIS compliance obligations and tooling investment profiles that shape supplier qualification.
Product Type:
Integration depth varies sharply across product categories, with some segments serving as standalone assemblies while others embed within larger subsystems requiring multi-material joining.
- Engine Components:Cylinder head covers, timing chain housings, and oil pump bodies demand creep-resistant zinc alloys rated for continuous 150°C under-hood exposure. Demand concentrates among hybrid powertrain programs in Kanagawa prefecture where thermal management complexity elevates precision requirements.
- Transmission Cases:Multi-speed hybrid gearset housings require vacuum-assisted thin-wall casting below 1.2 mm to achieve weight targets without sacrificing dimensional stability under cyclic loading. Kanto-based Tier-1 suppliers are expanding dedicated cell capacity for these programs.
- Chassis Parts:Structural nodes and suspension brackets integrate crash management functions with mounting points for battery packs in electrified platforms.
- Fasteners:Clips, brackets, and hardware serve secondary attachment roles with lower structural certification thresholds.
Engine Components leads volumes today; Transmission Cases is gaining share fastest.
Material Grade:
Cost tier differentiation separates premium-certified formulations from commodity-grade alternatives, with pricing spreads reflecting smelter traceability and batch testing documentation.
- Alloyed Zinc:ZA-8 and ZA-12 formulations with aluminum and copper additions deliver superior creep resistance for powertrain applications above 120°C. Mass production lines in Saitama prefecture favor these grades for their predictable shrinkage behavior and reduced porosity in high-pressure cells.
- Coated Zinc:Chromate and organic polymer coatings extend salt-spray performance beyond 500 hours for brake and steering components exposed to road de-icing chemicals. Premium positioning commands extended contract durations from safety-critical Tier-1 programs.
- High Purity Zinc:SHG-grade material serves decorative interior applications where surface finish quality outweighs mechanical loading requirements.
- Others:Experimental formulations including rare-earth modified alloys remain limited to prototype volumes pending JIS certification.
Alloyed Zinc leads volumes today; Coated Zinc is expanding most quickly.
End User:
Customer type determines specification authority, with direct OEM relationships carrying design control while aftermarket channels prioritize inventory velocity over technical customization.
- Tier-1 Suppliers:Denso, Aisin, and JTEKT subsidiaries specify zinc castings for integration into larger assemblies, maintaining direct engineering relationships with foundries for concurrent design validation.
- OEMs:Toyota, Honda, and Nissan procurement divisions source transmission cases and structural nodes directly for platform-commonality programs, bypassing Tier-1 markup on critical weight-reduction components.
- Aftermarket Suppliers:Independent distributors service collision repair and classic restoration demand with reverse-engineered equivalents lacking original alloy certification.
- Dealerships:Authorized retail channels handle warranty replacement parts with captive sourcing from OEM-approved foundries.
Tier-1 Suppliers leads volumes today; OEMs is climbing the fastest.
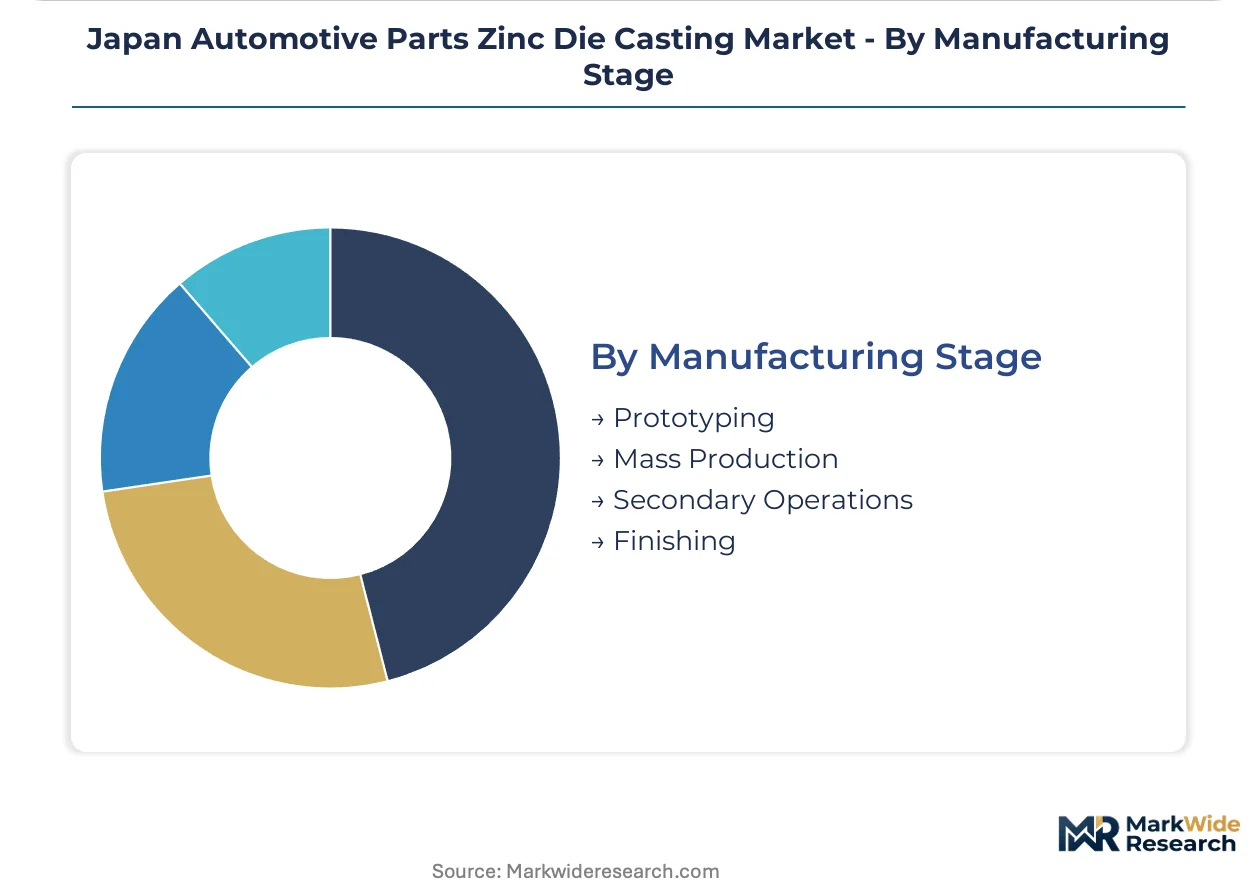
Manufacturing Stage:
Volume concentration and margin structure diverge across production phases, with mass production cells amortizing tooling over hundreds of thousands of shots while prototyping commands premium pricing for rapid iteration.
- Mass Production:Hardened steel molds with 200,000+ shot lifespans achieve unit economics only at volumes exceeding 50,000 annual pieces, concentrating investment among integrated multi-site producers.
- Secondary Operations:CNC machining, thread forming, and surface finishing add dimensional precision beyond as-cast tolerances, with some Tier-1 suppliers bringing these capabilities in-house to compress lead times.
- Prototyping:Soft-tool aluminum molds and 3D-printed inserts enable design validation within four-week cycles for hybrid powertrain housing development.
- Finishing:Passivation, painting, and assembly complete the value chain with environmental compliance costs disproportionately burdening smaller Saitama-based operations.
Mass Production leads volumes today; Secondary Operations is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's die casting workforce concentrates in the Kanto industrial corridor, where generations of precision metalworkers anchor transmission housing and chassis component production for domestic OEMs.
Kanto Region
Tokyo, Kanagawa, and Saitama prefectures host the densest concentration of zinc die casting capacity, serving Toyota and Honda hybrid powertrain programs. METI's decarbonization roadmap mandates foundry energy efficiency upgrades across this corridor. Kawasaki and Yokohama industrial zones are consolidating thin-wall casting cells for multi-speed transmission cases.
Kansai Region
Osaka and Kyoto prefectures maintain legacy engine component foundries supplying piston housings and timing covers. JIS H 5301 certification requirements filter supplier pools for safety-critical brake and steering castings. Sakai industrial harbor clusters are retrofitting electric melting furnaces to meet METI 2030 emissions benchmarks.
Chubu Region
Aichi prefecture anchors Nagoya-centered automotive production, with die casters integrated into Toyota keiretsu supply structures. Hybrid system complexity is forcing concurrent engineering co-location at OEM technical centers. Toyohashi and Okazaki foundry zones face tooling amortization pressure from shortened platform lifecycles.
Kyushu Region
Fukuoka and Oita prefectures host secondary suppliers serving Tier-1 assembly plants with lower-complexity fasteners and brackets. Process engineer scarcity constrains cell commissioning and defect analysis capabilities. Kitakyushu industrial zones are experimenting with zinc-aluminum hybrid casting for battery electric vehicle structural nodes.
Tohoku Region
Miyagi and Fukushima prefectures operate smaller foundry operations focused on prototype-to-production transitions for new hybrid architectures. METI regional revitalization incentives channel investment toward advanced casting simulation capabilities. Sendai technical institutes are training replacement technicians for retiring veteran die casting specialists.
Japan Automotive Parts Zinc Die Casting Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's automotive zinc die casting base, creating a tiered structure where integration depth determines contract access. Large multi-site producers with captive alloy supply and in-house finishing command mass production economics, while mid-size specialists capture premium positioning through JIS precision certification. Three archetypes dominate: integrated material-to-component producers, engineering-centric precision specialists, and regional foundry clusters serving keiretsu captive demand. Competitive moves center on concurrent engineering partnerships with OEM technical centers and multi-material assembly capabilities combining zinc with aluminum and polymer composites.
Among precision-focused specialists, Dynacast occupies a position exemplifying global process standardization applied to Japanese hybrid transmission programs. Sandhar Technologies Ltd represents the engineering-center archetype, anchoring lightweight chassis development through dedicated technical facilities. Continental Castings LLC sits within the high-volume engine component tier, where tooling amortization economics dominate supplier selection criteria.
| Leading Market Players |
|---|
| Dynacast |
| Continental Castings LLC |
| Ashok Minda Group |
| Kemlows Die Casting Products Ltd |
| Carteret Die Casting Corporation |
| Sandhar Technologies Ltd |
| Brillcast Manufacturing LLC |
| Chamundi Die Cast Pvt Ltd |
| Pace Industries |
| Others |
Supply & Pricing Matrix
METI's 2030 industrial decarbonization targets gate qualified supply access and premium-tier pricing for Tier-1 automotive zinc die casting programs. Foundries achieving documented energy efficiency compliance capture extended contract durations from hybrid powertrain buyers, while non-compliant operators face margin compression from exclusion.
Pricing Analysis
Bundled engineering-services contracts dominate hybrid transmission case procurement, while unbundled commodity transactions persist for standard engine brackets. Three-tier pricing structure across JIS H 5301 precision-certified, alloy-grade standard, and uncertified economy levels reflects smelter traceability and batch documentation depth. Pricing pressure stems from London Metal Exchange zinc volatility transmitted through annual renegotiation windows. Tier-1 suppliers with captive finishing operations exhibit lowest price sensitivity; small Saitama-based foundries face acute margin vulnerability.
Supply Chain Analysis
Direct-to-OEM channels handle Toyota and Honda platform-commonality demand for transmission cases, while Tier-1 integrators like Denso and Aisin manage engine component procurement. Raw material supply draws from Chinese smelter concentration for zinc concentrate, domestic Japanese alloy formulation, and South Korean coating chemical inputs. Single-source vulnerability runs through Kanto corridor logistics nodes serving concurrent engineering partnerships. Distribution runs through keiretsu-captive relationships with limited spot-market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive zinc die casting market functions as a stable compounder, with METI regulatory compliance creating predictable replacement demand for certified capacity.
For Market Incumbents: Anchor position through JIS H 5301 precision-grade certification investment and backward integration into alloy formulation. Aluminum thixomolding substitution in non-structural brackets threatens legacy engine component volumes. Concurrent engineering co-location at OEM technical centers secures platform lock-in against emerging competitors. For New Entrants and Emerging Players: Begin with battery electric vehicle structural node prototyping for Kyushu-based Tier-2 suppliers facing process engineer scarcity. Chassis electrification white space offers lowest keiretsu penetration. JIS certification arbitrage in safety-critical brake components provides premium positioning entry. For Investors and Strategic Acquirers: Roll-up economics work for mid-size precision specialists because tooling amortization compression favors multi-site producers with shared sustainability engineering staff. Five-to-ten year viability rests on hybrid powertrain persistence and zinc-aluminum hybrid casting adoption. Monitor battery electric vehicle platform load-bearing specifications for material substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| JIS H 5301 Precision Certification Investment | Unlocks safety-critical brake and steering component contracts with extended durations from Tier-1 suppliers. |
| Concurrent Engineering Partnership | Collapses prototype-to-production cycles for hybrid transmission housing programs at Toyota technical centers. |
| Electric Melting Furnace Retrofit | Satisfies METI 2030 decarbonization benchmarks mandatory for Tier-1 supplier qualification pools. |
| Thin-Wall Vacuum Casting Cell Deployment | Achieves sub-1.2 mm transmission case walls demanded by multi-speed hybrid gearset architectures. |
| Zinc-Aluminum Hybrid Casting Development | Enables weight-optimized battery electric vehicle structural nodes beyond single-material process limits. |
Research Methodology
Coverage spans Kanto, Kansai, Chubu, Kyushu, and Tohoku regions, with primary inputs from each. Foundry operations directors, Tier-1 supplier procurement managers, OEM platform engineers, and METI industrial policy officials contributed structured interviews. Secondary validation drew from JIS standard documentation, METI decarbonization roadmap publications, vehicle production databases, and customs trade records. Bottom-up capacity aggregation and top-down demand modeling triangulated volume estimates.
Rate-of-change decomposition isolated hybrid powertrain penetration, platform weight reduction mandates, and foundry energy efficiency compliance as core drivers across the projection horizon. Segmentation modeling incorporated product type, material grade, end user category, and manufacturing stage dimensions. CAGRs derived from regression analysis against historical production volumes and OEM platform rollout schedules. Zinc alloy price volatility and keiretsu supply structure rigidity served as scenario sensitivity inputs.
Several conditions sit outside the modeled scope, including unannounced battery electric vehicle platform architectures and potential aluminum substitution acceleration. Forecasts reflect assumptions regarding METI regulatory timeline adherence and hybrid powertrain persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Propeller Shaft Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
External Combustion Engine Market