
 Automotive Wheel Speed Sensor Tone Ring Market | 2026-2036
Automotive Wheel Speed Sensor Tone Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Speed Sensor Tone Ring Market Insights
Aftermarket distribution channels is reconfiguring as digital procurement platforms and direct tier-1 contracts displace traditional wholesale intermediaries. Robert Bosch GmbH leverages its captive sensor-to-ring integration to control specification flows across multiple OEM programs. Continental AG anchors European supply through in-house stamping and magnetic encoding capabilities. ZF Friedrichshafen AG competes by bundling tone rings within complete axle module assemblies, reducing customer sourcing complexity.
An automotive wheel speed sensor tone ring is a circumferential encoder component, typically ferromagnetic steel or polymer-bonded composite, with precisely machined teeth or magnetic poles that modulate sensor output as the wheel rotates; it translates mechanical rotation into digital pulse trains for anti-lock braking and stability control systems. Magnetic and Hall Effect technologies dominate current OEM specifications due to proven performance in contaminated environments, while optical variants remain confined to specialty motorsport applications where resolution demands override cost constraints. Metallic tone rings retain volume leadership in heavy trucks where thermal and mechanical loads exceed polymer limits, though composite formulations gain ground in passenger vehicles seeking unsprung mass reduction.
Federal Motor Vehicle Safety Standard 126 mandates electronic stability control on all US light vehicles, directly embedding tone ring performance into federal compliance testing administered by NHTSA. ECE R13 harmonizes braking system requirements across UN member states, creating a transnational specification ceiling that shapes supplier R&D priorities. Stakeholders must monitor the trajectory of China's GB/T vehicle safety standards and the EU's evolving type-approval frameworks, as divergence between these regimes would fragment test protocols and complicate platform engineering decisions for multinational programs.
Market Dynamics
Magnetic encoder technology is virtualizing the interface between tone rings and sensor electronics, collapsing the traditional mechanical-to-electrical boundary that once required discrete component sourcing from separate supplier tiers.
Growth Catalysts
- ABS and ESC Mandates:Federal Motor Vehicle Safety Standard 126 requires electronic stability control on all US light vehicles, embedding tone ring performance into federal compliance testing administered by NHTSA.
- China's NMPA Standards:The National Medical Products Administration's vehicle safety protocols tighten material specifications and performance thresholds for braking system components in domestic production.
- Unsprung Mass Reduction:Polymer-bonded composite formulations displace ferromagnetic steel in passenger vehicle applications, enabling lighter wheel assemblies without sacrificing magnetic field strength.
Market Restraints
- Neodymium Price Volatility:Rare earth magnet input costs fluctuate with Chinese export quota policies, compressing margins for magnetic encoder suppliers dependent on consistent material pricing.
- German Supply Concentration:Tier-1 stamping and magnetic encoding capabilities cluster along the Stuttgart-Munich engineering corridor, creating single-source vulnerability for European OEM programs.
- Optical Encoder Substitution Ceiling:Hall Effect and magnetic technologies dominate contaminated environments, blocking optical variants from expanding beyond motorsport niche applications where resolution demands override cost constraints.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for automotive component manufacturing attract tone ring suppliers to establish localized stamping and encoding operations near Chennai and Pune assembly plants.
- Axle Module Integration:Complete wheel-end assemblies bundle tone rings with bearings and sensors, reducing OEM sourcing complexity and locking in specification control for integrated suppliers.
- Digital Procurement Platforms:Direct tier-1 contracts and B2B marketplaces displace traditional wholesale intermediaries in aftermarket distribution, compressing channel margins and accelerating price discovery.
Industry Challenges
- Magnetic Calibration Expertise:Precision encoding requires specialized technicians capable of maintaining pole-to-pole consistency within micrometer tolerances, constraining workforce scalability for capacity expansion.
- Dual Certification Burden:Suppliers must simultaneously satisfy ECE R13 braking harmonization and China's evolving GB/T vehicle safety standards, fragmenting test protocols and complicating platform engineering for multinational programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Speed Sensor Tone Ring Market |
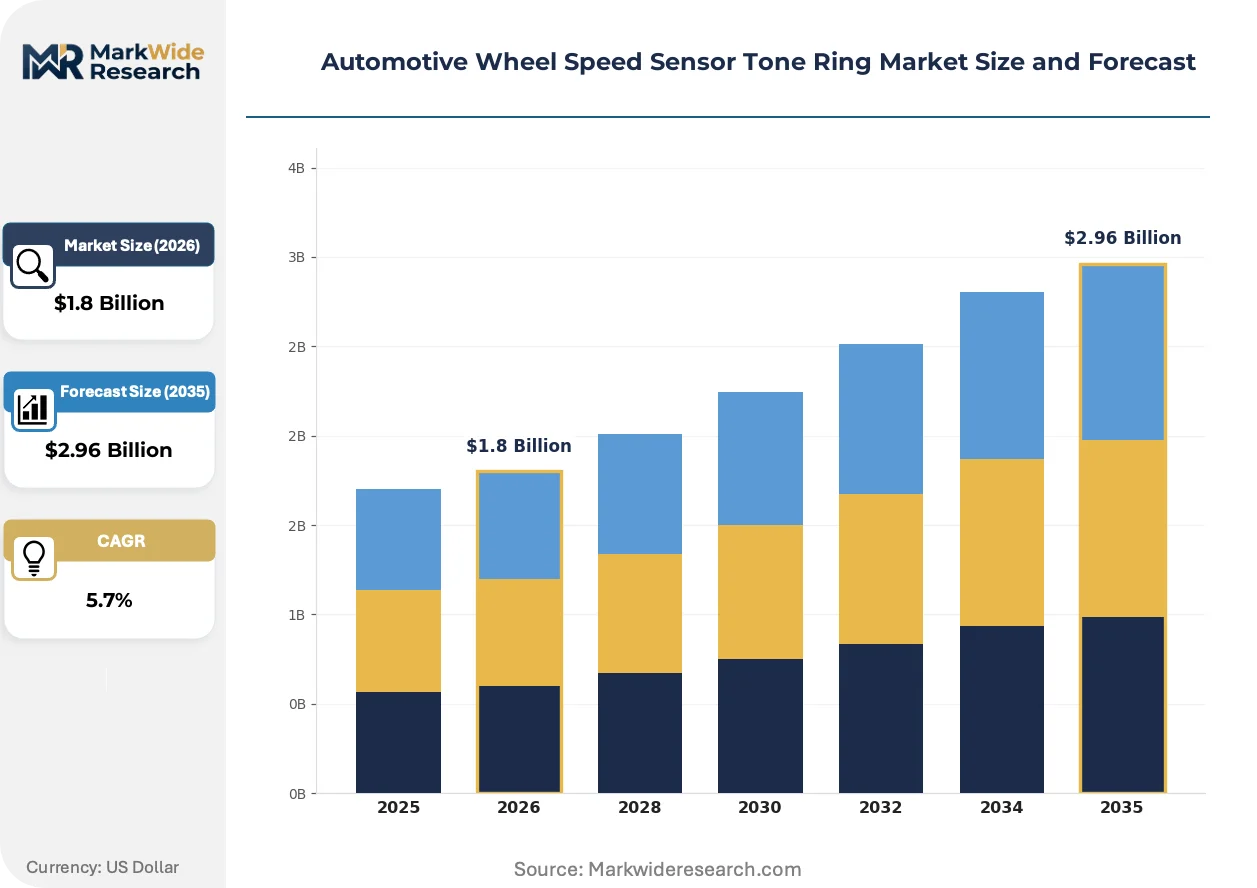
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic, Non-metallic, Composite, Hybrid Technology: Magnetic, Hall Effect, Inductive, Optical, Capacitive Application: Passenger Vehicles, Light Commercial Vehicles, Heavy Trucks, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, ZF Friedrichshafen AG, HELLA GmbH & Co. KGaA, TE Connectivity, NXP Semiconductors, Melexis, Sensata Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Speed Sensor Tone Ring Market Trends and Innovations
Digital pulse train generation is migrating from passive ferromagnetic rings to active semiconductor-integrated modules, collapsing the historical separation between mechanical encoders and electronic signal conditioning.
Polymer-bonded ferrite composites are virtualizing the traditional steel stamping workflow by enabling injection-molded tone rings with embedded magnetic domains. Passenger vehicle OEMs in Germany and Japan adopt these formulations to achieve unsprung mass targets. The technology is virtualizing supplier relationships by allowing sensor manufacturers to specify ring magnetic properties directly rather than delegating to discrete metalforming vendors.
ECE R13 harmonizes braking system requirements across UN member states, creating a transnational specification ceiling that shapes supplier R&D priorities. Component manufacturers must design for the strictest national interpretation rather than optimizing for regional variance. Heavy truck programs face the steepest compliance burden, as ECE R13's load-specific provisions require validated tone ring performance across wider temperature and contamination ranges than passenger car equivalents.
Fleet operators compress replacement cycles for wheel speed sensors as predictive maintenance platforms flag degradation patterns before ABS fault codes trigger. Digital procurement platforms capture this demand shift by offering real-time inventory matching against vehicle-specific tone ring specifications. North American aftermarket distributors report the fastest channel migration, where direct tier-1 contracts now bypass traditional jobber networks for high-volume fleet accounts.
Automotive Wheel Speed Sensor Tone Ring Market Segmentation
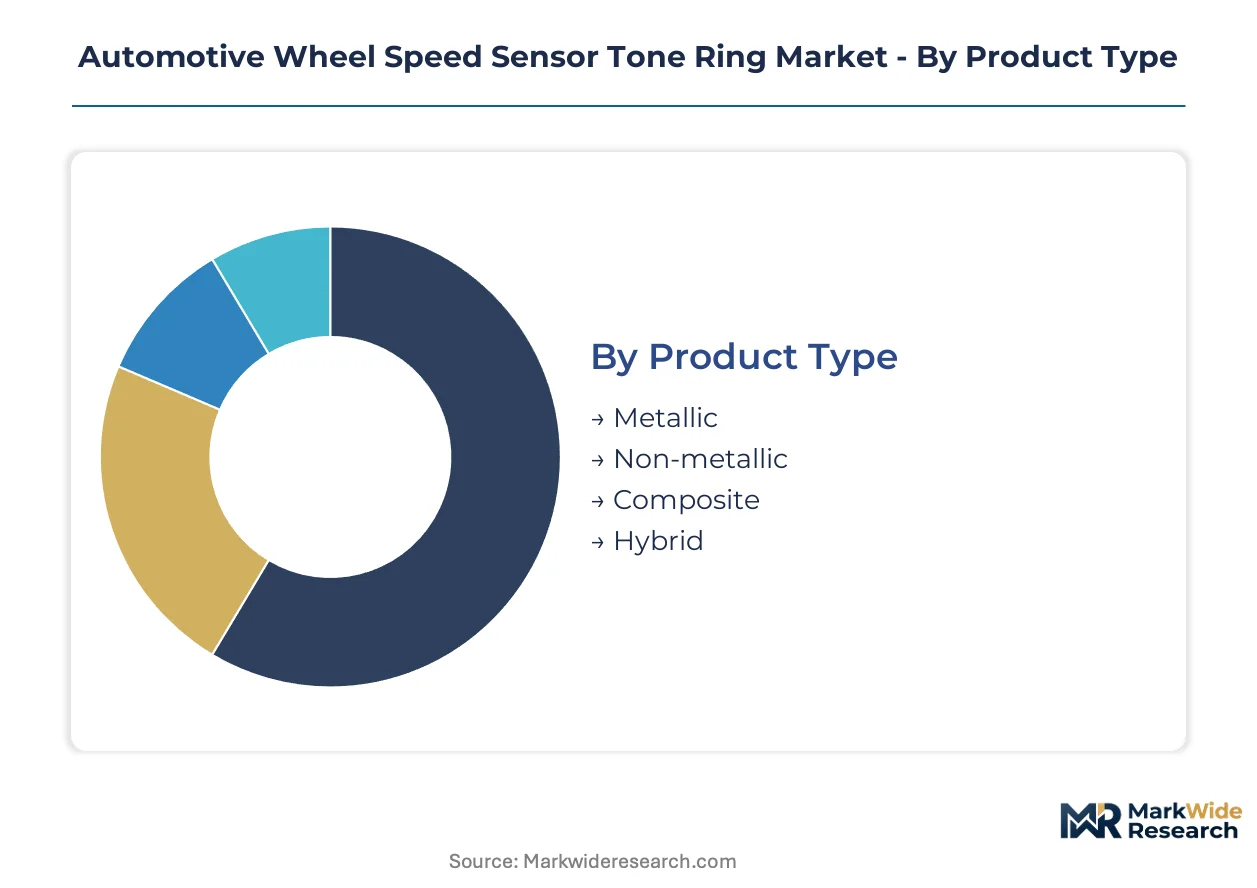
Tone ring procurement patterns diverge sharply across material technologies and supply chain tiers, with OEM specification power concentrating around integrated sensor-ring modules while aftermarket channels fragment across discrete component sourcing. Understanding these segment boundaries reveals where supplier margin pools accumulate and where price compression threatens incumbent positioning.
Product Type:
Mature stamping workflows anchor metallic production while emerging polymer formulations recalibrate unsprung mass engineering targets across passenger vehicle platforms.
- Metallic:Ferromagnetic steel rings with precision-machined teeth dominate heavy truck applications where thermal cycling and mechanical shock exceed polymer tolerance limits. Demand clusters in Germany's Stuttgart-Munich engineering corridor and China's eastern manufacturing belt near heavy vehicle assembly plants, with ECE R13 braking harmonization mandating validated performance across wider temperature ranges than passenger car equivalents.
- Non-metallic:Engineering-grade polymers reduce rotational inertia in passenger wheel assemblies without compromising magnetic field modulation capability. Japanese and German OEMs specify these formulations aggressively to meet chassis mass targets, though material qualification cycles extend platform development timelines compared to proven steel alternatives.
- Composite:Polymer-bonded ferrite blends enable injection-molded production workflows that collapse traditional metalforming supplier relationships. Sensor manufacturers now specify magnetic properties directly rather than delegating to discrete stamping vendors.
- Hybrid:Multi-material constructions combine metallic structural cores with polymer magnetic encoding layers, bridging performance gaps in light commercial vehicle segments where load variability complicates material selection.
Metallic tone rings retain volume leadership; composite formulations hold the steepest expansion curve as polymer-bonded ferrite virtualizes supplier relationships.
Technology:
Cost tiers separate proven magnetic architectures from emerging capacitive alternatives still seeking contamination-resistance validation.
- Magnetic:Passive ferromagnetic rings modulate sensor output through reluctance variation, dominating OEM specifications where cost minimization outweighs resolution demands. Hall Effect sensor pairing creates standardized module architectures across multiple vehicle programs.
- Hall Effect:Semiconductor-integrated sensors with active signal conditioning embed directly into wheel hub modules, collapsing historical separation between mechanical encoders and electronic processing. ZF Friedrichshafen bundles these within complete axle assemblies to reduce customer sourcing complexity.
- Inductive:Eddy-current sensing tolerates wider air-gap variation than magnetic alternatives, finding application in heavy truck wheel ends where bearing wear and suspension travel complicate sensor positioning consistency.
- Optical:Photoelectric encoding delivers resolution advantages confined to motorsport niche applications where trackside contamination control overrides cost constraints. NHTSA compliance testing for FMVSS 126 stability control mandates excludes optical variants from volume light vehicle programs.
- Capacitive:Emerging electrode architectures sense rotation through dielectric variation, promising immunity to metallic debris contamination that plagues magnetic sensors in mining and construction vehicle deployments.
Hall Effect modules command premium positioning through integration depth; capacitive sensing gains share fastest in specialty off-highway segments.
Application:
Volume concentration in passenger vehicles contrasts with margin intensity in heavy truck programs where regulatory load-specific provisions multiply certification burden.
- Passenger Vehicles:Unsprung mass reduction targets drive polymer composite specification across German and Japanese OEM platforms. China's NMPA vehicle safety standards tighten material and performance thresholds for domestic production, fragmenting test protocols for multinational programs.
- Light Commercial Vehicles:Hybrid material constructions balance payload capacity with chassis weight targets, with India's PLI scheme attracting localized stamping operations near Chennai and Pune assembly plants.
- Heavy Trucks:ECE R13 harmonization mandates validated tone ring performance across contamination and temperature ranges exceeding passenger car requirements. Metallic rings retain exclusive specification due to thermal and mechanical load tolerance.
- Specialty Vehicles:Motorsport and off-highway applications tolerate optical encoder costs where resolution demands override contamination constraints. Predictive maintenance platforms compress replacement cycles as fleet operators flag sensor degradation before ABS fault code triggers.
Passenger vehicles anchor volume demand; heavy trucks capture the steepest margin premiums through regulatory compliance complexity.
End User:
Customer type determines specification control points, with integrated tier-1 suppliers capturing module-level decisions while aftermarket channels fragment across digital procurement migration.
- OEMs:Vehicle manufacturers specify tone ring performance parameters within ABS and ESC system requirements, embedding compliance into platform engineering gates. Robert Bosch leverages captive sensor-to-ring integration to control specification flows across multiple programs.
- Tier-1 Suppliers:Axle and brake module integrators bundle tone rings with bearings and sensors, reducing OEM sourcing complexity. Continental AG anchors European supply through in-house stamping and magnetic encoding capabilities clustered along Germany's engineering corridor.
- Vehicle Assemblers:Contract manufacturing arrangements in China's eastern belt concentrate demand near major production facilities, with localized content requirements under NMPA protocols shaping supplier qualification.
- Aftermarket Providers:Digital procurement platforms and direct tier-1 contracts displace traditional wholesale intermediaries. North American distributors report fastest channel migration as fleet accounts bypass jobber networks for high-volume specifications.
Tier-1 suppliers retain specification leadership through module integration; aftermarket providers expand most quickly via digital channel reconfiguration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering corridors command premium pricing for precision-stamped tone rings while China's eastern manufacturing belt undercuts on volume production, creating a transatlantic pricing asymmetry that shapes procurement decisions for multinational OEM programs.
United States
NHTSA-administered FMVSS 126 mandates electronic stability control on all light vehicles, embedding tone ring performance into federal compliance testing. Detroit's automotive corridor concentrates stamping operations near Michigan assembly plants. Fleet operators accelerate digital procurement migration as predictive maintenance platforms compress replacement cycles.
Germany
ECE R13 braking harmonization creates specification ceilings that shape supplier R&D priorities across Stuttgart-Munich engineering clusters. KBA type-approval frameworks enforce validated performance across wider temperature ranges than passenger car equivalents. Continental AG anchors European supply through in-house magnetic encoding capabilities clustered along this corridor.
China
NMPA vehicle safety standards tighten material specifications and performance thresholds for domestic production. Yangtze River Delta manufacturing belt concentrates tier-1 suppliers near Shanghai assembly plants. Localized content requirements under evolving GB/T protocols fragment test protocols for multinational programs.
Japan
METI industrial policy drives chassis mass reduction targets that accelerate polymer composite specification. Kanto and Kansai manufacturing regions host sensor-to-ring integration specialists. DENSO Corporation leverages captive integration to control specification flows across multiple OEM programs.
India
PLI scheme production-linked incentives attract tone ring suppliers to establish localized stamping operations. Chennai and Pune assembly plants concentrate demand in southern and western manufacturing belts. BIS certification requirements add compliance layers for component qualification.
Automotive Wheel Speed Sensor Tone Ring Market Competitive Landscape
Integrated module suppliers and discrete component specialists split the market along the axis of specification control. Tier-1 axle integrators capture module-level decisions through bundled offerings, while metalforming and magnetic encoding specialists retain influence in heavy truck programs where material performance dominates. Two strategic archetypes define competitive positioning: sensor-to-ring integrators leveraging captive technology flows, and stamping specialists commanding precision tolerances. Dominant competitive moves include axle module bundling to reduce OEM sourcing complexity, and backward integration into magnetic encoding to capture specification authority.
Among German-based integrated suppliers, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the sensor-to-ring integration archetype, with Continental AG occupying a parallel position through in-house stamping and encoding capabilities. Japanese specialists represented by DENSO Corporation anchor Asian supply networks through similar integration depth. These players sit within the premium tier where module-level specification control determines margin capture, while smaller stamping houses compete on precision tolerance delivery for heavy truck programs where ECE R13 compliance complexity sustains specialist positioning.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| ZF Friedrichshafen AG |
| HELLA GmbH & Co. KGaA |
| TE Connectivity |
| NXP Semiconductors |
| Melexis |
| Sensata Technologies |
| Others |
Pricing and Supply Chain Analysis
Neodymium supply concentration in China's rare earth processing belt feeds directly into margin compression for magnetic encoder suppliers downstream. Tier-1 module integrators capture premium pricing through captive specification control, while discrete stamping houses compete on volume efficiency.
Pricing Analysis
Configured-to-order tone rings for heavy truck programs command substantial premiums over standard passenger vehicle specifications. Three-tier pricing structure across premium, standard, and economy levels separates ECE R13-certified heavy truck variants from NMPA-compliant domestic Chinese production and economy aftermarket replacements. Price differentiation hinges on magnetic calibration precision and certification tier, with Hall Effect integration adding further margin capture. Pricing pressure stems from digital procurement platforms compressing aftermarket channel margins as fleet accounts bypass traditional jobbers. Aftermarket distributors exhibit highest price sensitivity; integrated OEM module suppliers demonstrate lowest.
Supply Chain Analysis
Supplier financing facilities with extended payment terms have become critical competitive weapons as tier-1 integrators squeeze upstream stamping houses. Manufacturing concentrates in Germany, China, and Japan, with the Stuttgart-Munich corridor anchoring European precision encoding and China's eastern belt dominating volume ferromagnetic stamping. Supply chains draw from neodymium rare earth feeds, cold-rolled steel, and polymer ferrite composites. Single-source vulnerability in German magnetic encoding capabilities creates structural risk for European OEM programs. Distribution runs through direct tier-1 contracts to vehicle assemblers, with digital platforms capturing aftermarket migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service layers expand faster than hardware replacement cycles as fleet operators adopt sensor health monitoring platforms. This service-attach dynamic recalibrates supplier revenue models toward recurring diagnostic and replacement scheduling revenues.
For Market Incumbents: Pre-empt capacitive encoder substitution in mining and construction vehicle segments by accelerating contamination-resistant magnetic calibration R&D. Secure backward integration into polymer-bonded ferrite compounding to defend margin position against composite formulation specialists. Lock in axle module bundling contracts before ZF Friedrichshafen and Continental AG consolidate European specification control. For New Entrants and Emerging Players: Build out localized stamping capacity in India's PLI scheme corridors near Chennai and Pune assembly plants, where domestic content requirements create protected demand pools. Target light commercial vehicle hybrid material constructions as the most penetrable segment, bridging metallic and composite specification gaps. Lead with digital procurement platform partnerships to bypass entrenched aftermarket distribution networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German stamping specialists clustered along the Stuttgart-Munich engineering corridor, where ECE R13 compliance complexity sustains specialist margins. Long-term viability favors sensor-to-ring integrators with captive magnetic encoding capabilities. Watch for divergence between China's GB/T standards and EU type-approval frameworks as the signal for platform engineering fragmentation that would favor regional specialists over multinational module suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Axle Module Integration | ZF Friedrichshafen bundles tone rings with bearings and sensors to reduce OEM sourcing complexity. |
| Polymer Composite Transition | Robert Bosch GmbH specifies injection-molded magnetic properties directly, collapsing discrete metalforming vendor relationships. |
| Predictive Maintenance Platform | Fleet operators compress replacement cycles as sensor degradation patterns trigger pre-fault interventions. |
| Digital Procurement Migration | Direct tier-1 contracts bypass traditional jobber networks, accelerating price discovery in North American aftermarket channels. |
| Dual Certification Investment | Suppliers must simultaneously satisfy ECE R13 braking harmonization and China's evolving GB/T vehicle safety standards. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and magnetic encoding technicians; and secondary validation through NHTSA FMVSS 126 compliance filings, ECE R13 regulatory harmonization documents, vehicle production databases, and customs trade records. Bottom-up segmentation modeling triangulated against top-down market sizing from regulatory mandate penetration rates.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the projection horizon. CAGRs derived from segment-level demand build-ups weighted by regulatory mandate phase-in schedules and OEM platform refresh cycles. Modeled variables include neodymium price trajectory, polymer ferrite adoption curves, and digital procurement platform penetration in aftermarket channels.
The forecast holds incumbent behavior within observed patterns; aggressive moves by rare earth processors or capacitive encoder specialists would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
Wind Shield Washer Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Automotive Brake Friction Products Market