
 Global Automotive Plastics Market | 2026-2036
Global Automotive Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Plastics Market Analysis
Aftermarket service revenue is reconfiguring competitive economics across the automotive plastics value chain. BASF SE leverages its integrated polyamide production network to dominate high-performance under-the-hood applications. SABIC anchors its position through captive petrochemical feedstock access and specialized engineering resin portfolios. Covestro AG differentiates via optical-grade polycarbonate leadership for autonomous vehicle sensor housings.
Automotive plastics encompass thermoplastic and thermoset polymer compounds formulated to meet impact resistance, thermal stability, and weight reduction specifications, typically processed through injection molding or extrusion to achieve dimensional tolerances within 0.1 millimeters for critical safety components. Polypropylene occupies the largest volume share across interior trim and bumper applications due to its cost-performance balance and recyclability profile. Polyamide concentrates margin pools in under-the-hood thermal management segments where heat deflection temperatures above 200 degrees Celsius command premium pricing. Injection Molding leads technology adoption for complex geometries, while 3D Printing emerges fastest in low-volume tooling and prototype validation workflows.
The US EPA tailpipe emissions standards and the EU Green Deal carbon-border adjustment mechanism are redirecting OEM material selection toward recycled-content and bio-based polymer grades. China's SAMR GB standards for automotive interior air quality restrict volatile organic compound emissions from plastic components. Japan's METI circular economy roadmap mandates recycled plastic ratios in new vehicle production. Stakeholders must monitor regulatory divergence across these jurisdictions when configuring regional supply footprints and certification strategies.
Market Dynamics
Electric vehicle platform architectures are compressing vehicle development cycles and forcing polymer suppliers to co-engineer lightweight thermal management systems alongside OEM engineering teams from concept phase.
Growth Catalysts
- EU Green Deal carbon-border adjustments:The mechanism penalizes high-carbon-intensity imports, accelerating European OEM sourcing shifts toward recycled-content and bio-based polymer grades certified under ECHA frameworks.
- China EV production scaling:Domestic manufacturers like BYD and NIO are deploying polymer-intensive battery enclosures and structural components that substitute aluminum with glass-reinforced polyamide.
- Autonomous sensor integration:LiDAR and camera housing demand for optical-grade polycarbonate is expanding application scope beyond traditional lighting into perception-system enclosures.
Market Restraints
- Propylene feedstock volatility:Polypropylene margins compress when naphtha-cracker economics tighten, particularly affecting European compounders without backward integration into petrochemicals.
- REACH authorization bottlenecks:ECHA's sunset date schedule for plasticizers and flame retardants forces reformulation cycles that extend qualification timelines by 18-24 months.
- Aluminum substitution threat:Cast aluminum battery trays retain cost advantages above 150 kWh pack capacities, capping polymer penetration in premium EV segments.
Strategic Opportunities
- India PLI scheme for auto components:The production-linked incentive framework subsidizes advanced polymer processing equipment, attracting compounders to establish regional compounding facilities.
- Chemical recycling infrastructure:Pyrolysis and depolymerization capacity expansion enables food-contact-grade recycled polypropylene for interior applications previously closed to mechanical recycling.
- Japan METI circular economy mandates:Recycled plastic ratio requirements in new vehicle production create guaranteed offtake agreements for post-industrial automotive scrap.
Industry Challenges
- Multi-material bonding expertise:Polymer-to-metal adhesive selection and corrosion management require specialized joining engineers scarce in traditional plastics processing workforces.
- GB standards compliance timelines:China's SAMR volatile organic compound testing protocols for cabin air quality extend homologation cycles for imported interior components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Plastics Market |
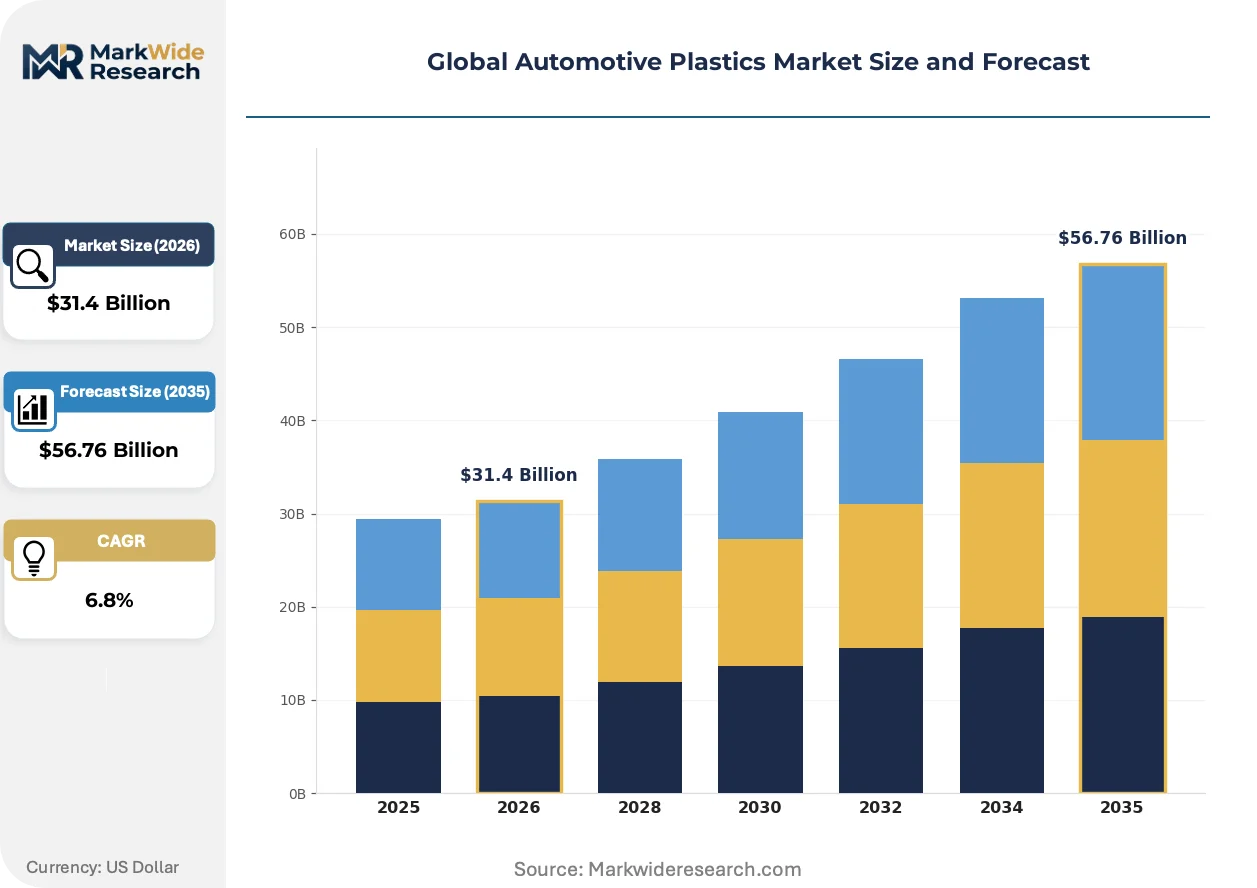
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polycarbonate, Polyamide, Acrylonitrile Butadiene Styrene End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Interior, Exterior, Under-the-Hood, Structural Technology: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | LyondellBasell Industries, Celanese Corporation, BASF SE, Solvay, Evonik Industries AG, SABIC, DuPont, Mitsubishi Chemical Corporation, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Plastics Market Emerging Trajectories
Automotive plastics development is pivoting from incremental density reduction toward functional integration, where single components deliver thermal, electromagnetic, and structural performance previously requiring multi-part assemblies.
Continuous fiber-reinforced thermoplastic composites are migrating from aerospace heritage applications into automotive structural battery enclosures and seat frames. BMW and Porsche engineering teams have validated unidirectional tape laying processes for A-pillar reinforcements, achieving 40% mass reduction versus high-strength steel. The technology is migrating from prototype tooling toward high-volume press-forming lines capable of sub-90-second cycle times.
REACH restriction proposals targeting microplastic release from tire and brake wear are redirecting R&D investment toward closed-loop material tracking systems. Compounders must now document polymer chain-of-custody from virgin resin through regrind incorporation. Suppliers serving German KBA type-approval pathways face the most stringent documentation requirements, with some qualifying recycled-content grades for under-the-hood thermal shields.
Fleet operators and mobility service providers are consolidating specification power previously dispersed across individual consumers. Lease-finance structures for electric commercial vehicles bundle maintenance and residual value guarantees, forcing polymer suppliers into long-term performance contracts rather than discrete component sales. This procurement compression is most visible in European last-mile delivery electrification, where DHL and Amazon Logistics specify 10-year UV stability warranties for exterior trim.
Global Automotive Plastics Market Segmentation
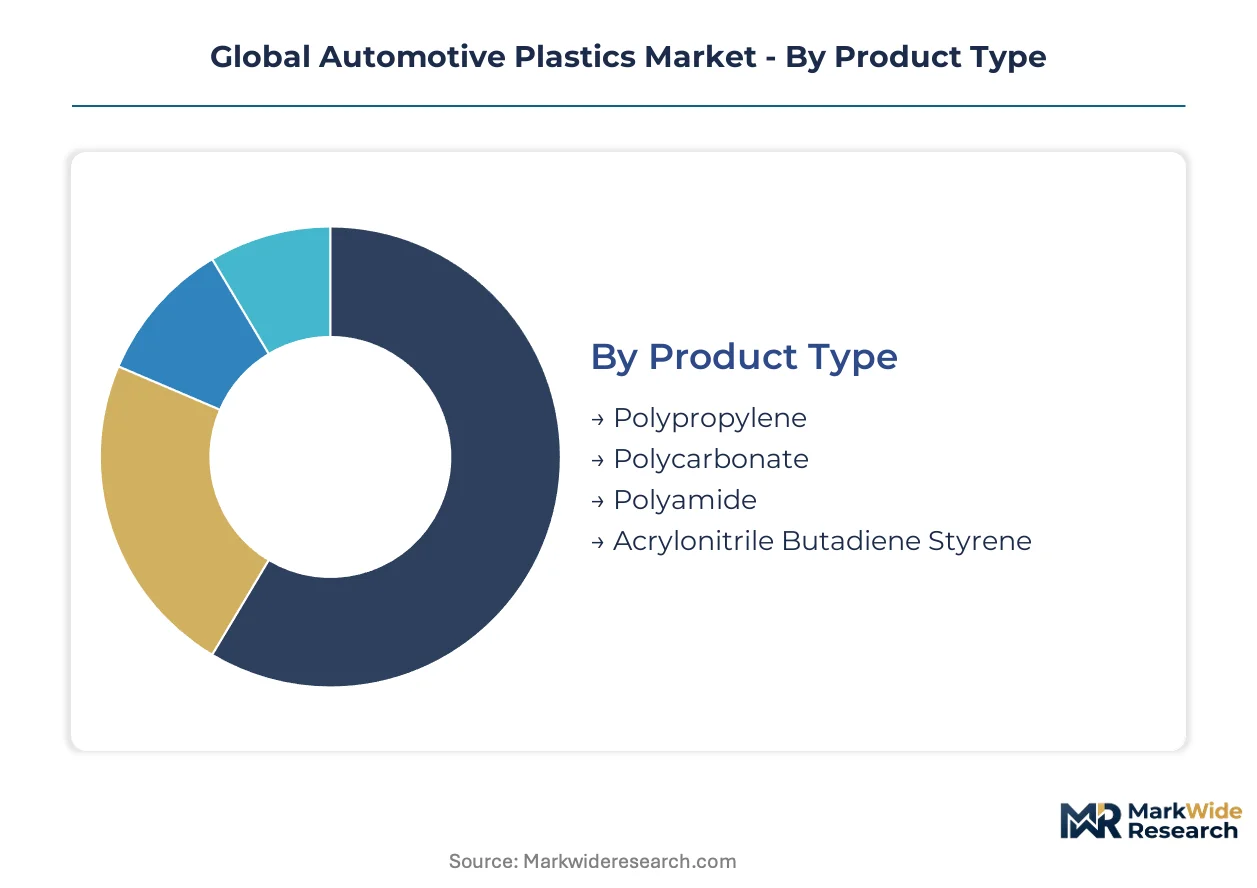
Segmentation in automotive plastics reveals divergent margin structures across the value chain. Aftermarket service intensity varies dramatically by product type and end-user channel, reshaping supplier economics.
Product Type:
Aftermarket service revenue concentrates disproportionately in polymers requiring specialized repair protocols and thermal reprocessing expertise.
- Polypropylene:Formulated as homopolymer and copolymer grades with melt flow indices between 5-50 g/10min for thin-wall injection molding. Demand clusters in bumper fascias and interior trim across Chinese EV platforms where BYD and NIO specify high-flow grades for complex geometries. The polymer's weld-line strength limitations drive aftermarket replacement rather than repair.
- Polycarbonate:Optical-grade variants with light transmission above 90% and Vicat softening points near 150 degrees Celsius. LiDAR and camera housing demand from autonomous vehicle programs in Germany and California absorbs premium-priced grades certified under ECHA frameworks.
- Polyamide:Glass-reinforced compounds dominate under-the-hood thermal management where heat deflection temperatures exceed 200 degrees Celsius.
- Acrylonitrile Butadiene Styrene:Terpolymer balancing impact resistance with surface aesthetics for instrument panel skins and decorative trim.
By volume, Polypropylene leads. By growth pace, Polycarbonate is ahead.
End User:
Cost tier stratification separates specification authority from manufacturing execution across the value chain.
- OEMs:Retain material selection authority for visible and safety-critical components, leveraging platform-scale purchasing power to mandate recycled-content ratios. BMW and Porsche engineering teams specify continuous fiber-reinforced thermoplastics for structural applications.
- Tier-1 Suppliers:Compound and process polymers to OEM specifications, capturing margin through toll manufacturing and design-for-manufacturing expertise. Magna and Faurecia operations in Germany and Michigan concentrate high-volume injection molding capacity.
- Aftermarket Providers:Service collision repair and refurbishment channels with color-matched and mechanically compatible grades.
- Vehicle Assemblers:Contract manufacturers and joint-venture operations execute final assembly without material specification authority.
Specification power concentrates with OEMs. Volume throughput peaks at Tier-1 Suppliers.
Application:
Margin pools align with thermal and structural performance requirements rather than visible surface area.
- Interior:Cabin air quality regulations from China's SAMR restrict volatile organic compound emissions, favoring low-odor polypropylene grades and bio-based polyurethanes. DHL and Amazon Logistics specify 10-year UV stability warranties for commercial vehicle trim.
- Under-the-Hood:Thermal management components command premium pricing through heat deflection temperature thresholds above 200 degrees Celsius. Battery enclosure demand from EV architectures in China and Germany absorbs glass-reinforced polyamide volumes.
- Exterior:Bumper systems and body panels balance impact resistance with paint adhesion and dimensional stability.
- Structural:Continuous fiber-reinforced composites migrate from aerospace into automotive A-pillars and seat frames.
By revenue per kilogram, Under-the-Hood leads. By application expansion, Structural is climbing fastest.
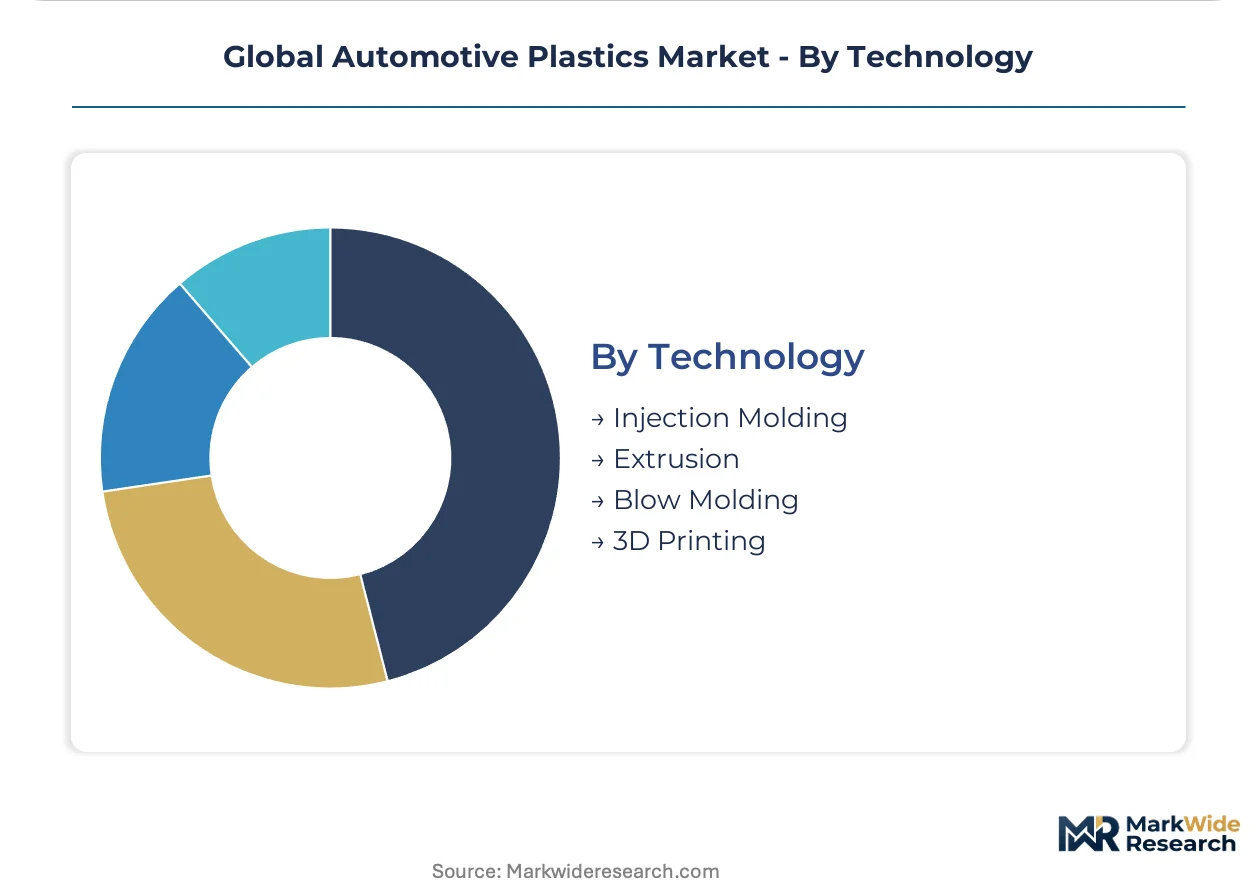
Technology:
Customer type differentiation separates prototype validation from mass production tooling investments.
- Injection Molding:Dominates complex geometries with cycle times below 60 seconds for high-volume interior and exterior components. Tooling investments exceed $500,000 per cavity pair, concentrating capacity with integrated compounders.
- 3D Printing:Fused filament fabrication and selective laser sintering enable low-volume tooling and prototype validation workflows. Porsche engineering teams validate unidirectional tape laying processes before committing to hard tooling.
- Extrusion:Produces continuous profiles for weatherstripping, trim, and thermal management tubing.
- Blow Molding:Forms hollow containers for fluid reservoirs and ducting components.
Production volume concentrates in Injection Molding. Technology transition momentum favors 3D Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese EV buyers absorb premium polymer pricing with minimal elasticity, while European fleet operators demand decade-long performance warranties that compress supplier margins. German OEMs prioritize REACH-compliant grades regardless of cost. Indian commercial vehicle segments remain acutely price-sensitive, favoring commodity polypropylene over engineered compounds.
China
BYD and NIO specifications for battery enclosures and structural components drive glass-reinforced polyamide consumption at volumes unmatched elsewhere. SAMR GB standards for cabin air quality restrict volatile organic compound emissions, forcing reformulation of interior grades. Shanghai and Shenzhen host the densest concentrations of polymer compounding capacity serving domestic EV platforms.
Germany
BMW and Porsche engineering teams specify continuous fiber-reinforced thermoplastics for A-pillar and seat frame applications, validating aerospace-derived processes. KBA type-approval pathways impose the most stringent documentation requirements for recycled-content grades under ECHA frameworks. The Stuttgart and Munich metropolitan regions concentrate OEM engineering centers and Tier-1 supplier headquarters.
United States
EPA tailpipe emissions standards redirect material selection toward lightweight thermal management systems for hybrid and electric powertrains. Michigan and Ohio retain high-volume injection molding infrastructure serving Detroit-based OEM platform teams. The Inflation Reduction Act's domestic content provisions influence polymer sourcing decisions for battery enclosure applications.
Japan
METI circular economy mandates guarantee offtake agreements for post-industrial automotive scrap, creating structural demand for recycled-content grades. Toyota and Honda engineering specifications prioritize polyamide thermal management components with heat deflection thresholds above 200 degrees Celsius. The Nagoya and Osaka industrial corridors concentrate compounding facilities serving domestic and export vehicle programs.
India
The PLI scheme for auto components subsidizes advanced polymer processing equipment, attracting compounders to establish regional compounding facilities. BIS certification requirements for automotive interior materials extend homologation timelines for imported grades. Maharashtra and Gujarat host emerging clusters of Tier-1 suppliers serving Maruti Suzuki and Tata Motors production networks.
Global Automotive Plastics Market Vendor Landscape
Capability concentration sits with integrated petrochemical conglomerates commanding backward feedstock access; scale advantage sits with specialized engineering resin compounders serving niche thermal management applications. The market structures around three archetypes: captive-resin producers with cracker-to-compound integration, independent compounders with formulation expertise, and materials-science specialists with optical-grade certification. Dominant competitive moves include capacity expansion in China-aligned geographies and strategic partnerships for chemical recycling feedstock security.
Within the integrated-resin tier, BASF SE and SABIC exemplify archetypes of captive feedstock control and specialized engineering portfolios respectively. Covestro AG occupies a position representing optical-grade polycarbonate leadership for autonomous vehicle sensor applications. These three entities anchor competitive dynamics through distinct capability vectors rather than overlapping segment contestation.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| Celanese Corporation |
| BASF SE |
| Solvay |
| Evonik Industries AG |
| SABIC |
| DuPont |
| Mitsubishi Chemical Corporation |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
Shanghai and Shenzhen polymer compounding clusters concentrate global capacity for glass-reinforced polyamide serving BYD and NIO battery enclosure programs, translating feedstock proximity into pricing leverage over European compounders lacking backward integration. This geographic concentration enables Chinese suppliers to absorb propylene volatility more effectively than European counterparts exposed to naphtha-cracker economics.
Pricing Analysis
Long-term offtake agreements dominate procurement between OEM platform teams and integrated resin producers, insulating BASF and SABIC from spot propylene volatility while independent compounders face margin compression. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified optical grades for autonomous sensor housings from commodity interior polypropylene. Pricing pressure stems from aluminum substitution threats in battery trays above 150 kWh capacities. Indian commercial vehicle segments exhibit highest price sensitivity, while German OEMs prioritize ECHA-compliant grades regardless of cost premium.
Supply Chain Analysis
Tariff exposure between China and the European Union under the carbon-border adjustment mechanism dominates supply chain risk assessment for recycled-content polymer grades. Feedstock concentration centers on Saudi Arabia, South Korea, and the United States for virgin polypropylene resin. Raw material dependencies rest on naphtha and propane feedstocks, glass fiber reinforcement, and specialized flame retardant additives. Single-source vulnerability persists in optical-grade polycarbonate for LiDAR housings. Distribution runs through captive logistics networks of integrated petrochemical conglomerates and independent distributors serving Tier-1 injection molders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive plastics incumbents must defend polymer-intensive vehicle architectures against aluminum substitution in structural battery applications, where cast metal retains cost advantages at scale. The substitution threat intensifies as OEMs optimize pack economics above 150 kWh capacities.
For Market Incumbents: Entrench position through captive chemical recycling infrastructure securing food-contact-grade recycled polypropylene feedstock for interior applications previously closed to mechanical reprocessing. Prioritize backward integration into pyrolysis and depolymerization capacity to isolate margins from virgin resin volatility. Defend against aluminum encroachment by co-engineering thermal management systems with OEM platform teams from concept phase, locking in polyamide specifications before metal alternatives enter design review.
For New Entrants and Emerging Players: India's PLI-subsidized auto component corridors represent the most penetrable entry point for regional compounding facilities serving Maruti Suzuki and Tata Motors production networks. Chemical recycling technology licensing agreements with European pyrolysis operators provide differentiated feedstock access without capital-intensive capacity buildout. Target aftermarket collision repair channels with color-matched polypropylene grades where weld-line strength limitations prevent repair and drive replacement demand.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates divesting non-core automotive compounding assets to focus on specialty chemicals. Long-term viability hinges on positioning within EV platform architectures where polymer content per vehicle expands versus internal combustion equivalents. Monitor Inflation Reduction Act domestic content provisions as inflection indicator for North American battery enclosure polymer demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Investment | Pyrolysis capacity expansion enables food-contact-grade recycled polypropylene for cabin applications under SAMR GB standards. |
| Backward Integration into Feedstock | Captive naphtha-cracker access insulates BASF and SABIC from propylene volatility compressing independent compounder margins. |
| Co-Engineering Partnerships with OEMs | Early-stage collaboration with BYD and NIO platform teams locks in glass-reinforced polyamide specifications for battery enclosures. |
| REACH Certification Investment | ECHA framework compliance opens premium pricing tiers for optical-grade polycarbonate in German autonomous vehicle programs. |
| Regional Compounding Facility Expansion | PLI-subsidized capacity in Maharashtra and Gujarat captures Maruti Suzuki and Tata Motors procurement localization mandates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, ACC and Cefic industry reports, and vehicle production databases. Interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations specialists informed demand-side validation. Technical discussions with plant managers and R&D directors at integrated resin producers and independent compounders captured supply-side dynamics. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Forecast inputs incorporate propulsion architecture evolution, content-per-vehicle trajectories for electric platforms, and regional production cluster shifts. Segmentation dimensions span product type, application thermal performance tier, end-user specification authority, and technology processing method. CAGRs derive from regression analysis against historical polymer intensity trends and OEM platform rollout schedules. Battery enclosure polymer adoption curves and autonomous sensor integration timelines constitute automotive-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting automotive leasing penetration and commercial vehicle fleet investment cycles would shift the trajectory. Forecasts embed assumptions regarding REACH authorization timelines and SAMR GB standard enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Drum Brake Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
North America Gear Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Europe Industrial Roller Chain Drive Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Hydroformed Parts Market