
 Automotive Roller Bearing Market | 2026-2036
Automotive Roller Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Roller Bearing Market Outlook
The capital-intensity divergence between integrated steel-forging operations and outsourced precision-grinding specialists is unwinding legacy cost structures in bearing manufacturing. SKF leverages captive supply of vacuum-degassed bearing steel to sustain margin control across European OEM contracts. Schaeffler AG anchors its competitive position through in-house production of ceramic rolling elements for electrified drivetrains. The Timken Company differentiates via tapered roller expertise purpose-built for North American heavy-duty truck axles.
An automotive roller bearing is a precision-engineered antifriction component comprising hardened steel or ceramic rolling elements captured between inner and outer raceways, manufactured through controlled atmosphere heat treatment and superfinishing to achieve surface roughness below 0.1 micrometers Ra; its primary function is to transmit radial and axial loads while minimizing rotational friction in powertrain, wheel hub, and transmission assemblies. Tapered roller bearings occupy the dominant revenue share in internal combustion applications where combined load handling justifies higher unit costs. Ceramic material variants represent the fastest-expanding segment as electric vehicle thermal management requirements push beyond conventional steel temperature thresholds. Needle roller bearings command concentrated demand in motorcycle and compact transmission designs where radial space constraints override absolute load capacity.
The EPA enforces fuel economy standards that indirectly mandate friction reduction across drivetrain components, while NHTSA safety regulations prescribe wheel-end bearing integrity thresholds for commercial vehicles. China's SAMR administers GB/T rolling bearing standards that govern dimensional accuracy and fatigue life testing protocols for both domestic production and import certification. Stakeholders must monitor how divergent emissions compliance timelines between US IRA industrial policy and EU Green Deal carbon border adjustments reshape regional sourcing priorities for bearing-grade specialty steel.
Market Dynamics
The automotive roller bearing market is experiencing a fundamental structural compression as electric vehicle powertrain architectures eliminate multi-speed transmissions and consolidate bearing positions into fewer, higher-specification units. This transition is forcing manufacturers to recalibrate volume forecasts against radically different unit economics.
Growth Catalysts
- China's GB/T 30512 fatigue life standards:Mandatory certification protocols for automotive bearings are accelerating replacement cycles in domestic commercial vehicle fleets.
- Ceramic rolling element adoption:Silicon nitride balls are penetrating high-speed e-motor applications where thermal management exceeds steel operational thresholds.
- Germany's manufacturing belt concentration:Stuttgart and Wolfsburg anchor precision machining clusters that reduce logistics costs for European OEM supply contracts.
Market Restraints
- Vacuum-degassed bearing steel supply concentration:Specialty steel production clusters in select European and Asian regions create input cost volatility during energy price spikes.
- Technical limitation in hybrid ceramic-steel interfaces:Differential thermal expansion coefficients between ceramic balls and steel raceways constrain maximum operating temperature windows.
- EU Green Deal carbon border adjustments:Import levies on carbon-intensive steel inputs are restructuring sourcing economics for non-European bearing manufacturers.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives are attracting precision grinding capacity expansion for export-oriented bearing assemblies.
- Wheel hub unit consolidation:Integrated bearing-sensor modules for autonomous vehicle positioning systems represent unpenetrated value-capture potential.
- US IRA industrial policy:Clean vehicle tax credits are redirecting North American EV supply chain investment toward domestic bearing qualification programs.
Industry Challenges
- Superfinishing technician scarcity:Surface roughness below 0.1 micrometers Ra requires specialized grinding expertise that outpaces vocational training pipeline output.
- Dual certification complexity:Simultaneous compliance with China's SAMR GB protocols and EPA fuel economy friction mandates extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Roller Bearing Market |
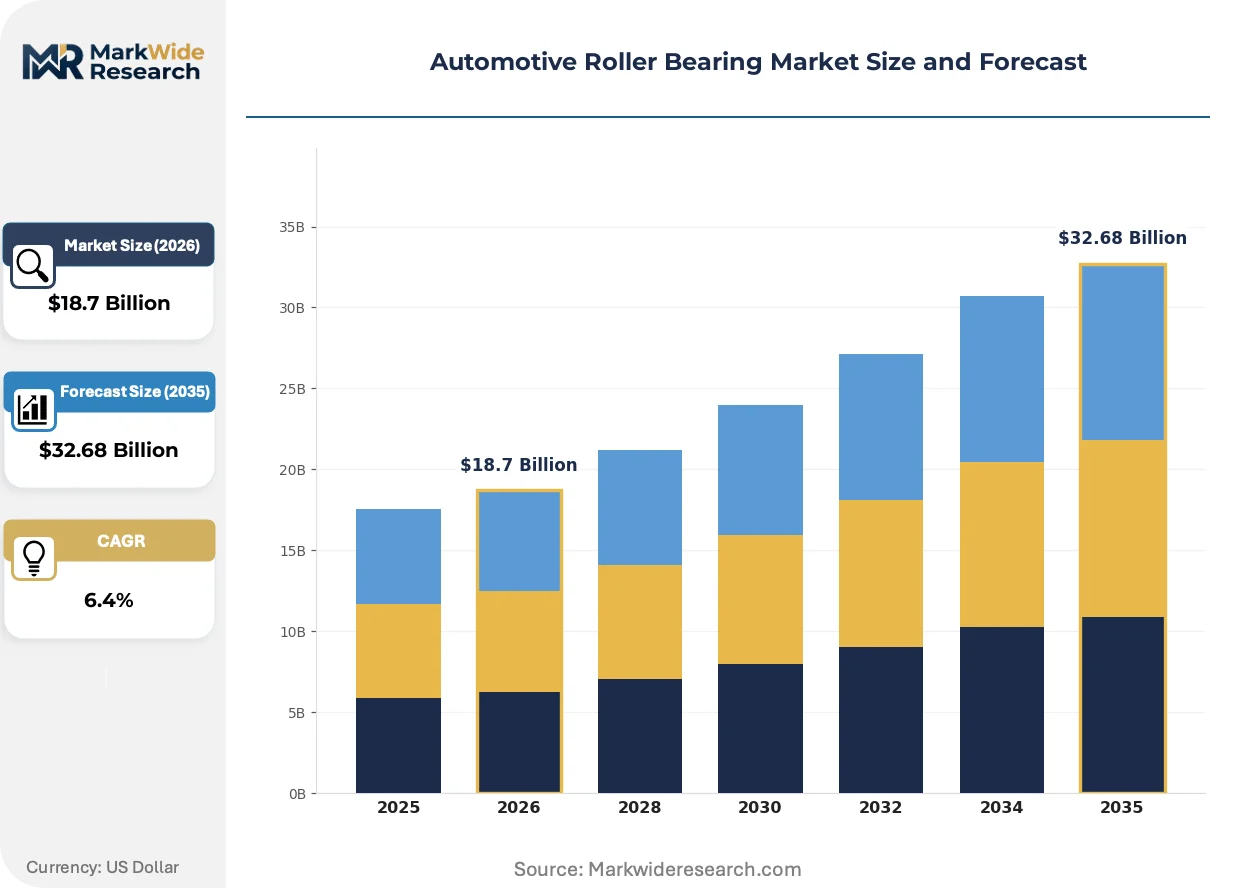
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Tapered Roller Bearings, Cylindrical Roller Bearings, Needle Roller Bearings End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Steel, Ceramic, Polymer, Composite Application: Light Vehicles, Heavy-Duty Trucks, Motorcycles, Electric Vehicles |
| Companies Covered | NTN Corp., JTEKT Corp., SKF, C&U Group, MinebeaMitsumi Inc., Schaeffler AG, The Timken Company, Nachi-Fujikoshi Corp., NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Roller Bearing Market Strategic Shifts
Automotive bearing technology is splitting along powertrain electrification fault lines, with divergent performance specifications emerging for battery-electric versus hybrid thermal management profiles. Manufacturers are racing to platform architectures that accommodate both trajectories without full duplication.
Hybrid ceramic bearing assemblies are bifurcating the product mix as silicon nitride rolling elements penetrate high-speed e-motor applications while conventional steel retains cost-sensitive wheel-end positions. Premium EV platforms specify ceramic for thermal resilience above 150°C continuous operation. The technology is bifurcating supplier tier structures into ceramic-capable specialists versus steel-dominant volume producers.
EPA fuel economy standards and NHTSA safety thresholds are tightening in parallel, forcing bearing designs to simultaneously reduce friction coefficients and withstand higher structural loads. Wheel-end integrity mandates for commercial vehicles now prescribe accelerated life testing protocols. Heavy-duty truck axle applications face the steepest compliance cost escalation.
Fleet operators are unbundling bearing replacement from full powertrain service contracts, creating direct procurement relationships with component specialists rather than Tier 1 system integrators. This channel disintermediation compresses margin capture for traditional distributors. North American long-haul trucking verticals exhibit the most pronounced procurement model evolution.
Automotive Roller Bearing Market Segmentation
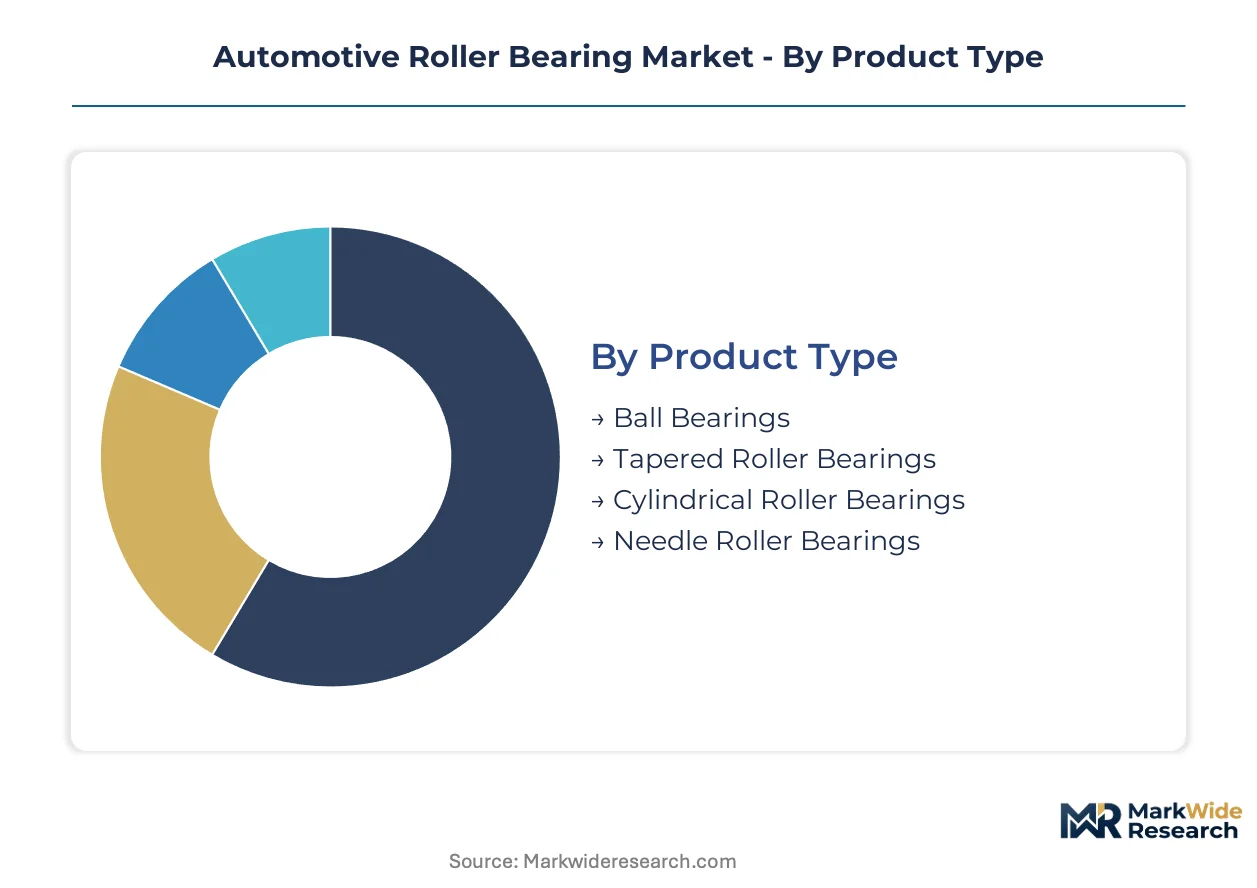
Segmentation in automotive roller bearings tracks how electrification, regulatory divergence, and supply chain consolidation are reshaping procurement patterns across powertrain architectures. Manufacturers must align product portfolios with divergent certification requirements and thermal performance thresholds.
Product Type:
EPA fuel economy mandates and China's GB/T 30512 fatigue protocols are bifurcating certification pathways, with steel-intensive designs facing divergent testing regimens versus ceramic-hybrid assemblies.
- Tapered Roller Bearings:These units handle combined radial and axial loads through conical rolling elements and precision-matched raceway angles. Heavy-duty truck axle manufacturers in Germany's Stuttgart corridor specify these for load-bearing integrity under NHTSA commercial vehicle safety thresholds. Differential thermal expansion between steel components constrains maximum operating temperatures.
- Ball Bearings:Spherical rolling elements minimize friction coefficients in high-speed rotational applications. Electric vehicle e-motor assemblies specify these for rotational efficiency above 15,000 RPM where silicon nitride variants penetrate. China's MIIT powertrain efficiency standards accelerate qualification timelines for ceramic-hybrid configurations.
- Cylindrical Roller Bearings:Line-contact geometry maximizes radial load capacity in transmission shaft applications. Conventional internal combustion powertrains retain these for multi-speed gearbox architectures.
- Needle Roller Bearings:Compact cylindrical elements address radial space constraints in motorcycle engines and compact transmissions. Japanese OEMs specify these for lightweight powertrain packaging.
Established volume favors tapered roller bearings in commercial vehicle positions; emerging adoption favors ball bearings in electrified drivetrains.
End User:
Procurement concentration varies by customer integration depth, with captive manufacturing operations commanding divergent margin structures versus independent distributors.
- OEMs:Vehicle manufacturers with in-house bearing qualification programs specify direct supply relationships for powertrain-critical positions. Germany's Wolfsburg manufacturing cluster anchors European OEM procurement gravity for high-volume contracts. EPA fuel economy certification requirements extend development timelines for new supplier onboarding.
- Tier-1 Suppliers:System integrators bundle bearing assemblies into transmission and axle modules for OEM delivery. These intermediaries capture value-add through sensor integration and pre-assembly testing protocols.
- Aftermarket Providers:Independent distributors serve fleet replacement cycles outside warranty coverage. North American long-haul operators increasingly procure directly from component specialists.
- Vehicle Assemblers:Contract manufacturers without captive bearing engineering rely on specification-managed procurement from qualified supplier pools.
Direct OEM relationships concentrate in high-specification ceramic applications; aftermarket channels expand fastest in commercial vehicle replacement cycles.
Material:
Thermal performance thresholds and carbon border compliance are restructuring raw material sourcing economics across supplier tiers.
- Steel:Vacuum-degassed bearing grades from European specialty mills dominate cost-sensitive wheel-end and transmission applications. EU Green Deal carbon border adjustments impose import levies on carbon-intensive steel inputs from non-European sources.
- Ceramic:Silicon nitride rolling elements withstand continuous operation above 150°C in high-speed e-motor positions. China's NMPA reliability standards accelerate domestic qualification programs for ceramic-hybrid assemblies.
- Polymer:Reinforced thermoplastic cages reduce weight in auxiliary systems where absolute load capacity is secondary to mass reduction targets.
- Composite:Hybrid material configurations address niche applications requiring electromagnetic interference shielding in sensor-integrated hub units.
Steel retains cost-driven volume in conventional powertrains; ceramic materials are climbing the fastest in electrified drivetrain specifications.
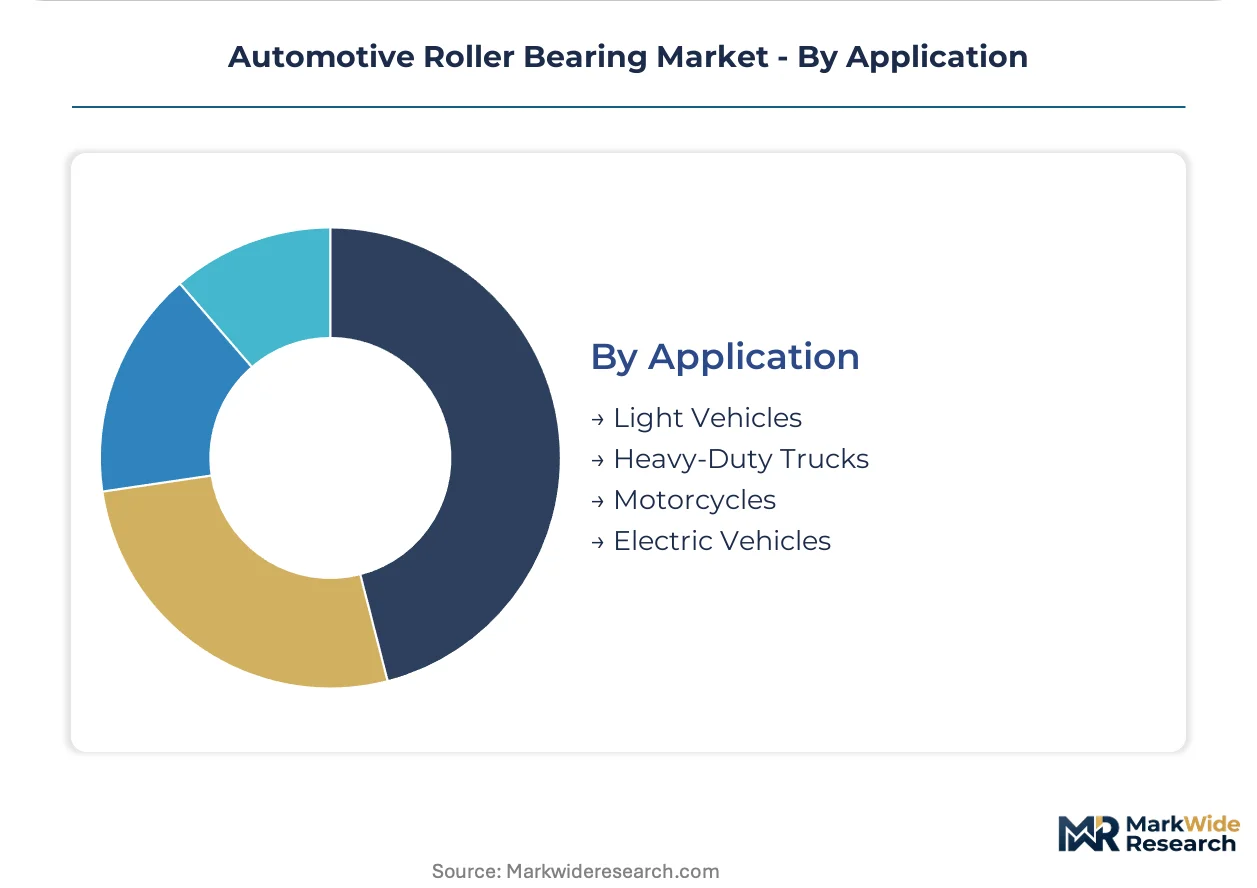
Application:
Powertrain electrification is collapsing bearing position counts in some segments while intensifying performance requirements in retained positions.
- Electric Vehicles:Consolidated drivetrain architectures concentrate bearing demand into fewer, higher-specification units for e-motor and reduction gear applications. China's dual carbon goals and MIIT efficiency mandates accelerate domestic EV bearing qualification programs.
- Heavy-Duty Trucks:Multi-speed transmissions and drive axle assemblies retain high bearing counts with severe-duty load requirements. NHTSA wheel-end integrity mandates prescribe accelerated life testing for commercial vehicle applications.
- Light Vehicles:Passenger car powertrains present diversified demand across internal combustion, hybrid, and battery-electric platforms.
- Motorcycles:Compact engine packaging specifies needle roller configurations for space-constrained crankshaft and transmission positions.
Heavy-duty truck applications anchor absolute volume; electric vehicle platforms are gaining share fastest in specification-weighted revenue terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Fleet operators in North American long-haul trucking demand standardized steel bearings with minimal premium tolerance. European OEMs and China's EV manufacturers absorb ceramic-hybrid cost premiums for thermal performance.
China
MIIT efficiency mandates and NMPA reliability standards under GB protocols are accelerating domestic qualification programs for ceramic-hybrid bearing assemblies. The country's dual carbon goals redirect procurement toward high-temperature-capable e-motor bearings. Yangtze River Delta manufacturing clusters around Shanghai anchor precision grinding capacity expansion.
Germany
Stuttgart and Wolfsburg manufacturing corridors concentrate European OEM procurement gravity for high-volume bearing contracts. EU Green Deal carbon border adjustments impose import levies on carbon-intensive steel inputs, restructuring sourcing economics for non-European suppliers. KBA vehicle certification requirements extend supplier onboarding timelines.
United States
IRA clean vehicle tax credits redirect EV supply chain investment toward domestic bearing qualification programs. NHTSA wheel-end integrity mandates prescribe accelerated life testing for commercial vehicle applications. Heavy-duty truck axle manufacturers in Michigan and Ohio specify tapered roller configurations for load-bearing integrity.
Japan
METI industrial policy supports domestic ceramic rolling element production for high-speed e-motor applications. JIS standards govern dimensional accuracy and fatigue life testing protocols for automotive bearing certification. Kanto region manufacturing clusters around Tokyo maintain precision machining expertise for sensor-integrated hub units.
India
PLI scheme production-linked incentives attract precision grinding capacity expansion for export-oriented bearing assemblies. BIS certification requirements govern domestic automotive component quality standards. Tamil Nadu and Gujarat automotive corridors concentrate Tier-1 supplier manufacturing for European and North American OEM contracts.
Automotive Roller Bearing Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated steel-forging operations with captive vacuum-degassed bearing steel supply compete against outsourced precision-grinding specialists. Three archetypes dominate: ceramic-capable specialists serving electrified drivetrains, steel-dominant volume producers for conventional powertrains, and hybrid manufacturers platforming both trajectories. Competitive moves concentrate on backward integration into specialty steel supply and geographic expansion through India's PLI-attracted capacity.
Among European-integrated manufacturers, Schaeffler AG and SKF occupy positions exemplifying the technology-leadership archetype through in-house ceramic element production and captive steel supply respectively. The Timken Company represents North American specialization in heavy-duty commercial vehicle applications. These three entities anchor the premium-tier competitive vector without dominating absolute volume.
| Leading Market Players |
|---|
| NTN Corp. |
| JTEKT Corp. |
| SKF |
| C&U Group |
| MinebeaMitsumi Inc. |
| Schaeffler AG |
| The Timken Company |
| Nachi-Fujikoshi Corp. |
| NSK Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at European vacuum-degassed bearing steel mills shapes both supply concentration and price floors for precision-ground automotive roller bearings. China's Yangtze River Delta grinding clusters and Germany's Stuttgart-Wolfsburg corridor anchor manufacturing gravity, with scale economics determining which supplier tiers can absorb carbon border adjustment costs.
Pricing Analysis
Aftermarket service contracts and fleet replacement cycles drive lifetime value capture for bearing manufacturers. Three-tier pricing structure across premium ceramic-hybrid, standard vacuum-degassed steel, and economy induction-hardened grades segments buyer archetypes. Price differentiation rests on GB/T 30512 certification tier and MIIT efficiency qualification status. Cost compression in steel-intensive wheel-end positions intensifies as North American long-haul operators unbundle procurement from Tier 1 integrators. Fleet operators exhibit highest price sensitivity; European OEMs absorbing ceramic premiums for e-motor thermal performance show lowest.
Supply Chain Analysis
Just-in-time inventory protocols dominate OEM supply contracts, while aftermarket distributors maintain strategic stockpiles of high-rotation SKUs for commercial vehicle replacement cycles. Geographic supply concentration centers on Germany, China, and Japan for precision grinding capacity. Raw material dependencies draw from Swedish and Japanese vacuum-degassed bearing steel, Chinese silicon nitride ceramic powder, and German heat treatment equipment. Single-source vulnerability in specialty steel supply creates structural risk during energy price spikes. Distribution runs through captive OEM supply agreements, Tier 1 system integrator channels, and direct fleet procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle powertrain consolidation represents a high-growth disruption, with MIIT efficiency mandates and EPA fuel economy standards forcing bearing position counts to collapse while thermal specifications escalate.
For Market Incumbents: Compound technology leadership through captive ceramic rolling element production and backward integration into vacuum-degassed steel supply. SKF and Schaeffler AG exemplify this trajectory. Defend margin position against steel-dominant volume producers by accelerating GB/T 30512 certification timelines for hybrid assemblies. Channel control through direct OEM relationships offsets distributor disintermediation pressure. For New Entrants and Emerging Players: Differentiate on ceramic-hybrid qualification speed for China's NMPA reliability protocols. India's PLI scheme attracts precision grinding capacity for export-oriented assemblies serving European carbon border-adjusted markets. White-space targets include sensor-integrated wheel hub units for autonomous vehicle positioning and high-speed e-motor bearings above 15,000 RPM. Go-to-market angle: qualification-managed procurement bypassing Tier 1 intermediaries for fleet direct relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic-capable specialists over steel-dominant volume producers as electrification penetration deepens. Long-term viability over the next decade hinges on backward integration into specialty steel or forward integration into sensor-bearing modules. Acquisition target archetype: mid-cap precision grinders with GB/T and JIS dual certification capability. Signal to watch: China's domestic silicon nitride production scale crossing thresholds that restructure ceramic element supply economics.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Rolling Element Production Scale-Up | In-house silicon nitride capability secures margin control under NMPA reliability standards. |
| Dual Certification Investment (GB/T + EPA) | Simultaneous compliance with China's SAMR and US fuel economy mandates accelerates OEM onboarding. |
| India PLI-Attracted Capacity Expansion | Tamil Nadu and Gujarat corridors reduce carbon border exposure for European aftermarket supply. |
| Sensor-Integrated Hub Unit Development | Autonomous vehicle positioning requirements create unpenetrated value-capture in wheel-end modules. |
| Vacuum-Degassed Steel Supply Security | Captive or long-term offtake agreements mitigate energy-price-driven input volatility. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and superfinishing technician training programs anchored the qualitative base. Primary interviews triangulated with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed bearing manufacturers, and MIIT efficiency certification disclosures. Bottom-up segment sizing across propulsion architecture, material grade, and application position combined with top-down market reconciliation.
Sensitivity analysis tested forecast robustness across electrification penetration scenarios and carbon border adjustment implementation timelines. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from regression against historical production volumes and technology substitution curves. Industry-specific inputs incorporated GB/T 30512 fatigue life standard adoption rates and ceramic-hybrid qualification timelines under NMPA protocols.
The analysis sits within stated boundaries; outcomes outside sustained EV powertrain consolidation or divergent regulatory compliance timelines would require recalibration. Forecasts reflect assumptions on specialty steel supply continuity and superfinishing technician pipeline output. Revision becomes warranted when China's domestic ceramic production scale or EU carbon border adjustment scope crosses thresholds that restructure sourcing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Mobile Emission Catalysts Market
Automotive Parts
Philippines Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Wiper Blade Market
Automotive Parts
Global Motorcycle Carbon Ceramic Brake Rotors Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Odometer Market